
 Steam Methane Reforming Market | 2026-2036
Steam Methane Reforming Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Methane Reforming Market Intelligence
Production of high-purity, low-carbon hydrogen via SMR with integrated carbon capture is bifurcating the market from conventional grey hydrogen facilities. This shift creates distinct competitive arenas for technology licensors and engineering firms. Haldor Topsoe A/S specializes in advanced catalyst and reactor designs for enhanced efficiency. KBR Inc. leverages its extensive experience in large-scale ammonia and methanol plant engineering, while Linde plc dominates the industrial gas supply chain, delivering hydrogen to a diverse end-user base.
Steam methane reforming is a mature chemical process that reacts methane with high-temperature steam, typically between 700°C and 1,000°C, using a nickel-based catalyst. Its primary purpose is the large-scale production of synthesis gas, a mixture of hydrogen and carbon monoxide. Hydrogen gas production for petroleum refining and chemicals production constitutes the largest share of the market by application. Within technology, autothermal reforming is gaining interest for its operational efficiency and suitability for integration with carbon capture systems.
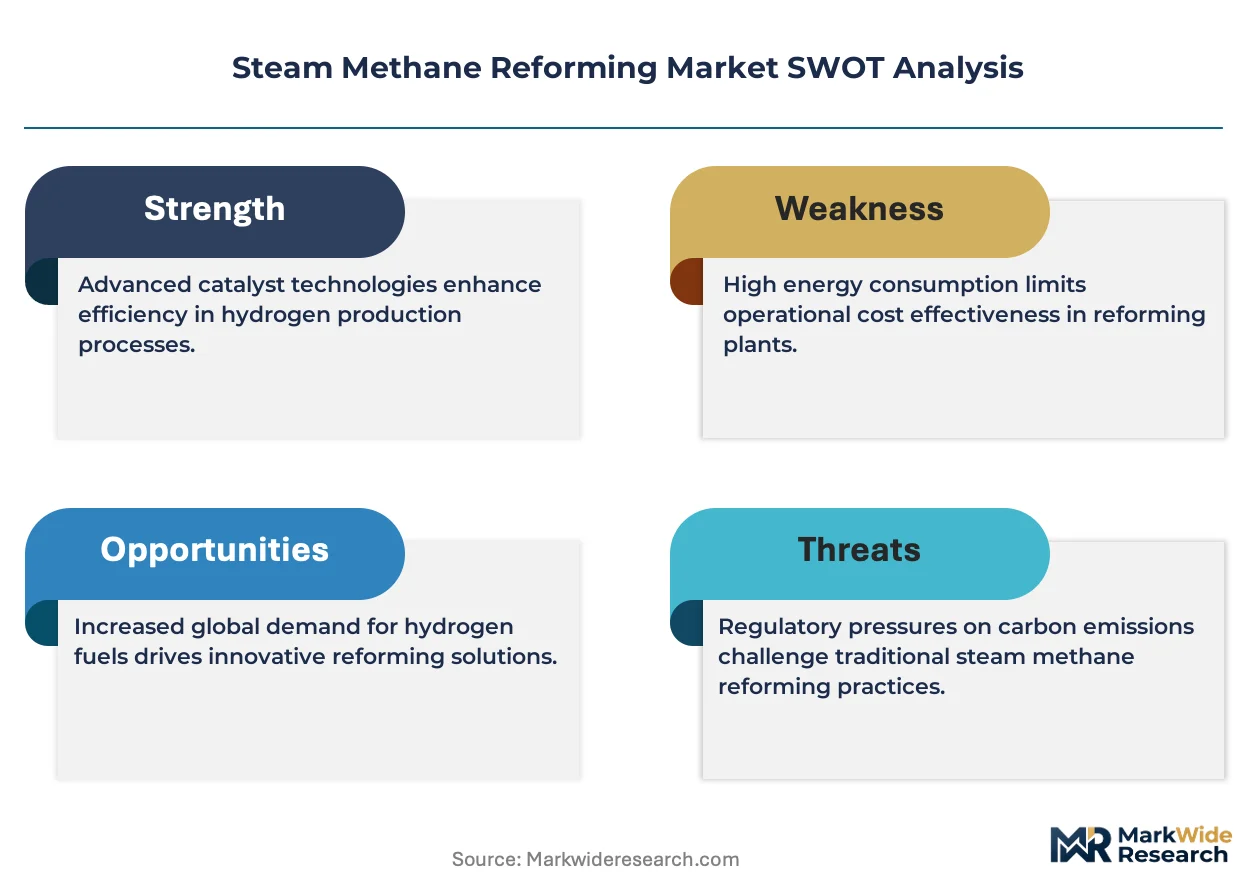
Regulatory frameworks increasingly influence SMR plant economics and technology choices. The US EPA enforces stringent emissions standards for industrial pollutants, affecting plant operations. The EU Green Deal provides incentives for low-carbon hydrogen, pushing SMR operators towards CCUS integration. Similarly, China's MEE implements policies aligned with its dual carbon goals, impacting industrial energy consumption. The core strategic decision for operators is determining the economic viability of retrofitting existing assets versus investing in new production technologies.
Market Dynamics
The imperative to decarbonize industrial hydrogen production is the central force shaping the market. This pressure bifurcates the industry, creating a distinct segment for low-carbon hydrogen produced via SMR with CCUS, separate from conventional grey hydrogen facilities.
Growth Catalysts
- Policy Incentives for Decarbonization:The EU Green Deal and related carbon pricing mechanisms provide direct financial incentives for industrial consumers to source low-carbon hydrogen, stimulating investment in SMR plants integrated with carbon capture technology.
- Fertilizer Production Expansion:Sustained demand for ammonia-based fertilizers to support global food production provides a foundational consumption base for synthesis gas produced through steam methane reforming, particularly in agricultural economies.
- Industrial Cluster Development:The co-location of hydrogen producers and consumers in industrial hubs, such as those on the US Gulf Coast, creates economies of scale for large SMR facilities and shared CO2 transport infrastructure.
Market Restraints
- High Carbon Capture Retrofit Costs:The significant capital expenditure required to retrofit existing SMR plants with CCUS systems presents a major financial barrier for many asset owners, slowing the transition to low-carbon hydrogen production.
- Natural Gas Price Volatility:As the primary feedstock, the price of natural gas directly impacts hydrogen production costs, and market volatility creates significant operational and financial risk for SMR plant operators.
- Competition from Green Hydrogen:The declining cost of renewable energy and electrolyzer technology makes green hydrogen an increasingly viable long-term substitute, posing a structural threat to new investments in fossil-fuel-based SMR.
Strategic Opportunities
- Emerging Clean Fuel Applications:The production of hydrogen as a feedstock for sustainable aviation fuels and e-methanol presents a significant new demand vector for SMR with CCUS, opening new high-value markets.
- US Regulatory Support:Tax credits offered under the US Inflation Reduction Act, specifically 45Q for carbon sequestration and 45V for clean hydrogen production, create a powerful economic case for new blue hydrogen projects.
- Advanced Process Control Integration:Deploying digital twin technology and AI-driven process controls offers opportunities to optimize SMR plant efficiency, reduce energy consumption, and improve catalyst lifetime, enhancing asset profitability.
Industry Challenges
- Complex Retrofitting Projects:The engineering complexity of integrating CCUS equipment into existing brownfield SMR facilities poses significant project execution risks, including extended downtime and budget overruns. *Specialized Talent Scarcity: A shortage of chemical engineers and plant operators with combined expertise in high-temperature reforming processes and carbon capture systems constrains the ability to design, build, and operate new facilities.
- CO2 Infrastructure Deficits:The lack of available pipeline networks and geological storage sites for captured carbon dioxide in many industrial regions remains a critical bottleneck for the deployment of new SMR with CCUS projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Methane Reforming Market |
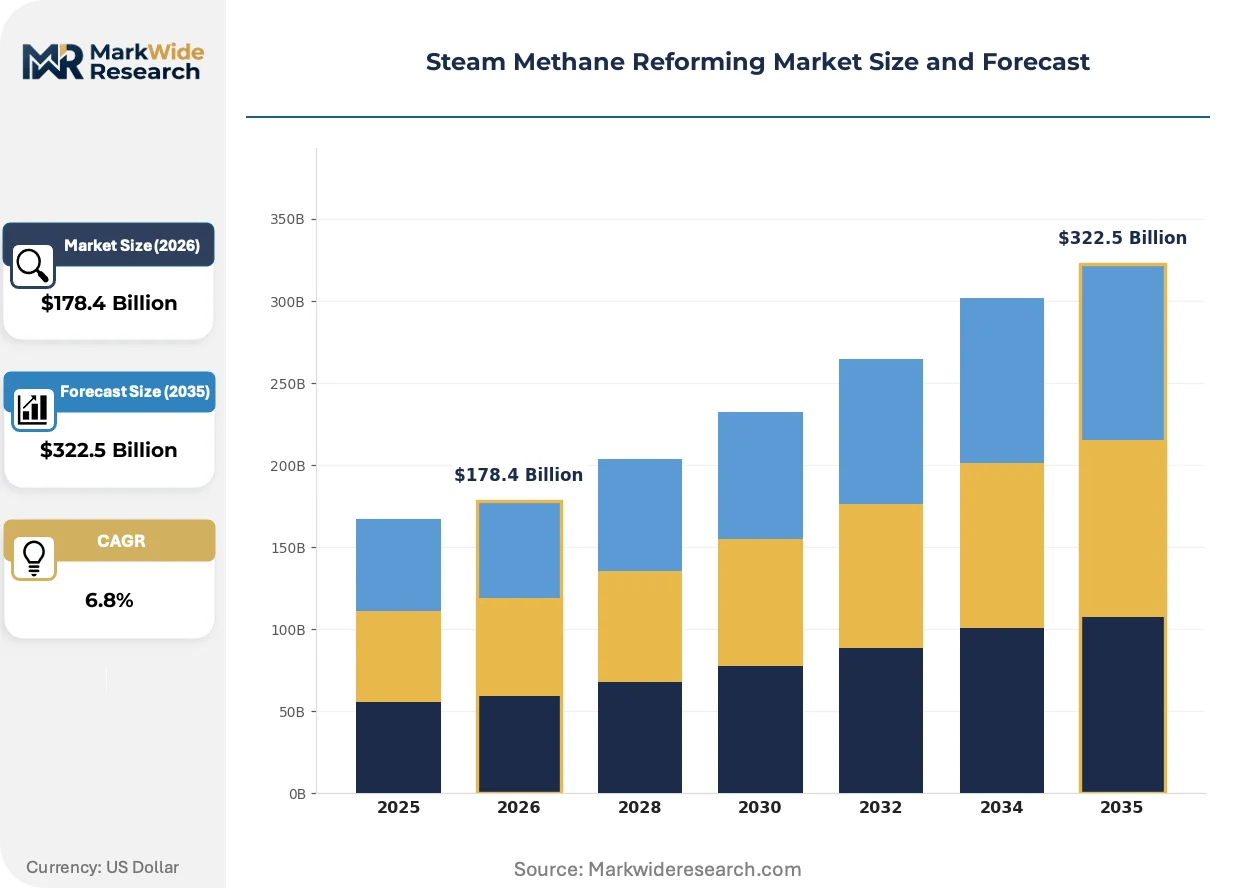
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
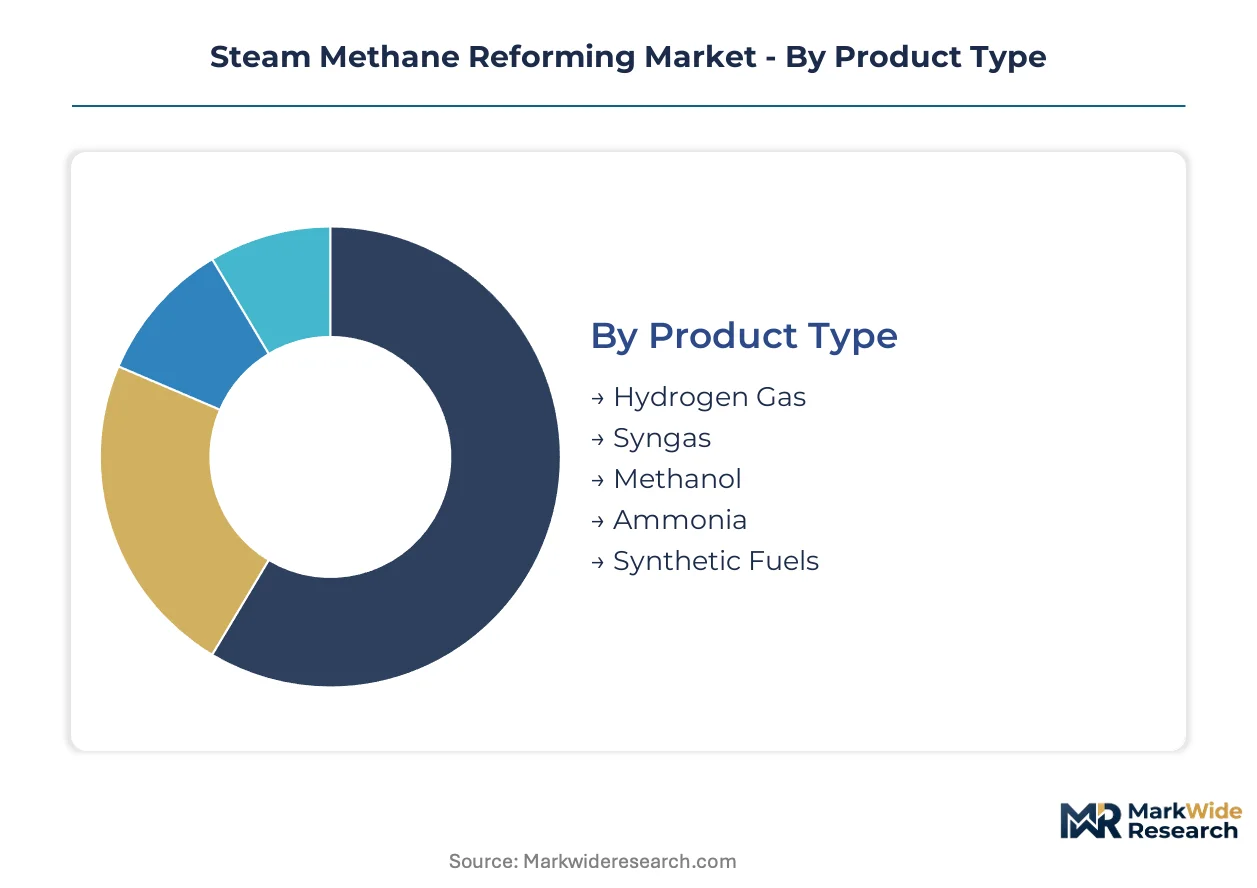
| Segmentation | Product Type: Hydrogen Gas, Syngas, Methanol, Ammonia, Synthetic Fuels Technology: Autothermal Reforming, Catalytic Reforming, Combined Reforming, Partial Oxidation, Pressure Swing Reforming Application: Refining, Chemicals Production, Fuel Cell Power, Fertilizer Synthesis, Synthetic Fuel Manufacturing End User Industry: Petrochemical Plants, Power Generation Facilities, Fertilizer Manufacturers, Industrial Gas Suppliers, Energy Companies |
| Companies Covered | Haldor Topsoe A/S, KBR Inc., Air Liquide, Honeywell UOP, Fluor Corporation, Linde plc, Chevron Lummus Global LLC, Baker Hughes Company, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Methane Reforming Market Strategic Shifts & Innovations
Decarbonization mandates are compelling a technological and operational evolution within the mature SMR landscape. The primary focus is on improving thermal efficiency and integrating carbon capture systems to produce economically viable, low-carbon hydrogen at an industrial scale.
Autothermal reforming, or ATR, is a process that integrates partial oxidation with steam reforming in a single reactor to produce synthesis gas. Chemical producers and petroleum refiners are increasingly specifying ATR for new, large-scale hydrogen facilities. Its ability to generate a highly concentrated CO2 stream suitable for capture at a lower cost is displacing conventional SMR technology in next-generation blue hydrogen project designs.
China's "dual carbon" policy framework, implemented by the Ministry of Ecology and Environment (MEE), is forcing a reassessment of industrial emissions. The policy creates stringent energy consumption and carbon intensity targets for heavy industries, including chemicals and refining. SMR operators in industrial zones like the Yangtze River Delta are now compelled to invest in efficiency upgrades or conduct feasibility studies for CCUS integration to comply.
Hydrogen consumers are shifting from dedicated, on-site supply agreements to participating in shared pipeline networks within industrial clusters. This model allows multiple offtakers, such as refineries and ammonia producers, to be served by a single, large-scale SMR with CCUS, replacing less efficient, distributed grey hydrogen assets. This aggregation of demand is most prominent in regions like the Port of Rotterdam and along the US Gulf Coast.
Steam Methane Reforming Market Segmentation
Segmentation provides a granular understanding of the Steam Methane Reforming market's diverse outputs, technological approaches, and end-use sectors. Analyzing these distinct segments reveals specific demand drivers and competitive dynamics. This granular view assists stakeholders in strategic planning and resource allocation.
Product Type:
The market for SMR product types exhibits varying degrees of global and regional demand concentration, reflecting diverse industrial supply chains.
- Hydrogen Gas:Hydrogen gas, a colorless and odorless element, is primarily produced as a synthesis gas component or purified for direct use. Demand for high-purity hydrogen gas is concentrating in industrial clusters on the US Gulf Coast, driven by petroleum refining and chemical production needs.
- Ammonia:Ammonia, a compound of nitrogen and hydrogen, serves as a foundational chemical intermediate for fertilizers and industrial applications. Global demand for ammonia is sustained by fertilizer synthesis expansion in agricultural economies like China and India, requiring large-scale SMR production.
- Syngas:A mixture of hydrogen and carbon monoxide, syngas is a versatile building block for various chemical syntheses.
- Methanol:This simple alcohol is synthesized from syngas, serving as a chemical feedstock and a clean-burning fuel.
- Synthetic Fuels:Produced from syngas via Fischer-Tropsch processes, synthetic fuels offer alternatives to conventional petroleum products.
Hydrogen Gas holds the largest share; momentum sits with Ammonia due to expanding fertilizer synthesis applications.
Technology:
Technological advancements are driving efficiency improvements and carbon capture integration across different SMR processes.
- Autothermal Reforming:ATR integrates partial oxidation and steam reforming in a single reactor, generating a highly concentrated CO2 stream for capture. Chemical producers and petroleum refiners are specifying ATR for new, large-scale hydrogen facilities, especially for blue hydrogen projects in the US.
- Catalytic Reforming:This mature process reacts methane with high-temperature steam over a nickel-based catalyst, producing synthesis gas. Conventional catalytic SMR remains the dominant technology for grey hydrogen production, particularly in established industrial zones lacking CCUS infrastructure.
- Combined Reforming:This technology combines steam reforming and partial oxidation in separate reactors to optimize syngas composition.
- Partial Oxidation:POX reacts hydrocarbons with oxygen to produce syngas, suitable for heavier feedstocks and generating less CO2 than SMR.
- Pressure Swing Reforming:This process typically refers to SMR combined with Pressure Swing Adsorption (PSA) for high-purity hydrogen separation.
Efficiency gains are central to Autothermal Reforming's expansion, while Catalytic Reforming seeks broader adoption with CCUS integration.
Application:
The SMR market applications vary significantly in scale and purity requirements, influencing plant design and operational parameters.
- Refining:Hydrogen is critical for hydrotreating and hydrocracking processes in petroleum refining, removing sulfur and upgrading crude oil fractions. Large-scale hydrogen production for refining is concentrated in major oil processing hubs like the US Gulf Coast and Rotterdam, driven by fuel quality standards.
- Fertilizer Synthesis:SMR-produced hydrogen is a key feedstock for ammonia synthesis, which is then converted into various nitrogen-based fertilizers. Foundational consumption for fertilizer synthesis is robust in agricultural economies globally, including China and India, supporting food production.
- Chemicals Production:Hydrogen and syngas from SMR serve as essential building blocks for producing a wide array of industrial chemicals and polymers.
- Fuel Cell Power:High-purity hydrogen from SMR can power fuel cells for stationary power generation or transportation, particularly in heavy-duty applications.
- Synthetic Fuel Manufacturing:SMR-derived syngas is converted into liquid synthetic fuels, including sustainable aviation fuels and e-methanol, offering decarbonization pathways.
The largest volume is directed towards Refining, with Synthetic Fuel Manufacturing representing a high-growth segment.
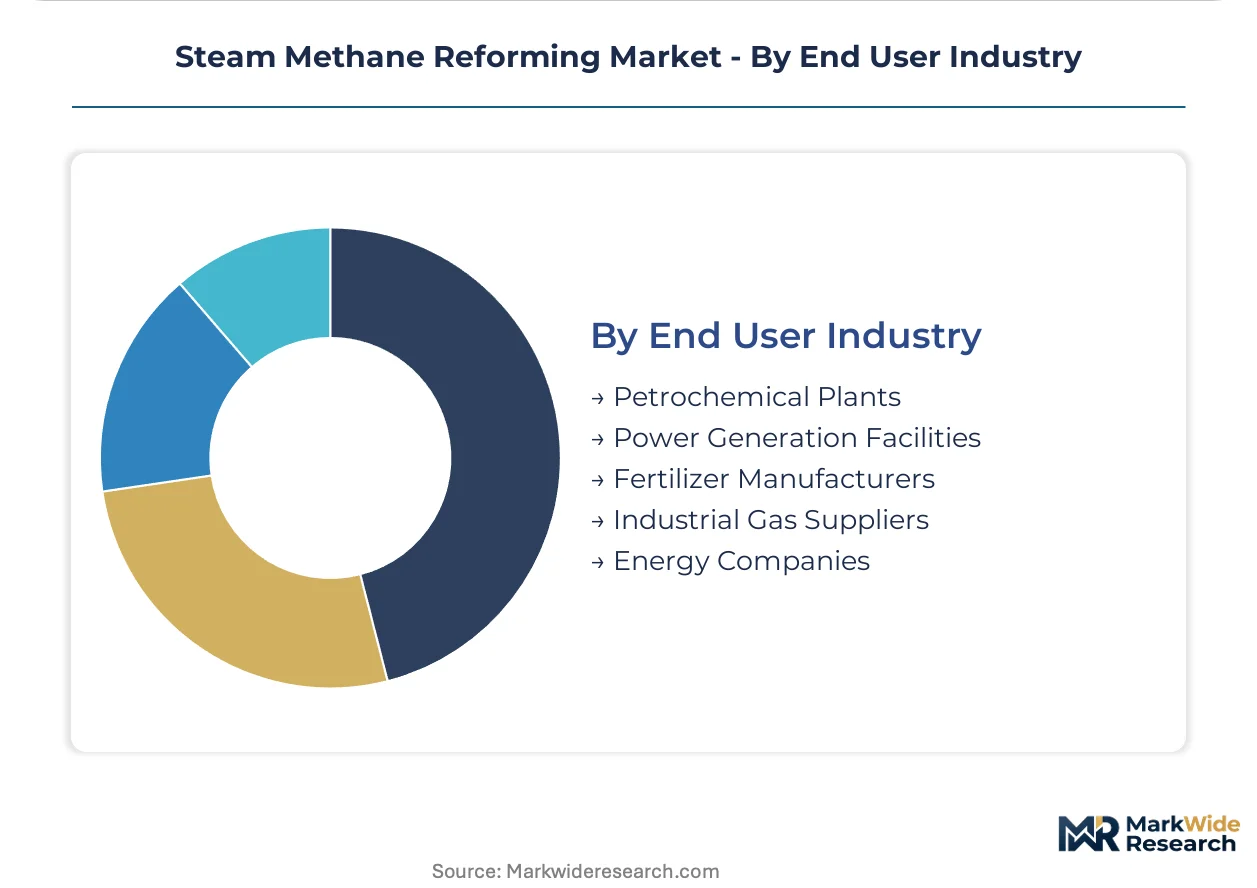
End User Industry:
End-user industries for SMR products demonstrate distinct procurement strategies and integration levels, from captive production to external supply.
- Fertilizer Manufacturers:These companies operate large-scale SMR units to produce hydrogen captive for their ammonia synthesis processes, ensuring feedstock security. Global fertilizer manufacturers, particularly in major agricultural regions, drive consistent demand for integrated SMR facilities to support ammonia production.
- Industrial Gas Suppliers:These firms produce and distribute hydrogen and syngas to diverse industrial clients, often operating centralized SMR plants and extensive pipeline networks. Companies like Linde plc dominate the industrial gas supply chain, delivering hydrogen to a broad end-user base across various sectors in Europe and North America.
- Petrochemical Plants:These facilities utilize SMR-derived hydrogen for various chemical processes, including hydrotreating and the production of intermediates.
- Power Generation Facilities:SMR-produced hydrogen can serve as a clean fuel for gas turbines or fuel cells in power generation, supporting grid stability.
- Energy Companies:Integrated energy companies leverage SMR for hydrogen production to support refining operations, develop blue hydrogen projects, and explore new energy vectors.
Strategic partnerships are common for Industrial Gas Suppliers, while Fertilizer Manufacturers often rely on captive production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of SMR production capabilities, particularly with carbon capture integration, is emerging in regions with robust industrial infrastructure and supportive regulatory frameworks. These areas benefit from established energy supply chains and a growing imperative for decarbonized industrial processes. The strategic co-location of hydrogen producers and consumers in these hubs optimizes infrastructure development.
United States
Demand for large-scale hydrogen production for petroleum refining and chemical manufacturing drives SMR market activity. The US Inflation Reduction Act provides significant tax credits (45Q and 45V) for carbon sequestration and clean hydrogen, stimulating blue hydrogen projects. Industrial clusters along the US Gulf Coast, including Houston and Port Arthur, are seeing substantial investment in SMR with CCUS facilities.
China
Fertilizer synthesis and chemical production are foundational demand sources for SMR-derived hydrogen in China. The Ministry of Ecology and Environment (MEE) implements stringent "dual carbon" policies, compelling SMR operators to improve efficiency and explore CCUS integration. Industrial zones like the Yangtze River Delta are focusing on emissions reduction and efficiency upgrades for existing SMR plants.
India
Ammonia production for fertilizer manufacturing consistently generates high demand for synthesis gas in India. The government's National Green Hydrogen Mission encourages the transition to cleaner hydrogen, indirectly influencing SMR operators to consider efficiency improvements. Major chemical and fertilizer complexes in states like Gujarat and Uttar Pradesh are critical consumption centers for SMR outputs.
Netherlands
The Netherlands focuses on decarbonizing its industrial base, with SMR-produced hydrogen serving refining and chemical sectors. The EU Green Deal incentivizes low-carbon hydrogen production, pushing for CCUS integration in SMR operations. The Port of Rotterdam is a prime example, developing a comprehensive hydrogen backbone and CO2 transport infrastructure to support large-scale SMR with CCUS.
Saudi Arabia
Petroleum refining and petrochemical production are the primary drivers for SMR hydrogen demand in Saudi Arabia. The Kingdom's ambitious Vision 2030 includes plans for developing blue hydrogen and ammonia, influencing investment in SMR with carbon capture. Industrial cities such as Jubail and Yanbu are central to these efforts, leveraging existing hydrocarbon resources for hydrogen production.
Steam Methane Reforming Market Key Industry Players
Concentration sits with technology licensors and large engineering firms, which provide the core intellectual property and project execution capabilities for SMR plants. The market structure exhibits a tiered consolidation, where a few dominant players offer comprehensive solutions, while specialized firms focus on niche components or services. Dominant competitive moves include strategic partnerships for project development and continuous innovation in catalyst and reactor designs.
Within the technology licensing and engineering services segment, Haldor Topsoe A/S represents advanced catalyst and reactor designs for enhanced SMR efficiency. KBR Inc. exemplifies extensive experience in large-scale ammonia and methanol plant engineering, leveraging its project delivery capabilities. Linde plc occupies a position as a dominant industrial gas supplier, delivering hydrogen to a diverse end-user base through its expansive supply chain infrastructure.
| Leading Market Players |
|---|
| Haldor Topsoe A/S |
| KBR Inc. |
| Air Liquide |
| Honeywell UOP |
| Fluor Corporation |
| Linde plc |
| Chevron Lummus Global LLC |
| Baker Hughes Company |
| Air Products and Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for hydrogen gas lock in supply access and price visibility for large industrial consumers. These contracts mitigate natural gas price volatility for both producers and end-users, stabilizing project economics.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure for blue hydrogen, offering significant tax credits (45Q and 45V) that directly reduce the effective cost of production. The dominant pricing model is contract-based long-term offtake, with price differentiation driven by certification level for low-carbon intensity and volume scale. Pricing softness reflects competition from conventional grey hydrogen production and declining green hydrogen costs. Fertilizer manufacturers exhibit high price sensitivity, while petroleum refiners prioritize supply security and purity.
Supply Chain Analysis
Pipeline network development costs significantly impact the supply chain for SMR-produced hydrogen, especially for CCUS-integrated facilities. Supply concentration for natural gas feedstock centers on the United States, China, and Middle Eastern countries. The market relies on nickel-based catalysts and high-temperature refractories as key components. Commodity price volatility for natural gas presents a structural risk, while distribution runs through dedicated pipeline networks within industrial clusters or via industrial gas suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents in the Steam Methane Reforming market face a substitution defense challenge against the rising viability of green hydrogen. Navigating this threat requires strategic adjustments to maintain market share and profitability.
For Market Incumbents: Fortify existing SMR assets through CCUS integration, leveraging tax credits like the US Inflation Reduction Act's 45Q and 45V. Pursue backward integration into natural gas supply to mitigate feedstock price volatility, a persistent margin pressure point. Invest in advanced catalyst R&D to enhance efficiency, further defending against green hydrogen competition. Expand long-term offtake agreements with anchor industrial customers.
For New Entrants and Emerging Players: Low-carbon hydrogen certification fast-tracks, particularly under the EU Green Deal, offer a strategic entry point for SMR with CCUS projects. Target industrial clusters in regions with nascent CO2 infrastructure, such as emerging hubs in the Middle East, for new blue hydrogen facilities. Focus on specialized applications like sustainable aviation fuels and e-methanol production, which represent high-value, underserved segments. Offer integrated project development and financing solutions as a go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward technology licensors specializing in advanced SMR and ATR designs, offering long-term viability over a 5-10 year window. Seek acquisition targets with proven CCUS integration capabilities and established pipeline networks within industrial zones. These assets provide critical infrastructure for blue hydrogen deployment. The signal to watch is the accelerated deployment of CO2 transport and storage infrastructure in key industrial clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop advanced ATR technology | This initiative enhances efficiency and CO2 capture suitability for new blue hydrogen projects. |
| Invest in CO2 pipeline infrastructure | This investment unlocks large-scale CCUS deployment in US Gulf Coast industrial clusters. |
| Secure long-term natural gas supply contracts | These contracts mitigate feedstock price volatility for SMR operators like Linde plc. |
| Expand into sustainable aviation fuel production | This expansion creates a new high-value demand vector for SMR with CCUS outputs. |
| Retrofit existing grey hydrogen plants with CCUS | This move aligns SMR facilities with EU Green Deal low-carbon hydrogen incentives. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. We engaged plant managers, procurement leads at petrochemical plants, R&D directors, and industrial gas suppliers. Secondary validation drew from US EPA reports, EU Green Deal policy documents, and company 10-K filings. This approach facilitated robust bottom-up and top-down triangulation of market data.
The forecast horizon spans across the analysis window, utilizing a comprehensive analytical framework. Segmentation dimensions modeled include product type, technology, application, end-user industry, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected technological adoption. Key inputs included natural gas price projections and CCUS deployment rates.
Underlying assumptions cover regulatory stability and sustained industrial decarbonization efforts, with deviation risk concentrated in rapid shifts in green hydrogen economics or unforeseen policy changes. Forecasts reflect these assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
Refinery Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Homogeneous Catalyst Market