
 Chevron Seals Market | 2026-2036
Chevron Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Chevron Seals Market Analytics
China is reconfiguring regional supply dynamics through expanded fluoroelastomer compounding capacity and precision molding investments. Freudenberg Sealing Technologies leverages backward integration into custom polymer development to sustain margin resilience. Trelleborg Sealing Solutions anchors its position through marine and offshore specialization. SKF competes via integrated bearing-seal system architectures that reduce procurement complexity for OEM buyers.
Chevron seals are multi-lip elastomeric or thermoplastic sealing elements stacked in a V-shaped configuration, typically rated for pressures from 5,000 to 10,000 psi and temperatures spanning -40°F to 400°F depending on material grade, designed to prevent fluid leakage in reciprocating or static assemblies. Their primary purpose centers on maintaining system integrity in hydraulic cylinders, wellhead equipment, and process valves where single-lip designs fail under pressure cycling or chemical exposure. Hydraulic seals command the largest volume share due to pervasive deployment in construction and mining machinery, though PTFE-based materials represent the fastest-expanding margin pool as operators seek extended service intervals in corrosive media. Aerospace end-use generates premium pricing power through certification-driven material traceability and lot-controlled manufacturing.
EPA fugitive emissions regulations under New Source Performance Standards compel seal replacement cycles in US refining and chemical processing, while REACH restrictions on perfluorinated compounds in Europe redirect formulation roadmaps toward hydrogenated nitrile alternatives. China's GB standards for hydraulic equipment safety create localized testing and certification barriers for imported seal assemblies. Stakeholders must monitor polymer substitution timelines and regional qualification protocols to align capacity investments with shifting compliance baselines.
Market Dynamics
Downstream infrastructure operators are compressing replacement cycles for sealing systems as EPA fugitive emissions standards tighten enforcement thresholds, forcing capital allocation toward higher-performance elastomer formulations.
Growth Catalysts
- EPA New Source Performance Standards:Refining and chemical processing operators face mandatory seal replacement protocols, accelerating demand for fluorocarbon and hydrogenated nitrile grades certified to 10,000 psi ratings.
- Shale basin equipment intensity:Permian and Bakken wellhead operations require redundant sealing architectures for high-pressure hydraulic fracturing equipment, concentrating procurement volumes with domestic distributors.
- PTFE compounding advances:Extended service interval formulations now withstand aromatic hydrocarbon exposure, displacing conventional nitrile rubber in corrosive process valve applications.
Market Restraints
- Fluoroelastomer feedstock volatility:Hexafluoropropylene and vinylidene fluoride monomer prices swing with refrigerant chemical demand, squeezing compounder margins and destabilizing long-term supply agreements.
- Chinese molding capacity concentration:Precision V-seal fabrication gravitates toward Zhejiang and Jiangsu provinces, creating single-source dependency risks for North American OEMs qualifying alternative suppliers.
- REACH perfluorinated compound restrictions:ECHA authorization requirements for PFAS-containing formulations force European operators toward hydrogenated nitrile substitutes with narrower temperature envelopes.
Strategic Opportunities
- India PLI scheme for hydraulic equipment:Domestic content incentives for construction and mining machinery create localized seal assembly demand requiring GB-standard certification partnerships.
- Carbon capture injection systems:Supercritical CO2 handling infrastructure demands specialized low-permeability elastomers, opening premium pricing tiers for compounders with rapid qualification capabilities.
- Digital twin integration:Seal wear prediction algorithms embedded in IoT-enabled hydraulic systems enable predictive replacement service models, shifting revenue from product sales to performance contracts.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for high-pressure hydrogen service seals remains concentrated among retiring specialists at legacy compounders, constraining new product development timelines.
- API 6A certification backlog:Wellhead equipment qualification protocols require 18-24 month validation cycles, delaying commercialization of next-generation temperature-resistant grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chevron Seals Market |
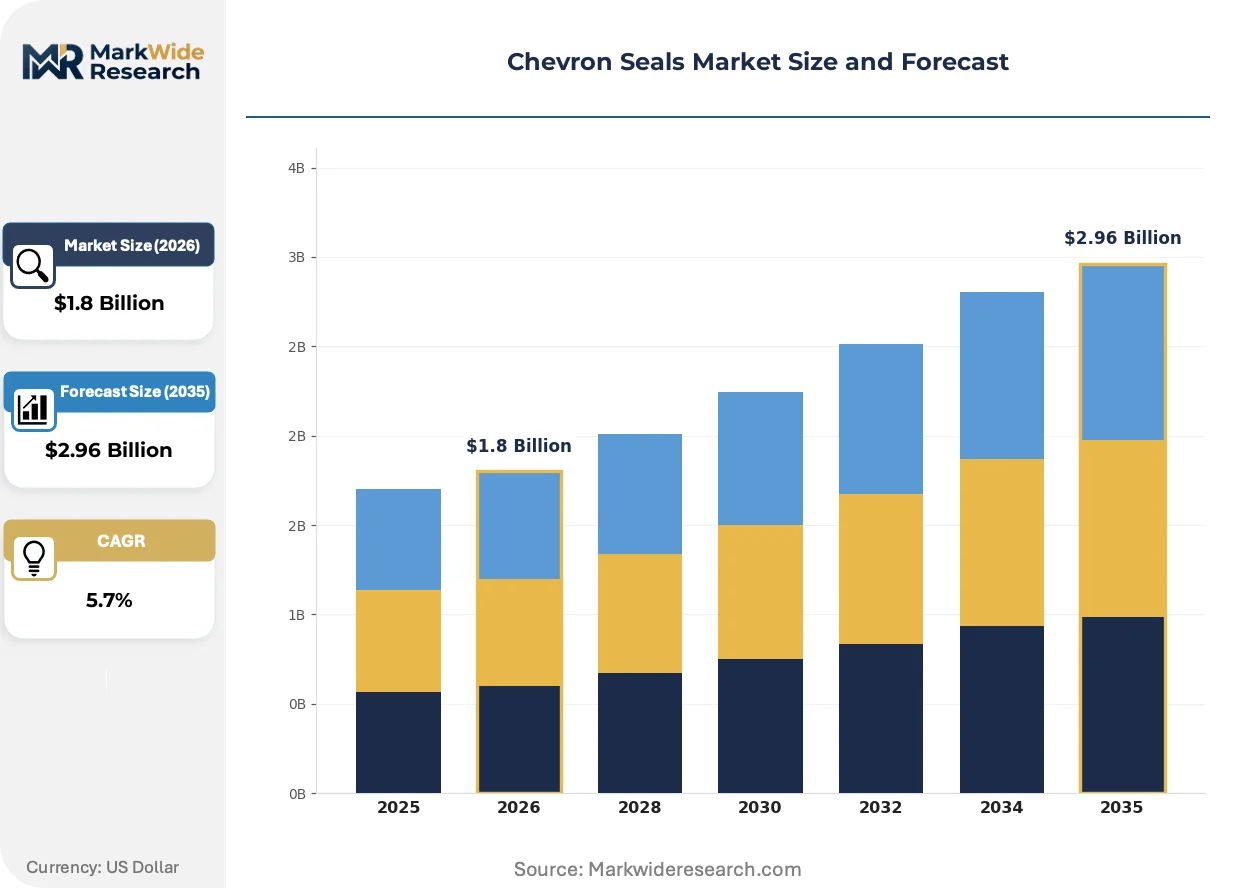
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Seals, Pneumatic Seals, Rotating Seals, Static Seals Material: Rubber, PTFE, Nitrile, Silicone End User: Aerospace, Automotive, Industrial Equipment, Oil & Gas Application: Sealing Systems, Pumps, Valves, Compressors |
| Companies Covered | Freudenberg Sealing Technologies, Trelleborg Sealing Solutions, Parker Hannifin Corporation, SKF, EagleBurgmann, Garlock Sealing Technologies, Chesterton, Greene Tweed, Kalsi Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chevron Seals Market Evolving Landscape
Material science breakthroughs and regulatory enforcement patterns are compressing traditional equipment lifecycles while opening premium segments for certified specialty formulations.
Additive manufacturing of thermoplastic elastomer seal geometries is rendering obsolete conventional mold-and-trim production for prototype and low-volume aerospace applications. Tier-one hydraulic OEMs now specify 3D-printed V-seal stacks for flight control actuator development programs, collapsing lead times from twelve weeks to seventy-two hours and eliminating hard-tooling capital for sub-thousand-unit orders.
REACH F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin refrigerant transitions, indirectly constraining legacy fluoroelastomer supply chains dependent on tetrafluoroethylene co-monomer streams. European process valve manufacturers are reformulating seal specifications toward hydrogenated nitrile and thermoplastic polyurethane alternatives, triggering two-year requalification programs for existing equipment installations.
Consolidated procurement through integrated bearing-seal system architectures is displacing discrete component sourcing for construction equipment OEMs. Komatsu and Caterpillar procurement divisions now specify complete actuator subassemblies rather than individual seal kits, compressing vendor bases and elevating technical service capabilities above unit pricing in supplier selection criteria across North American and Australian mining operations.
Chevron Seals Market Segmentation
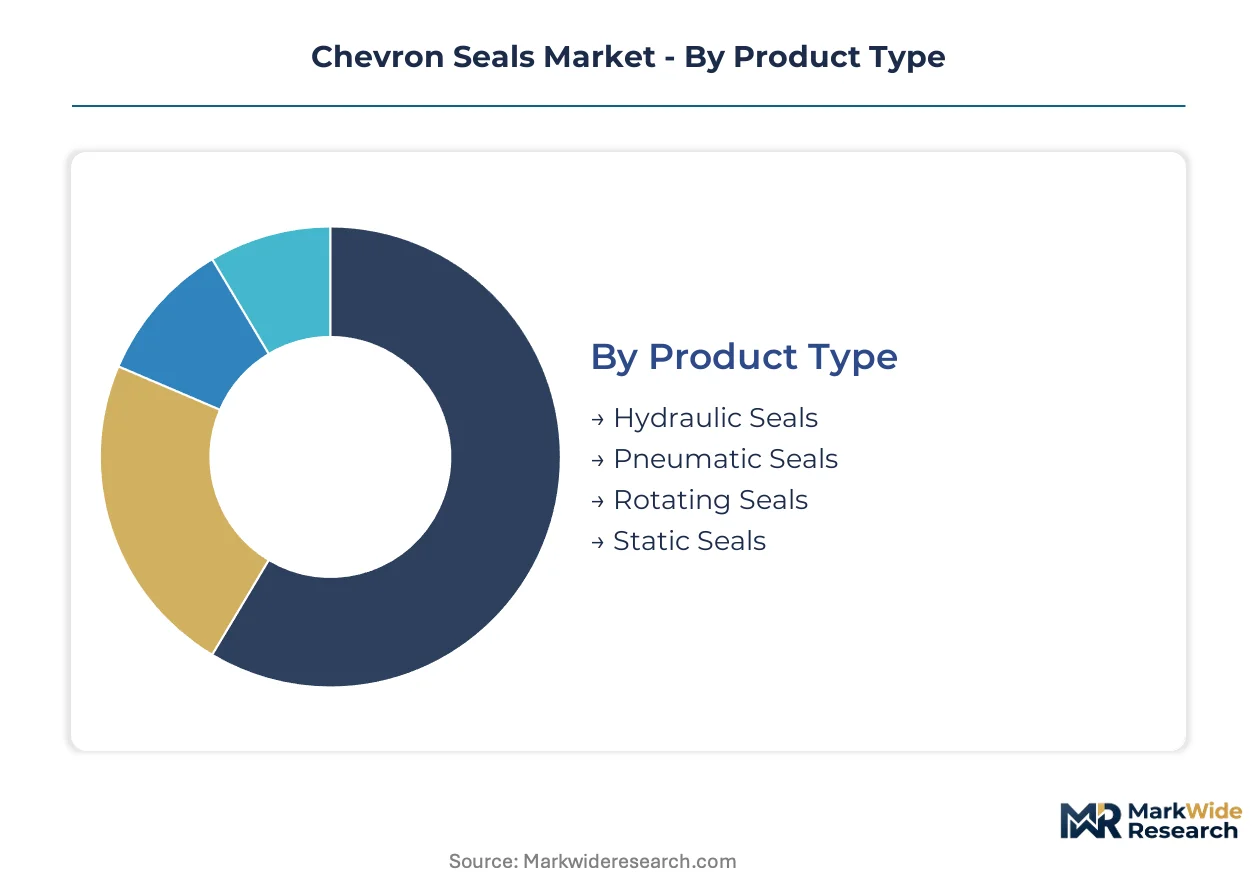
Chevron seals serve radically different duty cycles across applications, from the continuous reciprocation of hydraulic cylinders to the static compression of wellhead flanges. Understanding which segments compress replacement intervals versus extend service life shapes procurement strategy and compounder R&D allocation.
Product Type:
Hydraulic seals turn over fastest under high-cycle mining and construction equipment, while static seals in wellhead assemblies persist for years before scheduled replacement.
- Hydraulic Seals:Multi-lip elastomeric stacks rated for 5,000-10,000 psi pressure cycling dominate construction machinery and mining equipment fleets. Permian Basin fracturing operations concentrate demand for redundant sealing architectures that withstand aromatic hydraulic fluid exposure.
- Pneumatic Seals:Lower-pressure V-configurations optimized for air and inert gas retention serve factory automation and material handling systems. German automotive stamping plants drive specification tightening for ISO-standard cleanliness compliance.
- Rotating Seals:PTFE-composite designs manage shaft speeds in process pumps and compressor crankcases.
- Static Seals:Compression-set resistant formulations seal flange joints and valve bonnets with minimal movement.
Hydraulic seals dominate installed base. Pneumatic seals are where expansion concentrates.
Material:
Cost tiers separate commodity nitrile compounds from fluorocarbon grades commanding 3-4x pricing for corrosive service.
- Rubber:General-purpose elastomeric formulations balance cost and performance for standard industrial hydraulics. Indian construction equipment manufacturing under PLI scheme incentives is absorbing volume for domestically compounded grades.
- PTFE:Sintered and filled polytetrafluoroethylene compounds deliver near-zero friction and chemical inertness for extended service intervals. US Gulf Coast petrochemical processors specify PTFE-based V-seals to satisfy EPA fugitive emissions monitoring requirements.
- Nitrile:Hydrogenated variants (HNBR) bridge temperature and chemical resistance for mid-tier applications.
- Silicone:Extreme-temperature flexibility serves aerospace actuators and food-grade processing equipment.
Rubber dominates installed base. PTFE is where expansion concentrates.
End User:
Application maturity varies sharply—oil and gas infrastructure runs decades-old specifications while aerospace demands lot-controlled traceability.
- Oil & Gas:Wellhead, pipeline, and downstream processing equipment consumes the largest absolute volume of high-pressure V-seal configurations. EPA New Source Performance Standards enforcement is compressing replacement cycles across US refining corridors.
- Industrial Equipment:Construction, mining, and agricultural machinery manufacturers specify seal kits through integrated actuator procurement. Caterpillar and Komatsu procurement divisions now source complete hydraulic subassemblies rather than discrete components.
- Aerospace:Certification-driven material traceability and temperature extremes generate premium pricing tiers.
- Automotive:Steering and suspension hydraulics consume standardized high-volume seal configurations.
Industrial equipment dominates installed base. Oil and gas is where expansion concentrates.
Application:
Volume concentrates in sealing systems sold as integrated kits, while discrete valve and pump components serve maintenance-aftermarket channels.
- Sealing Systems:Pre-assembled V-stack configurations and integrated bearing-seal modules reduce OEM procurement complexity. SKF and Freudenberg supply complete actuator sealing architectures to construction equipment manufacturers.
- Valves:Process control and isolation valves require chemically resistant compounds for corrosive hydrocarbon and acid service. REACH F-Gas Regulation phase-downs are forcing European operators toward hydrogenated nitrile reformulations.
- Pumps:Centrifugal and positive displacement pump shaft seals manage pressure differentials and particulate ingress.
- Compressors:Reciprocating and rotary screw compressor piston and rod sealing manages gas compression cycles.
Sealing systems dominate installed base. Valves are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor anchors North American demand for high-pressure sealing systems, with downstream refineries and export terminals driving specification tightening for fugitive emissions compliance.
United States
Permian Basin fracturing operations concentrate procurement volumes for redundant hydraulic sealing architectures rated above 10,000 psi. EPA New Source Performance Standards enforcement compresses replacement cycles across Gulf Coast refining corridors. Houston-area distributors stock fluorocarbon and hydrogenated nitrile grades to satisfy same-day delivery requirements for emergency maintenance.
Germany
Automotive stamping plants in Baden-Württemberg and Bavaria drive specification tightening for pneumatic seal cleanliness under ISO standards. ECHA REACH restrictions on perfluorinated compounds force reformulation roadmaps toward hydrogenated nitrile alternatives. Stuttgart-based hydraulic OEMs now specify complete actuator subassemblies rather than discrete seal kits.
China
Zhejiang and Jiangsu provinces concentrate precision V-seal molding capacity serving domestic construction equipment manufacturing. GB standards for hydraulic equipment safety create localized testing barriers for imported seal assemblies. Shanghai petrochemical processors specify PTFE-based configurations to satisfy emissions monitoring protocols.
India
Construction and mining machinery production under PLI scheme incentives absorbs volume for domestically compounded rubber grades. Maharashtra and Gujarat host seal assembly operations requiring BIS certification partnerships. Mumbai-based distributors stock standard hydraulic configurations for aftermarket replacement cycles.
Saudi Arabia
Jubail Industrial City downstream complexes specify high-temperature elastomer formulations for sour gas processing applications. The country's national hydrocarbon regulator mandates leak detection protocols that accelerate seal replacement frequencies. Dammam-based service contractors maintain strategic inventories for wellhead maintenance campaigns.
Chevron Seals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and precision molding capabilities. The vendor base organizes around three strategic archetypes: integrated bearing-seal system architects, backward-integrated polymer compounders, and marine-offshore specialization houses. Dominant competitive moves include captive supply chain control over custom elastomer development and geographic expansion through localized certification partnerships.
Among European-based sealing specialists, Freudenberg Sealing Technologies and Trelleborg Sealing Solutions exemplify divergent strategic positions—one representing backward-integrated polymer science capabilities, the other anchoring marine and offshore application expertise. SKF occupies a position bridging mechanical systems and sealing technology through integrated architectures that reduce procurement complexity for OEM buyers.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies |
| Trelleborg Sealing Solutions |
| Parker Hannifin Corporation |
| SKF |
| EagleBurgmann |
| Garlock Sealing Technologies |
| Chesterton |
| Greene Tweed |
| Kalsi Engineering, Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Zhejiang and Jiangsu precision molding corridors is driving supplier selectivity and hardening price terms for North American OEMs qualifying alternative sources. This utilization squeeze simultaneously elevates minimum order thresholds and compresses lead-time flexibility across fluorocarbon and hydrogenated nitrile grade negotiations.
Pricing Analysis
Volume-discount tiering structures separate spot purchasers from contract-of-take buyers across API 6A-certified and standard industrial grades. Price differentiation centers on certification tier—API 6A wellhead specifications command substantial premiums over general hydraulic configurations—and geographic delivery cost differentials between Asian compounding hubs and Gulf Coast distribution points. Cost compression in standard nitrile rubber grades is intensifying because Chinese molding capacity expansion outpaces demand absorption in construction equipment channels. Aftermarket maintenance buyers exhibit highest price sensitivity, while aerospace OEMs prioritize lot-controlled traceability over unit economics.
Supply Chain Analysis
Upstream feedstock availability for hexafluoropropylene and vinylidene fluoride monomers draws from Chinese refrigerant chemical production, Belgian specialty chemical synthesis, and Japanese fluoroelastomer resin operations. Raw material dependencies encompass fluoropolymer resins, hydrogenated nitrile base polymers, and precision-machined PTFE billets. Single-source vulnerability concentrates in Zhejiang province V-seal fabrication, where consolidation among three precision molders creates qualification bottlenecks for alternative supplier onboarding. Distribution runs through Houston-area distributors for emergency maintenance, Stuttgart-based hydraulic OEM direct procurement, and Mumbai aftermarket channels serving Indian construction equipment fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase anchored by EPA enforcement acceleration compressing replacement cycles across Gulf Coast refining infrastructure. The downstream capital expenditure cycle in petrochemical processing is amplifying demand visibility for certified high-pressure sealing architectures.
For Market Incumbents: Pre-empt polymer substitution timelines by accelerating hydrogenated nitrile qualification programs ahead of REACH F-Gas Regulation phase-downs. Captive supply of custom elastomer formulations through backward integration into compounding operations defends margin position against feedstock volatility. Lock in long-term offtake agreements with Permian Basin service contractors before Chinese competitors complete GB-standard certification partnerships.
For New Entrants and Emerging Players: Carbon capture injection system seal applications represent the most penetrable entry point, as supercritical CO2 service demands specialized low-permeability compounds where incumbent qualification backlogs create procurement gaps. India's PLI scheme for hydraulic equipment offers localized assembly partnerships requiring BIS certification rather than full polymer science capabilities. Target predictive replacement service models enabled by IoT wear monitoring as a go-to-market angle displacing product-centric competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with captive polymer development and rapid qualification capabilities serving EPA-regulated replacement cycles. Long-term viability over the coming decade favors specialists with API 6A certification infrastructure and aerospace material traceability systems rather than commodity hydraulic seal assemblers. Watch for inflection in carbon capture infrastructure procurement timelines as the signal for premium pricing tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Polymer Development | Freudenberg's captive elastomer formulation shields margins from hexafluoropropylene price volatility. |
| API 6A Certification Infrastructure Investment | Eighteen-month validation cycles create defensive moats for wellhead equipment seal suppliers. |
| Digital Twin Integration for Predictive Replacement | IoT-enabled wear algorithms shift revenue from product sales to performance contracts at SKF. |
| Localized Certification Partnerships in India | BIS-compliant assembly operations capture PLI scheme incentives for domestic construction equipment. |
| PTFE Compounding Capacity Expansion | Extended service interval formulations displace nitrile rubber in EPA-monitored fugitive emissions applications. |
Research Methodology
Initial hypotheses were tested against primary input from hydraulic OEM procurement directors, petrochemical maintenance managers, and polymer compounder R&D leads and refined through secondary validation against API certification databases, EPA enforcement disclosure filings, and REACH authorization registers. Bottom-up triangulation across construction equipment production forecasts and top-down reconciliation with downstream refining capital expenditure patterns anchored volume estimates. Customs data tracking fluoroelastomer resin trade flows and SEC filings from listed sealing specialists provided cross-reference points for margin structure assumptions.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, material grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from equipment fleet replacement cycle modeling and emissions compliance deadline alignment. Industry-specific forecast inputs incorporated Permian Basin fracturing intensity projections and ECHA F-Gas Regulation phase-down schedules affecting polymer formulation roadmaps.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles or refrigerant chemical demand patterns would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement continuity and REACH authorization timelines. Cross-checking against API wellhead equipment certification backlogs and BIS registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Releasing Agents Market