
 China Starch and Starch Derivatives Market | 2026-2036
China Starch and Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
China Starch and Starch Derivatives Market Outlook
China's GB standards for food additives is broadening the compliance burden for new entrants. Yihai Kerry Group leverages its integrated crushing and refining footprint across coastal provinces to sustain cost advantages. Shandong Fuyang Bio-Tech anchors its position through deep specialization in modified starch derivatives for industrial binders. Qingdao CBH Co. Ltd differentiates via export-grade certification protocols that navigate dual domestic and overseas compliance requirements.
Starch and starch derivatives comprise carbohydrate polymers extracted from cereal grains, tubers, and root crops through wet milling, separation, and enzymatic or chemical modification processes yielding native starches, dextrins, maltodextrins, and chemically altered variants with specified viscosity, gelatinization temperature, and amylose content for thickening, binding, film-forming, and stabilizing functions across food, pharmaceutical, and industrial applications. Corn starch dominates volume throughput due to abundant domestic maize supply and established wet-milling infrastructure, while pharmaceutical-grade maltodextrins command premium positioning amid stricter purity benchmarks. Food and Beverage applications absorb the largest value share as instant noodle, sauce, and bakery manufacturers reformulate with clean-label modified starches.
SAMR's GB standards, the Ministry of Agriculture's quality protocols for feed-grade starches, and provincial environmental regulations under MEE collectively determine facility licensing, effluent discharge limits, and product labeling requirements across China's starch processing belt. Food-grade certification timelines have lengthened as SAMR tightens additive approval pathways, advantaging incumbents with established testing infrastructure. Stakeholders must monitor how Shandong and Jilin provincial governments allocate water-use permits amid intensifying scrutiny of wet-milling's consumption intensity.
Market Dynamics
SAMR's tightened GB standards for food additives are forcing facility-level compliance investments across Shandong and Jilin processing corridors. Wet-milling operators must simultaneously absorb water-use permit restrictions under MEE provincial enforcement while meeting reformulated product specifications from domestic food manufacturers.
Growth Catalysts
- Clean-label reformulation mandates:Domestic instant noodle and sauce manufacturers are substituting modified starches for synthetic thickeners. SAMR's additive restrictions accelerate this ingredient transition.
- GB 2760-2024 implementation:The updated food safety standard creates qualification barriers that favor established processors with in-house testing infrastructure.
- Pharmaceutical-grade maltodextrin demand:Stricter purity benchmarks from NMPA are pulling higher-margin specialty production into domestic supply chains.
Market Restraints
- Maize price volatility:Input cost swings from state grain reserve auctions compress margin predictability for corn starch derivatives.
- Water-use permit scarcity:MEE scrutiny of wet-milling intensity in Shandong limits capacity expansion at existing facilities.
- Enzymatic conversion bottlenecks:Specialized amylase supply concentration constrains modified starch yield consistency.
Strategic Opportunities
- Jilin province capacity expansion:Northeastern corn belt proximity offers logistics advantages for feed-grade starch derivatives serving animal nutrition formulators.
- Industrial binder applications:Paper and textile manufacturers are qualifying modified starches as petrochemical adhesive replacements.
- Dual certification protocols:Export-grade processors can capture premium positioning through simultaneous ISO and GB compliance documentation.
Industry Challenges
- Food-grade certification timelines:SAMR's lengthened additive approval pathways delay new product commercialization by 18-24 months.
- Effluent treatment capex:MEE discharge limit enforcement requires membrane bioreactor installations that strain mid-scale operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Starch and Starch Derivatives Market |
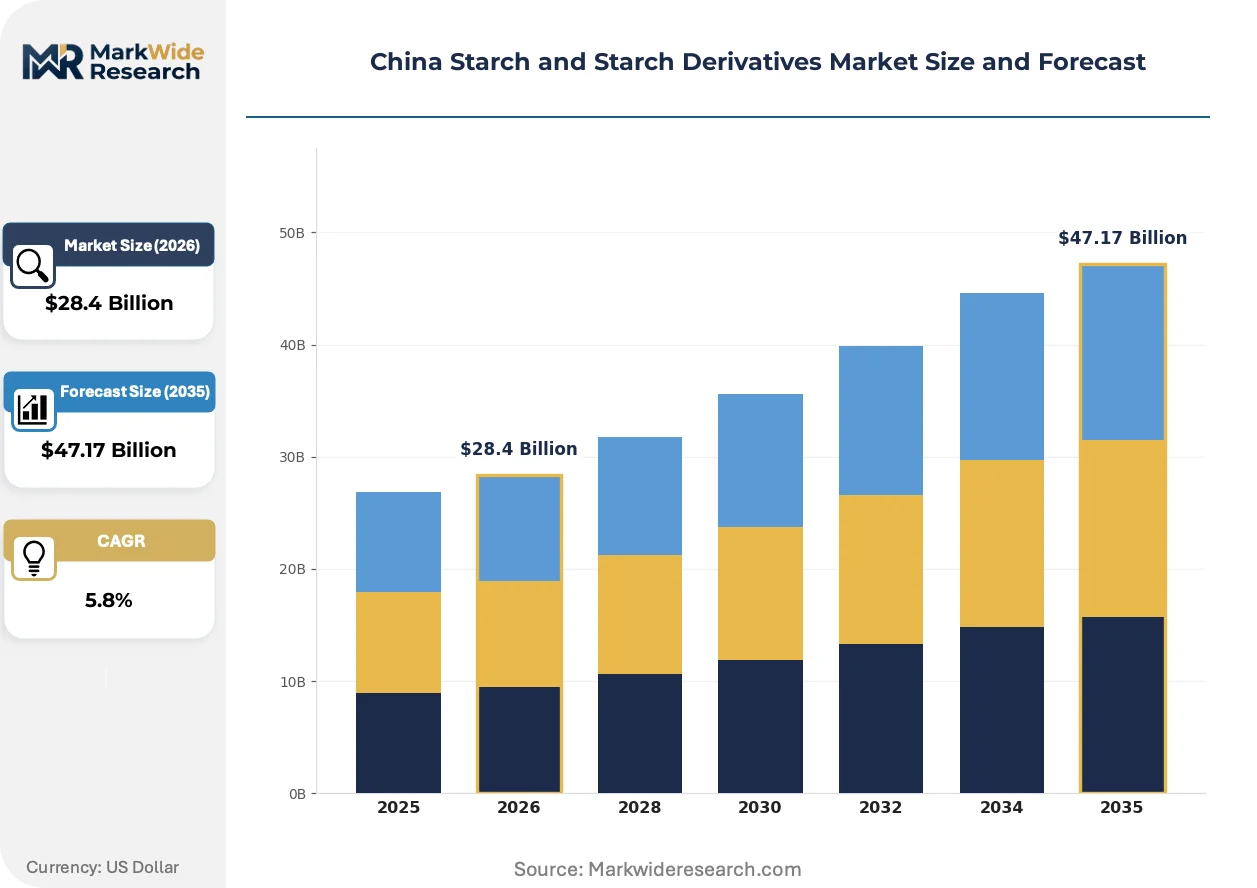
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Starch, Wheat Starch, Potato Starch, Tapioca Starch Application: Food & Beverage, Pharmaceuticals, Animal Feed, Personal Care Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Distribution Channel: Online Retail, Supermarkets, Distributors, Direct Sales |
| Companies Covered | Zhangzhou Haoshun Food Co., Ltd., Suzhou Lonf Biotechnology Co., Ltd., Aurora Industry Co., Ltd., Qingdao CBH Co. Ltd, Zhongshan Jolion Foodstuffs Co., Ltd., Shanghai Litian Industrial Co., Ltd., Shandong Fuyang Bio-Tech Co., Ltd., Yihai Kerry Group, Foodchem International Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Starch and Starch Derivatives Market Strategic Shifts
Enzymatic modification platforms are displacing chemical processing routes across China's starch derivatives sector. This shift alters capital deployment patterns and reconfigures supplier relationships between mills and enzyme houses.
Continuous enzymatic hydrolysis systems are integrating into Shandong wet-milling operations. Instant noodle manufacturers adopt these modified starches for precise viscosity control during production. The technology is integrating process efficiency gains that compress unit costs against conventional batch acid-thinning methods.
GB 2760-2024 additive specifications are tightening maximum residue limits for chemical modification reagents. Processors must validate alternative enzymatic pathways or absorb purification cost increases. Pharmaceutical-grade maltodextrin producers face the steepest compliance burden under NMPA cross-referenced purity requirements.
Direct mill-to-manufacturer contracting is displacing layered distribution for large-volume food accounts. Bakery and sauce producers in coastal provinces negotiate specification-grade supply agreements that bypass traditional chemical distributors. This pattern concentrates procurement leverage among processors with coastal logistics infrastructure and dual certification capability.
China Starch and Starch Derivatives Market Segmentation
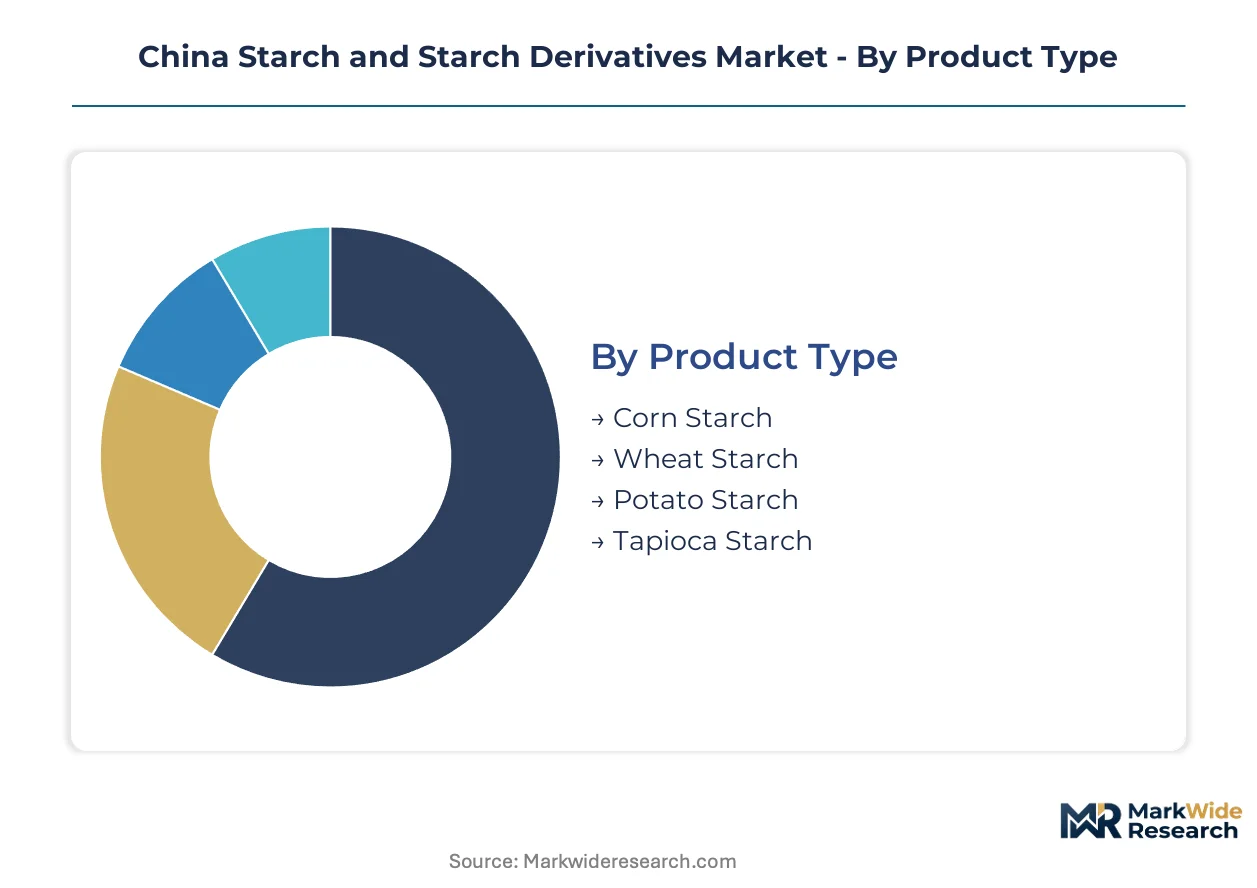
China's starch derivatives market fragments across four distinct dimensions that determine pricing power, compliance burden, and channel strategy. Product type dictates raw material sourcing geography and wet-milling infrastructure requirements. Application segments impose divergent purity standards from SAMR, NMPA, and Ministry of Agriculture protocols.
Product Type:
Corn starch commands volume dominance through Shandong and Jilin processing corridors, while specialty starches capture premium positioning in coastal reformulation markets.
- Corn Starch:Extracted via wet-milling of domestic maize with amylose content ranging from 25-28%. Instant noodle manufacturers in coastal provinces absorb the largest volume flows as SAMR's additive restrictions accelerate clean-label transitions.
- Wheat Starch:Separated from gluten through Martin or batter processes yielding low-protein fractions below 0.3%. Bakery applications in Jiangsu and Zhejiang drive demand as laminated dough producers seek European-style texture profiles.
- Potato Starch:High-viscosity cold-swelling properties suit sauce thickening applications in Sichuan and Chongqing processing clusters.
- Tapioca Starch:Southeast Asian import dependency constrains price stability for bubble tea and dessert manufacturers in Guangdong.
Today's leader: Corn Starch. Tomorrow's challenger: Potato Starch.
Application:
End-use concentration determines certification complexity and margin structure across SAMR-regulated food systems versus NMPA pharmaceutical pathways.
- Food & Beverage:Absorbs the largest value share across instant noodle, sauce, and bakery sub-segments. Modified starch reformulation accelerates as domestic brands eliminate synthetic thickeners under GB 2760-2024 timelines.
- Pharmaceuticals:Maltodextrin excipients and tablet binders face NMPA purity benchmarks that lengthen approval pathways. Shandong processors with dedicated pharmaceutical lines capture premium positioning.
- Animal Feed:Feed-grade starch derivatives from Jilin province serve Northeastern livestock nutrition formulators under Ministry of Agriculture quality protocols.
- Personal Care:Modified starches function as natural rheology modifiers in shampoo and lotion formulations for domestic beauty brands.
Food & Beverage maintains volume dominance. Pharmaceuticals climbs fastest on purity premium capture.
Grade:
Certification tier directly determines facility investment requirements and customer qualification barriers across SAMR, NMPA, and industrial standards.
- Food Grade:GB standards compliance mandates HACCP implementation and additive residue testing. SAMR's tightened approval pathways favor incumbents with established laboratory infrastructure.
- Pharmaceutical Grade:NMPA cross-referenced purity requirements impose the steepest compliance burden with endotoxin and heavy metal specifications.
- Industrial Grade:Paper and textile binder applications qualify modified starches as petrochemical adhesive replacements under less stringent protocols.
- Technical Grade:Construction and adhesive sectors absorb lower-purity derivatives with minimal regulatory oversight.
Food Grade dominates transaction volume. Pharmaceutical Grade expands most quickly on margin expansion.
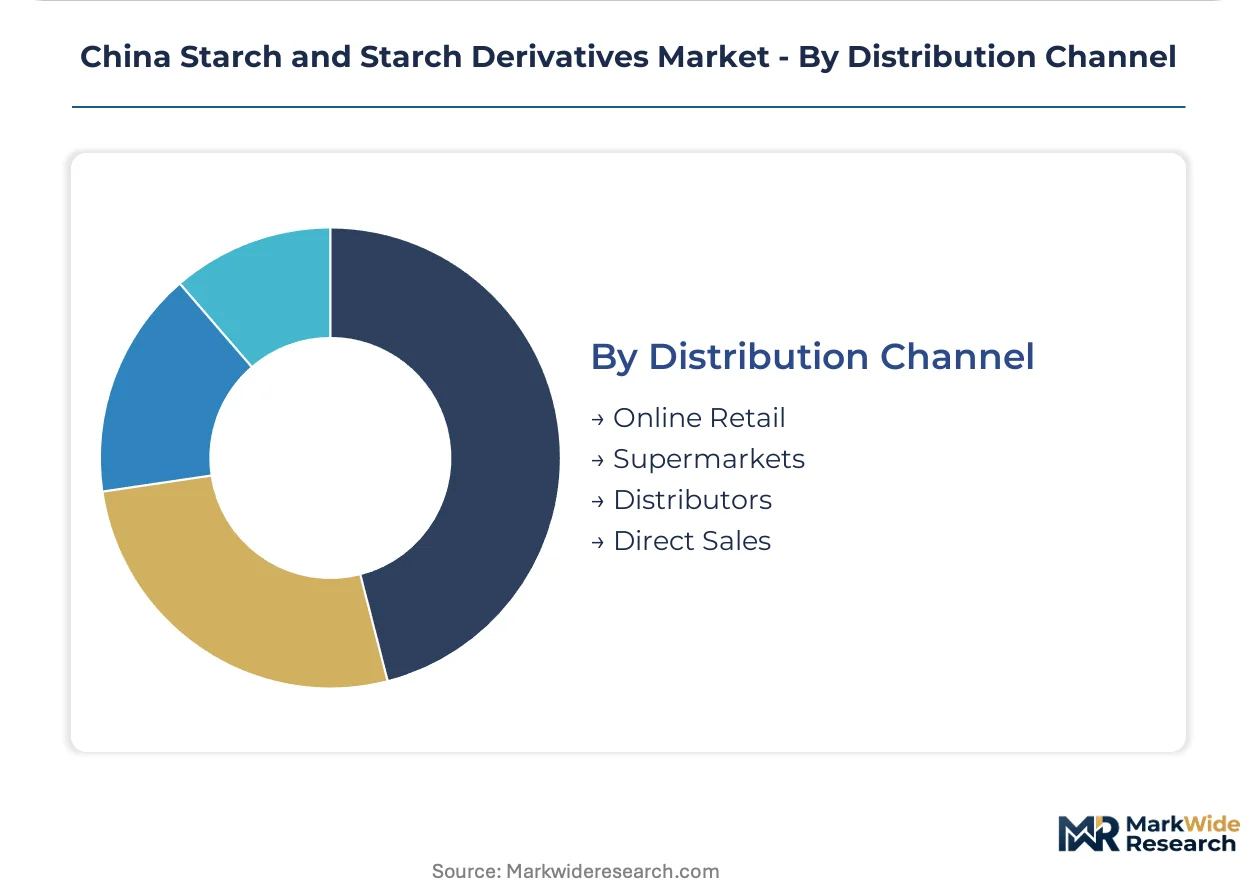
Distribution Channel:
Channel selection reflects customer scale, specification complexity, and certification documentation requirements.
- Direct Sales:Large-volume food manufacturers negotiate specification-grade supply agreements bypassing traditional chemical distributors. Coastal logistics infrastructure and dual certification capability concentrate procurement leverage.
- Distributors:Layered networks serve mid-scale processors lacking in-house procurement teams across inland provinces.
- Supermarkets:Consumer-packaged native starches for home cooking applications in tier-one cities.
- Online Retail:E-commerce platforms capture specialty starch demand from small-scale food entrepreneurs and regional bakeries.
Direct Sales commands the largest volume flows. Online Retail gains share fastest on SME customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled chemical engineers and food technologists cluster along China's eastern seaboard and northeastern corn belt, anchoring the country's starch processing capacity. Provincial industrial policies channel investment toward these established corridors.
Shandong Province
Instant noodle manufacturers in Jinan and Qingdao absorb modified starches for clean-label reformulation. MEE water-use permits restrict wet-milling expansion in the Yellow River basin. Weifang's chemical processing corridor hosts enzymatic modification facilities serving coastal food brands.
Jilin Province
Feed-grade starch derivatives supply Northeastern livestock nutrition formulators under Ministry of Agriculture protocols. State grain reserve auctions from the Songliao Plain moderate input cost volatility. Changchun's agro-industrial zone anchors corn wet-milling capacity expansion.
Jiangsu Province
Laminated dough producers in Suzhou and Wuxi source wheat starches for European-style bakery applications. SAMR's GB 2760-2024 additive restrictions accelerate synthetic thickener substitution. Nanjing's food science research institutes collaborate with processors on modified starch functionality.
Guangdong Province
Bubble tea and dessert manufacturers in Guangzhou and Shenzhen drive tapioca starch demand despite Southeast Asian import dependency. Dual certification protocols for export-grade products concentrate procurement leverage among processors with Pearl River Delta logistics infrastructure.
Sichuan-Chongqing Region
Sauce thickening applications in Chengdu and Chongqing absorb high-viscosity potato starches for regional cuisine formulations. Provincial environmental regulations under MEE shape effluent discharge limits for processing facilities. The Yangtze River corridor enables bulk starch logistics to interior markets.
China Starch and Starch Derivatives Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's starch derivatives sector. The vendor base organizes into three tiers: integrated agribusiness groups with crushing and refining footprints, regional wet-milling operators with provincial supply agreements, and export-certified processors with dual compliance documentation. Strategic moves center on enzymatic technology licensing and backward integration into maize sourcing networks.
Among coastal integrated processors, Yihai Kerry Group and Qingdao CBH Co. Ltd occupy positions within the top tier, while Shandong Fuyang Bio-Tech Co., Ltd. exemplifies the specialized derivative manufacturer archetype. These entities represent contrasting approaches to navigating SAMR's tightened certification timelines and MEE's water-use restrictions.
| Leading Market Players |
|---|
| Zhangzhou Haoshun Food Co., Ltd. |
| Suzhou Lonf Biotechnology Co., Ltd. |
| Aurora Industry Co., Ltd. |
| Qingdao CBH Co. Ltd |
| Zhongshan Jolion Foodstuffs Co., Ltd. |
| Shanghai Litian Industrial Co., Ltd. |
| Shandong Fuyang Bio-Tech Co., Ltd. |
| Yihai Kerry Group |
| Foodchem International Corporation |
| Others |
Value Chain & Pricing Dynamics
Enzymatic modification platform adoption across Shandong wet-milling corridors simultaneously compresses unit production costs and concentrates procurement leverage among processors with in-house enzyme supply agreements. This technology transition rewards coastal integrated operators while squeezing mid-scale facilities dependent on batch chemical processing routes.
Pricing Analysis
Unbundled enzyme supply contracts versus bundled modification-service agreements split pricing structures across the value chain. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels captures purity premium differentials under NMPA and SAMR protocols. Cost compression in feed-grade derivatives is intensifying because state grain reserve auction volatility passes directly to contract pricing. Small-scale inland processors exhibit highest price sensitivity, while coastal instant noodle manufacturers prioritize specification stability over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements from coastal food manufacturers mandate Shandong and Jilin supplier diversification across their approved vendor lists. Geographic supply concentration centers on domestic maize from the Songliao Plain, specialized amylase enzymes from international enzyme houses, and tapioca starch from Southeast Asian processing clusters. Single-source vulnerability in pharmaceutical-grade maltodextrin purification equipment creates bottlenecks for NMPA-certified lines. Distribution runs through direct mill-to-manufacturer contracting for large-volume accounts, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's starch derivatives market reads as a late-cycle quality story as pharmaceutical-grade maltodextrin demand pulls premium specifications into domestic supply chains under stricter NMPA purity benchmarks.
For Market Incumbents: To counter enzymatic technology licensing concentration among coastal integrated processors, mid-scale operators should pursue backward integration into captive maize sourcing networks in Jilin province and invest in dual GB-ISO certification infrastructure to defend specification-grade contract renewals. For New Entrants and Emerging Players: Capture white-space opportunity in industrial binder applications for paper and textile manufacturers qualifying petrochemical adhesive replacements, targeting Sichuan-Chongqing sauce thickening segments with high-viscosity potato starch specialization, and leveraging e-commerce platforms for SME bakery customer acquisition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional wet-milling operators with provincial supply agreements but lacking pharmaceutical-grade certification infrastructure. Long-term viability hinges on 5-10 year water-use permit security under MEE enforcement patterns. The signal to watch is SAMR additive approval pathway acceleration versus continued timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Technology Licensing | Processors securing amylase supply partnerships capture yield consistency advantages over chemical modification competitors. |
| Backward Integration into Maize Sourcing | Direct state grain reserve auction participation insulates margin volatility from spot market price swings. |
| Dual Certification Infrastructure Investment | Simultaneous GB and ISO compliance documentation opens premium export-grade positioning for coastal logistics-enabled facilities. |
| Pharmaceutical-Grade Line Dedication | NMPA-certified maltodextrin production captures purity premium margins unavailable to food-grade-only competitors. |
| Direct Mill-to-Manufacturer Contracting | Bypassing chemical distributors concentrates procurement leverage among processors with coastal logistics infrastructure. |
Study Parameters
Bottom-up food and beverage application modeling reconciled against top-down wet-milling capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Shandong and Jilin processing facilities, procurement leads at coastal instant noodle manufacturers, distribution channel partners in chemical supply networks, and technical R&D directors at enzyme technology providers combined with secondary validation from SAMR GB standard filings, Ministry of Agriculture quality protocol documents, MEE environmental discharge records, and provincial water-use permit allocations. Top-down customs data on starch derivative trade flows and bottom-up facility capacity surveys were triangulated against end-use consumption estimates.
Historical trendline analysis of corn starch derivative production volumes, modified starch adoption rates in clean-label reformulation, and pharmaceutical-grade maltodextrin certification timelines informed the projection framework. Segmentation dimensions modeled include product type, application end-use, certification grade tier, and distribution channel structure across the analysis window. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points including GB 2760-2024 implementation timelines and MEE water-use permit scarcity patterns. Industry-specific forecast inputs incorporated maize price volatility assumptions from state grain reserve auction dynamics and enzymatic conversion yield improvement curves.
Maize price volatility, SAMR regulatory timeline shifts, and MEE water-use permit allocation decisions are the dominant revision risks to the outlook. Deviation in state grain reserve auction frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market