
 Calcium Nitrate Market | 2026-2036
Calcium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Nitrate Market Analysis
China's capacity build-out is fragmenting as provincial chemical parks add calcium nitrate lines to capture domestic fertilizer demand. Yara International ASA leverages its integrated ammonia-nitrate chain to sustain cost leadership across European and Latin American outlets. Uralchem Holding PLC anchors its position through captive feedstock access in Russia's potassium and nitrogen corridors. Haifa Chemicals Ltd differentiates via specialty-grade formulations for fertigation systems in arid climates.
Calcium nitrate is a hygroscopic inorganic salt with the formula Ca(NO3)2, typically manufactured through neutralization of nitric acid with calcium carbonate or limestone to produce crystals or solutions containing 15.5% nitrogen by weight. Its primary industrial purpose centers on agricultural fertilization, concrete set acceleration, and wastewater treatment applications where it serves as a dual-nutrient source and corrosion inhibitor. Solid and granular product types dominate volume flows into bulk fertilizer blending operations, while liquid and solution formats capture expanding share in drip irrigation and hydroponic systems where solubility and handling efficiency command premium positioning. The agriculture end-use industry remains the structural anchor, though water treatment applications are gaining faster trajectory as municipal infrastructure upgrades accelerate across water-stressed regions.
EPA guidelines on nitrogen runoff shape product formulation standards in the United States, while REACH registration requirements in Europe enforce trace-metal thresholds that filter lower-purity imports from non-compliant origins. India's FSSAI and BIS frameworks govern food-contact and agricultural-grade specifications, creating layered compliance costs for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving fertilizer subsidy regimes and carbon-border adjustment mechanisms as these instruments increasingly determine competitive access and margin sustainability.
Market Dynamics
Water treatment facilities are accelerating calcium nitrate adoption for odor control and corrosion inhibition as municipal infrastructure upgrades intensify across water-stressed regions, while REACH compliance in Europe tightens purity standards that filter lower-grade fertilizer imports.
Growth Catalysts
- Precision fertilization programs:Soybean and corn producers in Brazil's agricultural belt are scaling fertigation systems that demand soluble calcium nitrate formulations.
- EPA nitrogen runoff guidelines:The EPA's formulation standards in the United States are pushing manufacturers toward controlled-release fertilizer grades that incorporate calcium nitrate as a stabilizing component.
- Concrete set acceleration:Construction sectors in arid climates are specifying calcium nitrate admixtures to counteract delayed curing in high-temperature environments.
Market Restraints
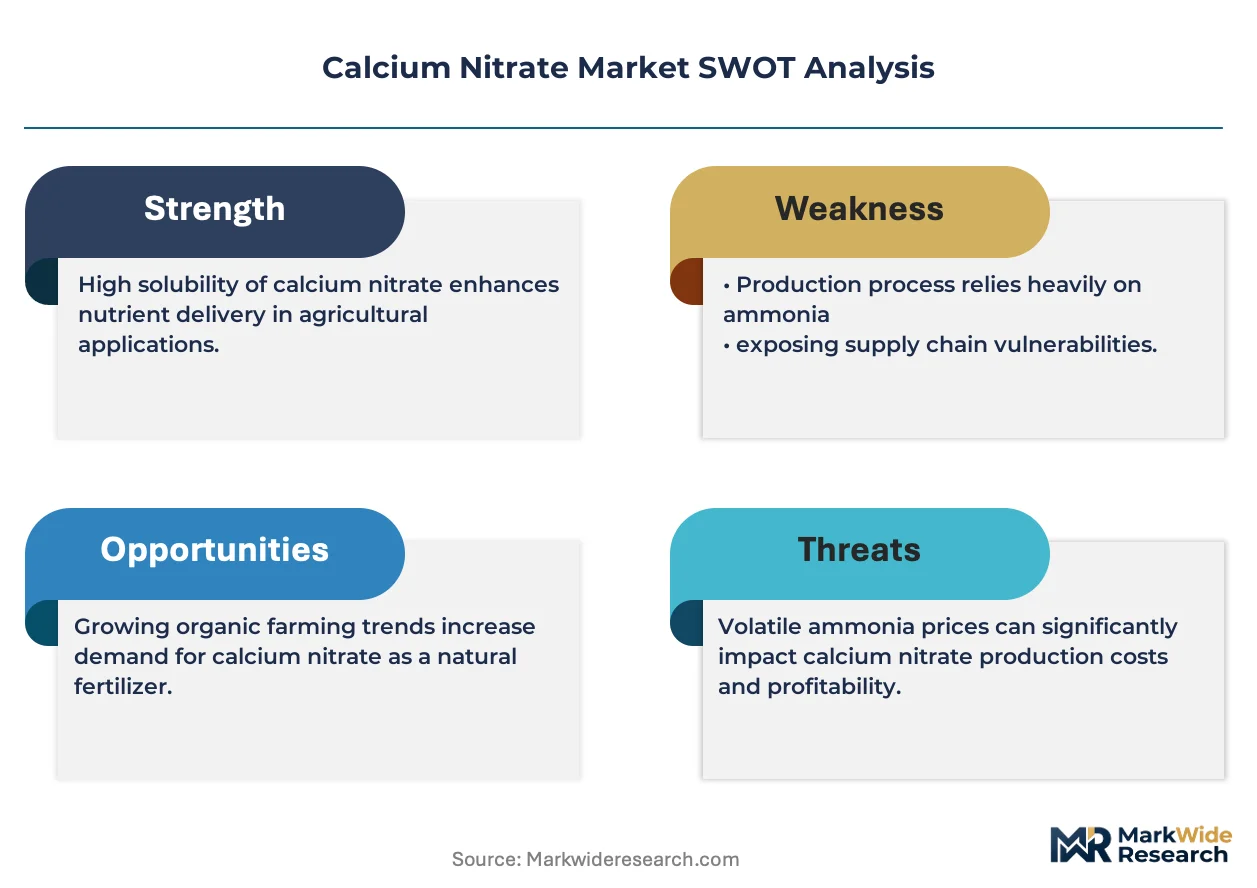
- Nitric acid price volatility:Feedstock cost swings tied to natural gas benchmarks compress margins for neutralization-based production routes.
- Russian supply concentration:Uralchem Holding PLC's captive feedstock access in Russia's nitrogen corridors creates dependency risk for European buyers seeking alternative sourcing.
- Ammonium nitrate substitution:Lower-cost nitrogen fertilizers displace calcium nitrate in bulk commodity applications where calcium value is not prioritized.
Strategic Opportunities
- Arid-climate fertigation:Specialty-grade formulations for drip irrigation systems in the Middle East command premium positioning as water scarcity intensifies.
- EU Green Deal fertilizer incentives:Carbon-border adjustment mechanisms favor low-carbon production routes for European-bound calcium nitrate shipments.
- Hydroponic cultivation convergence:Controlled-environment agriculture facilities are integrating calcium nitrate into automated nutrient dosing systems alongside pH monitoring technologies.
Industry Challenges
- REACH registration timelines:Extended trace-metal certification procedures delay market entry for new fertilizer-grade suppliers targeting European outlets.
- Hygroscopic handling infrastructure:Solid product formats require climate-controlled storage and transport systems that elevate working capital requirements for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Nitrate Market |
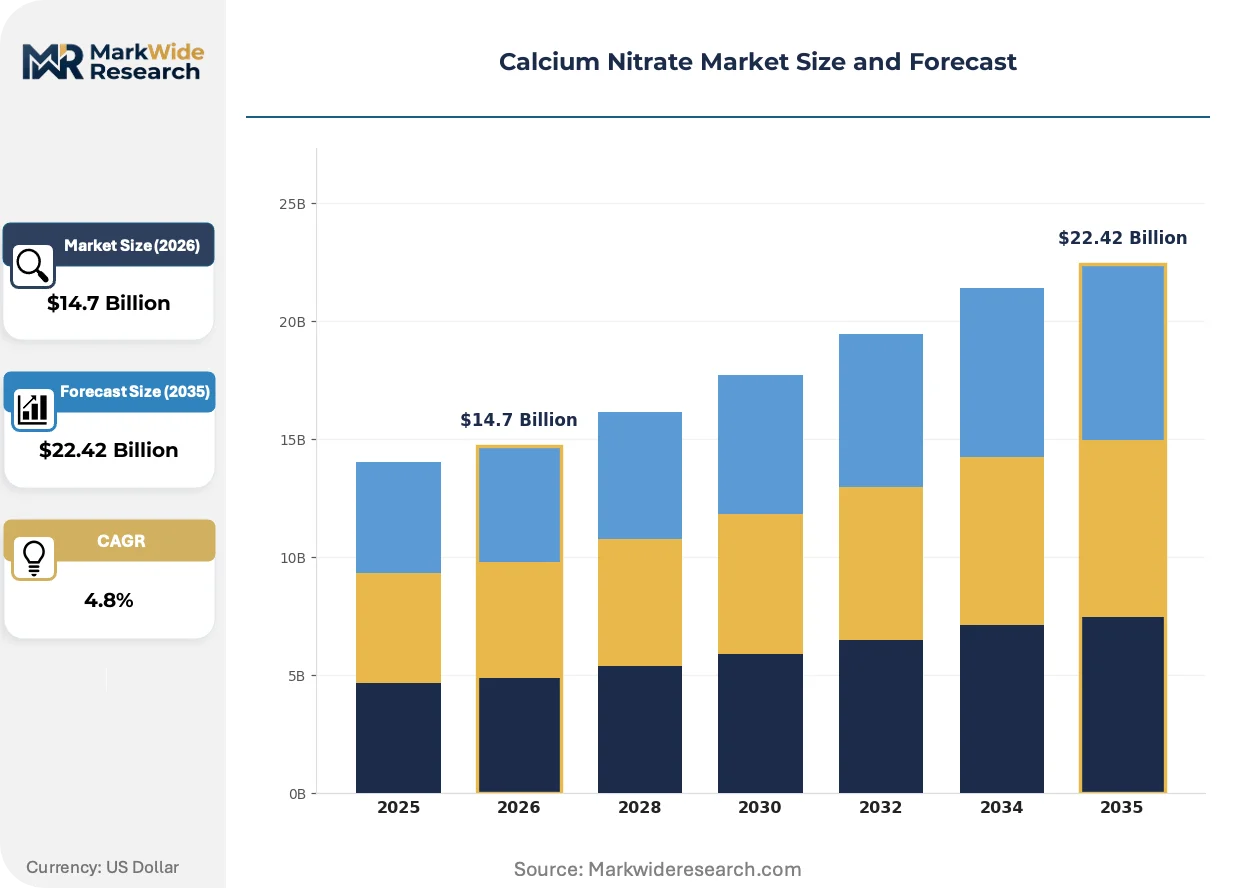
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Granular, Solution End Use Industry: Agriculture, Horticulture, Fertilizers, Water Treatment Distribution Channel: Wholesale, Retail, Online, Direct Sales Packaging Type: Bags, Drums, IBC Totes, Bulk |
| Companies Covered | Yara International ASA, Uralchem Holding PLC, Nutrien Ltd, GFS Chemicals Inc, Haifa Chemicals Ltd, Prathista Industries Limited, Rural Liquid Fertilizers (RLF), Shanxi Jiaocheng Tianlong Chemical Industry Co. Ltd., Sterling Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Nitrate Market Emerging Trajectories
Product formulation and regulatory compliance are converging to reshape competitive positioning in calcium nitrate supply chains. Manufacturers are responding to differentiated purity demands across agricultural, industrial, and water treatment segments.
Encapsulated slow-release calcium nitrate granules are collapsing the traditional trade-off between solubility speed and nutrient retention in fertigation applications. Drip irrigation operators in Spain and Israel are adopting these formulations to reduce application frequency. The technology is collapsing inventory carrying costs for distributors while extending the effective nutrient window for high-value vegetable crops.
REACH registration requirements are enforcing trace-metal thresholds that filter lower-purity imports from non-compliant origins. European fertilizer blenders are reformulating product lines to meet ECHA-mandated cadmium and nickel limits. Specialty-grade producers with integrated quality control systems are capturing displaced volume from commodity suppliers unable to certify compliance.
Buyers in the water treatment sector are consolidating procurement around long-term service contracts that bundle chemical supply with dosing equipment maintenance. Municipal utilities in California and Texas are shifting from spot purchasing to multi-year agreements with guaranteed availability clauses. This restructuring is visible most acutely in regions where EPA consent decrees mandate accelerated infrastructure upgrades.
Calcium Nitrate Market Segmentation
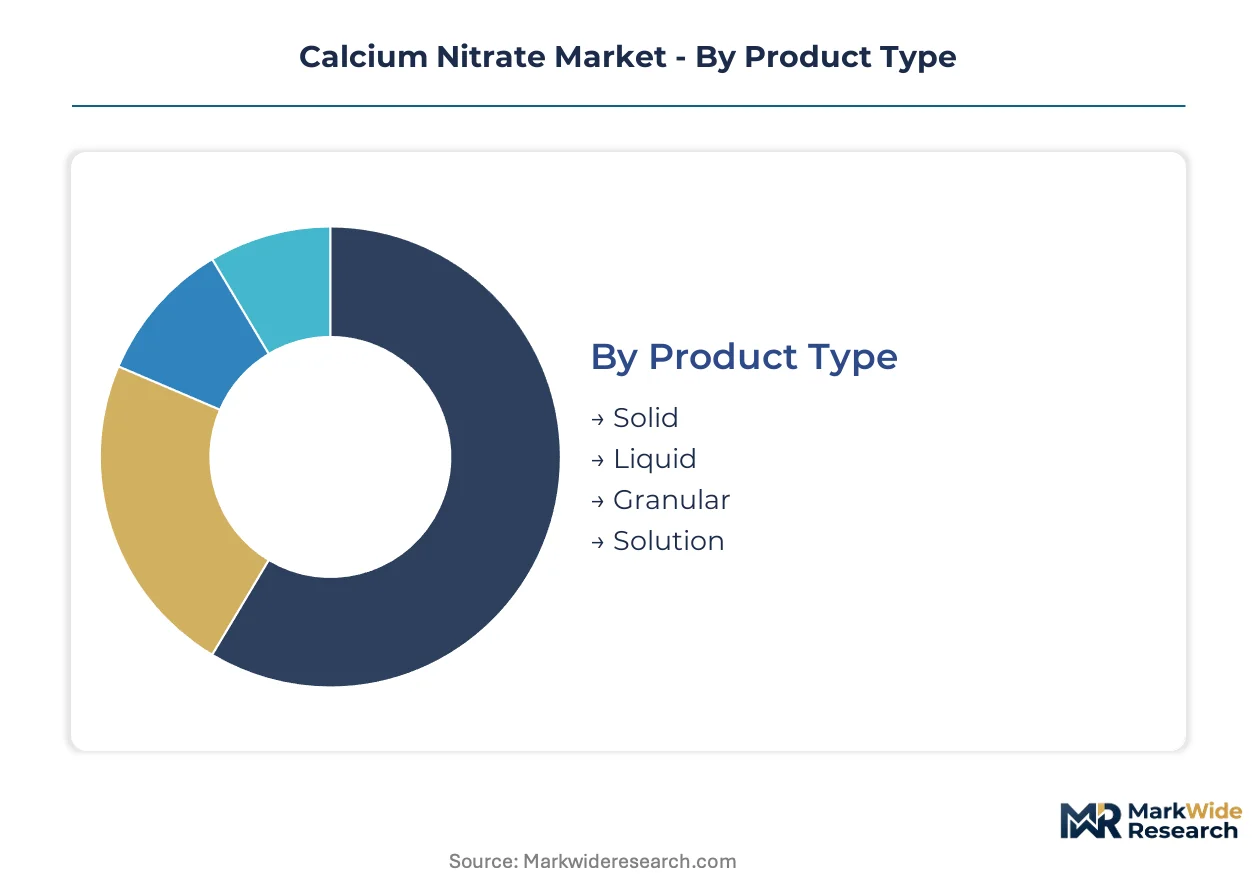
Calcium nitrate supply chains fragment across physical states, application intensities, and procurement modalities. Each segmentation axis reveals distinct margin profiles and working capital requirements that shape supplier strategy and buyer switching costs.
Product Type:
Liquid and solution formats turn inventory fastest through continuous-flow dosing systems, while solid and granular products lock capital in seasonal offtake patterns.
- Solid:Crystalline Ca(NO3)2 with 15.5% nitrogen content serves bulk fertilizer blending operations. Brazilian soybean cooperatives specify solid grades for dry-spread application during pre-planting windows, though hygroscopicity demands climate-controlled storage infrastructure.
- Liquid:Aqueous solutions at 40-50% concentration enable direct injection into fertigation lines without dissolution stages. Israeli drip irrigation operators in the Negev Desert prioritize liquid formats to eliminate field mixing labor and reduce clogging risk in emitters.
- Granular:Prilled or granular forms balance flowability with solubility for mechanized spreading equipment. The physical stability supports longer distribution channels but requires anti-caking agents that elevate formulation cost.
- Solution:Custom-concentrated preparations for industrial water treatment and concrete admixture markets. Municipal utilities in Texas specify solution strength for direct feed into odor control systems without on-site dilution.
Solid calcium nitrate dominates installed base through agricultural commodity volume. Liquid and solution formats are where expansion concentrates as precision application systems displace broadcast methods.
End Use Industry:
Cost tiers separate commodity fertilizer applications from premium-priced specialty formulations where purity certificates command measurable price premiums.
- Agriculture:Field crop fertilization consumes volume through calcium supplementation in NPK blends. Corn producers in Iowa integrate calcium nitrate to address calcium deficiency in acidic soils, with EPA nitrogen runoff guidelines pushing toward stabilized formulations.
- Horticulture:Greenhouse and nursery operations demand water-soluble grades for foliar feeding and root zone application. Dutch greenhouse tomato growers specify low-biuret calcium nitrate to prevent phytotoxicity in recirculating hydroponic systems.
- Fertilizers:Compound fertilizer manufacturing uses calcium nitrate as a calcium source in controlled-release granule production. The segment concentrates procurement around long-term supply agreements tied to seasonal production campaigns.
- Water Treatment:Odor control and corrosion inhibition in municipal wastewater and potable water systems. California utilities facing EPA consent decrees are accelerating adoption for hydrogen sulfide suppression in collection systems.
Agriculture anchors volume throughput across all geographies. Water treatment is climbing the fastest as infrastructure upgrade cycles intensify regulatory compliance spending.
Distribution Channel:
Customer type and order scale determine channel selection, with bulk commodity buyers bypassing intermediaries while fragmented horticulture operations rely on retail access.
- Wholesale:Aggregators serving regional fertilizer blenders and industrial compounders. The channel captures economies in consolidated logistics but adds margin layers that specialty-grade buyers increasingly circumvent.
- Retail:Agricultural supply stores and garden centers reaching small-scale growers. Brazil's rural retail network extends calcium nitrate access to soybean producers outside cooperative membership.
- Online:E-commerce platforms for specialty horticulture and hydroponic hobbyist segments. The channel is gaining traction among controlled-environment agriculture startups seeking rapid procurement without established supplier relationships.
- Direct Sales:Manufacturer-to-end-user contracts for water treatment utilities and large agricultural cooperatives. Municipal procurement offices in Texas are consolidating around multi-year direct agreements with guaranteed availability clauses.
Wholesale channels still move the majority of agricultural volume. Direct sales are where margin expansion concentrates as water treatment utilities professionalize procurement.
Packaging Type:
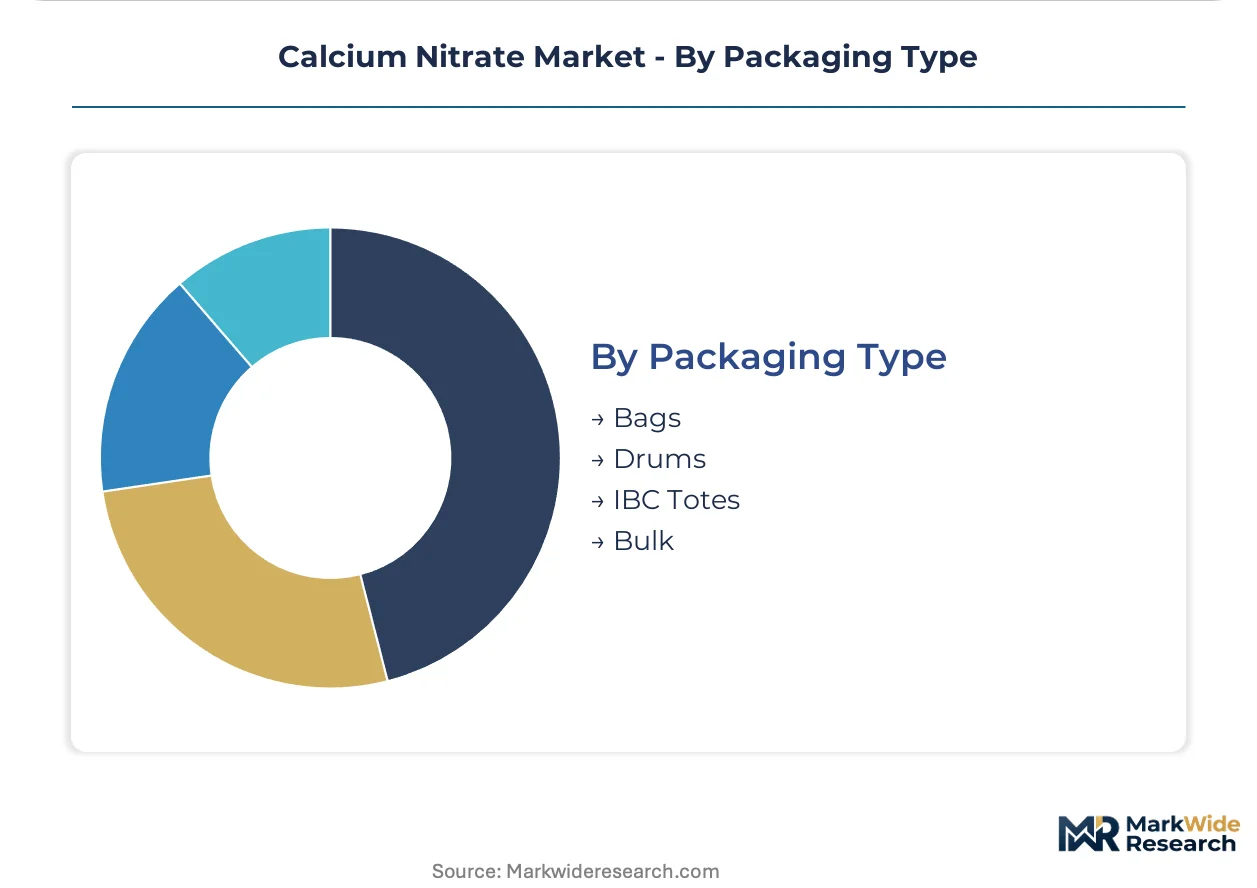
Supply concentration in bagged and bulk formats reflects agricultural dominance, while drum and IBC tote penetration tracks industrial and specialty segment growth.
- Bags:Multi-wall paper or woven polypropylene sacks at 25-50 kg for manual handling in retail and small-scale agricultural distribution. The format supports hygroscopic product protection through moisture-barrier liners.
- Drums:Steel or plastic containers for liquid and solution products in industrial maintenance and water treatment applications. EPA spill containment regulations elevate drum specification requirements for facility storage.
- IBC Totes:Intermediate bulk containers at 1000 liters for liquid product in medium-volume horticulture and industrial use. The format collapses return logistics costs for closed-loop supply arrangements.
- Bulk:Tanker truck or railcar delivery for large agricultural cooperatives and compound fertilizer manufacturers. Bulk procurement minimizes per-unit packaging cost but requires dedicated unloading infrastructure and inventory management systems.
Bulk and bag formats dominate installed base through agricultural volume concentration. IBC totes and drums are where packaging diversification concentrates as industrial and specialty segments expand procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacity concentration in Russia and China supplies feedstock leverage to nitrogen corridor operators, while European buyers navigate REACH-mandated purity thresholds and Brazilian agriculture drives soluble-grade consumption.
United States
Water treatment utilities in Texas and California are accelerating calcium nitrate procurement for hydrogen sulfide suppression under EPA consent decree timelines. The EPA's nitrogen runoff guidelines push fertilizer blenders toward stabilized formulations. Corn producers in Iowa integrate calcium nitrate into NPK blends to address calcium deficiency in acidic soils.
Brazil
Soybean and corn producers in Mato Grosso and Goiás are scaling precision fertigation systems that demand soluble calcium nitrate formulations. ANVISA governs agricultural chemical registration, creating compliance layers for imported specialty grades. The country's agricultural belt concentrates demand through cooperative procurement networks serving pre-planting application windows.
Germany
REACH registration requirements enforced by ECHA filter lower-purity fertilizer imports through trace-metal thresholds on cadmium and nickel. Fertilizer blenders in North Rhine-Westphalia are reformulating product lines to meet ECHA-mandated specifications. The country's chemical parks house integrated ammonia-nitrate production chains serving European outlets.
China
Provincial chemical parks in Shanxi and Shandong are adding calcium nitrate lines to capture domestic fertilizer demand. The Ministry of Ecology and Environment (MEE) enforces dual carbon goals that elevate compliance costs for high-emission neutralization routes. Tianlong Chemical Industry anchors regional supply through captive limestone and nitric acid integration.
Israel
Drip irrigation operators in the Negev Desert prioritize liquid calcium nitrate formats to eliminate field mixing labor and reduce emitter clogging risk. The country's national water authority regulates agricultural chemical discharge into recirculating hydroponic systems. Haifa Chemicals anchors specialty-grade production for arid-climate fertigation markets.
Calcium Nitrate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and formulation layers. The vendor base organizes around three archetypes: integrated nitrogen producers with captive ammonia access, regional compounders serving agricultural cooperatives, and specialty-grade formulators targeting precision application systems. Consolidation pressures favor backward integration into limestone and nitric acid supply, while geographic expansion into water-stressed regions captures municipal infrastructure upgrade cycles.
Among integrated nitrogen producers, Yara International ASA and Uralchem Holding PLC exemplify scale-driven positions anchored to feedstock corridors. Haifa Chemicals occupies the specialty-grade tier, representing the precision-formulation archetype for fertigation and hydroponic applications. Shanxi Jiaocheng Tianlong Chemical Industry sits within China's provincial capacity build-out, capturing domestic demand through regional chemical park integration.
| Leading Market Players |
|---|
| Yara International ASA |
| Uralchem Holding PLC |
| Nutrien Ltd |
| GFS Chemicals Inc |
| Haifa Chemicals Ltd |
| Prathista Industries Limited |
| Rural Liquid Fertilizers (RLF) |
| Shanxi Jiaocheng Tianlong Chemical Industry Co. Ltd. |
| Sterling Chemicals |
| Others |
Supply Flow & Price Mechanics
The Baltic Sea ammonia shipping corridor shapes cost dynamics for European calcium nitrate buyers, amplifying price spreads between integrated nitrogen producers and neutralization-based compounders while forcing downstream differentiation through REACH-certified specialty grades.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across the European fertilizer corridor. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant specialty grades from commodity fertilizer imports. Price differentiation hinges on cadmium certification thresholds and volume scale, with water treatment utilities showing least price sensitivity due to EPA consent decree mandates while bulk agricultural cooperatives drive hardest bargaining on per-ton nitrogen equivalent.
Supply Chain Analysis
Tariff exposure between Russia and the European Union dominates supply chain risk calculus for nitrogen corridor-dependent buyers. Production gravity centers on Russia, China, and Norway, with feedstock sourcing anchored in natural gas benchmarks and limestone deposits. Supply chain vulnerability rests on single-source dependency for ammonia feedstock, while distribution runs through bulk tanker and railcar networks serving compound fertilizer manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonium nitrate substitution pressure intensifies margin compression for commodity-grade producers, forcing incumbents to defend positioning through certification-based differentiation and captive feedstock control.
For Market Incumbents: Insulate margin structure through backward integration into nitric acid production and limestone quarrying, particularly in Shanxi and Shandong chemical parks where MEE dual carbon enforcement is tightening. Prioritize REACH pre-registration investment to capture displaced volume from non-compliant commodity suppliers facing ECHA trace-metal thresholds. For New Entrants and Emerging Players: Pursue white-space capture in arid-climate liquid fertigation systems across Israel and the Negev Desert, where emitter-clogging sensitivity commands premium positioning for low-residue formulations. Target water treatment utilities in Texas and California through direct sales contracts bundling chemical supply with dosing equipment maintenance. For Investors and Strategic Acquirers: Specialty-grade formulators with integrated quality control systems present the most defensible acquisition profile against carbon-border adjustment mechanism exposure. Long-term viability hinges on low-carbon production route certification and hydroponic cultivation convergence. Watch for EPA consent decree acceleration in water-stressed municipalities as the inflection signal for infrastructure upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive nitric acid and limestone access insulates margin from natural gas volatility in Shanxi corridors. |
| REACH Certification Investment | ECHA-compliant trace-metal thresholds filter lower-purity competitors from European fertilizer blending channels. |
| Long-term Supply Agreement | Multi-year direct contracts with Texas municipal utilities lock volume under EPA consent decree timelines. |
| Green Manufacturing Transition | Low-carbon neutralization routes capture EU Green Deal fertilizer incentives and carbon-border preference. |
| Joint Venture | Provincial chemical park partnerships in Brazil's Mato Grosso belt secure ANVISA registration and cooperative access. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the calcium nitrate value chain, including plant managers at integrated nitrogen facilities, procurement leads at Brazilian agricultural cooperatives, distribution channel partners in European fertilizer blending networks, and technical R&D directors specializing in fertigation formulations. Secondary validation drew from customs trade data, ECHA registration databases, SEC filings of listed nitrogen producers, and MEE environmental compliance disclosures. Bottom-up volume estimates triangulated against top-down nitrogen consumption benchmarks.
Calibration against historical capacity utilization rates and seasonal offtake patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include physical state (solid, liquid, granular, solution), end-use industry (agriculture, horticulture, water treatment), and distribution channel (wholesale, direct sales, retail, online). CAGRs were derived from regression analysis of nitrogen demand intensity and infrastructure investment cycles, with specific inputs for EPA consent decree spending and precision fertigation adoption curves.
Sensitivities concentrate around nitric acid feedstock volatility, REACH registration timeline extensions, and ammonium nitrate substitution elasticity in bulk commodity applications. Forecasts reflect documented assumptions on regulatory enforcement intensity and agricultural subsidy regime stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Tributyl Citrate Market