
 Global Sodium Hydrosulfite Market | 2026-2036
Global Sodium Hydrosulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Hydrosulfite Market Foresight
The EU Green Deal's chemical sustainability targets is decoupling European demand from conventional hydrosulfite grades with higher by-product loads. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of pharmaceutical-grade reducing agents. Guangdong ZhongCheng Chemicals Inc. anchors volume leadership through backward integration into sulfur derivatives across southern China. Jinhe Group dominates bulk powder exports to South Asian textile corridors.
Sodium hydrosulfite is a dithionite salt, typically supplied as an 85-90% active powder or stabilized aqueous solution, functioning as a potent oxygen scavenger and vat dye reducing agent in alkaline media. Its primary commercial purpose centers on cleaving disulfide bonds and maintaining reduced dye states during textile coloration and paper bleaching sequences. Powder formulations command the widest installed base across developing-market textile clusters, while granular grades capture premium placement in automated dosing systems at European pulp mills. Chemical reduction applications for specialty organics represent the fastest-expanding consumption pool, though absolute volumes remain below textile and paper segments.
EPA effluent guidelines for textile mills in the United States restrict sulfite discharge concentrations, compelling wastewater facilities to specify low-residual hydrosulfite grades. China's MEE enforces stricter sulfur oxide emission thresholds at chemical reduction plants, reshaping domestic production qualifications. India's BIS certification for textile processing chemicals creates compliance gates for imported material. Stakeholders must monitor evolving regional purity standards and carbon-intensity disclosures to align procurement with tightening downstream customer specifications.
Market Dynamics
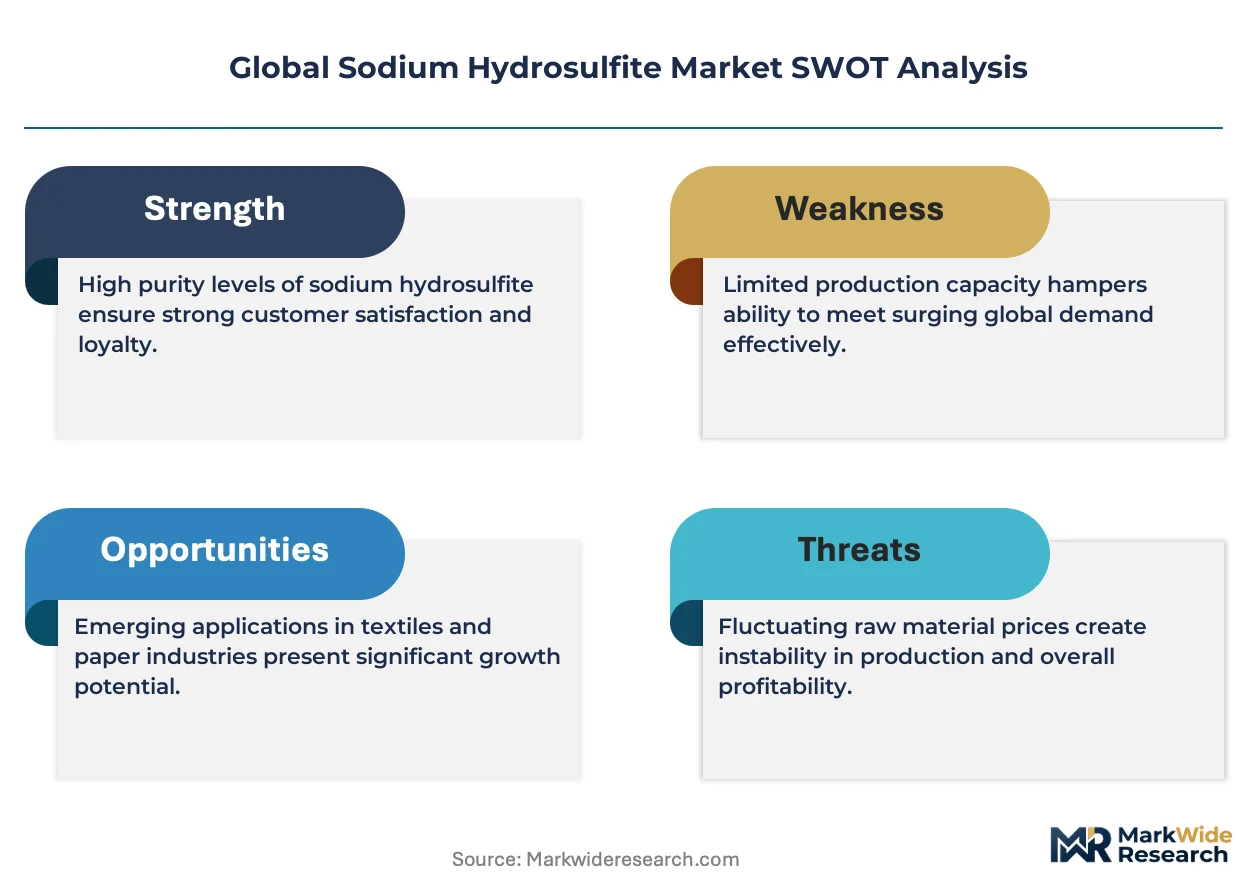
Textile wastewater discharge limits across Bangladesh, Vietnam, and China are forcing mills to specify lower-impurity hydrosulfite grades, compressing margins for conventional powder suppliers while rewarding certified producers with captive sulfur derivative integration.
Growth Catalysts
- EU REACH hazardous substance registration:European formulators face mandatory documentation requirements that favor certified low-impurity grades, pulling procurement toward qualified suppliers with verified impurity profiles.
- Vat dyeing water intensity:Bangladeshi and Vietnamese textile clusters expand hydrosulfite consumption as fast-fashion supply chains localize chemical sourcing to meet tighter discharge limits at water-intensive reduction stages.
- Specialty organics chemical reduction:Pharmaceutical and agrochemical intermediates manufacturing adopts hydrosulfite for selective disulfide bond cleavage, creating a consumption pool outside traditional textile and paper segments.
Market Restraints
- Sulfur input cost volatility:Sodium hydrosulfite production depends on elemental sulfur and sulfur dioxide pricing, exposing margin stability to energy-linked feedstock swings.
- Guangdong supply concentration:Southern China's backward integration into sulfur derivatives creates geographic supply risk, with domestic MEE emission thresholds further constraining qualified production capacity.
- Substitution by glucose-based reducers:Some European textile finishers trial enzymatic and carbohydrate reducing systems for low-temperature vat dyeing, threatening share in premium sustainability-driven contracts.
Strategic Opportunities
- India BIS certification gates:Mandatory Bureau of Indian Standards approval for imported textile processing chemicals creates first-mover advantage for suppliers completing domestic certification ahead of enforcement tightening.
- Automated dosing system penetration:European pulp mills retrofit powder handling infrastructure with granular-grade dosing equipment, opening premium placement for low-dust formulated products.
- Carbon-intensity disclosure mandates:EU CSRD supply chain reporting requirements favor hydrosulfite producers with verified low-carbon production routes, rewarding integrated Ludwigshafen-style complexes with captive energy and feedstock control.
Industry Challenges
- Cross-regional purity standard divergence:EPA effluent sulfite limits, China MEE sulfur oxide thresholds, and India BIS textile chemical specifications create fragmented compliance requirements demanding multiple product qualifications.
- Legacy powder handling infrastructure:Developing-market textile clusters retain manual dosing systems incompatible with stabilized aqueous solutions or granular grades, limiting premium product penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Hydrosulfite Market |
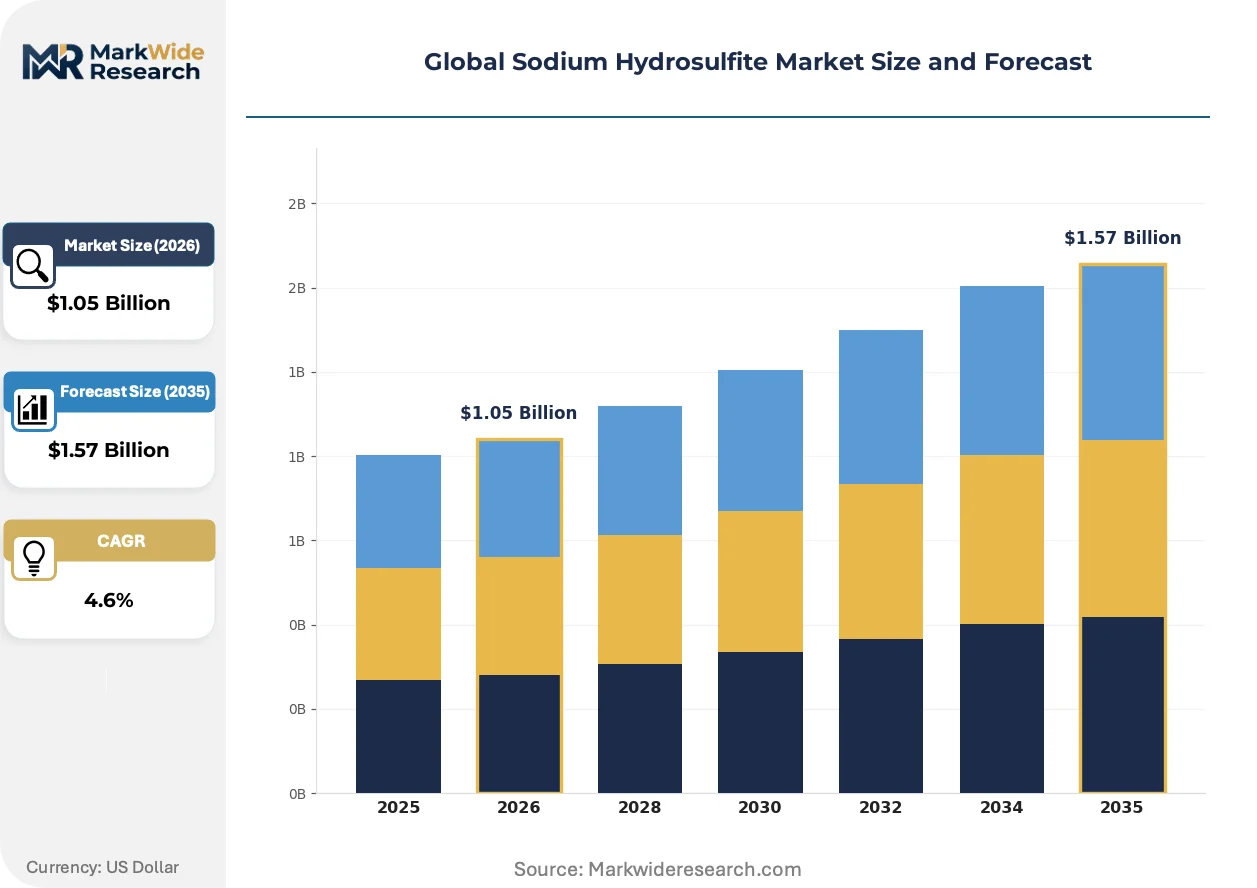
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.57 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Tablets, Flakes Application: Textile Dyeing, Paper Pulp Processing, Water Treatment, Chemical Reduction End User Industry: Textile Manufacturers, Pulp & Paper Mills, Wastewater Facilities, Chemical Producers Packaging Type: Paper Bags, Plastic Bags, Fiber Drums, Bulk Containers |
| Companies Covered | Jinhe Group, BASF SE, Guangdong ZhongCheng Chemicals Inc., AZ Chemicals, Chemtrade Logistics, Montgomery Chemicals, Royce International Corp, TCP Limited, Bruggemann Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Hydrosulfite Market Shifts & Advancements
Process automation and regulatory disclosure mandates are compressing the viable supplier base toward integrated producers with certified low-impurity output and verified carbon accounting.
Automated dosing and inline monitoring systems are automating hydrosulfite handling at European pulp mills and large-scale textile finishing plants, replacing manual powder weighing with closed-loop granular feed systems. Scandinavian paper producers lead adoption, driven by labor cost structures and OSHA-aligned workplace exposure limits. This shift is automating procurement decisions toward suppliers with ISO-certified bulk delivery logistics and real-time quality telemetry.
EU Green Deal chemical sustainability targets are decoupling European demand from conventional hydrosulfite grades carrying higher by-product loads, with ECHA registration requirements extending to full supply chain substance disclosure. Formulators now specify pharmaceutical-grade reducing agents for textile applications previously served by technical grades. German and Benelux textile chemical distributors respond by consolidating supplier panels to pre-qualified integrated producers with REACH-compliant documentation.
Buyer concentration among fast-fashion supply chain managers is compressing supplier negotiation cycles, with Bangladeshi and Vietnamese mills consolidating procurement through regional chemical distributors rather than direct import arrangements. This channel consolidation favors Guangdong and Indian producers with established local stocking partnerships. The shift is most visible in Dhaka and Ho Chi Minh City textile corridors, where annual contract structures replace spot purchasing for reduction chemicals.
Global Sodium Hydrosulfite Market Segmentation
Sodium hydrosulfite procurement splits across four distinct classification axes: physical formulation determines handling infrastructure compatibility, application defines purity and performance specifications, end-user concentration shapes regional demand geography, and packaging format reflects supply chain automation levels. Understanding these segment boundaries reveals where margin compression and premium capture opportunities concentrate.
Product Type:
Physical formulation dictates dosing system compatibility, dust exposure profiles, and storage stability requirements across textile and paper processing facilities.
- Powder:An 85-90% active dithionite salt supplied in fine particulate form, powder commands the widest installed base across manual dosing systems at Bangladeshi and Vietnamese textile mills. Legacy infrastructure in developing-market clusters locks in powder dominance despite higher dust exposure and workplace handling costs.
- Granular:Low-dust agglomerated particles engineered for pneumatic conveying and automated feed systems, granular grades capture premium placement at European pulp mills retrofitting closed-loop dosing equipment. REACH-compliant documentation and ISO-certified bulk logistics separate qualified granular suppliers from commodity powder traders.
- Tablets:Compressed solid forms enable precise unit dosing in small-batch textile finishing and specialty chemical synthesis operations where weighing accuracy trumps throughput speed.
- Flakes:Thin crystalline sheets dissolve rapidly in alkaline vat dye baths, finding niche application in artisanal textile operations and laboratory-scale reduction chemistry.
Powder leads on scale; granular leads on momentum.
Application:
End-use chemistry determines reduction potential requirements, alkaline media compatibility, and regulatory purity thresholds.
- Textile Dyeing:Vat dye reduction stages consume hydrosulfite to maintain leuco-indigo and sulfur dye states in alkaline baths, with Bangladeshi and Vietnamese mills driving procurement volume as fast-fashion supply chains localize chemical sourcing.
- Paper Pulp Processing:Oxygen scavenging and brightness reversion control in mechanical pulp bleaching sequences demand stabilized aqueous solutions or low-dust granular grades compatible with Scandinavian mill automation investments.
- Water Treatment:Dechlorination and heavy metal reduction applications in municipal and industrial wastewater facilities specify technical-grade powder for cost-sensitive large-volume treatment.
- Chemical Reduction:Pharmaceutical and agrochemical intermediate manufacturing adopts hydrosulfite for selective disulfide bond cleavage, creating the steepest expansion trajectory outside traditional commodity segments.
Textile dyeing leads on scale; chemical reduction leads on momentum.
End User Industry:
Customer concentration patterns align with regional manufacturing clusters and regulatory jurisdiction boundaries.
- Textile Manufacturers:Integrated dyeing and finishing operations across Dhaka, Ho Chi Minh City, and southern China corridors specify hydrosulfite grades matched to local discharge permit limits and BIS or MEE compliance requirements.
- Pulp & Paper Mills:Northern European producers with CSRD reporting obligations and OSHA-aligned workplace standards drive granular-grade adoption and carbon-intensity disclosure demands.
- Wastewater Facilities:Municipal and industrial treatment plants in the United States face EPA effluent sulfite restrictions that shape procurement toward low-residual grades with verified impurity profiles.
- Chemical Producers:Specialty organic synthesis and pharmaceutical intermediate manufacturers source pharmaceutical-grade reducing agents with full ECHA registration documentation.
Textile manufacturers lead on scale; chemical producers lead on momentum.
Packaging Type:
Container format reflects supply chain automation, inventory turnover velocity, and workplace safety regulatory exposure.
- Paper Bags:Multi-wall kraft constructions with moisture barriers dominate manual handling environments at South Asian textile mills where low unit cost outweighs automation compatibility.
- Plastic Bags:Polyethylene-lined woven polypropylene offers intermediate protection against humidity degradation for regional distribution networks with moderate storage duration.
- Fiber Drums:Rigid cylindrical containers enable forklift handling and intermediate bulk storage at chemical distributor warehouses serving consolidated procurement channels.
- Bulk Containers:ISO-tank and flexible intermediate bulk container (FIBC) formats support direct mill feed systems at large-scale European pulp operations with pneumatic conveying infrastructure.
Paper bags lead on scale; bulk containers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale dithionite production during the early twentieth century, establishing the technical foundation that Chinese and Indian producers later scaled across Asia. Today, regulatory divergence and manufacturing automation separate mature European demand from volume-driven Asian procurement.
China
Guangdong ZhongCheng Chemicals anchors sulfur derivative production across southern China, supplying powder grades to Bangladeshi and Vietnamese textile corridors. The MEE enforces stricter sulfur oxide emission thresholds at chemical reduction plants, reshaping domestic production qualifications and compressing qualified capacity. The Pearl River Delta cluster maintains backward integration into sulfur feedstocks despite tightening environmental compliance costs.
Germany
BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of pharmaceutical-grade reducing agents for European formulators. ECHA registration requirements under REACH extend to full supply chain substance disclosure, pulling procurement toward qualified suppliers with verified impurity profiles. The Rhine-Neckar metropolitan region concentrates automated dosing system adoption at pulp mills retrofitting closed-loop granular feed infrastructure.
United States
Montgomery Chemicals and Chemtrade Logistics serve EPA-regulated textile mills facing effluent guidelines that restrict sulfite discharge concentrations. The agency's wastewater facility specifications compel procurement toward low-residual hydrosulfite grades with verified impurity profiles. Southeastern textile finishing operations retain manual powder handling systems incompatible with stabilized aqueous solutions, limiting premium product penetration.
India
TCP Limited dominates bulk powder exports to South Asian textile corridors from production bases in western India. The BIS certification for textile processing chemicals creates compliance gates for imported material, rewarding first-movers completing domestic qualification ahead of enforcement tightening. The Gujarat industrial belt concentrates dyeing and finishing operations specifying hydrosulfite grades matched to local discharge permit limits.
Bangladesh
Dhaka-based textile dyeing mills expand procurement of hydrosulfite-based reduction agents as water-intensive vat dyeing stages face tighter discharge limits from the Department of Environment. Fast-fashion supply chain managers consolidate procurement through regional chemical distributors rather than direct import arrangements. The Narayanganj textile corridor drives annual contract structures replacing spot purchasing for reduction chemicals.
Global Sodium Hydrosulfite Market Competitive Landscape
Capital-heavy producers with integrated sulfur derivative complexes compete with asset-light traders sourcing standardized powder grades from third-party manufacturers. The supplier base stratifies across three tiers: multinational chemical conglomerates with captive energy and feedstock control, regional specialists with backward integration into sulfur inputs, and commodity traders lacking manufacturing assets. Consolidation pressures favor integrated producers capable of documenting REACH-compliant impurity profiles and verified carbon accounting. Dominant competitive moves include geographic expansion through regional distributor partnerships and portfolio diversification into pharmaceutical-grade reducing agents.
Within the multinational tier, BASF SE exemplifies integrated production architecture with pharmaceutical-grade certification. Among Chinese sulfur derivative specialists, Guangdong ZhongCheng Chemicals occupies a position representing regional volume leadership through captive feedstock control. At the export-focused commodity end, Jinhe Group anchors bulk powder supply to South Asian textile corridors. These three archetypes—integrated multinational, regional backward-integrated specialist, and volume-export commodity producer—capture the structural segmentation governing competitive positioning.
| Leading Market Players |
|---|
| Jinhe Group |
| BASF SE |
| Guangdong ZhongCheng Chemicals Inc. |
| AZ Chemicals |
| Chemtrade Logistics |
| Montgomery Chemicals |
| Royce International Corp |
| TCP Limited |
| Bruggemann Chemical |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant pharmaceutical grades and technical commodity powders manifests in divergent pricing architectures and procurement channel structures across European and South Asian markets. Price premiums for granular low-dust formulations with verified impurity profiles widen against standard powder grades as automated dosing infrastructure spreads through Scandinavian pulp operations and manual handling systems persist in Bangladeshi textile corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade reducing agents with full ECHA documentation from technical textile grades and unqualified commodity powders. Price differentiation rests on certification depth and carbon-intensity verification rather than active content alone. Cost compression in standard powder tiers intensifies as Chinese MEE emission thresholds constrain qualified production capacity and sulfur input volatility feeds through. Wastewater facilities and developing-market textile mills exhibit highest price sensitivity, while European formulators accepting premium placement for granular grades show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong's Pearl River Delta cluster, where backward integration into sulfur derivatives concentrates qualified production capacity. Geographic supply concentration spans southern China, western India, and the Rhine-Neckar metropolitan region in Germany. Raw material dependencies draw from elemental sulfur, sulfur dioxide, and caustic soda feedstocks. Supply chain risk centers on regulatory restriction as China MEE thresholds and EU REACH documentation requirements simultaneously tighten. Distribution runs through regional chemical distributors consolidating procurement for Bangladeshi and Vietnamese textile mills rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as discharge limit enforcement across Bangladesh, Vietnam, and China forces specification upgrades toward certified low-impurity grades.
For Market Incumbents: Lock in captive sulfur derivative supply through upstream control over feedstock inputs to defend margin position against sulfur price volatility. Secure BIS certification ahead of Indian enforcement tightening to gatekeep import competition. Deepen distributor partnerships in Dhaka and Ho Chi Minh City corridors where annual contract structures are displacing spot purchasing. For New Entrants and Emerging Players: EU REACH hazardous substance registration in Europe opens a window for qualified low-impurity grade suppliers with verified carbon accounting to capture share from commodity traders lacking documentation capabilities. Target automated dosing system retrofits at Scandinavian pulp mills as the most penetrable premium segment. Pursue pharmaceutical-grade qualification as the go-to-market angle commanding sustainable price premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented commodity trading operations lack manufacturing assets and regulatory documentation capabilities. Long-term viability favors integrated producers with captive energy and feedstock control across the analysis window. Acquisition target archetype: regional sulfur derivative specialists with existing BIS or REACH qualification pathways. Watch for MEE enforcement acceleration in China as the inflection indicator for qualified capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Derivatives | Captive feedstock control insulates BASF and Guangdong ZhongCheng from elemental sulfur price swings. |
| REACH-Compliant Documentation Investment | Full supply chain substance disclosure separates qualified European suppliers from commodity traders. |
| Automated Dosing System Partnerships | Granular-grade placement at Scandinavian pulp mills locks in premium pricing through infrastructure compatibility. |
| BIS Certification Completion | First-mover qualification ahead of Indian enforcement tightening gates import competition for South Asian supply. |
| Regional Distributor Consolidation | Channel control in Dhaka and Ho Chi Minh City corridors captures fast-fashion supply chain procurement centralization. |
Research Methodology
Coverage spans South Asia, Southeast Asia, China, and Europe, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Primary interviews engaged plant managers at textile dyeing mills, procurement leads at pulp and paper operations, distribution channel partners serving Bangladesh and Vietnam corridors, and technical R&D directors at sulfur derivative producers. Secondary sources included customs and trade flow data, China MEE emission disclosure filings, EU ECHA registration databases, SEC 10-K filings from listed chemical producers, and Bureau of Indian Standards certification records. Bottom-up volume modeling triangulated against top-down value estimates derived from regional pricing benchmarks.
Rate-of-change decomposition across the projection horizon segmented demand by physical formulation, application chemistry, end-user concentration, and packaging automation level. The analytical framework modeled grade tier, end-use industry, regional production hub, and carbon-intensity disclosure status as core dimensions. CAGRs were derived from segment-level growth rate aggregation weighted by baseline volume shares. Forecast inputs incorporated MEE emission threshold enforcement timelines, EU CSRD supply chain reporting phase-ins, and fast-fashion supply chain localization patterns.
Revisions become necessary when regulatory enforcement timelines accelerate, sulfur feedstock price volatility exceeds historical bands, or substitute reducing technologies achieve technical scale in European textile applications. Forecasts reflect documented assumptions on certification penetration rates and automation investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Potassium Fluoborate Market