
 Global Tetrahydrofuran Market | 2026-2036
Global Tetrahydrofuran Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tetrahydrofuran Market Foresight
Specialty chemical distribution channels between Asia-Pacific producers and European compounders is narrowing as regional self-sufficiency expands. BASF SE leverages backward integration into butanediol feedstock to secure margin control across the tetrahydrofuran value chain. INVISTA anchors North American supply through its integrated intermediates platform in Texas. Mitsubishi Chemical Group Corporation dominates pharmaceutical-grade output in Japan through stringent PMDA-aligned purity protocols.
Tetrahydrofuran is a cyclic ether with the molecular formula C4H8O, boiling point 66°C, and excellent solvent power for polar and nonpolar compounds alike. Industrial producers manufacture tetrahydrofuran primarily via acid-catalyzed dehydration of 1,4-butanediol or through maleic anhydride hydrogenation routes. Polymer-grade material commands premium positioning as spandex fiber manufacturers require ultra-low moisture and peroxide specifications. Pharmaceutical-grade tetrahydrofuran carries the tightest purity thresholds and attracts concentrated margin pools despite smaller volume throughput. Industrial-grade supply remains the volume backbone, serving coatings and resin producers across packaging materials and electronics fabrication sectors.
REACH registration requirements in Europe enforce comprehensive toxicological dossiers for tetrahydrofuran importers, elevating compliance costs for non-EU suppliers. EPA New Source Performance Standards under the Clean Air Act limit volatile organic compound emissions at U.S. production facilities, pushing capital allocation toward recovery and abatement systems. China's MEE oversees discharge permits and environmental audits at tetrahydrofuran plants along the Yangtze River chemical belt. Stakeholders must track evolving solvent restriction lists across multiple jurisdictions to anticipate reformulation mandates and qualification timelines.
Market Dynamics
Polymer-grade tetrahydrofuran specifications are tightening as spandex fiber producers enforce ultra-low moisture thresholds, forcing solvent manufacturers to retrofit distillation trains and analytical protocols across multiple production sites.
Growth Catalysts
- Spandex capacity expansion:Textile manufacturers in China and Vietnam are commissioning new fiber lines that specify polymer-grade tetrahydrofuran with peroxide content below 10 ppm, pulling high-purity solvent volumes upward.
- REACH registration completion:ECHA's full dossier requirements for tetrahydrofuran importers have stabilized European supply chains, reducing qualification uncertainty for compounders in Germany and the Netherlands.
- 1,4-butanediol process optimization:Acid-catalyzed dehydration routes are achieving higher selectivity through improved reactor design, lowering unit production costs for integrated producers.
Market Restraints
- Butanediol feedstock volatility:Crude oil-linked naphtha costs and bio-based BDO scale-up delays create margin compression for non-integrated tetrahydrofuran manufacturers.
- Yangtze River supply concentration:Environmental audits by China's MEE have idled capacity at multiple Jiangsu province plants, exposing buyers to single-region disruption risk.
- Aqueous cleaning substitution:Electronics fabricators in South Korea and Taiwan are adopting water-based flux removers for printed circuit board assembly, displacing industrial-grade tetrahydrofuran in surface preparation.
Strategic Opportunities
- Pharmaceutical-grade certification:PMDA-aligned purity protocols in Japan command 40-60% price premiums over industrial grades, attracting investment in dedicated production trains.
- Bio-based feedstock pathways:Fermentation-derived succinic acid hydrogenation to tetrahydrofuran aligns with EU Green Deal carbon intensity benchmarks for chemical intermediates.
- Direct compounder relationships:Polyurethane system houses in Italy and Poland are bypassing traditional distributors to secure contracted volumes with guaranteed specification compliance.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography expertise for peroxide and moisture specification testing is concentrated among retiring technicians in Germany and Japan, creating qualification bottlenecks.
- Recovery system capex:EPA New Source Performance Standards mandate volatile organic compound capture infrastructure that requires 18-24 month installation timelines at Texas and Louisiana production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tetrahydrofuran Market |
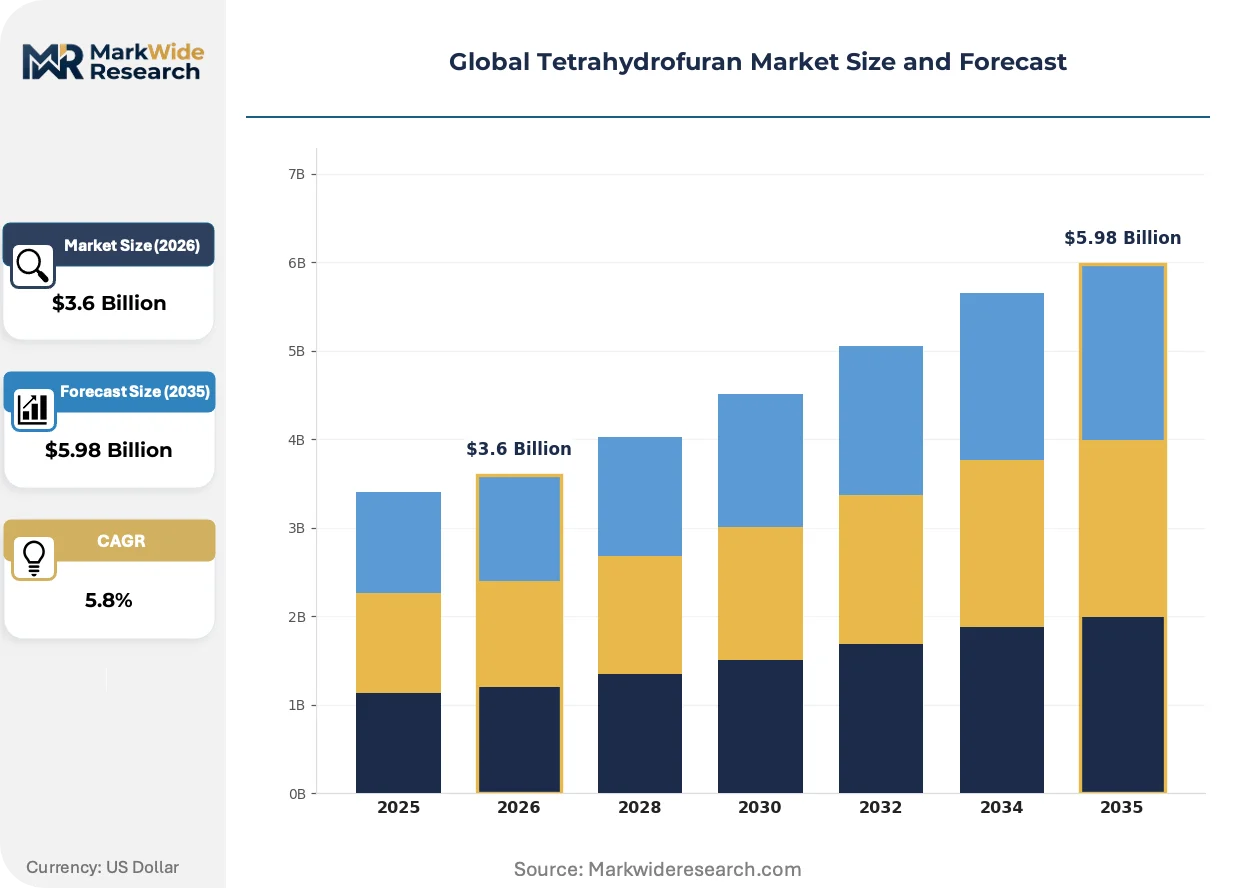
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Polymer Grade, Electronic Grade, Food Grade Application: Solvent, Chemical Intermediate, Coating Agent, Resin Production, Pharmaceutical Synthesis End Use Industry: Polymers Manufacturing, Chemicals Production, Pharmaceuticals, Electronics Fabrication, Packaging Materials Packaging Type: Drums, ISO Tanks, Bulk Containers, Fiber Drums, Intermediate Bulk Containers |
| Companies Covered | BASF SE, Dairen Chemical Corporation, INVISTA, LyondellBasell Industries Holdings B.V., Mitsubishi Chemical Group Corporation, Ashland Inc., Sipchem, Nan Ya Plastics, Penn A Kem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tetrahydrofuran Market Shifts & Advancements
Process analytical technology and closed-loop solvent recovery systems are compressing the gap between industrial-grade and polymer-grade production economics, reshaping capital allocation priorities across the tetrahydrofuran value chain.
Inline near-infrared spectroscopy is digitizing real-time moisture monitoring during tetrahydrofuran finishing operations. Spandex fiber producers in China are mandating this capability for supplier qualification. The technology is digitizing quality assurance workflows that previously required 4-6 hour laboratory turnaround times, enabling just-in-time release protocols that reduce working capital requirements.
REACH authorization list expansion is tightening downstream notification obligations for tetrahydrofuran formulators. ECHA's 2024 update moved the substance to higher tonnage band scrutiny, forcing European compounders to resubmit exposure scenarios. Pharmaceutical-grade suppliers in Switzerland and Germany are responding by segregating production lines to isolate regulatory risk from industrial-grade volumes.
Specification-driven procurement contracts are displacing spot market purchasing for polymer-grade material. Polyurethane system houses now require 12-18 month locked pricing with guaranteed purity bands. This shift concentrates purchasing power among German and Italian compounders with volume commitments above 5,000 tonnes annually, marginalizing smaller coatings producers in Eastern Europe.
Global Tetrahydrofuran Market Segmentation
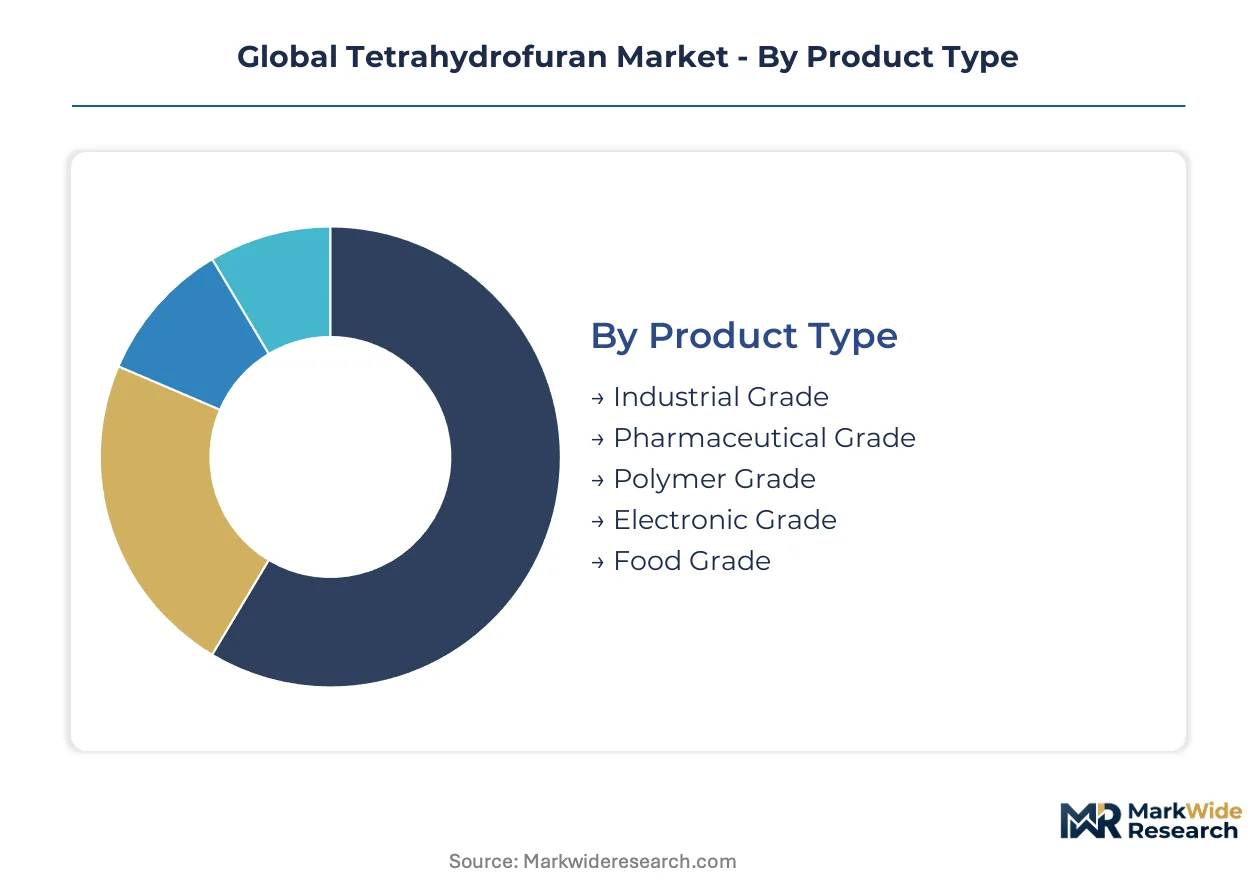
Tetrahydrofuran market segmentation reveals stark divergence in inventory velocity, with polymer-grade material turning over in days while pharmaceutical lots sit for qualification review. Specification tiers create parallel supply chains with minimal interchangeability, forcing producers to commit capital to dedicated trains.
Product Type:
Polymer-grade material cycles fastest through the supply chain as spandex fiber producers run continuous operations with just-in-time delivery contracts, while pharmaceutical-grade batches undergo extended stability testing before release.
- Industrial Grade:Standard purity specifications serve coatings and adhesive formulators across packaging materials and general chemical synthesis. Demand concentrates in China's Yangtze River chemical belt where MEE discharge permits shape production scheduling.
- Pharmaceutical Grade:Ultra-stringent purity protocols align with PMDA requirements in Japan and Swissmedic standards in Switzerland. Manufacturers in Germany and Japan command 40-60% price premiums over industrial grades due to analytical chemist scarcity and dedicated production line requirements.
- Polymer Grade:Ultra-low moisture and peroxide thresholds below 10 ppm serve spandex fiber production. Chinese and Vietnamese textile manufacturers specify this grade for new capacity commissioning.
- Electronic Grade:Particulate and ionic contamination controls meet semiconductor fabrication requirements in South Korea and Taiwan. Water-based flux remover substitution is displacing volumes in printed circuit board assembly.
- Food Grade:Extractant applications in flavor and fragrance processing require compliance with FDA indirect food additive regulations. Smallest volume tier with concentrated European demand.
Industrial grade anchors the volume base while polymer grade gains share at the steepest rate.
Application:
Cost tier stratification separates commodity solvent use from value-added chemical transformation roles, with intermediate applications commanding integrated producer advantages.
- Solvent:Dissolution and extraction applications span polar and nonpolar compound processing. REACH registration completion in Europe has stabilized qualification pathways for coatings compounders in Germany and the Netherlands.
- Chemical Intermediate:Feedstock for polytetramethylene ether glycol production serves polyurethane value chains. INVISTA's Texas platform and BASF's Ludwigshafen complex dominate this conversion pathway through backward integration into butanediol.
- Coating Agent:Solvent-borne formulations for packaging films and electronics conformal coatings. EPA New Source Performance Standards mandate recovery system investments at U.S. production facilities.
- Resin Production:Polyvinyl chloride and other polymer synthesis applications. Demand clusters in Italy and Poland where system houses contract directly with producers.
- Pharmaceutical Synthesis:Reaction medium for active pharmaceutical ingredient manufacturing. ECHA's 2024 tonnage band scrutiny forces European compounders to resubmit exposure scenarios.
Solvent applications retain the largest volume footprint while chemical intermediate usage climbs the fastest on polyurethane demand.
End Use Industry:
Customer type concentration creates divergent procurement patterns, with polymer manufacturers locking in annual contracts while electronics fabricators migrate to spot purchasing.
- Polymers Manufacturing:Spandex and polyurethane feedstock consumption drives the majority of polymer-grade demand. China's domestic chemical intermediates output expansion concentrates supply chain gravity in Jiangsu province.
- Chemicals Production:General industrial solvent and intermediate applications. Environmental audits by China's MEE have idled capacity at multiple plants, exposing buyers to single-region disruption risk.
- Pharmaceuticals:API synthesis and purification operations. PMDA-aligned purity protocols in Japan create qualification bottlenecks as gas chromatography expertise concentrates among retiring technicians.
- Electronics Fabrication:Surface preparation and cleaning applications. South Korean and Taiwanese printed circuit board assemblers are adopting aqueous cleaning substitution.
- Packaging Materials:Flexible film coatings and laminating adhesives. Italian and Polish compounders now require 12-18 month locked pricing with guaranteed purity bands.
Polymers manufacturing anchors the volume base while pharmaceuticals gains share at the steepest rate on certification premiums.
Packaging Type:
Supply concentration in bulk formats reflects the commodity chemistry economics of tetrahydrofuran, with drum packaging serving only specialty qualification volumes.
- Drums:Standard 200-liter steel containers serve small-lot industrial and pharmaceutical customers. Higher per-unit logistics costs limit this format to qualification samples and remote delivery.
- ISO Tanks:Intermodal containerization enables efficient Asia-Europe chemical distribution. Specialty chemical distribution channels are narrowing as regional self-sufficiency expands.
- Bulk Containers:Dedicated tank truck and railcar deliveries serve integrated polymer producers with continuous offtake. BASF leverages captive logistics through its butanediol-tetrahydrofuran integrated network.
- Fiber Drums:Lightweight alternative for non-hazardous industrial formulations. Limited adoption due to solvent compatibility constraints.
- Intermediate Bulk Containers:Flexible bag-in-box systems for mid-volume chemical processors. Emerging format for Italian and Polish polyurethane system houses.
Bulk containers anchors the volume base while ISO tanks gains share at the steepest rate on intermodal efficiency improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites Northwest Europe's tetrahydrofuran distribution, while the Yangtze River Delta's port infrastructure anchors Asia-Pacific supply chain gravity. These backbone assets determine where capacity investment flows and where inventory buffers accumulate.
China
Spandex fiber producers in Jiangsu province commission new polymer-grade lines specifying sub-10 ppm peroxide thresholds. China's MEE enforces discharge permits and environmental audits along the Yangtze River chemical belt. Nantong and Zhangjiagang clusters concentrate acid-catalyzed dehydration capacity serving domestic polyurethane intermediates expansion.
Germany
Ludwigshafen's integrated butanediol-tetrahydrofuran complex supplies chemical intermediate demand across European polyurethane value chains. ECHA's REACH registration requirements enforce comprehensive toxicological dossiers for importers, elevating compliance costs for non-EU suppliers. The Rhine-Main industrial corridor hosts pharmaceutical-grade production trains aligned with Swissmedic purity benchmarks.
United States
Texas Gulf Coast petrochemical infrastructure supports INVISTA's integrated intermediates platform for polytetramethylene ether glycol feedstock. EPA New Source Performance Standards under the Clean Air Act limit volatile organic compound emissions, pushing capital toward recovery and abatement systems. Houston and Lake Charles facilities face 18-24 month installation timelines for mandated capture infrastructure.
Japan
Pharmaceutical-grade output serves active pharmaceutical ingredient synthesis with PMDA-aligned purity protocols commanding 40-60% price premiums. METI oversees chemical manufacturing standards and carbon intensity benchmarks under national decarbonization roadmaps. Kanto and Kansai industrial belts concentrate gas chromatography expertise for peroxide and moisture specification testing.
South Korea
Electronics fabricators in Gyeonggi province adopt water-based flux removers for printed circuit board assembly, displacing industrial-grade tetrahydrofuran in surface preparation. MFDS regulates pharmaceutical-grade solvent purity for domestic API manufacturing. Busan-Ulsan petrochemical complexes supply coating agent volumes for semiconductor fabrication demand.
Global Tetrahydrofuran Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower specification scope. The tetrahydrofuran market structures around three archetypes: integrated petrochemical majors with captive butanediol feedstock, regional dehydration specialists serving industrial-grade demand, and pharmaceutical-grade purifiers with dedicated analytical protocols. Capacity expansion and backward integration into feedstock represent the dominant competitive vectors as margin pressure intensifies on non-integrated producers.
Among integrated petrochemical majors, BASF SE exemplifies the platform archetype through its Ludwigshafen complex spanning butanediol to polymer-grade finishing. INVISTA occupies a comparable position in North American supply through its Texas intermediates infrastructure. Mitsubishi Chemical Group Corporation represents the pharmaceutical-grade specialization tier with PMDA-aligned production protocols. These three anchors illustrate how feedstock control, geographic positioning, and specification tier concentration determine competitive viability across distinct value chain segments.
| Leading Market Players |
|---|
| BASF SE |
| Dairen Chemical Corporation |
| INVISTA |
| LyondellBasell Industries Holdings B.V. |
| Mitsubishi Chemical Group Corporation |
| Ashland Inc. |
| Sipchem |
| Nan Ya Plastics |
| Penn A Kem |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp pipeline corridor's intermodal cost dynamics compress margins for non-integrated European compounders while amplifying price differentiation between polymer-grade and industrial-grade tiers. This freight backbone's capacity constraints feed directly into supply concentration along China's Yangtze River chemical belt, where MEE discharge permits shape production scheduling and downstream pricing power.
Pricing Analysis
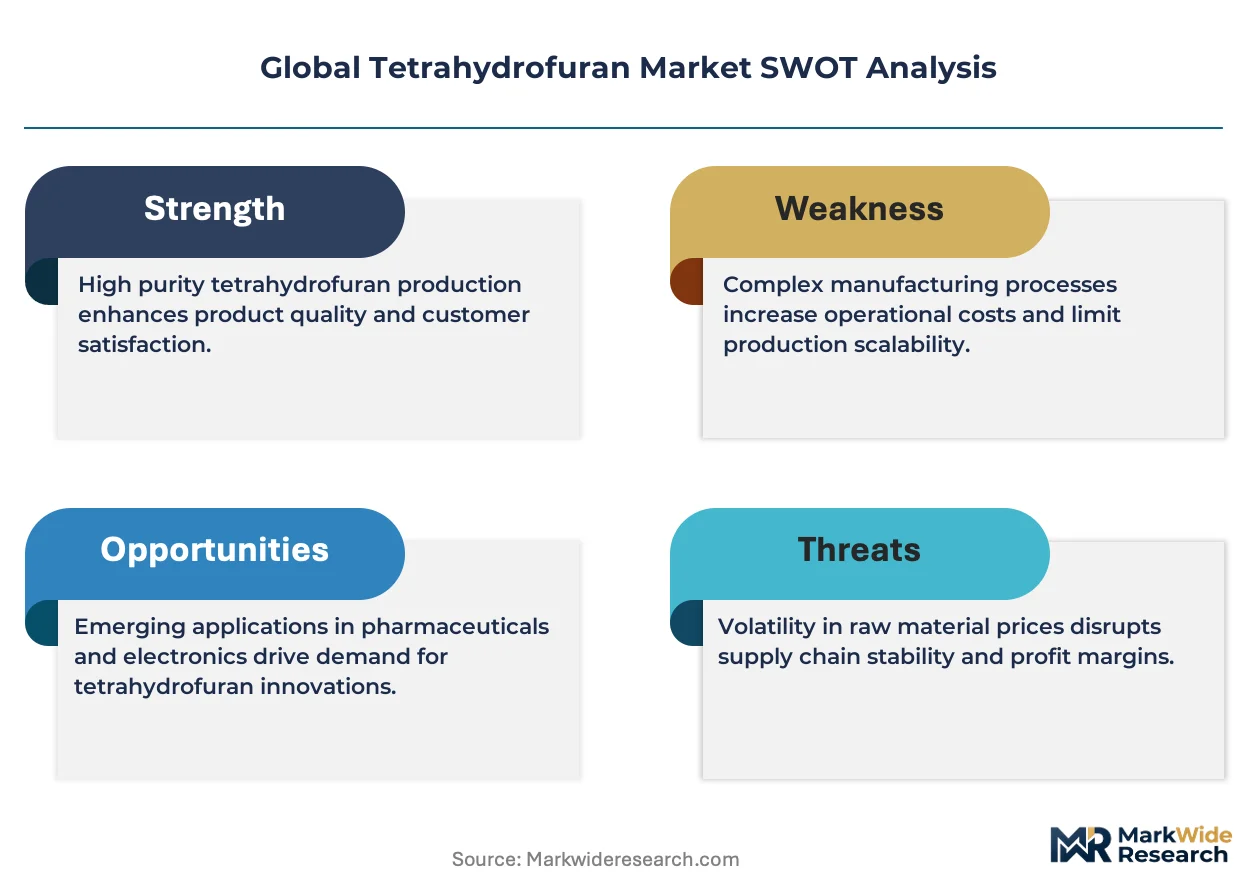
Three-tier pricing structure across premium, standard, and economy levels dominates tetrahydrofuran procurement, with pharmaceutical-grade certification and volume scale as the primary differentiation drivers. Cost compression in industrial-grade supply is intensifying because aqueous cleaning substitution displaces solvent volumes in South Korean electronics fabrication. Polyurethane system houses with annual commitments above 5,000 tonnes exhibit the lowest price sensitivity, while smaller Eastern European coatings producers face the highest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for tetrahydrofuran importers navigating REACH registration requirements. Manufacturing concentrates in China, Germany, and the United States, with feedstock 1,4-butanediol, maleic anhydride, and hydrogen as critical input dependencies. Single-region vulnerability persists as environmental audits by China's MEE idle Jiangsu province capacity without immediate replacement sources. Distribution runs through bulk container and ISO tank intermodal networks serving integrated polymer producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemist scarcity for gas chromatography-based peroxide testing creates persistent qualification bottlenecks that reshape competitive advantage toward producers with in-house technical capabilities.
For Market Incumbents: Harden analytical infrastructure through dedicated pharmaceutical-grade production trains that isolate regulatory risk from industrial-grade volumes. BASF SE's backward integration into butanediol feedstock provides the template for margin defense against bio-based BDO scale-up delays. Capacity addition in Texas and Louisiana should prioritize EPA-mandated recovery system completion ahead of competitor timelines. For New Entrants and Emerging Players: Pharmaceutical-grade certification gaps in Eastern European markets represent the most penetrable entry point, with Italian and Polish polyurethane system houses seeking direct compounder relationships outside traditional distribution channels. Bio-based feedstock pathways aligned with EU Green Deal carbon intensity benchmarks offer differentiation leverage against incumbent petrochemical majors. Target PMDA-aligned purity protocol partnerships with Japanese API manufacturers as the anchor go-to-market angle. For Investors and Strategic Acquirers: Regional dehydration specialists with captive analytical capabilities and established REACH dossier completion offer the strongest acquisition profile for portfolio positioning. Long-term viability across the analysis window hinges on feedstock integration depth rather than standalone solvent finishing capacity. The signal to watch is inline near-infrared spectroscopy adoption rates among Chinese spandex fiber producers as supplier qualification inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butanediol | BASF SE's Ludwigshafen complex demonstrates margin control through captive feedstock supply. |
| Pharmaceutical-Grade Certification Investment | PMDA-aligned protocols in Japan command 40-60% price premiums over industrial grades. |
| Long-term Supply Agreement with Textile Manufacturers | Chinese and Vietnamese spandex producers specify 12-18 month locked pricing with guaranteed purity bands. |
| Green Manufacturing Transition | Fermentation-derived succinic acid hydrogenation aligns with EU Green Deal carbon intensity benchmarks. |
| Joint Venture for Regional Production | Jiangsu province clustering reduces logistics exposure to MEE environmental audit disruptions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and Cefic chemical industry reports through structured interviews with plant managers, procurement leads at polyurethane system houses, distribution channel partners, and technical R&D directors. Bottom-up capacity modeling and top-down demand aggregation provide cross-validation for volume estimates across the analysis window.
Forecast inputs include grade tier segmentation, end-use industry demand patterns, packaging format preferences, and regional production hub capacity utilization. Modeled CAGRs derive from production cost curve analysis, feedstock price trajectory assumptions, and substitution elasticity estimates for aqueous cleaning technologies in electronics fabrication.
Macroeconomic conditions sit as an overlay; deviation in crude oil-linked naphtha costs and bio-based feedstock scale-up timelines would shift the trajectory for non-integrated producers. Forecasts reflect documented assumptions regarding REACH authorization list expansion and EPA New Source Performance Standards implementation pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Global Vanadium Pentoxide Market