
 Asia-Pacific Ammonia Market | 2026-2036
Asia-Pacific Ammonia Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ammonia Market Insights
Green hydrogen is consolidating its position as the feedstock alternative reshaping ammonia production economics across the region. Yara leverages its integrated supply chain to sustain cost leadership in low-carbon ammonia pilots. BASF SE anchors its regional presence through technology leadership in catalytic reforming processes. Indorama Corporation specializes in ammonia-to-caprolactam flows that serve Southeast Asia's textile chemical demand.
Ammonia is a colorless alkaline gas with the chemical formula NH3, produced industrially via the Haber-Bosch process using nitrogen and hydrogen under high pressure and temperature; it functions primarily as a nitrogen carrier for fertilizers and a chemical building block for explosives, plastics, and synthetic fibers. Agricultural Grade ammonia dominates volume flows due to embedded demand from urea and DAP manufacturing across India and China. Chemical Synthesis applications are expanding fastest as ammonia serves as a hydrogen vector for maritime fuel trials and power generation blending. Pipeline delivery occupies the highest margin pool where captive industrial networks reduce logistics exposure.
India's CEA and MNRE green hydrogen mandates, China's MEE dual carbon enforcement, and Australia's Safeguard Mechanism are collectively tightening emissions thresholds for ammonia producers. BIS certification requirements and China's GB standards for food-grade and industrial-grade purity are raising compliance costs for cross-border suppliers. Stakeholders must monitor hydrogen subsidy eligibility rules and carbon border adjustment timelines to position feedstock sourcing and offtake contracts.
Market Dynamics
Green hydrogen electrolysis is restructuring ammonia production economics across the Asia-Pacific region as producers pivot from natural gas reforming to renewable-powered synthesis. India's PLI scheme and China's dual carbon enforcement are accelerating capital reallocation toward low-carbon feedstocks.
Growth Catalysts
- Electrolysis cost curves:Alkaline and PEM electrolyzer capital costs are declining across Chinese manufacturing bases, enabling parity with steam methane reforming in coastal industrial zones.
- Food security mandates:Southeast Asian governments are expanding fertilizer subsidies and strategic reserve programs, embedding ammonia offtake into national agricultural policies.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment is tightening emissions intensity thresholds for chemical producers, redirecting investment toward carbon capture and green hydrogen pilots.
Market Restraints
- Natural gas price volatility:Feedstock cost swings in Australia and Malaysia are compressing margins for conventional Haber-Bosch operators without long-term LNG contracts.
- Pipeline infrastructure concentration:Captive ammonia distribution networks in eastern China and western India limit third-party supplier access to high-volume industrial buyers.
- Electrolyzer efficiency ceilings:Current alkaline cell stack energy densities impose throughput constraints that prevent direct retrofit of existing ammonia synthesis loops.
Strategic Opportunities
- Maritime fuel vector applications:Ammonia bunkering trials at Singapore and Rotterdam are creating new offtake channels for zero-carbon shipping fuels.
- India's eastern hydrogen hubs:Odisha and Tamil Nadu state governments are allocating land and grid access for electrolysis-based ammonia production serving fertilizer and chemical corridors.
- Power generation blending:Japanese utilities are testing ammonia co-firing ratios in coal plants, opening demand from METI-supported decarbonization programs.
Industry Challenges
- Electrolyzer engineering talent scarcity:Shortages of stack design specialists and membrane material scientists are extending commissioning timelines for green ammonia projects.
- BIS certification complexity:India's Bureau of Indian Standards is implementing multi-stage purity testing for industrial-grade ammonia, delaying cross-border shipments.
- Legacy reformer asset stranding:SMR plant operators face write-down risks as carbon pricing mechanisms tighten, complicating refinancing of mid-life production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ammonia Market |
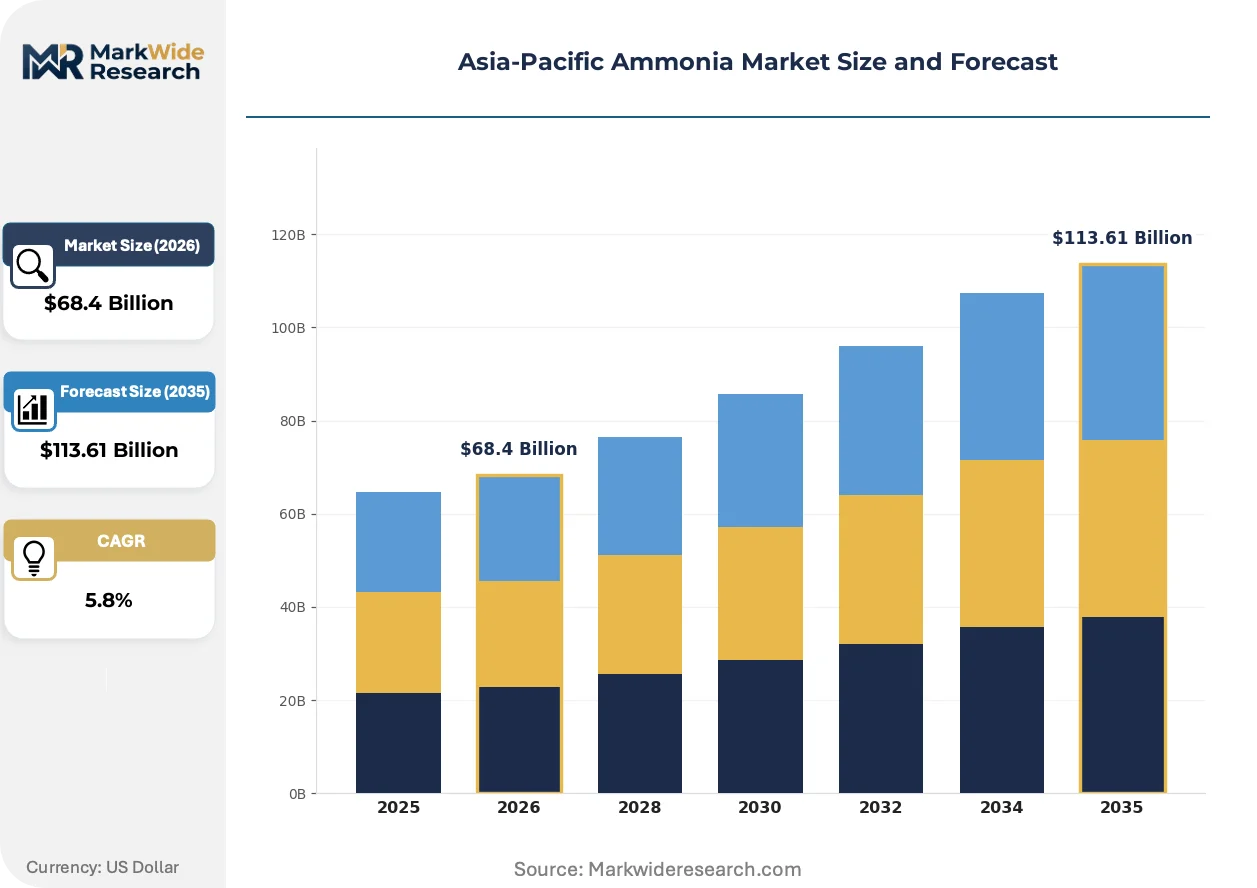
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Agricultural Grade, Food Grade, Pharmaceutical Grade Application: Chemical Synthesis, Fertilizer Production, Refrigeration, Cleaning Agents Delivery Mode: Pipeline, Truck, Rail, Ship End User: Agriculture, Chemical Manufacturing, Food Processing, Pharmaceuticals |
| Companies Covered | Rashtriya Chemicals and Fertilizers Limited, Gujarat Narmada Valley Fertilizers & Chemicals Limited, Yara, National Fertilizers Limited, IFFCO, Indorama Corporation, Chambal Fertilizers and Chemicals Limited, BASF SE, PETRONAS Chemicals Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ammonia Market Trends and Innovations
Solid oxide electrolysis is advancing toward commercial scale as producers seek higher thermal efficiency in ammonia synthesis. Regulatory carbon accounting and buyer procurement criteria are converging to reward verified low-carbon production.
Solid oxide electrolysis (SOEC) technology is consolidating its position as the high-efficiency pathway for green ammonia production. Japanese chemical conglomerates are piloting SOEC-integrated synthesis loops at demonstration scale. The technology is compressing the energy penalty gap between renewable and fossil-based ammonia, enabling cost-competitive exports from Australian solar-hydrogen hubs.
China's GB standards for industrial chemical purity are tightening cross-border compliance requirements for ammonia traders. The State Administration for Market Regulation is harmonizing food-grade and technical-grade specifications, raising testing costs for regional suppliers. Importers into China are responding by securing third-party certification from accredited laboratories in South Korea and Singapore.
Long-term offtake contracting is displacing spot market procurement among Southeast Asian fertilizer manufacturers. Thai and Vietnamese urea producers are locking in five-year supply agreements with Middle Eastern and Australian suppliers, bypassing traditional trading house intermediaries. This shift concentrates volume commitments with integrated producers possessing verified carbon intensity credentials.
Asia-Pacific Ammonia Market Segmentation
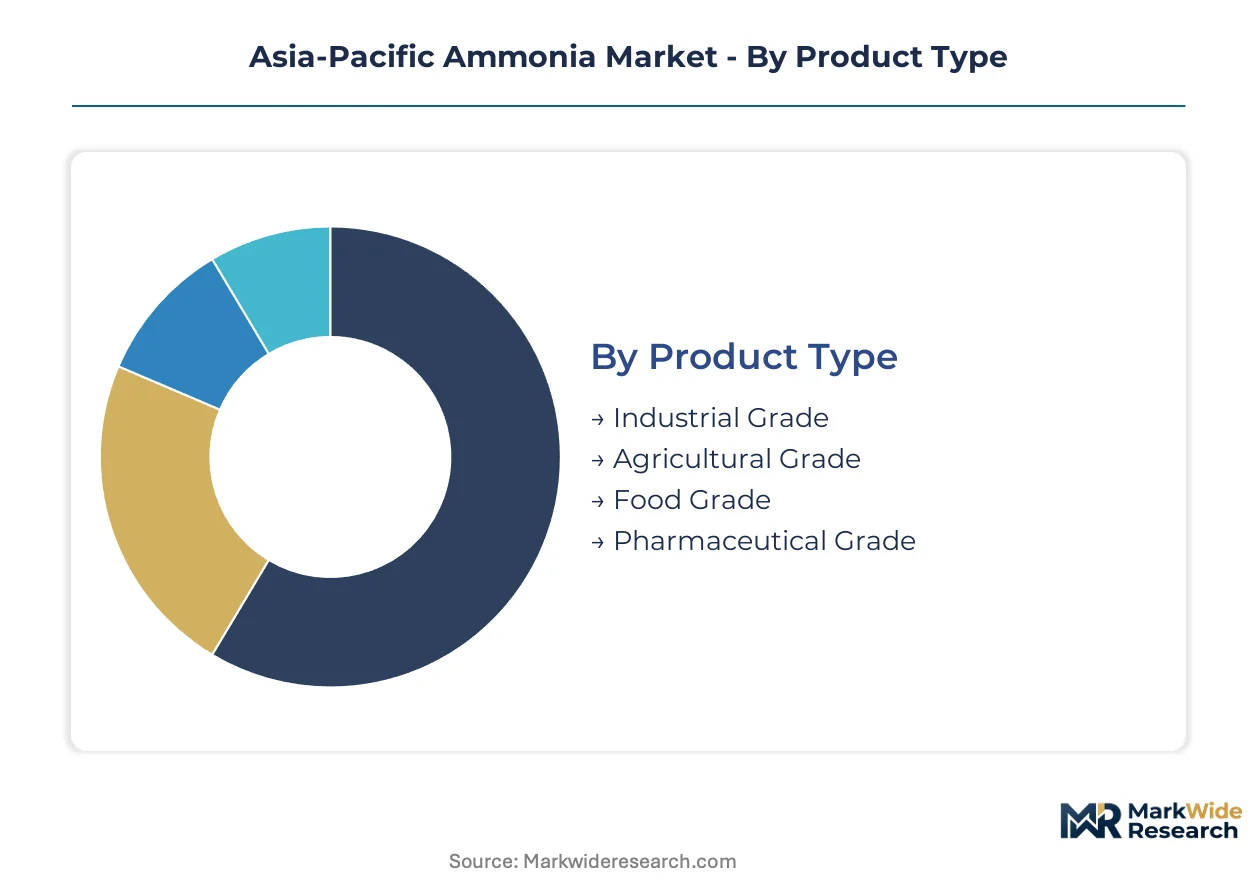
Ammonia flows through the Asia-Pacific region along distinct commercial channels shaped by purity requirements, logistics infrastructure, and end-use specifications. Each segmentation dimension reveals where margin pools concentrate and how procurement patterns diverge across industrial buyers.
Product Type:
Agricultural Grade dominates tonnage flows while Pharmaceutical Grade commands the steepest price premiums per kilogram.
- Agricultural Grade:Contains 99.5% minimum NH3 purity with controlled water content below 0.5% to prevent equipment corrosion in fertilizer plants. Demand concentrates in eastern India's urea manufacturing corridor and Shandong Province's compound fertilizer belt, driven by government subsidy programs embedding ammonia offtake into national food security frameworks.
- Industrial Grade:Technical specification NH3 at 99.0% purity with tolerance for trace contaminants acceptable in chemical synthesis loops. Procurement clusters in Jiangsu and Zhejiang chemical parks serving caprolactam and acrylonitrile producers, constrained by MEE emissions intensity thresholds that favor suppliers with verified carbon accounting.
- Food Grade:Meets GB 29201-2020 standards for residual contaminants with maximum 3 ppm heavy metal content. Applications span cold storage facilities in Thailand's seafood processing zones and Vietnam's poultry refrigeration networks.
- Pharmaceutical Grade:USP-NF compliant with 99.9% purity and sub-ppm impurity profiles for API synthesis. Manufacturing concentrates at dedicated facilities in Maharashtra and Telangana serving India's generic drug export industry.
Mature deployment sits with Agricultural Grade across subsidized fertilizer corridors. Newer deployment is concentrated in Pharmaceutical Grade as CDSCO certification requirements tighten for export-oriented API manufacturers.
Application:
Chemical Synthesis applications are climbing the fastest as ammonia gains traction as a hydrogen carrier, while Fertilizer Production retains absolute volume leadership.
- Fertilizer Production:Urea and DAP manufacturing absorb the majority of regional ammonia offtake, with integrated plants in Indonesia's Bontang complex and Malaysia's Gurun facility operating at nameplate capacity. India's CEA mandates for domestic fertilizer self-sufficiency are locking in long-term supply contracts with Middle Eastern producers.
- Chemical Synthesis:Caprolactam, acrylonitrile, and nitric acid production drive demand from petrochemical clusters in Singapore's Jurong Island and South Korea's Yeosu complex. METI-supported ammonia co-firing trials in Japan are opening parallel demand channels for power generation blending.
- Refrigeration:Industrial cold chain applications in Australia's meat processing sector and New Zealand's dairy export infrastructure specify anhydrous ammonia for its thermodynamic efficiency and zero ozone depletion potential.
- Cleaning Agents:Household and industrial formulations leverage ammonia's alkaline properties for degreasing and surface treatment, with manufacturing concentrated in Thailand's surfactant production hubs.
Volume leadership remains with Fertilizer Production across government-procured supply chains. Steepest expansion trajectory belongs to Chemical Synthesis as maritime fuel vector applications mature at Singapore bunkering terminals.
Delivery Mode:
Pipeline networks capture the highest margin pool through captive supply relationships, while maritime delivery enables cross-border arbitrage.
- Pipeline:Dedicated industrial networks in eastern China's chemical manufacturing corridor and western India's fertilizer belt eliminate logistics exposure for high-volume consumers. Third-party access restrictions limit supplier competition in these corridors.
- Ship:LNG carrier-compatible ammonia tankers enable Middle Eastern and Australian exports to Southeast Asian urea producers, with discharge terminals at Map Ta Phut and Cai Lan supporting Thai and Vietnamese fertilizer manufacturing.
- Truck:Pressurized tanker delivery serves dispersed agricultural cooperatives and small-scale chemical processors across India's hinterland states where pipeline infrastructure remains underdeveloped.
- Rail:Bulk railcar shipments connect Australian production facilities at Karratha and Gladstone to eastern port terminals, with Queensland Rail operating dedicated ammonia service corridors.
Established infrastructure sits with Pipeline delivery across China's state-owned chemical park networks. Emerging deployment concentrates in Ship delivery as Australian solar-hydrogen ammonia projects seek Asian offtake markets.
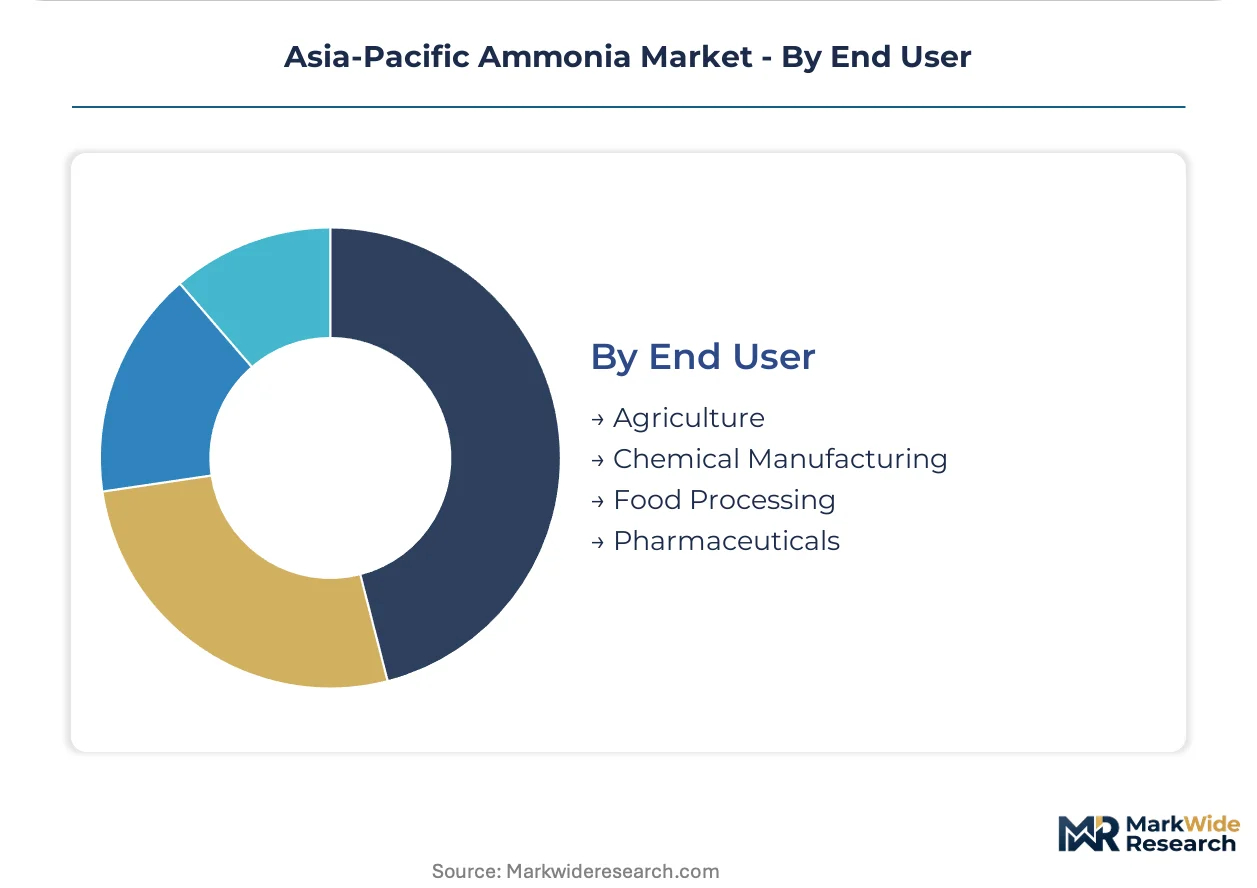
End User:
Agriculture anchors procurement volume while Chemical Manufacturing exhibits the most sophisticated supplier qualification requirements.
- Agriculture:Urea and compound fertilizer manufacturers in Indonesia, Vietnam, and the Philippines operate under government-mandated procurement programs with price stabilization mechanisms. BIS certification requirements for imported ammonia are extending supplier qualification timelines.
- Chemical Manufacturing:Caprolactam producers in Thailand and acrylonitrile manufacturers in South Korea specify tight purity windows and carbon intensity documentation. SAMR's GB standards harmonization is raising compliance costs for cross-border suppliers.
- Food Processing:Cold storage operators and beverage carbonation facilities in Malaysia and Singapore require food-grade certification with third-party laboratory verification from accredited facilities.
- Pharmaceuticals:API synthesis operations in Hyderabad and Mumbai demand pharmaceutical-grade ammonia with complete batch traceability and USP-compliant documentation for export registration.
Procurement maturity sits with Agriculture across state-supported fertilizer distribution networks. Sophistication growth concentrates in Chemical Manufacturing as carbon border adjustment mechanisms reshape supplier selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in eastern China's chemical manufacturing corridor and India's urea-producing heartland, where ammonia serves as feedstock for fertilizer and caprolactam synthesis. Southeast Asian governments are embedding strategic ammonia offtake into food security frameworks. Australia's emerging solar-hydrogen hubs are positioning for export-oriented green ammonia production.
China
Caprolactam and urea manufacturing drive ammonia consumption across Jiangsu and Shandong chemical parks. MEE dual carbon enforcement is tightening emissions intensity thresholds for Haber-Bosch operators. The Yangtze River Delta hosts integrated ammonia-to-nitric acid facilities serving regional explosives and fertilizer demand.
India
Urea self-sufficiency mandates and DAP manufacturing anchor ammonia procurement across Uttar Pradesh and Gujarat fertilizer corridors. CEA and MNRE green hydrogen directives are redirecting capital toward electrolysis-based production in Odisha. IFFCO and National Fertilizers Limited operate nameplate capacity plants at Paradeep and Nangal under government-procured supply contracts.
Japan
METI-supported ammonia co-firing trials in coal power plants are opening demand channels for zero-carbon fuel vectors. JIS standards harmonization is raising purity specifications for industrial-grade imports. Chubu and Kansai industrial zones host demonstration-scale SOEC-integrated synthesis loops testing high-efficiency production pathways.
Australia
Solar-hydrogen ammonia projects at Karratha and Gladstone are targeting Asian offtake markets with renewable-powered electrolysis. The Safeguard Mechanism is tightening baseline emissions thresholds for existing LNG-linked production. Queensland Rail operates dedicated ammonia service corridors connecting Pilbara production to eastern port terminals.
Vietnam
Urea manufacturing at Cai Lan and Haiphong chemical zones absorbs maritime ammonia imports from Middle Eastern suppliers. Government fertilizer subsidy programs are locking in long-term procurement contracts with Australian and Qatari producers. The Red River Delta hosts expanding compound fertilizer capacity serving Mekong Delta rice cultivation demand.
Asia-Pacific Ammonia Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit existing Haber-Bosch facilities and commission greenfield electrolysis-based plants. The vendor base clusters around three strategic archetypes: integrated fertilizer conglomerates with captive ammonia synthesis, petrochemical majors leveraging technology licensing, and emerging renewable-hydrogen specialists targeting maritime fuel offtake. Geographic expansion and strategic partnerships represent the primary competitive vectors, with Australian solar-hydrogen developers seeking Asian supply contracts and Indian state-owned enterprises securing Middle Eastern offtake agreements.
Within the integrated fertilizer tier, Rashtriya Chemicals and Fertilizers Limited and Gujarat Narmada Valley Fertilizers & Chemicals Limited exemplify state-backed producers with captive ammonia-to-urea infrastructure. Yara occupies a position bridging European technology transfer with Asia-Pacific operational scale. BASF SE anchors the chemical synthesis segment through catalytic process licensing. Indorama Corporation represents the petrochemical integration archetype, converting ammonia flows into caprolactam for Southeast Asian textile chemical demand.
| Leading Market Players |
|---|
| Rashtriya Chemicals and Fertilizers Limited |
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Yara |
| National Fertilizers Limited |
| IFFCO |
| Indorama Corporation |
| Chambal Fertilizers and Chemicals Limited |
| BASF SE |
| PETRONAS Chemicals Group |
| Others |
Pricing and Supply Chain Analysis
Government-procured fertilizer buyers across India and Southeast Asia anchor contract structures around long-term offtake agreements with price stabilization mechanisms, compressing spot market liquidity and embedding volume discounts into national subsidy frameworks.
Pricing Analysis
Volume leadership in Agricultural Grade ammonia runs through government-negotiated contracts with Middle Eastern suppliers, while Pharmaceutical Grade captures margin premiums through USP-compliant certification tiers. Price differentiation hinges on carbon intensity documentation and BIS purity certification. Pricing pressure stems from electrolyzer capital costs delaying green ammonia cost parity. State-backed urea manufacturers exhibit lowest price sensitivity; specialty chemical producers in Singapore's Jurong Island show highest.
Supply Chain Analysis
Regional distribution centers at Singapore and Rotterdam function as ammonia bunkering hubs, with hub-and-spoke patterns radiating to Thai and Vietnamese discharge terminals. Manufacturing concentrates in China, India, and Australia. Feedstock draws from natural gas basins in Malaysia and Qatar, plus renewable hydrogen from Australian solar corridors. Single-source vulnerability runs through Middle Eastern LNG-linked production exposed to feedstock volatility. Distribution runs through maritime tanker networks with pipeline captivity in eastern China's chemical parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where electrolyzer stack manufacturing and renewable power offtake agreements determine who captures green ammonia margin pools.
For Market Incumbents: Anticipate stranded asset risk in steam methane reforming facilities as China's MEE dual carbon enforcement tightens emissions baselines. Secure backward integration into renewable hydrogen supply through power purchase agreements with Australian solar developers. Lock in five-year offtake contracts with Southeast Asian fertilizer distributors before greenfield electrolysis projects reach commissioning. For New Entrants and Emerging Players: India's PLI scheme for green hydrogen and ammonia opens a window for electrolysis-based production serving Odisha's fertilizer corridor. Target maritime fuel vector applications at Singapore bunkering terminals where METI-supported co-firing trials are creating first-mover demand. Pursue tolling arrangements with stranded SMR operators seeking carbon intensity reduction without capital replacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale electrolyzer developers in Tamil Nadu with secured land and grid access but incomplete financing. Long-term viability hinges on hydrogen subsidy eligibility rules and carbon border adjustment implementation timelines. Watch for BIS certification delays as an inflection signal for import-dependent supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | SOEC-integrated synthesis loops at Japanese demonstration plants compress energy penalties for renewable ammonia. |
| Backward Integration | Yara's captive hydrogen supply from Norwegian electrolyzers insulates margin exposure to European gas volatility. |
| Long-term Supply Agreement | Thai urea producers locking in Australian solar-ammonia contracts bypass trading house intermediaries. |
| Joint Venture | Indorama's ammonia-to-caprolactam partnerships in Southeast Asia secure feedstock for textile chemical demand. |
| Capacity Expansion | IFFCO's Paradeep facility expansion serves India's CEA mandates for domestic fertilizer self-sufficiency. |
Research Methodology
Independent corroboration across plant managers at Haber-Bosch facilities, procurement leads at Southeast Asian urea manufacturers, electrolyzer engineering specialists, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC filings by listed fertilizer conglomerates, MEE emissions disclosure databases, and IEA hydrogen project tracking. Bottom-up capacity modeling and top-down demand aggregation triangulate volume estimates.
Comparable-period anchoring to historical production and trade flow data across the analysis window informs the projection framework. Segmentation dimensions span product grade tier, end-use application, delivery mode infrastructure, and regional production hub clustering. CAGRs derive from electrolyzer cost curve trajectories, fertilizer subsidy program trajectories, and maritime fuel vector adoption curves. Industry-specific inputs include MEE dual carbon enforcement timelines and PLI scheme disbursement schedules.
Caveats apply where hydrogen subsidy eligibility revisions or carbon border adjustment implementation delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Global Sodium Hydrosulfite Market