
 Rubber Seal Plugs Market | 2026-2036
Rubber Seal Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Seal Plugs Market Intelligence
Automotive electrification is hardening demand for high-performance sealing solutions as battery thermal management systems require specialized plugs. Parker Hannifin Corporation leverages its fluid power expertise to dominate aerospace and industrial channels. Trelleborg AB anchors its position through advanced polymer compounding capabilities across European automotive OEMs. Freudenberg Sealing Technologies sustains technology leadership in extreme-temperature applications through intensive materials R&D.
Rubber seal plugs are elastomeric closure devices engineered to specific durometer ratings, typically between 40 and 80 Shore A, manufactured through compression or injection molding to create pressure-tight barriers in fluid systems, electrical housings, and mechanical assemblies. Their primary purpose is preventing contamination ingress, retaining lubricants, and maintaining pressure differentials across operating environments from -60°C to 300°C. Custom plugs command premium positioning due to low-volume, high-specification requirements in aerospace and medical device channels, while standard plugs compete on scale economies in automotive and consumer goods. EPDM grades lead volume demand for outdoor and coolant applications, whereas silicone captures margin pools in thermal-cycling-intensive segments such as electric vehicle battery packs and industrial ovens.
EPA regulations on volatile organic compound emissions from rubber processing shape manufacturing location decisions and compounding formulations in the United States. REACH restrictions on phthalate plasticizers and heavy metal accelerators in Europe force reformulation investments across imported and domestic supply chains. China's SAMR enforces GB standards for automotive component durability that directly specify seal performance under thermal shock testing. Stakeholders must monitor evolving battery safety codes in multiple jurisdictions, as thermal runaway containment standards will determine next-generation material specifications and certification requirements for suppliers serving electrified transport platforms.
Market Dynamics
Automotive electrification is restructuring material specifications across the rubber seal plugs value chain, with battery thermal management systems now commanding durometer tolerances and thermal cycling performance that legacy coolant applications never required.
Growth Catalysts
- REACH RoHS compliance mandates:European material restrictions on phthalate plasticizers and heavy metal accelerators are forcing specification upgrades across imported supply chains, creating pull for certified EPDM and silicone grades.
- Electric vehicle battery pack sealing:Thermal runaway containment standards are hardening demand for high-durometer silicone plugs rated above 200°C continuous operation in Germany, China, and US Midwest manufacturing clusters.
- Fluid power system modernization:Industrial hydraulic equipment refurbishment cycles are accelerating replacement demand for compression-molded NBR and FKM seal plugs in process industries.
Market Restraints
- Petrochemical feedstock volatility:EPDM and silicone polymer prices track ethylene and siloxane monomer markets, compressing compounder margins during upstream price spikes.
- Carbon black supply concentration:Reinforcing filler production clusters in China and Russia create geographic single-point-of-failure exposure for global compounders.
- Fluorocarbon substitution pressure:Perfluoroelastomer grades face displacement risk from advanced thermoplastic vulcanizates in cost-sensitive industrial applications.
Strategic Opportunities
- India automotive supplier corridor:PLI scheme incentives for electric vehicle component localization are opening specification windows for domestic seal plug manufacturers serving Maruti Suzuki and Tata Motors.
- Additive manufacturing convergence:3D-printed mold tooling is compressing prototype-to-production timelines for custom aerospace and medical device plugs below 1,000 unit volumes.
- China GB standard harmonization:SAMR automotive durability testing protocols are aligning with UN ECE regulations, enabling single-SKU certification across domestic and export markets.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing Shore A precision with thermal aging resistance command premium compensation in Germany and US industrial hubs.
- Multi-jurisdiction certification timelines:Parallel EPA VOC emissions testing, ECHA REACH dossier preparation, and China GB durability validation extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Seal Plugs Market |
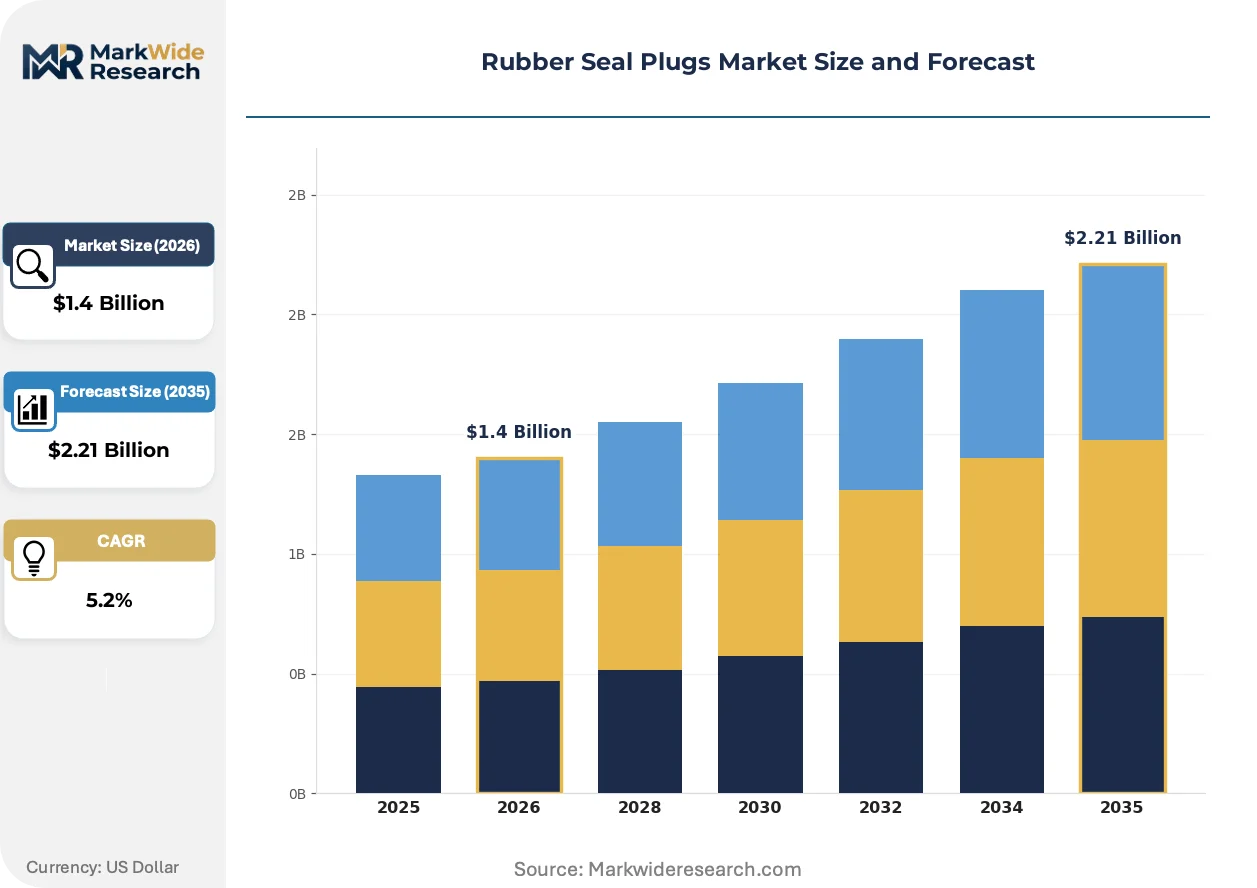
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plugs, Custom Plugs, High-Temperature Plugs, Low-Temperature Plugs Application: Automotive Manufacturing, Aerospace Applications, Industrial Machinery, Consumer Goods Material Grade: EPDM, Silicone, Neoprene, Nitrile End User: OEMs, Aftermarket Suppliers, Service Providers, Retailers |
| Companies Covered | Parker Hannifin Corporation, Trelleborg AB, Freudenberg Sealing Technologies, Hutchinson SA, SKF Group, Sinclair and Rush, MOCAP, Saint-Gobain Performance Plastics, NOK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Seal Plugs Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization are compressing the gap between custom specification development and scaled production, reshaping how compounders allocate R&D capital across thermal cycling, chemical resistance, and processability trade-offs.
Self-healing silicone formulations is converging with electric vehicle battery pack architectures to enable autonomous sealing recovery after thermal shock events. BMW and CATL procurement teams are qualifying these grades for 15-year service life warranties. This convergence is compressing the traditional replacement cycle assumption in automotive sealing specifications.
EPA volatile organic compound emission rules for rubber processing are forcing compounding facility relocations and emission control capital deployment. Compounders serving US automotive OEMs are consolidating mixing operations in states with streamlined air quality permitting. Small-batch custom compounders in Ohio and Michigan are most affected, with several pursuing toll manufacturing arrangements to avoid direct compliance liability.
Buyer consolidation among tier-one automotive suppliers is shifting procurement toward direct compounder relationships, bypassing traditional distribution channels. Continental and Bosch sealing divisions now specify raw polymer grades and durometer ranges directly with Trelleborg and Freudenberg. This disintermediation is most visible in Germany's automotive supplier corridor, where distributor margins have compressed by half in specialized thermal management applications.
Rubber Seal Plugs Market Segmentation
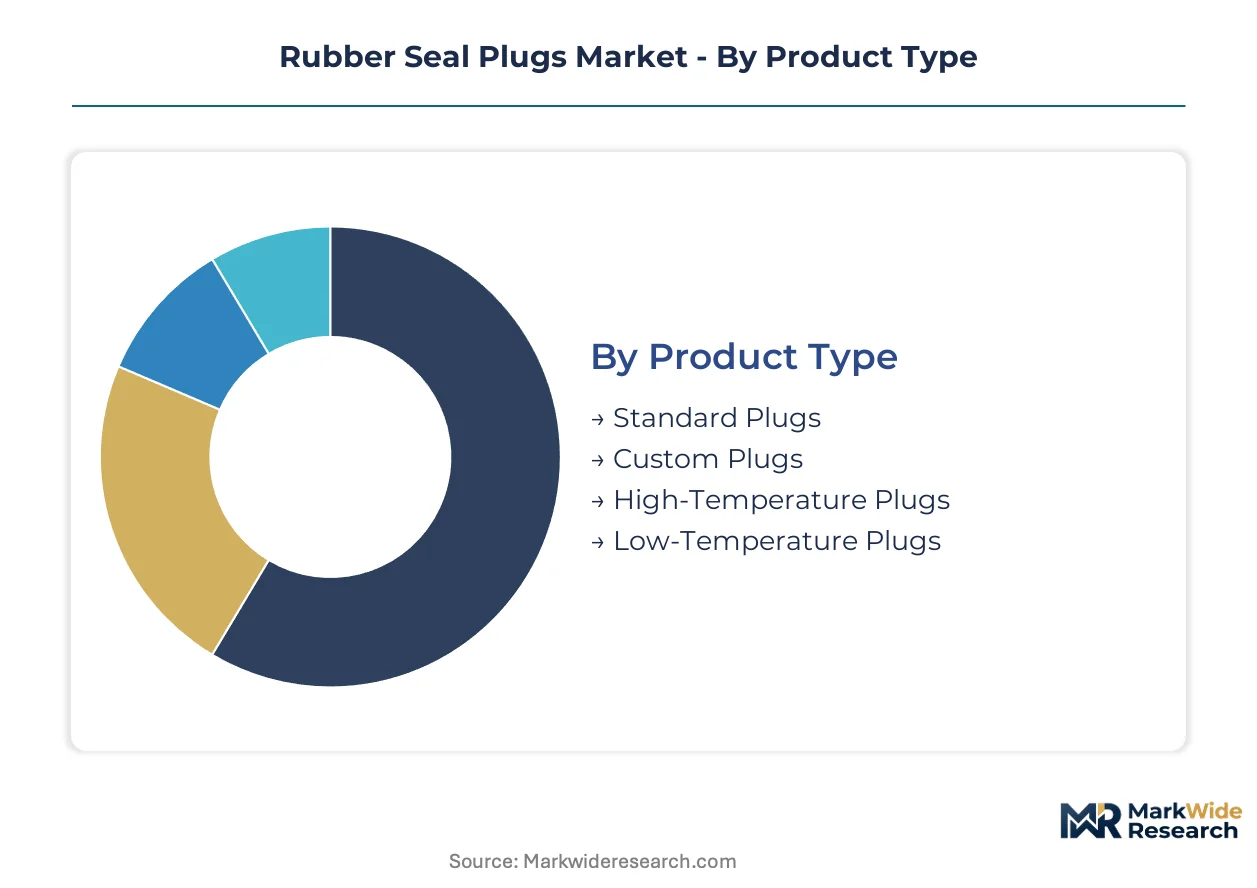
Rubber seal plugs serve divergent performance requirements across thermal cycling intensity, chemical exposure profiles, and regulatory certification burdens. Segmentation reveals where compounders capture margin premiums versus competing on production scale.
Product Type:
Standalone sealing components dominate high-specification channels, while embedded plug systems integrate into larger subassemblies for volume automotive programs.
- Standard Plugs:Compression-molded EPDM and NBR formulations in durometer ranges of 50-70 Shore A serve coolant lines, HVAC drainage, and general industrial fluid containment. Procurement concentrates among tier-one automotive suppliers in Germany's supplier corridor and China's eastern manufacturing belt, where scale economies override customization needs. EPA volatile organic compound regulations on rubber processing have forced compounder consolidation in Ohio and Michigan, reducing supplier diversity.
- Custom Plugs:Low-volume, high-precision silicone and FKM grades engineered to ±3 Shore A tolerances address aerospace fuel systems, medical device sterilization chambers, and battery thermal management architectures. BMW and CATL procurement teams specify these for 15-year service life warranties in electric vehicle platforms. Additive-manufactured mold tooling has compressed prototype-to-production timelines below six weeks for sub-1,000 unit volumes.
- High-Temperature Plugs:Perfluoroelastomer and specialized silicone compounds rated above 200°C continuous operation serve industrial oven sealing and exhaust aftertreatment systems.
- Low-Temperature Plugs:Hydrogenated nitrile and advanced EPDM grades maintaining elasticity below -40°C address arctic pipeline infrastructure and cold-chain logistics equipment.
Volume placements concentrate in Standard Plugs; the steepest expansion trajectory belongs to Custom Plugs.
Application:
Cost-tier differentiation separates specification-intensive programs with multi-year qualification cycles from replacement-driven channels with rapid inventory turnover.
- Automotive Manufacturing:Battery pack thermal runaway containment standards in Germany, China, and the United States now mandate high-durometer silicone plugs with documented thermal cycling performance across 5,000+ cycles. SAMR's GB durability testing protocols and UN ECE regulation harmonization enable single-SKU certification for export and domestic Chinese markets. Electrification is restructuring material specifications faster than legacy coolant applications ever required.
- Aerospace Applications:FAA-certified fluorocarbon and silicone formulations must demonstrate zero leakage across -60°C to 300°C operational envelopes for fuel system and hydraulic actuation sealing. Parker Hannifin leverages fluid power expertise to dominate this channel through direct OEM relationships with Boeing and Airbus tier-one suppliers.
- Industrial Machinery:Process industry refurbishment cycles accelerate replacement demand for compression-molded NBR and FKM seal plugs in hydraulic equipment.
- Consumer Goods:Cost-sensitive appliance and electronics manufacturers prioritize EPDM grades for weatherstripping and cable entry sealing.
Margin capture concentrates in Aerospace Applications; the fastest volume climb occurs in Automotive Manufacturing.
Material Grade:
Maturity-stage commodities compete on feedstock sourcing efficiency against specialty grades commanding formulation expertise premiums.
- EPDM:Ethylene-propylene-diene monomer compounds dominate outdoor and coolant applications through ozone resistance and cost-efficient ethylene feedstock access. REACH restrictions on phthalate plasticizers have forced reformulation investments across European imported and domestic supply chains. Carbon black reinforcing filler supply concentration in China and Russia creates geographic single-point-of-failure exposure for global compounders.
- Silicone:Polysiloxane-based elastomers capture premium positioning in thermal-cycling-intensive segments including electric vehicle battery packs, medical sterilization equipment, and industrial ovens. Self-healing formulations are converging with BMW and CATL procurement specifications to enable autonomous sealing recovery after thermal shock events.
- Neoprene:Chloroprene grades balance oil resistance and weathering performance in marine and heavy equipment applications.
- Nitrile:Acrylonitrile-butadiene rubber serves cost-sensitive hydraulic and fuel system sealing with proven petroleum fluid compatibility.
Supply concentration sits with EPDM; the fastest share gain belongs to Silicone.
End User:
Customer-type segmentation reveals disintermediation pressure as procurement patterns shift from distribution channels toward direct compounder relationships.
- OEMs:Original equipment manufacturers in automotive, aerospace, and industrial machinery specify raw polymer grades and durometer ranges directly with Trelleborg and Freudenberg, bypassing traditional distribution. Continental and Bosch sealing divisions now control formulation decisions previously delegated to tier-two distributors. This shift compresses distributor margins by half in specialized thermal management applications across Germany's automotive supplier corridor.
- Aftermarket Suppliers:Independent service networks and refurbishment operators prioritize inventory velocity and cross-reference compatibility over specification customization.
- Service Providers:Maintenance, repair, and overhaul contractors source standard plugs through industrial distribution for field replacement programs.
- Retailers:Hardware and automotive parts chains stock commodity EPDM and neoprene grades for consumer DIY applications.
Revenue concentration rests with OEMs; the fastest relationship-model shift is occurring in Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces specialized compounds for automotive electrification while China consumes the majority of standard-grade volumes for domestic vehicle assembly. The United States maintains a deficit in high-temperature silicone grades, importing from European compounders to serve battery thermal management demand. India is emerging as a production alternative through localization incentives.
Germany
Battery pack sealing specifications from BMW and Volkswagen drive demand for high-durometer silicone plugs rated above 200°C continuous operation. REACH restrictions on phthalate plasticizers force reformulation investments across domestic compounders serving the automotive supplier corridor. Stuttgart and Munich anchor concentration for thermal management component development.
China
CATL and BYD procurement teams specify self-healing silicone formulations for 15-year battery service life warranties. SAMR enforces GB standards for automotive component durability that mandate thermal shock testing protocols. The Yangtze River Delta manufacturing belt concentrates injection molding capacity for both domestic EV programs and export markets.
United States
EPA volatile organic compound regulations on rubber processing shape compounding facility location decisions in Ohio and Michigan. Fluid power system refurbishment cycles accelerate replacement demand for compression-molded NBR seal plugs. The Midwest industrial hub faces supply constraints for perfluoroelastomer grades used in exhaust aftertreatment systems.
Japan
Toyota and Honda electrification programs source precision-tolerance custom plugs for hybrid battery architectures. METI industrial standards harmonize with UN ECE regulations to enable single-certification export strategies. The Nagoya automotive supplier cluster specializes in low-volume, high-specification aerospace and medical device applications.
India
Maruti Suzuki and Tata Motors localization requirements under the PLI scheme open specification windows for domestic seal plug manufacturers. BIS certification mandates for automotive components create entry barriers for unqualified compounders. The Gujarat automotive supplier corridor attracts toll manufacturing investments from European compounders seeking cost-competitive production bases.
Rubber Seal Plugs Market Key Industry Players
Top-tier vendors anchor premium specification channels, while mid-scale compounders compete on production scale for standard automotive programs. The vendor base stratifies across three tiers: integrated polymer compounders with captive mixing operations, specialized seal fabricators sourcing raw materials externally, and toll manufacturers serving cost-sensitive volume applications. Two dominant competitive moves are reshaping positioning: direct OEM relationships that bypass traditional distribution channels, and additive manufacturing adoption that compresses custom plug prototyping timelines.
Among integrated compounders with European headquarters, Parker Hannifin Corporation, Trelleborg AB, and Freudenberg Sealing Technologies exemplify the premium-tier archetype. These entities occupy positions defined by formulation expertise and direct specification relationships with tier-one automotive suppliers. Parker Hannifin leverages fluid power heritage to anchor aerospace and industrial channels. Trelleborg represents advanced polymer compounding capabilities across European automotive OEMs. Freudenberg exemplifies technology leadership in extreme-temperature applications through intensive materials R&D investment.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Trelleborg AB |
| Freudenberg Sealing Technologies |
| Hutchinson SA |
| SKF Group |
| Sinclair and Rush |
| MOCAP |
| Saint-Gobain Performance Plastics |
| NOK Corporation |
| Others |
Cost & Logistics Intelligence
Tier-one automotive supplier procurement teams in Germany's automotive corridor and China's eastern manufacturing belt anchor contract-based long-term offtake agreements, compressing spot-market liquidity and reinforcing compounder pricing power in high-durometer silicone grades.
Pricing Analysis
Margin tightening in standard EPDM and NBR grades traces to ethylene feedstock volatility and carbon black supply concentration in China and Russia. Three-tier pricing structure across premium silicone, standard EPDM, and economy nitrile tiers separates certification-intensive automotive battery applications from commodity coolant sealing. Pricing pressure intensifies in standard grades as toll manufacturers in India and Southeast Asia expand compression-molding capacity. OEM direct procurement teams exhibit lowest price sensitivity for custom aerospace and medical device plugs, while aftermarket distributors and refurbishment operators drive hardest bargain in industrial replacement channels.
Supply Chain Analysis
Dual-sourcing mandates from BMW, CATL, and Continental procurement teams require qualified backup compounders for silicone grades rated above 200°C continuous operation, forcing redundant mixing capacity investments. Supply concentrates in Germany for high-specification automotive and aerospace compounds, China for standard EPDM injection molding serving domestic EV assembly, and the United States Midwest for NBR hydraulic sealing serving fluid power refurbishment cycles. Raw material dependencies span ethylene and propylene monomers for EPDM, siloxane precursors for silicone, and carbon black reinforcing fillers predominantly sourced from Chinese and Russian production clusters. Single-source vulnerability in carbon black supply creates geographic concentration risk for global compounders. Distribution runs through direct compounder-OEM relationships in premium thermal management applications, bypassing traditional distributor channels in Germany's automotive supplier corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer compounding expertise scarcity in formulation chemistry capable of balancing Shore A precision with thermal aging resistance props pricing premiums, constraining rapid capacity expansion in high-specification silicone grades.
For Market Incumbents: Extend formulation R&D investment in self-healing silicone architectures to defend against advanced thermoplastic vulcanizate substitution pressure in cost-sensitive industrial segments. Deepen backward integration into siloxane monomer supply through captive production or long-term offtake agreements with German and Chinese precursor manufacturers to secure feedstock access during ethylene price spikes. Certify redundant mixing facilities under EPA VOC regulations and REACH dossier requirements to mitigate 18-24 month multi-jurisdiction approval timelines. For New Entrants and Emerging Players: Launch via toll manufacturing arrangements with established compounders in India's Gujarat automotive corridor to bypass direct EPA compliance liability while serving Maruti Suzuki and Tata Motors localization requirements under PLI scheme incentives. Target aftermarket refurbishment channels for industrial hydraulic equipment in the US Midwest, where procurement prioritizes inventory velocity over specification customization and distributor relationships remain open. Pursue additive-manufactured mold tooling partnerships to compress prototype-to-production timelines below six weeks for sub-1,000 unit aerospace and medical device custom plug volumes. For Investors and Strategic Acquirers: The window for entry favors specialized seal fabricators with captive polymer compounding capabilities and existing REACH certification dossiers, as regulatory barriers compound formulation expertise scarcity. Acquisition candidates include mid-scale European compounders serving thermal management applications with documented thermal cycling performance across 5,000+ cycles for battery pack architectures. Watch for inflection in UN ECE regulation harmonization with China GB standards, which would enable single-SKU certification economics and compress margin premiums currently captured by multi-jurisdiction specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer Supply | Secures feedstock access for high-durometer silicone grades serving CATL and BMW battery thermal management specifications. |
| REACH Certification Dossier Investment | Enables European market access for EPDM and silicone compounds amid phthalate plasticizer restrictions. |
| Additive Manufacturing Mold Tooling Adoption | Compresses custom plug prototyping timelines below six weeks for aerospace fuel system and medical sterilization applications. |
| India PLI Scheme Localization Partnership | Opens specification windows for domestic seal plug manufacturers serving Maruti Suzuki and Tata Motors electrification programs. |
| Dual-Sourcing Qualification Expansion | Meets Continental and Bosch procurement mandates for redundant silicone compounder capacity in battery thermal management. |
Research Approach
Multi-period observation of polymer feedstock pricing indices, automotive production volumes, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with formulation chemists at integrated compounders, procurement directors at tier-one automotive suppliers, plant managers at carbon black production facilities, and regulatory affairs specialists at ECHA and EPA. Secondary validation drew from customs and trade data, SEC 10-K filings of publicly traded seal manufacturers, REACH registration dossiers, and SAMR GB standard publication records. Bottom-up segment sizing triangulated against top-down automotive and industrial equipment production forecasts.
Input-output matrices mapped ethylene and siloxane monomer supply through compounding operations to downstream automotive, aerospace, and industrial end-use demand across the projection horizon. Segmentation dimensions modeled included material grade tier, application intensity of thermal cycling, OEM versus aftermarket procurement channel, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume relationships with automotive electrification penetration rates and industrial equipment refurbishment cycle data. Battery thermal runaway containment standard adoption curves and fluid power system modernization spend patterns served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for self-healing silicone formulations in electric vehicle battery architectures; alternative pathways for advanced thermoplastic vulcanizate displacement of fluorocarbon grades would alter the outlook for compounder margin pools. Deviation in carbon black supply availability from China and Russia, or acceleration in EPA VOC enforcement actions against Ohio and Michigan mixing operations, would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Reclaimed Rubber Market
Rubber
Liquid Polybutadiene Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Liquid Silicone Rubber Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Masterbatch Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Rubber Ropes Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Rubber Foam Market
Rubber
Silicone Rubber Market
Rubber
Global Chloroprene Rubber Market
Rubber
Carboxylated Nitrile Rubber Market