
 North America Acrylamide Monomer Market | 2026-2036
North America Acrylamide Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acrylamide Monomer Market Intelligence
Chemical engineering talent is rotating toward polymer synthesis and water chemistry specializations as regional universities expand petrochemical and environmental engineering programs. Dow Inc. leverages its integrated acrylic acid-acrylamide chain to control feedstock costs across the U.S. Gulf Coast. SNF Group anchors North American supply through its Louisiana manufacturing complex, sustaining one of the continent's largest polyacrylamide production footprints. BASF SE competes on specialty acrylate copolymer formulations for high-salinity oilfield applications.
Acrylamide monomer is an unsaturated amide compound (C₃H₅NO) typically manufactured through the catalytic hydration of acrylonitrile, with polymer-grade purity specifications exceeding 98.5% for most industrial applications. Its primary commercial purpose centers on serving as the foundational building block for polyacrylamide polymers used in water clarification, enhanced oil recovery, and papermaking retention chemistry. Polyacrylamide derivatives dominate value capture in the product type structure, while acrylate copolymer grades command premium positioning in oilfield brine conditions. Water treatment end users represent the mature volume base, whereas oil and gas applications drive formulation innovation and margin expansion.
The EPA enforces acrylamide residual limits in drinking water treatment polymers under NSF/ANSI Standard 60 certification requirements, directly shaping product specifications and manufacturer compliance investments. Environment Canada administers the Chemicals Management Plan for acrylamide toxicity profiling, while OSHA mandates workplace exposure controls through permissible exposure limits in monomer production facilities. Stakeholders must monitor evolving state-level PFAS contamination protocols in the U.S., as these frameworks increasingly influence polymer selection criteria in municipal procurement decisions.
Market Dynamics
The North America acrylamide monomer market is tightening around water treatment polymer specifications as EPA residual limits under NSF/ANSI Standard 60 force reformulation investments and reshape supplier qualification criteria across municipal procurement channels.
Growth Catalysts
- EPA effluent discharge tightening:Industrial facilities across Texas and Louisiana are accelerating polymer-based flocculation program upgrades to meet stricter wastewater standards, expanding monomer offtake.
- Enhanced oil recovery chemistry:High-salinity polyacrylamide formulations for Permian Basin tertiary recovery operations are pulling specialty acrylate copolymer demand.
- Gulf Coast petrochemical corridor concentration:Proximity of oilfield chemical blending and water treatment supply chains in Texas-Louisiana creates integrated demand density.
Market Restraints
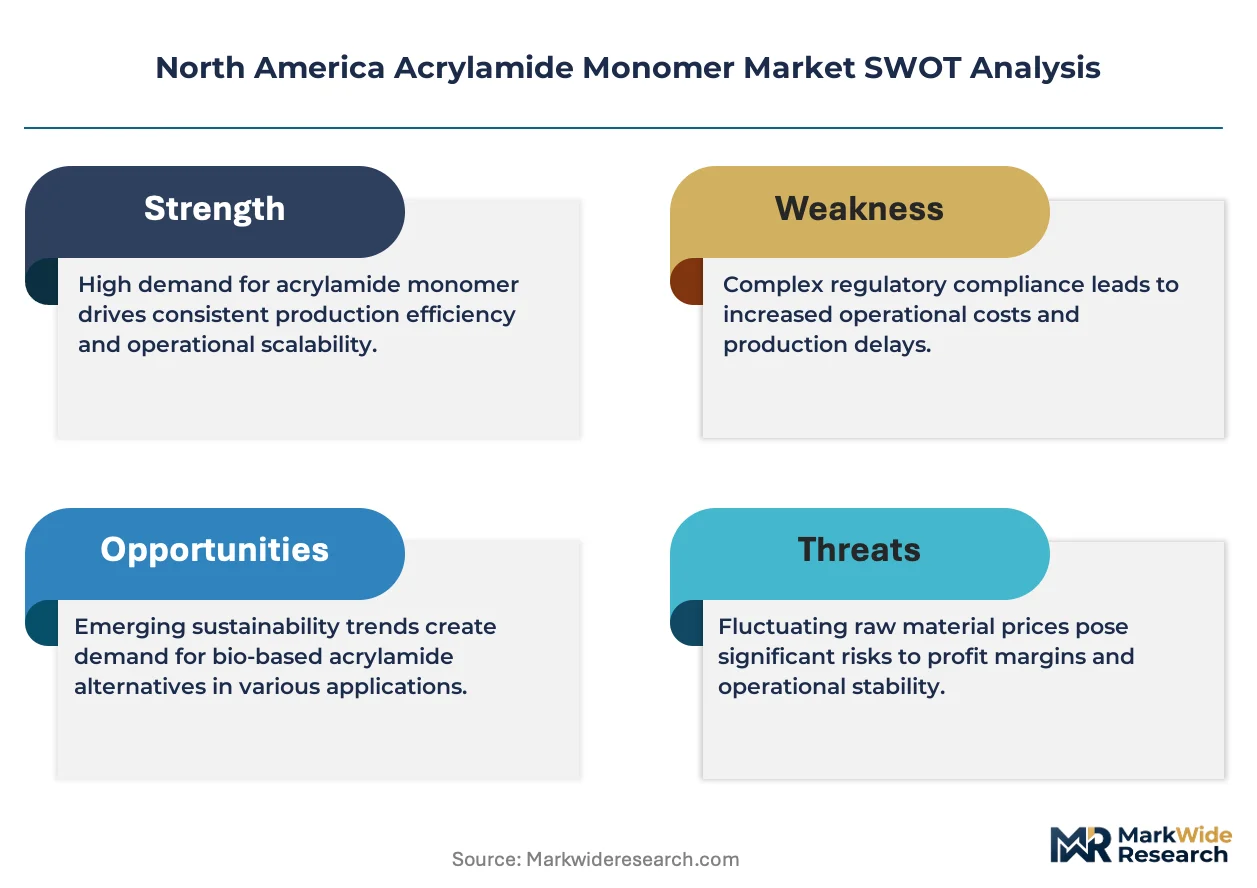
- Acrylonitrile feedstock volatility:Propylene price swings transmit directly to monomer production economics, compressing margin predictability for non-integrated producers.
- Louisiana manufacturing concentration:North American polyacrylamide supply anchors heavily on a single Gulf Coast production complex, creating geographic risk exposure.
- Acrylamide toxicity profiling:Environment Canada's Chemicals Management Plan and OSHA workplace exposure mandates elevate compliance overhead across the value chain.
Strategic Opportunities
- Canadian oil sands extraction chemistry:Alberta thermal recovery operations present underpenetrated demand for high-temperature-stable polyacrylamide derivatives.
- PFAS contamination protocol alignment:State-level U.S. procurement frameworks increasingly favor acrylamide-based polymers as PFAS alternatives in municipal water treatment.
- Papermaking retention chemistry modernization:Southeastern U.S. pulp and paper capacity upgrades are opening formulation partnerships for next-generation retention aids.
Industry Challenges
- Polymer synthesis specialization scarcity:Regional universities are expanding programs, but graduating chemical engineering talent with water chemistry expertise remains insufficient for immediate industry needs.
- NSF/ANSI Standard 60 certification timelines:New product qualification cycles stretch 18-24 months, delaying revenue recognition for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acrylamide Monomer Market |
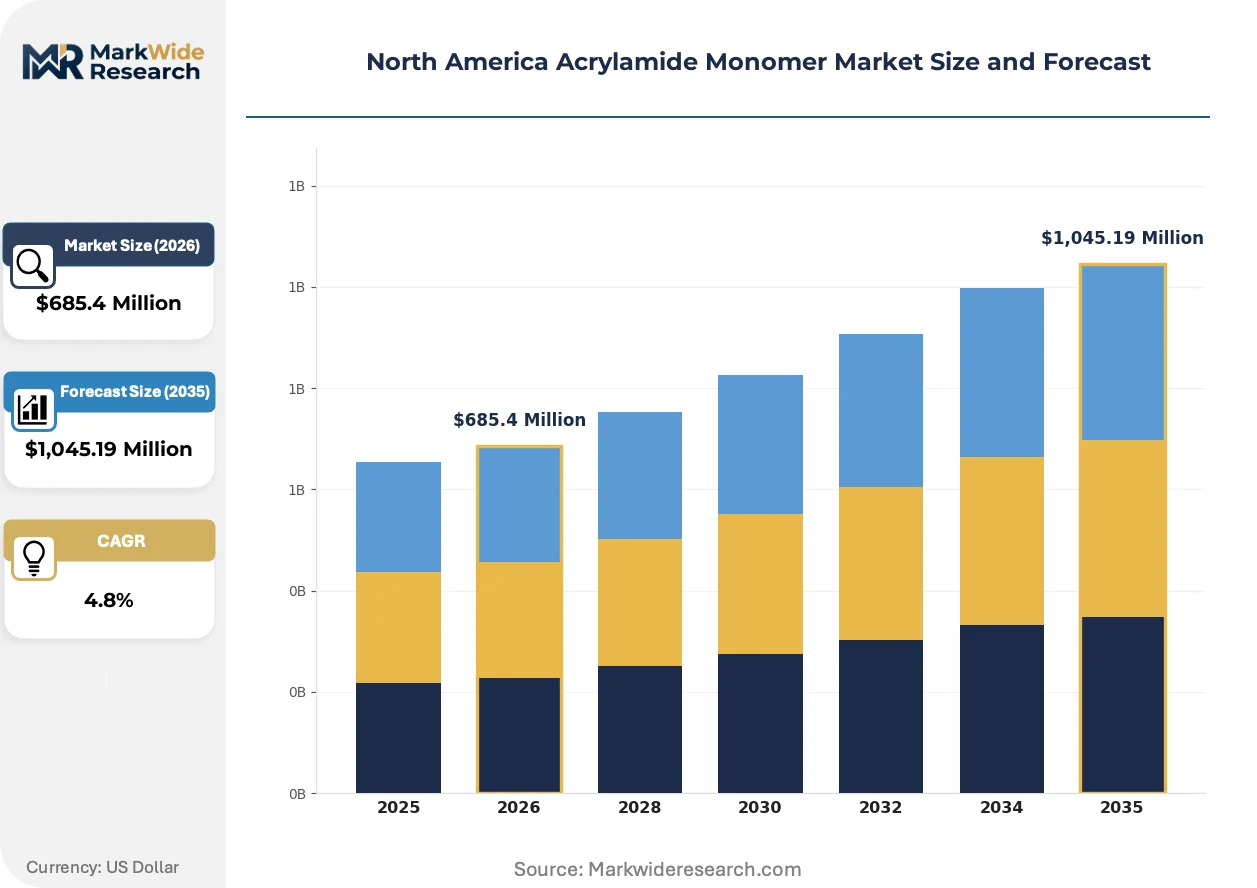
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylamide, Sodium Acrylate, Polyacrylamide, Acrylate Copolymer End User: Water Treatment, Oil & Gas, Pulp & Paper, Textile Industry Technology: Batch Process, Continuous Process, Reactive Extrusion, Solution Polymerization Packaging Type: Drums, Bags, IBC Totes, Flexible Containers |
| Companies Covered | Dow Inc., SNF Group, BASF SE, Solenis, Kemira Oyj, INEOS Group Limited, Mitsubishi Chemicals, Mitsui Chemicals, Inc., Black Rose Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acrylamide Monomer Market Strategic Shifts & Innovations
Reformulation pressure is accelerating across the North American acrylamide value chain as end-users seek higher-performance polymers that satisfy tightening regulatory thresholds while maintaining cost efficiency in large-volume water treatment applications.
Microbial biocide integration into polyacrylamide delivery systems is miniaturizing the ancillary chemical footprint at municipal treatment plants. Water utilities in California and Arizona are piloting these combined formulations to reduce storage complexity and dosing equipment requirements. The structural consequence is compressing the addressable market for standalone biocide suppliers while elevating formulation capability requirements for monomer producers.
EPA enforcement of acrylamide residual limits under NSF/ANSI Standard 60 is forcing specification upgrades across drinking water treatment polymer supply chains. Manufacturers must now document sub-0.05% monomer content in finished polyacrylamide, driving investments in catalytic hydration process controls. Municipal procurement departments in Texas and Florida are prioritizing pre-certified suppliers, reshaping competitive access to the largest volume segment.
Specification-driven vendor consolidation is concentrating municipal water treatment procurement around fewer qualified polymer suppliers. Large-volume buyers are unbundling technical service from product supply, contracting directly with formulation specialists while disintermediating traditional chemical distributors. This pattern is most visible in the Great Lakes region, where Chicago and Detroit metropolitan water authorities have consolidated polymer sourcing through direct manufacturer agreements.
North America Acrylamide Monomer Market Segmentation
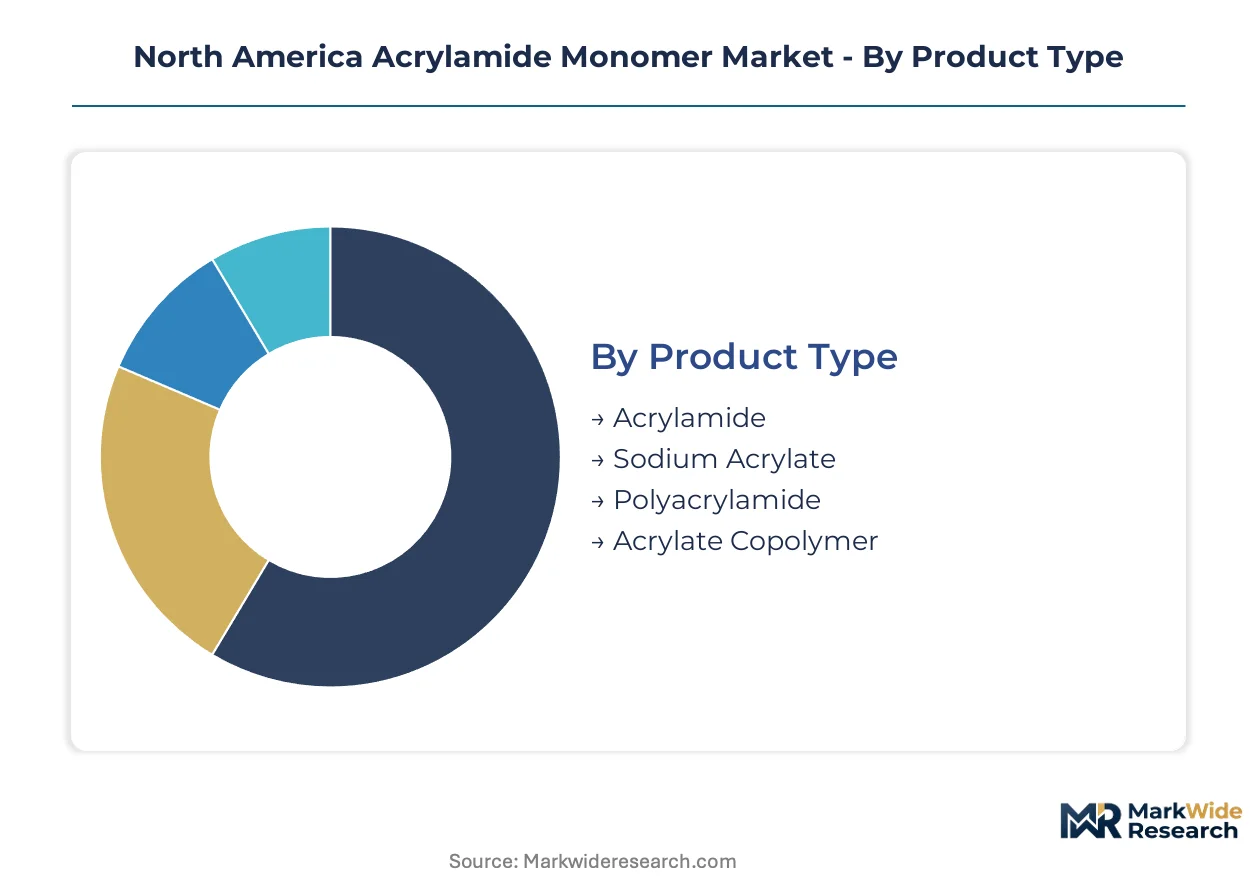
Acrylamide monomer segmentation in North America reflects the tension between commodity-grade water treatment volumes and specialty oilfield formulations. Distinct purity specifications, process technologies, and packaging requirements create divergent margin profiles across the value chain.
Product Type:
Domestic demand concentrates on higher-purity polymer-grade materials, while export flows favor intermediate acrylate derivatives.
- Acrylamide:The foundational unsaturated amide (C₃H₅NO) manufactured through catalytic hydration of acrylonitrile, with polymer-grade purity exceeding 98.5%. Texas-Louisiana Gulf Coast water treatment utilities and Permian Basin oilfield blenders anchor regional offtake, though EPA residual limits under NSF/ANSI Standard 60 force continuous purity upgrades.
- Polyacrylamide:Crosslinked polymer derivatives dominate commercial value capture, serving as the primary flocculation chemistry for municipal water clarification and enhanced oil recovery. SNF Group's Louisiana manufacturing complex sustains the continent's largest production footprint, with specialty anionic and cationic grades commanding formulation premiums in high-salinity brine conditions.
- Sodium Acrylate:Salt-neutralized monomer intermediate used in superabsorbent polymer feedstock and select copolymer synthesis.
- Acrylate Copolymer:Specialty formulations incorporating acrylic acid or other vinyl monomers for extreme-temperature or high-ionic-strength applications.
Polyacrylamide commands the established base. The steepest expansion runs through acrylate copolymer grades tailored for thermal recovery chemistry.
End User:
Application-driven cost tiers separate municipal procurement from oilfield specification premiums, with mid-market pulp and paper occupying intermediate positioning.
- Water Treatment:Municipal and industrial effluent clarification represents the mature volume foundation, with EPA discharge tightening across Texas and Louisiana accelerating polymer program upgrades. Chicago and Detroit metropolitan authorities have consolidated sourcing through direct manufacturer agreements, bypassing traditional chemical distributors.
- Oil & Gas:Enhanced oil recovery operations in the Permian Basin and prospective Alberta oil sands thermal recovery drive formulation innovation and margin expansion. High-salinity polyacrylamide specifications for tertiary recovery pull specialty acrylate copolymer demand.
- Pulp & Paper:Southeastern U.S. capacity upgrades are opening partnerships for next-generation retention aids, though volume scale trails water treatment.
- Textile Industry:Sizing and finishing applications represent legacy demand with limited regional growth trajectory.
Water treatment secures the volume anchor. Oil and gas applications deliver the steepest margin expansion trajectory.
Technology:
Process selection tracks scale economics, with continuous systems dominating Gulf Coast integrated producers and batch configurations serving specialty formulation houses.
- Continuous Process:Catalytic hydration in fixed-bed or fluidized-bed reactors enables the throughput economics required for Texas-Louisiana corridor supply. Dow Inc. leverages integrated acrylic acid-acrylamide chain architecture to optimize feedstock conversion efficiency.
- Batch Process:Flexible reactor configurations accommodate smaller-volume specialty grades and rapid formulation iteration for oilfield chemistry partners.
- Reactive Extrusion:Solid-state polymerization eliminates solvent handling, reducing environmental compliance overhead for selected applications.
- Solution Polymerization:Aqueous-phase systems predominate in polyacrylamide finishing, with molecular weight control critical to flocculation performance.
Continuous process technology secures the cost base. Batch flexibility enables the steepest premium capture in specialty segments.
Packaging Type:
Container selection reflects customer scale and handling infrastructure, with bulk formats concentrating in integrated water utility procurement.
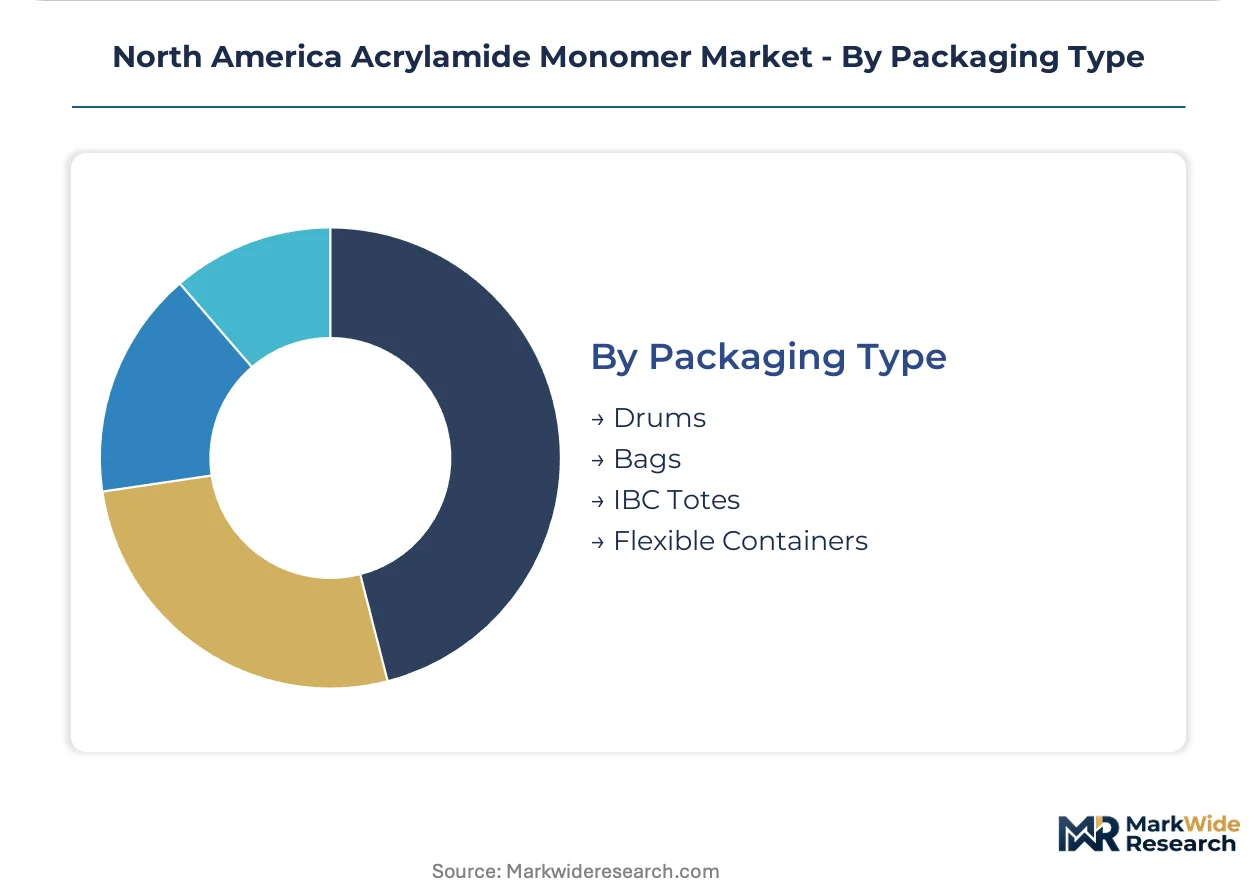
- IBC Totes:Intermediate bulk containers balance logistics efficiency with handling flexibility, dominating mid-volume oilfield chemical blending operations across the Permian Basin.
- Drums:Standard 55-gallon steel and poly configurations serve laboratory, pilot-scale, and specialty formulation customers requiring precise inventory rotation.
- Bags:Multi-wall paper and FIBC formats address powder polyacrylamide shipment for remote municipal treatment facilities with limited liquid handling infrastructure.
- Flexible Containers:Bulk bag and tanker-trailer configurations minimize unit costs for large-volume water treatment utilities with dedicated unloading systems.
IBC totes command the versatile middle ground. Flexible containers enable the steepest logistics cost reduction at volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of NSF/ANSI Standard 60 residual limits dominates North American regulatory architecture. The Texas-Louisiana Gulf Coast corridor anchors integrated production capacity. Canadian oil sands and Mexican industrial expansion present adjacent growth vectors.
United States
Texas and Louisiana concentrate petrochemical infrastructure where oilfield chemical blending intersects with water treatment supply chains. EPA discharge tightening across industrial facilities accelerates polymer-based flocculation program upgrades. The Permian Basin drives specialty acrylate copolymer demand for high-salinity enhanced oil recovery operations.
Canada
Alberta thermal recovery operations generate underpenetrated demand for high-temperature-stable polyacrylamide derivatives in oil sands extraction. Environment Canada's Chemicals Management Plan administers acrylamide toxicity profiling and workplace exposure protocols. Ontario and Quebec municipal water authorities maintain procurement frameworks that increasingly favor pre-certified polymer suppliers.
Mexico
Northern border states industrialize wastewater treatment capacity to meet export-oriented manufacturing effluent standards. Mexican environmental regulators align discharge protocols with US EPA frameworks to maintain trade competitiveness. Monterrey and Tijuana metropolitan areas expand polymer sourcing for municipal clarification systems.
North America Acrylamide Monomer Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Gulf Coast production concentration creating geographic moats. The structure rewards backward integration into acrylonitrile feedstock and catalytic hydration process control. Three archetypes dominate: petrochemical majors with acrylic acid-acrylamide chains, water chemistry specialists with formulation depth, and diversified industrials with regional distribution density. Competitive moves center on capacity expansion in Louisiana and Texas, plus direct procurement contracts that disintermediate traditional chemical distributors.
Within the integrated petrochemical tier, Dow Inc. exemplifies feedstock chain architecture, while SNF Group anchors North American polyacrylamide production scale through its Louisiana manufacturing presence. BASF SE occupies a specialty formulation position emphasizing high-salinity oilfield applications. These three represent distinct competitive vectors: captive raw material economics, regional manufacturing dominance, and premium-grade technical service.
| Leading Market Players |
|---|
| Dow Inc. |
| SNF Group |
| BASF SE |
| Solenis |
| Kemira Oyj |
| INEOS Group Limited |
| Mitsubishi Chemicals |
| Mitsui Chemicals, Inc. |
| Black Rose Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at the Louisiana manufacturing complex shapes both supply concentration and price floors across the North American acrylamide monomer market. Gulf Coast petrochemical integration enables integrated producers to maintain cost discipline while non-integrated competitors face margin compression from acrylonitrile feedstock volatility.
Pricing Analysis
Gulf Coast-to-Midwest price spreads reflect the geographic concentration of polymer-grade production against dispersed municipal water treatment demand. Three-tier pricing structure across NSF/ANSI Standard 60 certified, industrial-grade, and unclassified economy levels tracks certification investment and volume scale. Pricing pressure stems from propylene cost transmission through the acrylonitrile value chain, squeezing non-integrated producers. Municipal procurement departments exhibit highest price sensitivity through consolidated direct-manufacturer contracts, while Permian Basin oilfield blenders absorb premiums for high-salinity specialty formulations.
Supply Chain Analysis
The United States anchors North American acrylamide monomer production through the Texas-Louisiana Gulf Coast corridor, with Canada serving secondary formulation demand for Alberta oil sands applications. Raw material flows draw from propylene feedstock networks and catalytic hydration catalyst supplies, with polymer-grade acrylonitrile representing the critical input. Single-source vulnerability concentrates at the Louisiana manufacturing complex, where disruption would cascade through water treatment and oilfield chemical blending channels. Distribution runs through direct manufacturer agreements with large-volume municipal utilities, bypassing traditional chemical distributors in the Great Lakes and Southeast regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across North American acrylamide monomer procurement as Chicago and Detroit metropolitan water authorities consolidate polymer sourcing through direct manufacturer agreements, disintermediating traditional channel intermediaries.
For Market Incumbents: Fortify backward integration into acrylonitrile feedstock to defend against propylene cost volatility eroding margin predictability. Accelerate NSF/ANSI Standard 60 certification timelines for reformulated low-residual grades to preempt municipal procurement lockouts. Channel control through direct utility contracts represents the critical lever against distributor disintermediation.
For New Entrants and Emerging Players: Anchor in Alberta oil sands thermal recovery chemistry, where high-temperature-stable polyacrylamide derivatives remain underpenetrated relative to Permian Basin saturation. Target Canadian oil and gas formulation partnerships as the most penetrable segment given limited regional manufacturing presence. A technical service-led go-to-market approach bypasses capital-intensive Gulf Coast capacity requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among water treatment chemical specialists with municipal direct-contract portfolios, offering visibility through multi-year procurement cycles. Long-term viability over the medium-term projection horizon rests on regulatory compliance capability rather than commodity scale. Acquisition screening should prioritize formulation houses with NSF/ANSI Standard 60 pre-certification assets. The signal to monitor is state-level PFAS contamination protocol expansion accelerating acrylamide-based polymer substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive propylene conversion insulates margin structure from feedstock volatility at Gulf Coast complexes. |
| NSF/ANSI Standard 60 Certification Acceleration | Pre-certified status unlocks consolidated municipal procurement in Texas and Florida metropolitan systems. |
| Alberta Oil Sands Formulation Partnership | High-temperature polymer development addresses underpenetrated thermal recovery chemistry demand in Canada. |
| Direct Utility Contracting | Bypassing chemical distributors captures margin compression from Great Lakes and Southeast consolidation trends. |
| Microbial Biocide Integration R&D | Combined formulation development responds to California and Arizona municipal pilot programs reducing ancillary chemical footprints. |
Research Approach
Cross-validation between plant manager interviews at Gulf Coast production facilities and SEC 10-K filings from integrated petrochemical majors anchors the qualitative findings. Primary fieldwork encompassed procurement leads at Texas and Louisiana water treatment utilities, technical R&D directors at polyacrylamide formulation houses, and distribution channel partners serving the Permian Basin oilfield chemical blending segment. Secondary validation drew from EPA enforcement databases, Environment Canada Chemicals Management Plan documentation, American Chemistry Council sector reports, and customs trade flow records. Bottom-up capacity and utilization estimates triangulate against top-down demand modeling across end-use segments.
Sensitivity analysis around propylene price scenarios and NSF/ANSI Standard 60 enforcement timelines shapes the analytical framework. Segmentation dimensions span polymer-grade purity tiers, water treatment versus oil and gas end-use applications, continuous versus batch process technologies, and IBC tote versus bulk flexible packaging formats. CAGRs derive from regression-based trending across historical volume trajectories, adjusted for regulatory inflection points and capacity expansion announcements. Industry-specific forecast inputs include Permian Basin enhanced oil recovery deployment rates and municipal water infrastructure capital program disclosures.
Decision-makers should treat outputs as directional under stable EPA enforcement intensity and Gulf Coast production continuity assumptions; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in propylene feedstock economics, state-level PFAS substitution mandates, and Louisiana manufacturing complex operational events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Cellulose Powder Market