
 Di-Isobutylene Market | 2026-2036
Di-Isobutylene Market Size, Share, and Industry Trends Forecast 2026-2036
Di-Isobutylene Market Analytics
Petrochemical distributor networks across Asia-Pacific and Europe are reshaping how di-isobutylene reaches downstream chemical producers. Evonik Industries leverages its integrated C4 chemistry platform to sustain captive supply advantages in specialty rubber intermediates. Nizhnekamskneftekhim anchors Russian feedstock availability through its proximity to Volga-Ural crude refining complexes. TPC Group competes on Gulf Coast logistics, controlling barge and pipeline access that extends its reach into Mexican and South American markets.
Di-isobutylene, a branched C8 olefin produced via acid-catalyzed dimerization of isobutylene, functions primarily as a reactive intermediate in manufacturing butyl rubber, octylphenol resins, and neodecanoic acid derivatives with typical purity grades ranging from 75% to 95% depending on distillation severity. The liquid product type dominates volume flows due to its compatibility with existing alkene handling infrastructure and lower vapor pressure relative to gaseous forms. Fuel additives applications lead value generation as refiners seek octane-boosting components that comply with evolving tailpipe emissions standards, while adhesives segments specialize in pressure-sensitive formulations for automotive assembly where di-isobutylene-derived tackifiers offer thermal stability advantages.
EPA fuel regulations and REACH chemical authorization frameworks in Europe constrain which di-isobutylene derivatives qualify for consumer-facing applications, particularly in coatings and sealants where volatile organic compound thresholds tighten progressively. China's SAMR enforces national GB standards on fuel additive composition that dictate import specifications and domestic blending ratios. Stakeholders must monitor how divergent regional compliance timelines affect cross-border formulation harmonization and capital allocation for derivative plant expansions.
Market Dynamics
Refiners are accelerating reformulation of gasoline blending pools to accommodate di-isobutylene-derived octane boosters as sulfur-content ceilings tighten across major automotive markets. This structural pull from fuel specification evolution is redirecting C4 derivative capacity toward automotive additive intermediates.
Growth Catalysts
- REACH authorization timelines:European chemical registrants are securing extended use permissions for di-isobutylene in fuel additive applications, creating predictable demand visibility for C4 derivative investments.
- China's GB standards evolution:SAMR-mandated fuel quality upgrades are expanding specification windows for imported octane-boosting components in coastal refining clusters.
- Butyl rubber capacity expansion:Tire manufacturers are commissioning new synthetic rubber lines that specify high-purity di-isobutylene feedstock for inner-liner production.
Market Restraints
- Crude-C4 price volatility:Steam cracker operating rate fluctuations in the US Gulf Coast propagate directly into isobutylene dimerization feedstock costs.
- Midstream concentration:Barge terminal access along the Mississippi River system concentrates effective supply control among a limited set of logistics operators.
- Isooctane substitution pressure:Refiners with alkylation unit spare capacity can displace di-isobutylene-derived components with in-house produced octane boosters.
Strategic Opportunities
- Indian fuel specification convergence:BIS-mandated Bharat Stage VI norms are opening import channels for high-octane blending components as domestic refinery upgrade cycles lag demand growth.
- Adhesive tackifier premiumization:Pressure-sensitive tape producers are qualifying di-isobutylene-derived hydrocarbon resins for elevated-temperature automotive assembly applications.
- Biogenic feedstock pathways:Bio-isobutylene demonstration projects are creating qualification pathways for renewable-attributed C8 olefins in European fuel pools.
Industry Challenges
- Process safety certification:Acid-catalyzed dimerization units require extended hazard and operability reviews that compress project commissioning schedules.
- Derivative specification fragmentation:Divergent purity requirements between fuel additive and specialty rubber applications force producers to maintain segregated product slates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Di-Isobutylene Market |
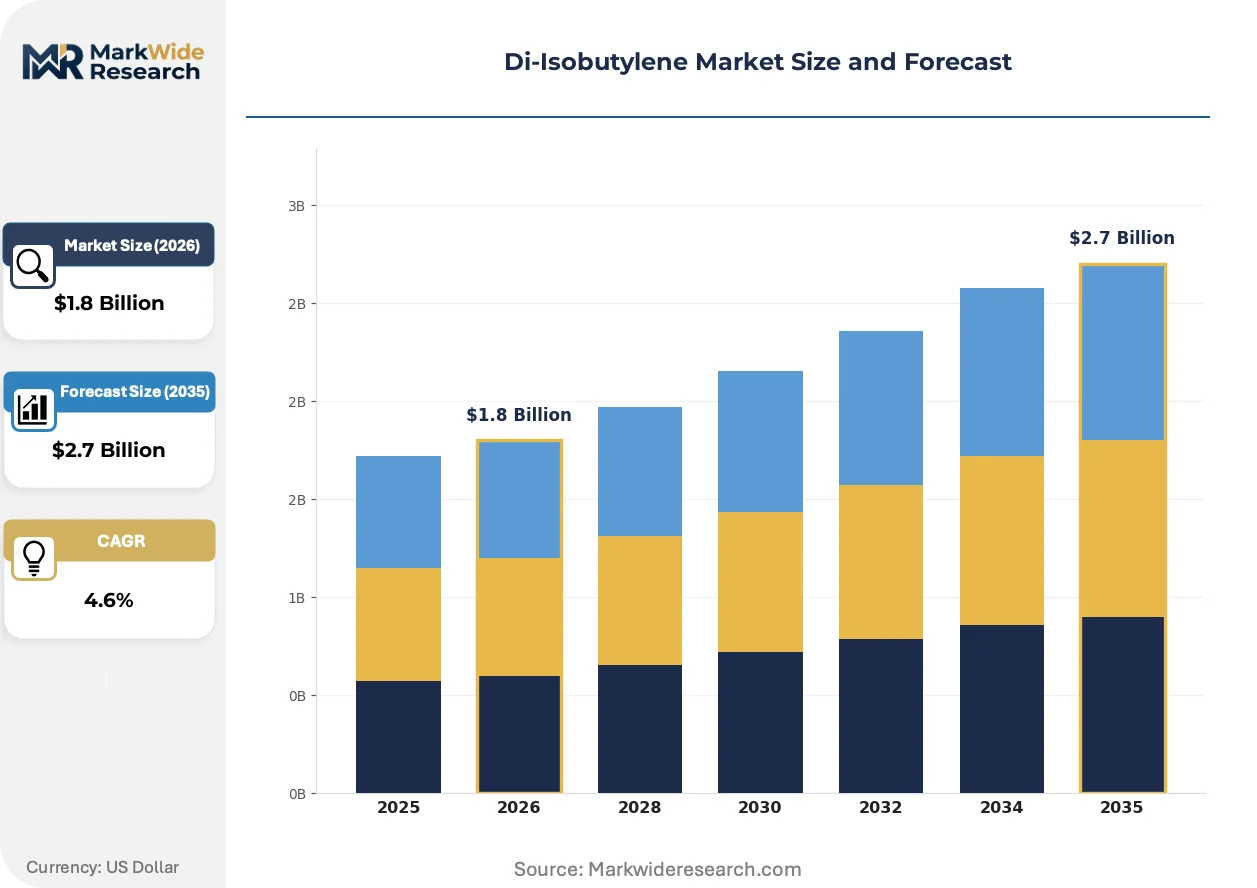
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Liquid, Solid, Polymer Application: Adhesives, Coatings, Sealants, Fuel Additives End User: Automotive Manufacturers, Construction Industry, Chemical Producers, Aerospace Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters |
| Companies Covered | Evonik Industries, Maruzen Petrochemical, Lanxess, TPC Group, LyondellBasell Industries Holdings, INEOS, Zibo JinLin Chemical, Shandong Huachao Chemical, Nizhnekamskneftekhim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Di-Isobutylene Market Evolving Landscape
Process intensification and regulatory alignment are converging to reshape how C4 olefin streams convert into specification-grade di-isobutylene. These developments are compressing capital requirements while expanding addressable end-use categories.
Reactive distillation technology is hybridizing conventional acid-catalyzed dimerization with in-situ product separation, enabling single-unit operation that previously required multiple processing trains. Specialty chemical producers in Germany and Japan are piloting these integrated systems to reduce steam consumption per ton of high-purity output. The technology is hybridizing project economics for mid-scale derivative plants that previously could not justify standalone C4 processing infrastructure.
EPA Tier 3 tailpipe emission standards are tightening benzene and sulfur allowances in finished gasoline, compelling refiners to seek alternative octane sources that avoid aromatic content. This regulatory pressure is elevating di-isobutylene's position in blending formulations relative to reformate-derived components. US Gulf Coast refiners are responding by locking in long-term offtake agreements with domestic C4 processors.
Consolidated procurement by multinational lubricant formulators is compressing supplier qualification cycles and concentrating volume awards among integrated C4 chemistry platforms. Direct refinery-to-blender relationships are displacing traditional distributor intermediaries in North American and European supply chains. This pattern is most visible in synthetic rubber applications where tire manufacturers are consolidating approved supplier lists to simplify raw material traceability compliance.
Di-Isobutylene Market Segmentation
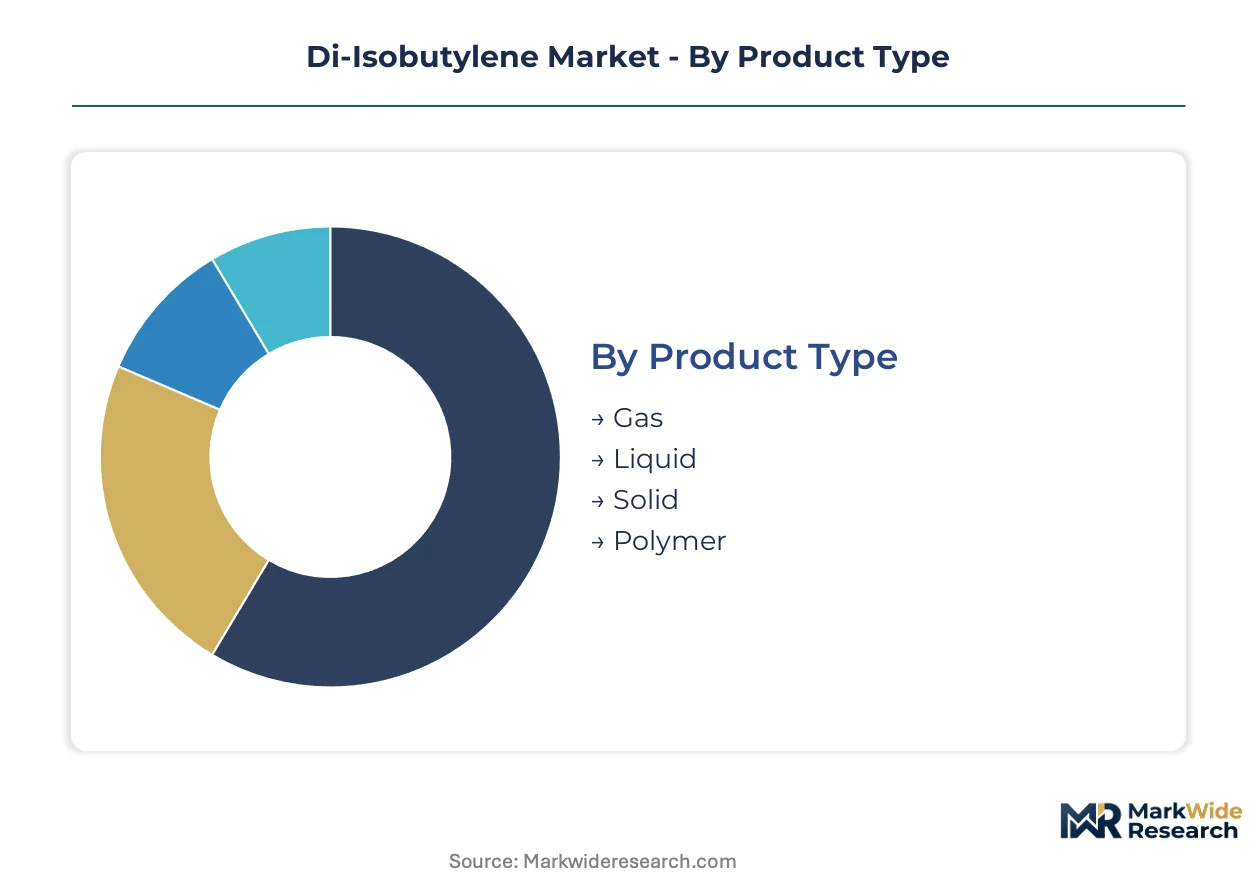
Di-isobutylene's value chain fragments across physical states, application chemistry, and customer procurement patterns. Each segmentation dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Physical state determines handling infrastructure requirements and vapor pressure specifications for downstream compatibility.
- Liquid:Dominates commercial flows due to compatibility with existing alkene handling infrastructure and lower vapor pressure relative to gaseous forms. Demand concentrates in fuel additive applications where refiners seek octane-boosting components that comply with EPA Tier 3 tailpipe emissions standards.
- Gas:Requires pressurized storage and specialized transport assets. Chemical producers in Germany and Japan are piloting reactive distillation systems to reduce steam consumption per ton of high-purity gaseous output.
- Solid:Polymer-grade specifications serve specialty rubber intermediates with extended shelf stability.
- Polymer:Captive consumption within integrated C4 chemistry platforms for synthetic rubber production.
Liquid holds installed capacity. Gas is rotating up the share rankings.
Application:
End-use chemistry dictates purity grades and regulatory qualification pathways across industrial and consumer markets.
- Fuel Additives:Lead value generation as refiners adapt gasoline blending pools to accommodate di-isobutylene-derived octane boosters under tightening sulfur-content ceilings. US Gulf Coast refiners are locking in long-term offtake agreements with domestic C4 processors.
- Adhesives:Pressure-sensitive tape producers are qualifying di-isobutylene-derived hydrocarbon resins for elevated-temperature automotive assembly applications where thermal stability advantages command premium positioning.
- Coatings:REACH chemical authorization frameworks in Europe constrain which derivatives qualify for consumer-facing applications where volatile organic compound thresholds tighten progressively.
- Sealants:Construction industry procurement concentrates volume among approved supplier lists to simplify raw material traceability compliance.
Fuel Additives holds installed capacity. Adhesives is rotating up the share rankings.
End User:
Customer scale and integration depth create divergent purchasing power and specification authority.
- Chemical Producers:Consolidated procurement by multinational lubricant formulators compresses supplier qualification cycles and concentrates volume awards among integrated C4 chemistry platforms.
- Automotive Manufacturers:Tire manufacturers commission new synthetic rubber lines that specify high-purity di-isobutylene feedstock for inner-liner production.
- Construction Industry:Project-based demand fluctuates with regional infrastructure spending cycles and building code adoption timelines.
- Aerospace Sector:Qualification protocols for specialty sealants extend sales cycles but secure multi-year supply agreements.
Chemical Producers holds installed capacity. Automotive Manufacturers is rotating up the share rankings.
Distribution Channel:
Channel selection reflects customer concentration geography and product hazard classification requirements.
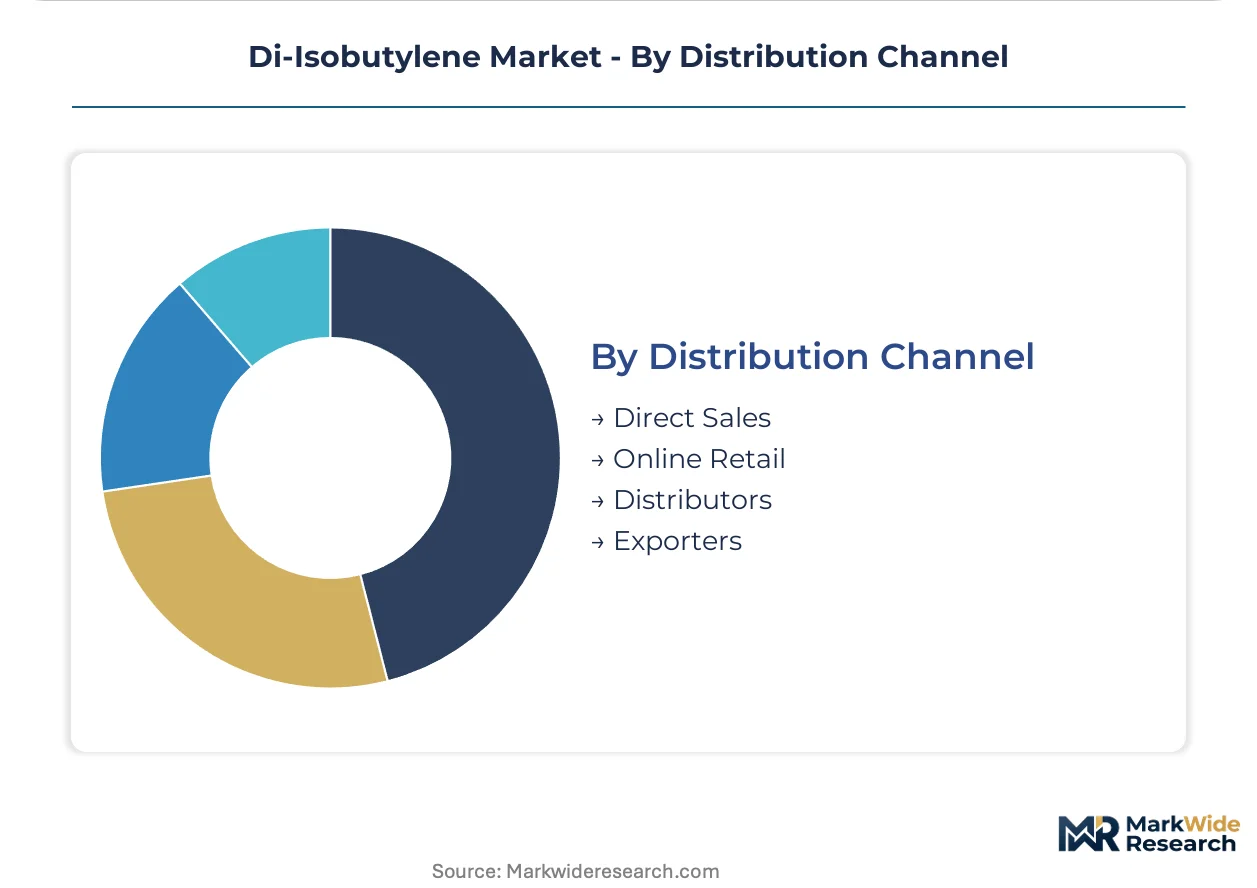
- Distributors:Petrochemical distributor networks across Asia-Pacific and Europe reshape how di-isobutylene reaches downstream chemical producers, though direct refinery-to-blender relationships are displacing traditional intermediaries in North American supply chains.
- Direct Sales:Barge terminal access along the Mississippi River system concentrates effective supply control among a limited set of logistics operators serving Gulf Coast refiners.
- Exporters:Coastal refining clusters in China expand specification windows for imported octane-boosting components under SAMR-mandated fuel quality upgrades.
- Online Retail:Limited to small-volume specialty grades and analytical reference standards.
Distributors holds installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Houston Ship Channel infrastructure anchor North American di-isobutylene flows to Gulf Coast refiners. Rotterdam's ARA storage complex serves as Europe's primary C4 olefin distribution hub. China's Ningbo-Zhoushan port cluster handles the majority of Asia-Pacific import volumes for octane-boosting components.
United States
Gulf Coast refiners are locking in long-term offtake agreements with domestic C4 processors as EPA Tier 3 tailpipe emission standards tighten benzene allowances in finished gasoline. The EPA's evolving sulfur-content regulations redirect formulation strategies toward cleaner-burning additives. Houston and Beaumont host concentrated acid-catalyzed dimerization capacity serving automotive fuel additive demand.
Germany
Specialty chemical producers in the Rhine-Ruhr industrial zone pilot reactive distillation systems to reduce steam consumption per ton of high-purity output. REACH authorization timelines secure extended use permissions for di-isobutylene in fuel additive applications, creating predictable demand visibility. Ludwigshafen and Marl anchor integrated C4 chemistry platforms for synthetic rubber intermediates.
China
SAMR-mandated fuel quality upgrades expand specification windows for imported octane-boosting components in coastal refining clusters. GB standards on fuel additive composition dictate import specifications and domestic blending ratios. Ningbo and Dalian concentrate petrochemical infrastructure supporting derivative production for lubricant applications.
Japan
METI-guided industrial policy supports qualification pathways for renewable-attributed C8 olefins in domestic fuel pools. Pressure-sensitive tape producers qualify di-isobutylene-derived hydrocarbon resins for elevated-temperature automotive assembly applications. Chiba and Yokkaichi host demonstration projects for bio-isobutylene feedstock integration.
India
BIS-mandated Bharat Stage VI norms open import channels for high-octane blending components as domestic refinery upgrade cycles lag demand growth. The country's national fuel regulator enforces progressively tighter sulfur specifications in metropolitan markets. Gujarat's Jamnagar refining complex and Maharashtra's Mumbai cluster concentrate import terminal capacity for C4 derivative distribution.
Di-Isobutylene Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive feedstock advantages. The vendor base organizes around three strategic archetypes: integrated petrochemical majors with C4 chemistry platforms, regional distributors controlling barge and pipeline logistics, and specialty chemical producers focusing on high-purity grades for synthetic rubber. M&A activity concentrates on securing midstream terminal access, while capacity expansion targets reactive distillation technology deployment.
Among Germany-based integrated chemical producers, Evonik Industries exemplifies the platform-integrator archetype through its C4 chemistry infrastructure. Japanese petrochemical specialists including Maruzen Petrochemical occupy positions within the high-purity specialty tier. TPC Group represents the logistics-anchored competitive model with Gulf Coast barge network control. Nizhnekamskneftekhim anchors the feedstock-proximity archetype through its Volga-Ural crude refining complex position.
| Leading Market Players |
|---|
| Evonik Industries |
| Maruzen Petrochemical |
| Lanxess |
| TPC Group |
| LyondellBasell Industries Holdings |
| INEOS |
| Zibo JinLin Chemical |
| Shandong Huachao Chemical |
| Nizhnekamskneftekhim |
| Others |
Value Network & Pricing Analysis
US Gulf Coast steam cracker concentration feeds directly into margin capture at the C4 derivative tier, where barge terminal operators extract logistics premiums before product reaches fuel additive blenders. This upstream tightness in isobutylene feedstock availability shapes how refiners negotiate long-term offtake terms versus spot market exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the di-isobutylene market by purity grade and delivery commitment length. Premium tiers command spreads based on polymer-grade specifications for synthetic rubber feedstock, while economy tiers serve fuel additive blenders with 75-85% purity acceptance. Cost compression in the standard tier is intensifying because alkylation unit operators at integrated refineries can substitute in-house isooctane for imported di-isobutylene derivatives. Fuel additive blenders exhibit highest price sensitivity due to formula cost pass-through limitations, whereas specialty rubber producers accept premium positioning for supply security.
Supply Chain Analysis
Export-control regimes on acid-catalyzed dimerization technology limit reactor system flows to qualified engineering contractors in Germany and Japan, constraining capacity expansion timelines in emerging markets. Geographic supply concentration centers on the United States, Germany, and China, where integrated C4 chemistry platforms anchor derivative output. Raw material dependencies draw from refinery isobutylene streams, sulfuric acid catalyst supply, and specialized distillation column internals. Single-source vulnerability runs through Mississippi River barge terminals controlled by limited logistics operators. Distribution feeds from coastal storage hubs into direct refinery contracts, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The di-isobutylene market sits in a cyclical recovery phase as automotive production normalization and tire capacity expansion restore C4 derivative offtake volumes from pandemic-era lows.
For Market Incumbents: Pre-empt isooctane substitution pressure by locking multi-year fuel additive supply contracts with Gulf Coast refiners ahead of alkylation unit restart cycles. Secure backward integration into barge terminal capacity along the Houston Ship Channel to defend logistics margin capture against regional distributors expanding their asset footprints. For New Entrants and Emerging Players: India's coastal refining clusters represent the most penetrable entry point as Bharat Stage VI compliance deadlines outpace domestic C4 processing capacity installation. Bio-isobutylene qualification pathways in European fuel pools offer a differentiated feedstock narrative for sustainability-mandated procurement tenders. Partner with engineering contractors holding licensed reactive distillation technology to bypass capital barriers of conventional multi-train process designs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across reactive distillation-equipped mid-scale plants as single-unit operations displace legacy infrastructure requirements. Long-term viability favors platforms with captive refinery relationships and specialty rubber qualification track records. Monitor EPA Tier 3 benzene limit enforcement intensity as the signal indicating fuel additive demand inflection versus alkylation substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barge Terminal Assets | Logistics control along the Houston Ship Channel secures Gulf Coast refinery access against competitor displacement. |
| Reactive Distillation Technology Deployment | Single-unit process intensification reduces steam consumption per ton at German and Japanese pilot installations. |
| Long-term Supply Agreement with Tire Manufacturers | High-purity feedstock commitments for inner-liner production anchor volume visibility through synthetic rubber demand cycles. |
| Bio-isobutylene Feedstock Qualification | Renewable-attributed C8 olefin pathways open European fuel pool access under evolving sustainability procurement mandates. |
| Joint Venture with Coastal Refining Cluster | China's Ningbo-Zhoushan port infrastructure enables import specification compliance under SAMR-mandated GB standards evolution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing refinery blending specialists, synthetic rubber plant managers, petrochemical procurement leads, and barge logistics coordinators. Secondary validation drew from EPA regulatory filings, ECHA REACH registration databases, SAMR GB standard publications, and customs trade flow records. Bottom-up volume builds from end-use application consumption were triangulated against top-down capacity assessments from acid-catalyzed dimerization unit installations.
Calibration against historical operating rate data and announced capacity expansion timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include physical state tier, application chemistry, end-user integration depth, and regional production hub classification. CAGRs were derived from elasticity-adjusted demand projections incorporating fuel specification evolution and synthetic rubber capacity commissioning schedules. Industry-specific inputs encompassed steam cracker operating rate volatility and reactive distillation technology adoption curves.
Practitioners should monitor refinery alkylation unit utilization rates and bio-isobutylene demonstration project scale-up milestones for early signals of demand displacement or feedstock transition. Forecasts reflect documented assumptions on regulatory timeline adherence and automotive production recovery trajectories. Material shifts in EPA benzene enforcement intensity or REACH authorization withdrawal would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Global Ammonium Chloride Market