
 Driverless Sweeper Market | 2026-2036
Driverless Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
Driverless Sweeper Market Insights
A shift from single-source sensor procurement to multi-source perception stacks is repositioning how manufacturers secure component reliability. Boschung leverages its European manufacturing footprint to sustain long-term municipal contracts. Gaussian Robotics dominates lidar integration for compact sweepers in dense Asian urban corridors. Trombia Technologies differentiates through specialized air-purification attachments that extend machine utility beyond surface cleaning.
Driverless sweepers are autonomous surface-cleaning vehicles integrating lidar arrays, computer vision modules, and GPS-tracked navigation systems to execute debris removal without human operators, typically operating at 6-15 km/h with 2-8 hour battery cycles depending on sweep path width. Their primary purpose is to reduce labor costs and extend cleaning coverage windows in high-traffic commercial and public environments. Ride-on sweepers anchor current revenue pools due to their compatibility with existing municipal fleet infrastructure, while compact sweepers represent the fastest-growing product category as property managers seek aisle-width machines for constrained retail and logistics spaces. Lidar systems capture the dominant technology share because they deliver centimeter-grade obstacle detection in low-light conditions where computer vision alone degrades.
FAA guidelines for autonomous ground vehicles on airport aprons, OSHA standards for industrial equipment operator safety, and CE marking under the EU Machinery Directive collectively shape product design requirements and market access conditions for cross-border sales. China's SAMR enforces GB standards that mandate fail-safe braking and electromagnetic compatibility testing before domestic deployment. Stakeholders must monitor how evolving liability frameworks for unmanned machinery intersect with insurance underwriting practices as fleet operators scale beyond pilot programs.
Market Dynamics
Multi-source perception stacks are displacing single-sensor architectures across autonomous sweeper manufacturing, forcing component procurement restructuring and reshaping supplier relationships throughout the value chain.
Growth Catalysts
- CE marking acceleration:Europe's Machinery Directive compliance timelines are compressing product certification cycles, enabling faster cross-border fleet deployment for municipal contractors.
- Airport apron automation:FAA guidelines for autonomous ground vehicles are opening controlled airside environments to unmanned cleaning operations where labor shortages constrain manual coverage.
- East Asian fleet networks:Dense urban corridors in Singapore and South Korea are deploying centrally managed sweeper pools that maximize equipment utilization through dynamic route optimization.
Market Restraints
- Lithium supply concentration:Battery pack manufacturing depends on cathode material flows from concentrated upstream geographies, exposing fleet operators to input cost volatility and procurement lead-time extension.
- GB standard friction:China's SAMR mandates fail-safe braking and electromagnetic compatibility testing that adds certification duration for equipment seeking domestic deployment.
- Computer vision degradation:Low-light performance limitations in camera-only systems create reliability gaps that lidar-dependent architectures must cover, raising bill-of-materials thresholds.
Strategic Opportunities
- Retail logistics penetration:Aisle-width compact sweepers are entering constrained warehouse environments where manual cleaning interrupts fulfillment velocity and autonomous coverage extends operational windows.
- EU Green Deal alignment:Battery-electric sweeper fleets qualify for municipal procurement preferences under carbon-reduction mandates, creating specification tailwinds for zero-emission equipment.
- Lidar-computer vision fusion:Sensor convergence is enabling perception redundancy that reduces single-point-of-failure risk and supports insurance underwriting for unmanned operations at scale.
Industry Challenges
- Autonomy software talent scarcity:Fleet operators and OEMs compete for embedded systems engineers capable of integrating SLAM navigation with safety-critical control loops, compressing development timelines.
- OSHA compliance complexity:Industrial equipment operator safety standards create interpretation ambiguity for unmanned machinery liability, slowing insurance product development for scaled deployments.
- Legacy fleet integration:Municipal procurement cycles must accommodate mixed autonomous-manual operations during transition periods, requiring telematics standardization that extends deployment planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driverless Sweeper Market |
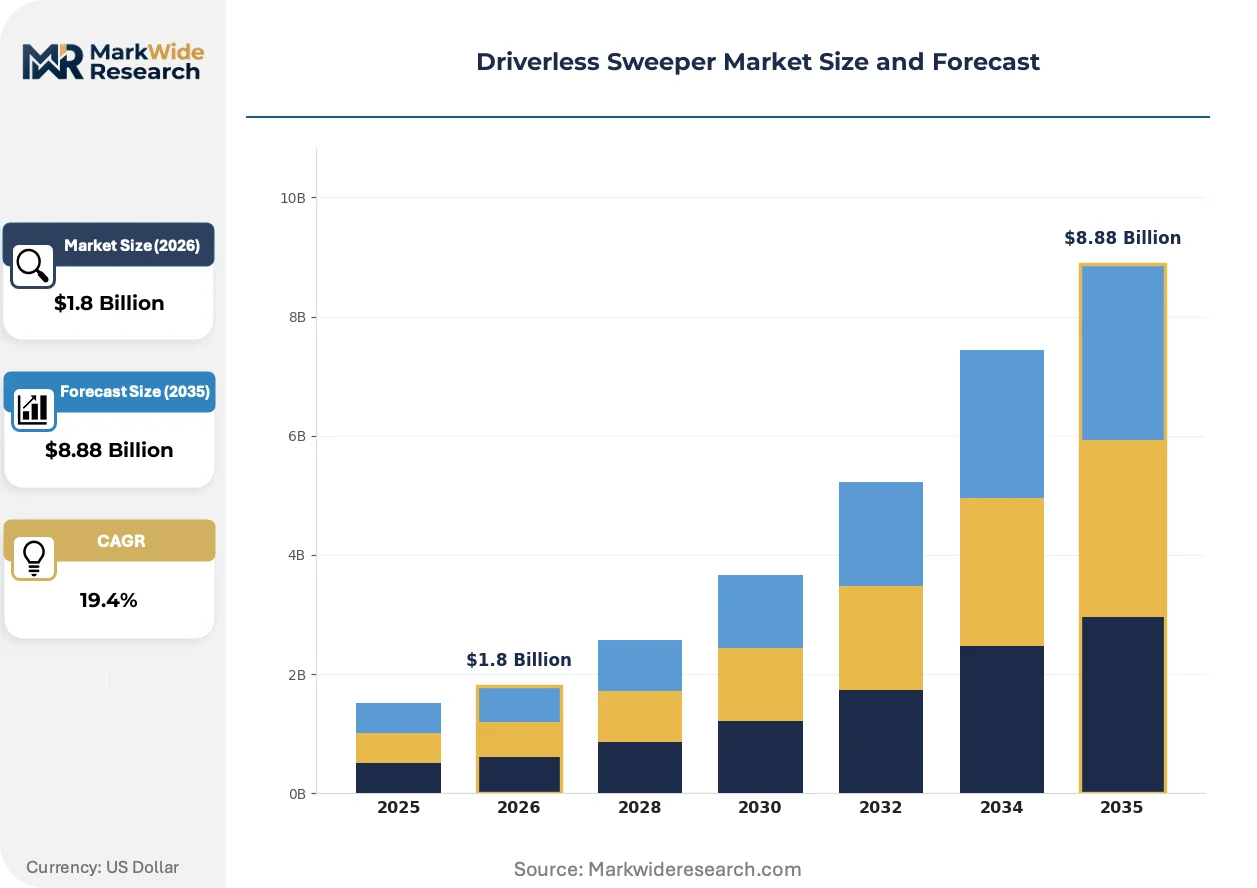
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ride-On Sweepers, Walk-Behind Sweepers, Compact Sweepers, Industrial Sweepers Technology: Laser Navigation, Lidar Systems, Computer Vision, GPS Tracking End User: Municipalities, Industrial Facilities, Commercial Spaces, Airports Deployment: On-Premise, Cloud-Based, Hybrid, Fleet Management |
| Companies Covered | Boschung, Trombia Technologies, Bucher Industries, Autowise, Fulongma, Cowarobot, Gaussian Robotics, Dulevo International, Aebi Schmidt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driverless Sweeper Market Trends and Innovations
Perception hardware convergence and procurement model restructuring are simultaneously reshaping technical architectures and commercial relationships across the autonomous surface-cleaning value chain.
Lidar arrays are integrating solid-state scanning mechanisms that reduce moving-part failure rates while maintaining centimeter-grade obstacle detection. Municipal fleet managers in Germany are specifying these configurations for 24-hour public space coverage where maintenance access is constrained. The technology is integrating with edge-compute modules that process point clouds locally, reducing latency in pedestrian-dense environments and enabling faster obstacle classification without cloud dependency.
China's GB standards for autonomous vehicle safety are mandating electromagnetic compatibility testing and fail-safe braking validation before domestic market entry. This regulatory architecture is elevating certification costs for imported equipment while creating compliance barriers that favor locally certified manufacturers. Compact sweeper categories face the most pronounced timeline compression as SAMR accelerates review cycles for urban sanitation applications.
Facility managers are unbundling equipment ownership from cleaning service delivery, preferring performance-based contracts where uptime guarantees replace capital expenditure commitments. Third-party fleet operators are capturing this demand shift by deploying autonomous sweepers under multi-year service agreements. Singapore's public space maintenance tenders are exhibiting this pattern most visibly, with procurement specifications emphasizing coverage metrics over equipment brand mandates.
Driverless Sweeper Market Segmentation
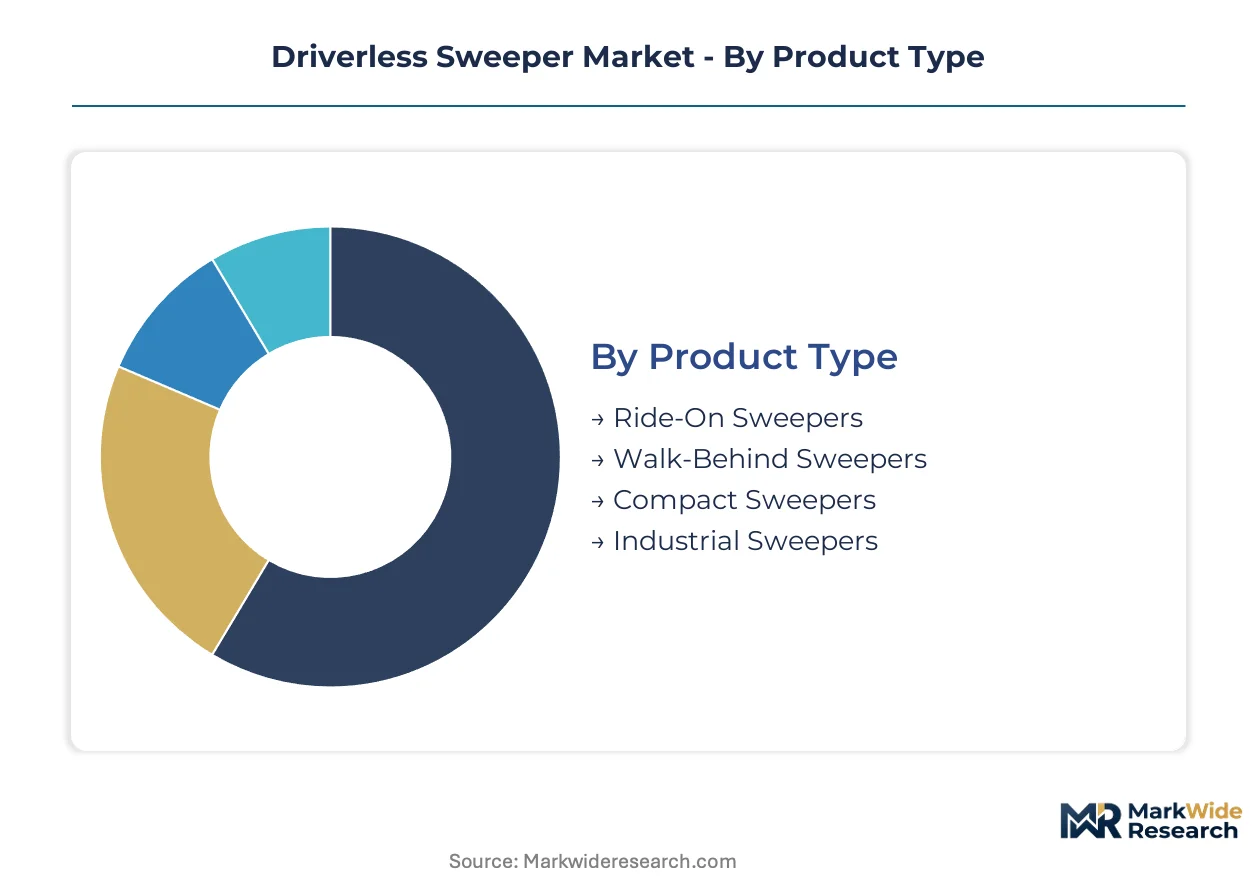
Segmentation in the driverless sweeper market reveals how procurement priorities diverge between capital-intensive fleet operators and facility managers optimizing constrained spaces. Technical specifications, deployment architectures, and regulatory compliance requirements reshape buying criteria across each dimension.
Product Type:
Buyers differentiate primarily by infrastructure compatibility and operational footprint rather than cleaning performance alone.
- Ride-On Sweepers:These units integrate with existing municipal fleet maintenance protocols and charging infrastructure. Municipalities in Germany specify ride-on configurations for 24-hour public space coverage where equipment standardization reduces spare parts inventory complexity.
- Compact Sweepers:Narrow chassis designs navigate retail aisles and logistics corridors below 1.5 meters width. Property managers in Singapore deploy these units in mixed-use developments where daytime cleaning must avoid pedestrian disruption.
- Walk-Behind Sweepers:Semi-autonomous units bridge manual and fully autonomous operations in transitional deployments.
- Industrial Sweepers:Heavy-duty configurations handle manufacturing debris loads and chemical exposure environments.
Volume sits with ride-on configurations; growth tilts toward compact sweepers.
Technology:
Perception stack choices determine reliability thresholds in low-light and high-clutter environments.
- Lidar Systems:Solid-state scanning mechanisms deliver centimeter-grade obstacle detection without moving-part failure risks. Dense urban corridors in South Korea mandate lidar-dominant architectures for pedestrian-dense night operations where camera degradation creates liability exposure.
- Computer Vision:Camera-based systems reduce unit cost but require supplemental sensing for 24-hour coverage. Warehouse operators in Japan deploy vision-primary configurations in climate-controlled environments with consistent artificial lighting.
- Laser Navigation:Structured-light positioning enables precise path repetition in fixed-route municipal applications.
- GPS Tracking:Satellite-based localization anchors fleet coordination and theft recovery in large-scale deployments.
Lidar captures current procurement preference; computer vision fusion architectures are gaining share fastest.
End User:
Contract structures and compliance obligations reshape specification requirements across buyer categories.
- Municipalities:Public procurement frameworks prioritize equipment interoperability and multi-year service availability. German cities specify CE-marked units with standardized telematics protocols for mixed-fleet integration during transition periods.
- Airports:FAA guidelines for autonomous ground vehicles create specialized certification pathways. Controlled airside environments in the United States deploy sweepers under strict radio-frequency and failsafe braking mandates.
- Industrial Facilities:OSHA compliance complexity slows unmanned deployment in manufacturing settings with human-robot interaction zones.
- Commercial Spaces:Performance-based contracts replace capital expenditure for retail and hospitality operators seeking uptime guarantees.
Municipalities anchor installed base; airports show the steepest expansion trajectory.
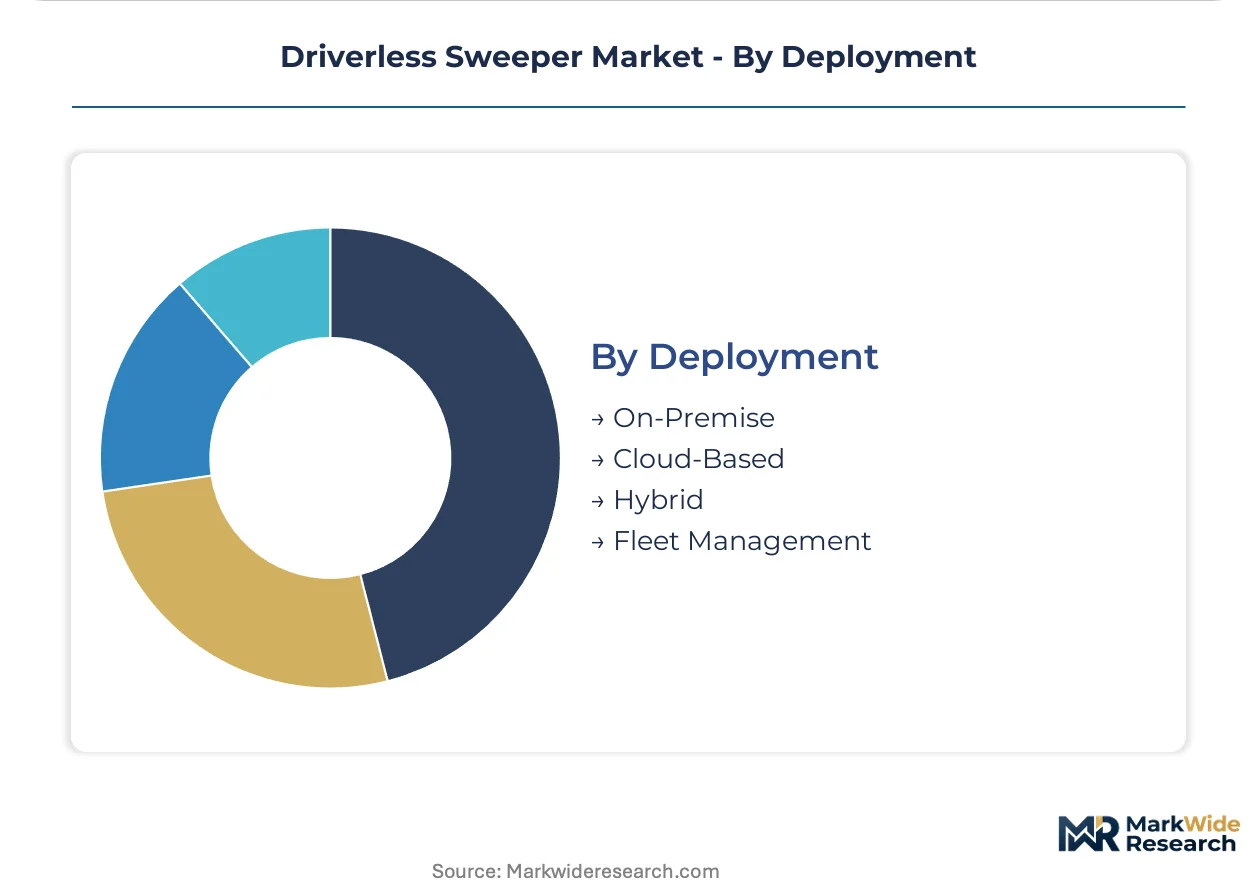
Deployment:
Data architecture choices determine latency, cybersecurity exposure, and operational continuity during connectivity interruptions.
- Fleet Management:Centralized coordination platforms optimize route efficiency across multi-unit deployments. Singapore's public space maintenance tenders specify fleet-native architectures with dynamic task allocation and predictive maintenance integration.
- Hybrid:Edge-cloud partitioning processes safety-critical functions locally while uploading telemetry for optimization. European operators favor hybrid configurations under GDPR constraints that limit continuous data transmission.
- On-Premise:Fully localized processing eliminates external connectivity dependencies in security-sensitive facilities.
- Cloud-Based:Pure cloud architectures reduce hardware cost but create operational risk in bandwidth-constrained environments.
Hybrid deployments dominate current procurement; fleet-native platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium processing capacity in Jiangsu Province anchors East Asian battery supply chains for autonomous sweeper fleets. German engineering clusters and Singaporean procurement frameworks reshape deployment economics across three continents.
China
Municipal sanitation departments in Shanghai and Shenzhen are tendering for centrally managed autonomous sweeper networks. SAMR enforces GB standards mandating fail-safe braking and electromagnetic compatibility testing that compresses certification timelines for domestic manufacturers. The Yangtze River Delta hosts dense concentrations of lidar component fabricators serving compact sweeper OEMs.
Germany
CE marking under the EU Machinery Directive accelerates cross-border fleet deployment for municipal contractors in Berlin and Munich. The KBA maintains type-approval pathways for autonomous ground vehicles operating in pedestrian-dense public spaces. Bavaria's industrial corridor sustains long-term manufacturing partnerships between European sweeper OEMs and municipal fleet operators.
Singapore
Performance-based procurement specifications emphasize coverage metrics over equipment ownership in public space maintenance tenders. The country's national environmental agency mandates telematics interoperability for mixed autonomous-manual fleet transitions. Urban redevelopment zones in Marina Bay deploy aisle-width compact sweepers for constrained retail and hospitality corridors.
United States
FAA guidelines for autonomous ground vehicles on airport aprons open controlled airside environments to unmanned cleaning operations. OSHA standards for industrial equipment operator safety create compliance interpretation challenges for scaled fleet deployments. Dallas-Fort Worth and Atlanta metropolitan airports are piloting autonomous sweeper coverage where labor shortages constrain manual operations.
South Korea
Seoul's metropolitan government specifies lidar-dominant perception architectures for 24-hour pedestrian-dense night operations. The MFDS maintains medical-device-grade reliability standards that cross-apply to safety-critical autonomous machinery controls. Busan's logistics hubs deploy compact sweepers under fleet-native platforms with dynamic route optimization.
Driverless Sweeper Market Competitive Landscape
Global majors compete with regional champions across perception technology sourcing and municipal contract tenure. The vendor base organizes around three tiers: European incumbents with established fleet service relationships, Chinese specialists in compact urban configurations, and airport-focused system integrators. Strategic archetypes include full-stack autonomy developers, component-assembly contract manufacturers, and fleet-as-a-service operators. Dominant competitive moves involve strategic partnerships for sensor procurement and geographic expansion through municipal tender participation.
Within the European manufacturing tier, Boschung GmbH and Aebi Schmidt occupy positions anchored by long-term municipal service contracts. Bucher Industries exemplifies the diversified industrial equipment archetype with sweeper operations sitting within broader environmental technology portfolios. Among China-based specialists, Gaussian Robotics represents the lidar-integration archetype for dense urban corridors, while Autowise occupies a position within the airport-focused deployment segment. Trombia Technologies anchors the air-purification attachment specialization that extends machine utility beyond surface cleaning functions.
| Leading Market Players |
|---|
| Boschung |
| Trombia Technologies |
| Bucher Industries |
| Autowise |
| Fulongma |
| Cowarobot |
| Gaussian Robotics |
| Dulevo International |
| Aebi Schmidt |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between CE-marked municipal fleets and uncertified compact units manifests in pricing spreads exceeding threefold, with warranty bundling and telematics integration determining procurement thresholds across European and East Asian buyer archetypes. This bifurcation concentrates procurement power among fleet operators capable of absorbing upfront capital, while cost-conscious facility managers prioritize unbundled equipment acquisition with third-party service overlays.
Pricing Analysis
Warranty and predictive maintenance bundling separates municipal fleet contracts from retail procurement, with CE-marked ride-on configurations commanding premium positioning against compact units sold without service overlays. Pricing stratifies across premium, standard, and economy tiers based on lidar array density and fail-safe braking certification grade. Cost compression in the compact segment intensifies as Chinese OEMs expand output without SAMR electromagnetic compatibility validation. Municipalities exhibit lowest price sensitivity due to multi-year amortization frameworks, while retail logistics operators prioritize per-unit acquisition cost over lifecycle value.
Supply Chain Analysis
Refurbishment and battery repurposing flows are emerging as secondary value streams as fleet operators extend asset lifecycles through remanufactured drivetrain components. Lidar sensor fabrication concentrates in China, South Korea, and Germany, with solid-state scanning mechanisms drawing from semiconductor foundries in the Yangtze River Delta and Bavarian engineering clusters. Cathode material supply rests on lithium carbonate flows from Chile and Australia, exposing battery pack assembly to commodity price volatility. Distribution runs through municipal procurement frameworks in Europe and fleet-as-a-service operators in Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The driverless sweeper market operates as a cost-of-compliance arena where CE marking and SAMR certification create durable moats for incumbent OEMs with established testing infrastructure. Europe's Machinery Directive and China's GB standards collectively elevate barrier-to-entry thresholds beyond the reach of component assemblers lacking regulatory affairs capabilities.
For Market Incumbents: Deepen backward integration into solid-state lidar fabrication to secure sensor supply against South Korean and Chinese component export restrictions. Defend municipal contract tenure by embedding predictive maintenance algorithms that create switching costs for fleet operators during renewal cycles. Prioritize certification investment in SAMR electromagnetic compatibility to preempt domestic Chinese OEMs in airport apron segments. For New Entrants and Emerging Players: Enter via performance-based service contracts in Singaporean retail logistics corridors where capital constraints prevent facility managers from equipment ownership. Target aisle-width compact configurations in Japanese warehouse environments with consistent artificial lighting that reduces perception stack complexity. Pursue white-label manufacturing partnerships with European incumbents seeking capacity expansion without greenfield facility investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial equipment conglomerates seeking autonomous capabilities for broader environmental technology portfolios. Long-term viability hinges on software-defined fleet coordination platforms that transcend hardware commoditization across the projection horizon. Acquisition targets should demonstrate SLAM navigation integration with safety-critical control loops. Monitor FAA guideline evolution for autonomous ground vehicles as inflection indicator for airport segment expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Perception Stack Integration | Fusing lidar with computer vision reduces single-point-of-failure risk for insurance underwriting at scale. |
| CE Marking Acceleration Investment | Compressed certification cycles enable faster cross-border deployment for German municipal contractors. |
| Fleet-as-a-Service Platform Launch | Performance-based contracts in Singapore replace capital expenditure with uptime guarantee structures. |
| Solid-State Lidar Backward Integration | Captive sensor supply insulates against South Korean component export restrictions and lead-time extension. |
| Airport Apron Certification Pathway | FAA guideline compliance opens controlled airside environments to unmanned cleaning operations. |
Research Methodology
Multi-period observation of municipal tender awards, certification timeline compression, and fleet deployment scale anchored the trend analysis, supplemented by interviews with municipal procurement officers, autonomous vehicle software engineers, lidar component suppliers, and aftermarket service directors. Secondary validation drew from KBA type-approval filings, SAMR GB standard documentation, FAA guideline publications, and EU Machinery Directive implementation records. Bottom-up unit deployment estimates triangulated against top-down fleet operator capital expenditure disclosures.
Segment-weighting approaches distributed value projections across ride-on, compact, walk-behind, and industrial product configurations, with technology splits between lidar-dominant and computer vision-fusion architectures. End-user segmentation incorporated municipality, airport, industrial facility, and commercial space procurement patterns. CAGRs derived from logistic growth curve fitting against observed fleet penetration rates in Singapore and Germany. Industry-specific inputs included battery cycle degradation curves and SLAM navigation reliability benchmarks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption and GB standard timeline extension scenarios. Projections reflect documented assumptions regarding regulatory compliance cost trajectories and fleet operator insurance product availability. Material deviation in FAA guideline finalization or SAMR review cycle acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
United States Automotive Service Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Americas MAP Market