
 North America Automotive Logistics Market | 2026-2036
North America Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Logistics Market Outlook
Aftermarket parts fulfillment is narrowing the margin gap with OEM inbound logistics as vehicle aging fleets expand service parts demand. DHL Supply Chain leverages its cross-border Mexico-US network to dominate automotive sequencing operations near assembly plants. C.H. Robinson sustains competitive positioning through digital freight-matching platforms that reduce empty miles for tier-1 supplier routes. XPO Logistics anchors its automotive portfolio in dedicated contract carriage serving Detroit Three manufacturers across the Midwest corridor.
Automotive logistics encompasses the coordinated movement of finished vehicles, production parts, and aftermarket components through multimodal networks governed by stringent delivery windows, vehicle-specific handling protocols, and real-time visibility requirements. The discipline relies on specialized covered railcars, vehicle processing centers, and cross-dock facilities designed to prevent damage while enabling high-velocity inventory turns. Transportation services capture the dominant value share as OEMs outsource fleet ownership and route optimization to third-party providers. Warehousing segments are expanding fastest near EV battery gigafactories in Tennessee and Kentucky where temperature-controlled storage and hazmat compliance add complexity. Telematics adoption differentiates leading operators by enabling predictive delay alerts and dynamic rerouting around port congestion or weather disruptions.
The US Department of Transportation hours-of-service rules and Mexico's SCT cross-border trucking permits shape fleet utilization rates and driver availability across the NAFTA trade lane. EPA emissions standards for heavy-duty tractors push carriers toward alternative-fuel investments that alter total cost of ownership calculations for long-haul automotive routes. Stakeholders must monitor how the USMCA rules of origin enforcement reshapes supplier geography and whether rail capacity expansions at Laredo and Detroit keep pace with surging EV component volumes.
Market Dynamics
Cross-border EV battery component flows are compressing delivery windows and forcing multimodal coordination upgrades across the Michigan-Mexico corridor, as USMCA rules of origin enforcement tightens supplier qualification requirements.
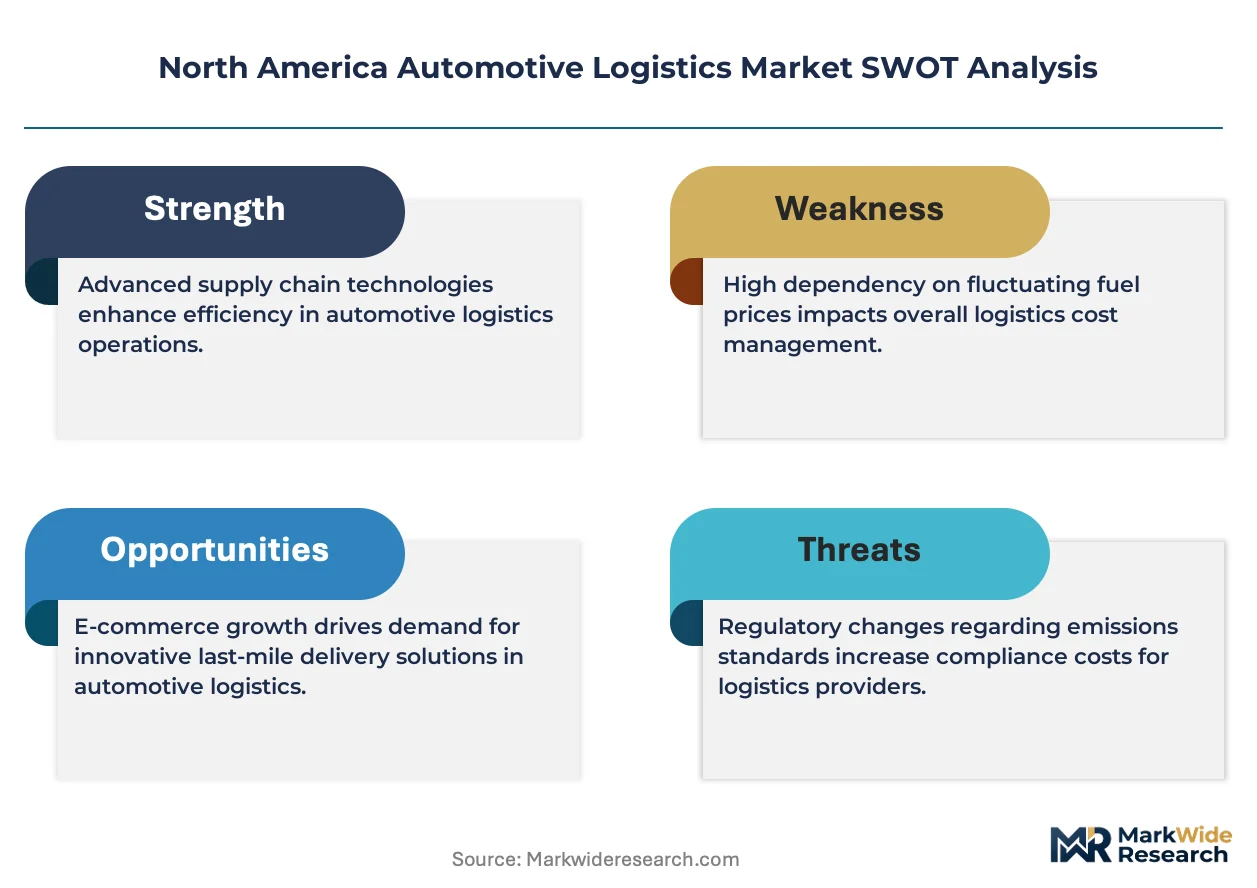
Growth Catalysts
- EPA Heavy-Duty Emissions Standards:The tightened rules accelerate fleet turnover toward alternative-fuel tractors, creating dedicated contract carriage demand for zero-emission vehicle logistics infrastructure.
- Maquiladora Supplier Density:Concentrated Mexican manufacturing clusters near the US border reduce inbound parts transit times for Detroit Three assembly plants.
- Lithium-Ion Battery Hazmat Protocols:Specialized temperature-controlled transport requirements expand value-added service margins for qualified 3PL providers serving Tennessee and Kentucky gigafactories.
Market Restraints
- Driver Hours-of-Service Constraints:US DOT regulations limit fleet utilization rates on long-haul routes between Midwest assembly plants and Mexican border crossings.
- Rail Capacity Bottlenecks:Fixed terminal infrastructure at Laredo and Detroit constrains surge capacity for EV component volume spikes.
- Cross-Border Permit Scarcity:Mexico's SCT trucking authorization delays create carrier allocation rigidities during peak production cycles.
Strategic Opportunities
- US Southeast Battery Corridor:Greenfield logistics parks near Georgia and South Carolina EV plants offer first-mover positioning for sequencing and cross-dock operations.
- Vehicle Processing Center Automation:Robotic inspection and accessorization systems reduce labor dependency at port-of-entry facilities handling Mexican-assembled vehicles.
- Aftermarket Parts Network Densification:Aging US vehicle fleets expand addressable demand for same-day service parts fulfillment from regional distribution nodes.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems require costly retrofitting to achieve real-time visibility across multi-carrier networks.
- Hazmat Certification Timelines:Driver qualification delays for lithium battery transport restrict available capacity on critical EV supply routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Logistics Market |
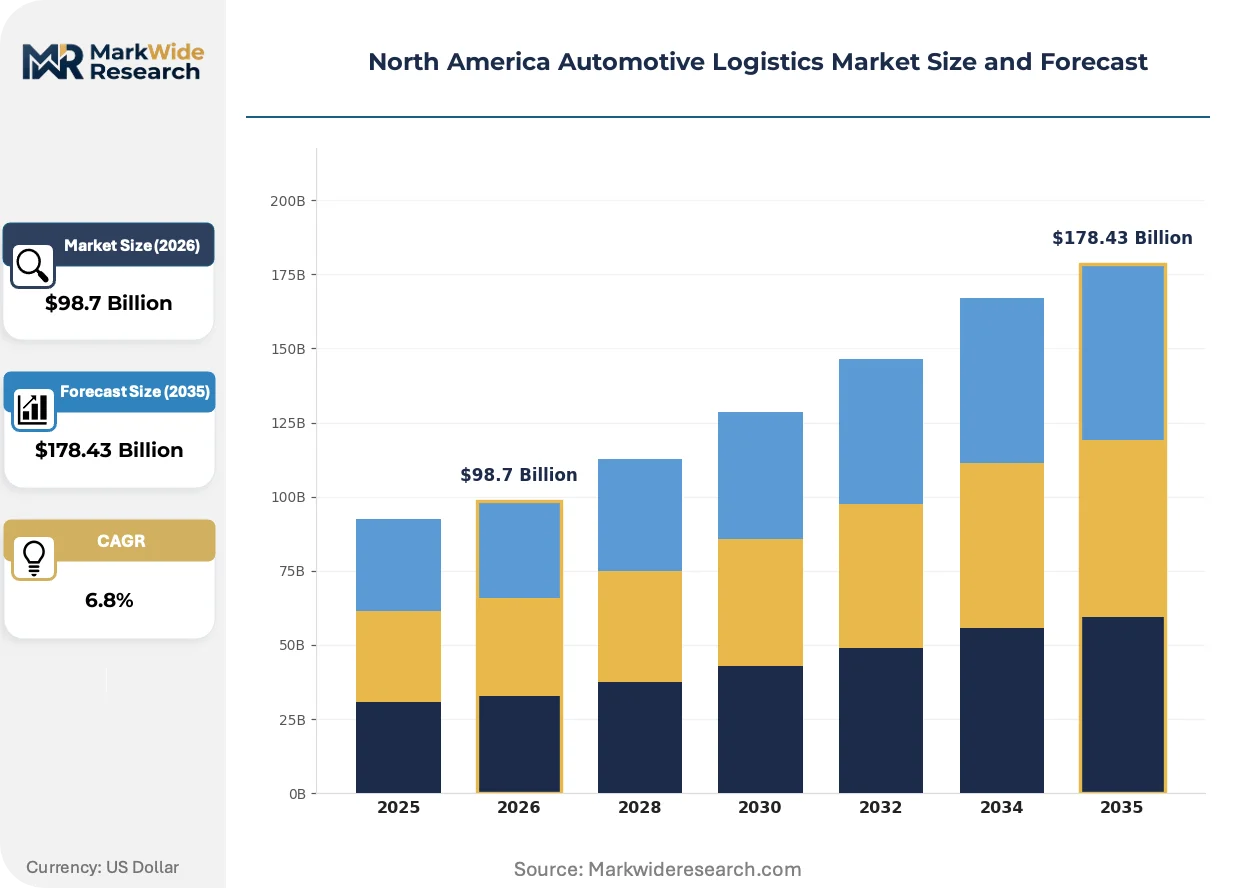
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management Customer Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Logistics Vendors Technology: Telematics, RFID, GPS Tracking, WMS Delivery Mode: Road, Rail, Sea, Air |
| Companies Covered | DHL Supply Chain, C.H. Robinson, XPO Logistics, Penske Logistics, Ryder System, Kuehne + Nagel, DB Schenker, UPS, FedEx, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Logistics Market Strategic Shifts
Digital freight-matching platforms and predictive analytics are compressing planning cycles and eliminating manual dispatch coordination across automotive supply chains.
Autonomous yard management systems are collapsing trailer dwell times at vehicle processing centers through AI-driven gate automation and robotic shuttle movements. Tier-1 suppliers near Detroit and Chattanooga are piloting these systems to meet tightened OEM delivery windows. The technology is collapsing traditional buffer inventory requirements by enabling precise arrival sequencing.
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles mandate progressive emissions reductions through 2032, forcing carriers to accelerate alternative-fuel tractor deployments. Fleet operators serving automotive routes face compressed payback period calculations for electric and hydrogen investments. The regulation most acutely affects long-haul corridors linking Midwest assembly plants to Mexican maquiladora zones, where carriers are pre-positioning charging infrastructure.
OEM procurement teams are consolidating tier-1 supplier base counts and mandating direct-to-line sequencing responsibilities, shifting inventory ownership and quality liability onto logistics providers. This model displaces traditional hub-and-spoke distribution with continuous-flow milk runs synchronized to assembly takt times. The pattern is most advanced in the cross-border Michigan-Mexico corridor, where DHL and XPO have built dedicated sequencing campuses.
North America Automotive Logistics Market Segmentation
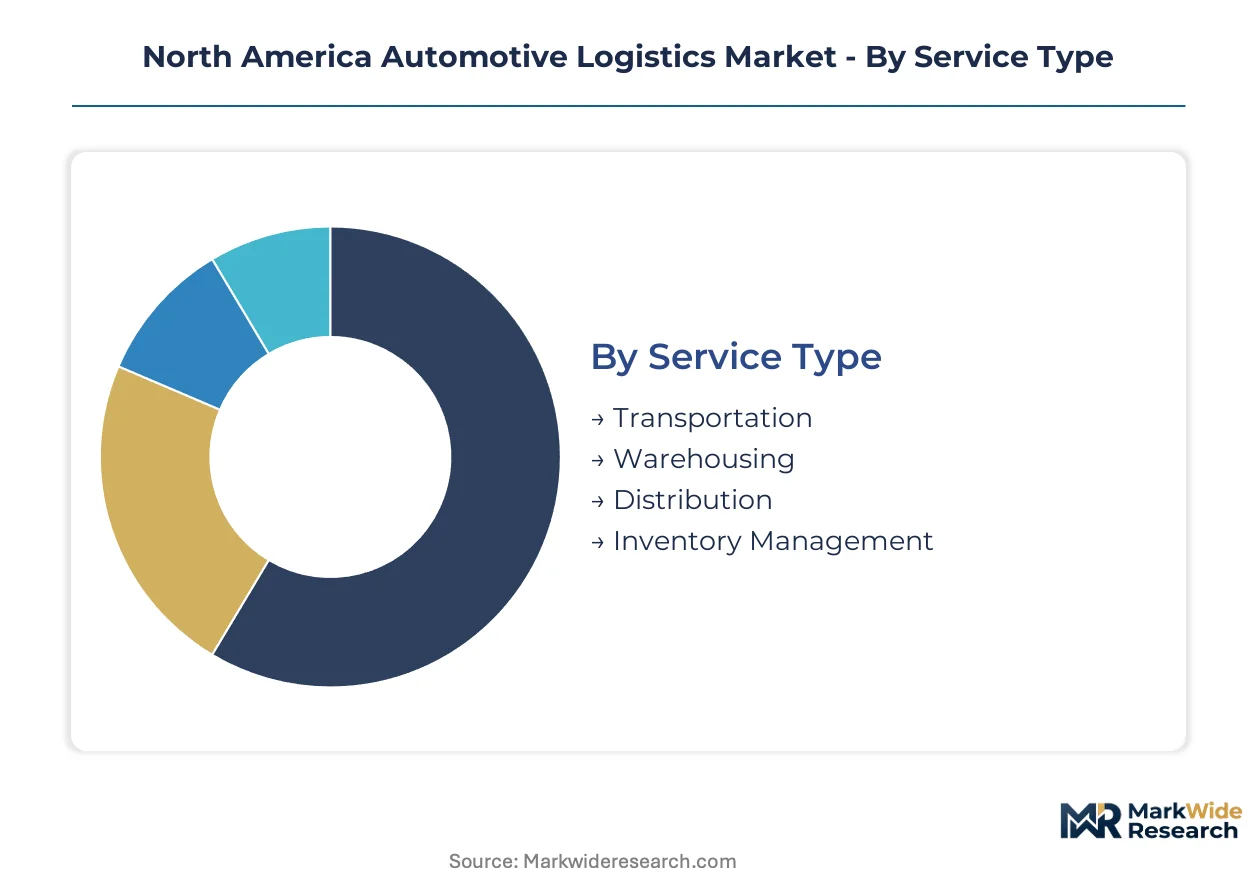
Segmentation reveals how service intensity varies sharply between production-linked flows and aftermarket fulfillment. Each dimension exposes different margin structures, capital requirements, and technology adoption patterns across the automotive supply chain.
Service Type:
After-sales-service intensity distinguishes segments by inventory velocity and handling specialization requirements.
- Transportation:Encompasses finished vehicle carriage, inbound parts hauling, and battery component logistics across multimodal networks. Demand concentrates on dedicated contract routes linking Detroit Three assembly plants to Mexican maquiladora zones, with EPA emissions standards accelerating alternative-fuel fleet investments.
- Warehousing:Temperature-controlled facilities and hazmat-compliant storage for lithium-ion batteries near Tennessee and Kentucky gigafactories. Cross-dock operations at border crossings handle sequencing for just-in-time assembly line feeds.
- Distribution:Finished vehicle delivery from port processing centers to dealer networks, plus aftermarket parts fulfillment from regional nodes serving aging US vehicle fleets.
- Inventory Management:Vendor-managed inventory systems and sequencing coordination that shifts ownership liability to logistics providers under direct-to-line OEM mandates.
Transportation holds the largest share; momentum sits with Warehousing as EV battery infrastructure expands.
Customer Type:
Cost tier stratification separates capital-intensive OEM relationships from fragmented aftermarket service models.
- OEMs:Original equipment manufacturers outsource fleet ownership and mandate direct-to-line sequencing, consolidating supplier bases and compressing delivery windows. Ford, GM, and Stellantis operations across Michigan, Ohio, and Ontario anchor contract volumes.
- Tier-1 Suppliers:Bosch, Denso, and Magna operations near Detroit and Chattanooga face compressed margins as OEMs transfer inventory ownership and quality liability.
- Aftermarket Providers:Service parts distributors addressing expanded demand from aging US vehicle parc, with same-day fulfillment requirements driving regional node densification.
- Logistics Vendors:Third-party providers including DHL, XPO, and C.H. Robinson competing on telematics integration and cross-border permit access.
OEMs hold the largest share; momentum sits with Aftermarket Providers as vehicle aging accelerates parts demand.
Technology:
Application maturity separates established tracking systems from emerging predictive platforms.
- Telematics:Real-time visibility platforms enabling predictive delay alerts and dynamic rerouting around port congestion or weather disruptions across Michigan-Mexico corridors.
- RFID:Automated identification systems for inventory tracking at vehicle processing centers and sequencing campuses.
- GPS Tracking:Location monitoring for high-value EV battery shipments and finished vehicle movements requiring theft prevention and route optimization.
- WMS:Warehouse management systems coordinating temperature-controlled storage protocols and hazmat compliance documentation for lithium-ion facilities.
Telematics holds the largest share; momentum sits with WMS as battery facility complexity escalates.
Delivery Mode:
Volume concentration and infrastructure investment levels differentiate modal economics.
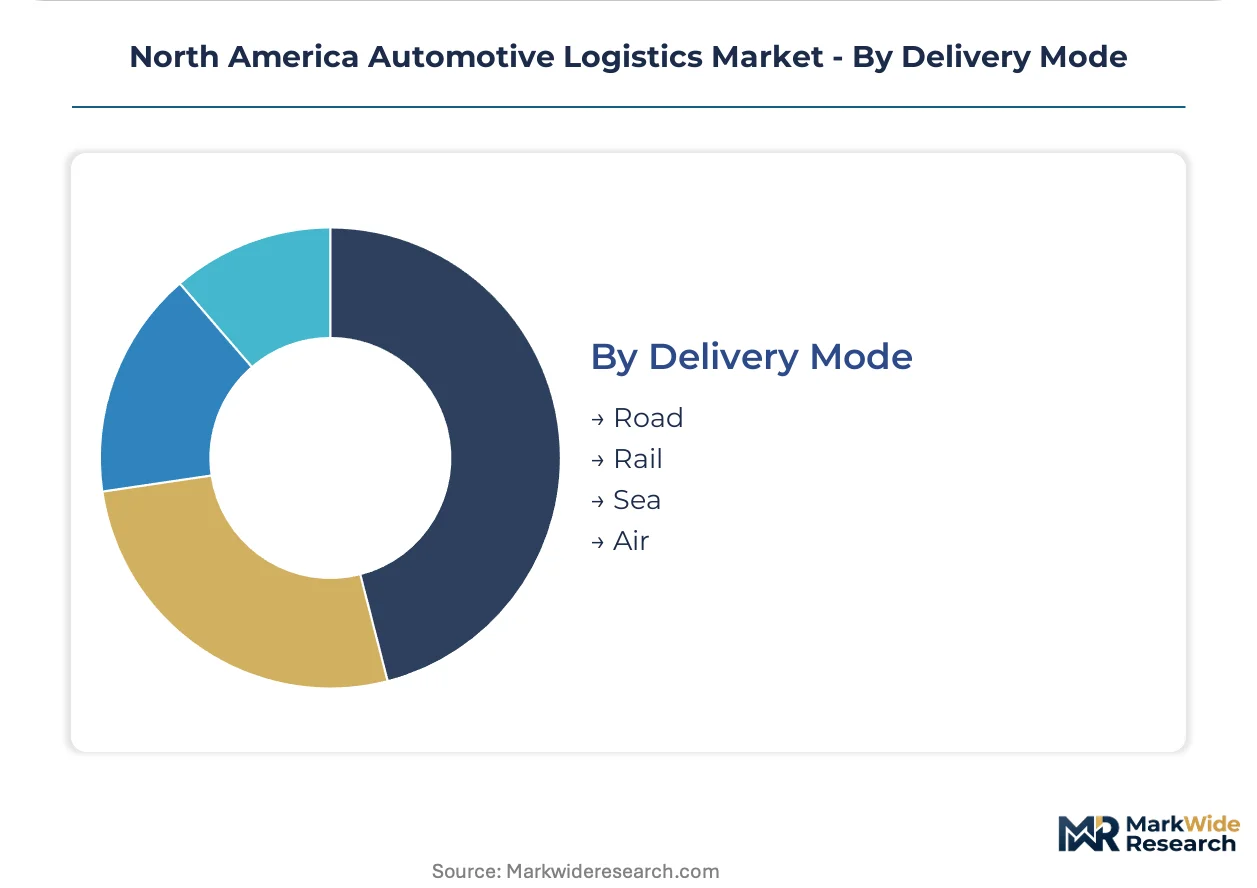
- Road:Dominant mode for cross-border parts sequencing and finished vehicle delivery, constrained by US DOT hours-of-service rules and Mexico SCT permit scarcity on peak production cycles.
- Rail:Specialized covered railcars for finished vehicle transport, with fixed terminal infrastructure at Laredo and Detroit constraining surge capacity for EV component spikes.
- Sea:Port-of-entry processing for Mexican-assembled vehicles and transoceanic parts flows, vulnerable to congestion delays requiring predictive rerouting.
- Air:Emergency parts and prototype movements for production line-down situations, premium-priced and limited to critical path exceptions.
Road holds the largest share; momentum sits with Rail as EV component volumes strain highway capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier networks cluster along the Michigan-Mexico manufacturing axis where Detroit Three assembly plants source components from border-adjacent maquiladoras. The EPA's Phase 3 heavy-duty emissions standards and USMCA rules of origin enforcement reshape fleet investment and supplier geography across this corridor.
United States
EV battery gigafactories in Tennessee and Kentucky drive specialized logistics demand for temperature-controlled hazmat transport. The EPA's tightened emissions standards for heavy-duty tractors accelerate alternative-fuel fleet turnover among contract carriers. Detroit anchors finished vehicle and inbound parts flows, while the Southeast corridor attracts greenfield sequencing campuses.
Mexico
Maquiladora clusters in Nuevo León and Tamaulipas compress inbound parts transit times for US assembly plants. Mexico's SCT cross-border trucking permits create allocation bottlenecks during peak production cycles. The Laredo-Colombia Solidarity corridor handles surge volumes of EV battery components bound for Midwest plants.
Canada
Ontario's Windsor-Oshawa automotive belt maintains integrated supply chains with Michigan assembly operations. Transport Canada harmonizes commercial vehicle regulations with US DOT standards to preserve seamless cross-border fleet utilization. The Detroit-Windsor tunnel and Blue Water Bridge constrain surge capacity for just-in-time parts movements.
North America Automotive Logistics Market Competitive Environment
Integrated 3PLs and specialized contract carriers split the market through distinct asset-light and asset-heavy positioning strategies. The vendor base concentrates around cross-border permit access and sequencing campus proximity rather than pure scale. Asset-heavy operators anchor dedicated fleet relationships with Detroit Three manufacturers, while digital freight platforms compete on empty-mile reduction for tier-1 supplier routes. Competitive moves center on telematics integration investments and USMCA-compliant cross-border infrastructure expansion.
Among integrated 3PLs, DHL Supply Chain and XPO Logistics exemplify the sequencing-campus model, occupying positions near Michigan and Southeast assembly plants where direct-to-line mandates transfer inventory liability from OEMs. C.H. Robinson represents the platform-centric archetype, leveraging digital freight-matching to reduce empty miles on tier-1 supplier routes without fixed asset ownership.
| Leading Market Players |
|---|
| DHL Supply Chain |
| C.H. Robinson |
| XPO Logistics |
| Penske Logistics |
| Ryder System |
| Kuehne + Nagel |
| DB Schenker |
| UPS |
| FedEx |
| Others |
Value Chain & Pricing Dynamics
USMCA rules of origin enforcement uncertainty determines both pricing tier spreads and supply chain shape as carriers and 3PLs recalibrate cross-border service premiums against supplier relocation costs.
Pricing Analysis
EPA Phase 3 heavy-duty emissions standards dictate the pricing tier structure across contract carriage segments. Three-tier pricing structure across premium, standard, and economy levels separates zero-emission fleet operators from conventional diesel carriers and spot-market independents. Price differentiation rests on hazmat certification depth and cross-border permit access. Cost compression in the standard tier is intensifying because OEMs are consolidating supplier bases and transferring inventory liability to logistics providers. Tier-1 suppliers exhibit highest price sensitivity due to compressed margins under direct-to-line mandates, while OEMs prioritize reliability over rate negotiation.
Supply Chain Analysis
Extended payment terms from Detroit Three manufacturers to tier-1 suppliers cascade through carrier networks, squeezing working capital for mid-size fleet operators. Geographic supply concentrates in Mexico, the United States, and Canada across the integrated North American production corridor. Raw material dependencies center on lithium carbonate, cobalt sulfate, and rare-earth magnets for EV powertrain components. Single-source vulnerability permeates the cross-border battery component lane where qualified hazmat carriers remain scarce. Distribution runs through dedicated contract routes linking maquiladora clusters to Midwest assembly plants, with rail intermodal providing surge capacity during peak production cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American automotive logistics sits at an early-cycle expansion phase as EV production penetration accelerates demand for specialized battery transport infrastructure and sequencing campus development.
For Market Incumbents: Entrench cross-border permit portfolios and sequencing campus proximity as defensive moats against digital freight platforms. Deepen backward integration into temperature-controlled trailer fleets serving Tennessee and Kentucky battery corridors. Prioritize telematics retrofit investments to meet OEM real-time visibility mandates.
For New Entrants and Emerging Players: Aftermarket parts fulfillment networks in secondary US metropolitan markets represent the most penetrable entry point given aging vehicle parc density and same-day service gaps. Autonomous yard management systems at vehicle processing centers offer technology-led differentiation without fixed route assets. Partner with regional parts distributors for last-mile density rather than competing head-to-head with integrated 3PLs on OEM contract carriage.
For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors asset-heavy operators with USMCA-compliant cross-border infrastructure and hazmat-certified fleet capacity. Long-term viability hinges on positioning ahead of EPA emissions compliance deadlines and EV production ramp schedules. Monitor SCT permit allocation policy shifts as the critical inflection signal for carrier capacity availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Conversion | EPA Phase 3 compliance mandates alternative-fuel tractor deployment across Michigan-Mexico corridors. |
| Cross-Border Sequencing Campus Expansion | Direct-to-line OEM mandates transfer inventory liability to 3PLs near Detroit and Chattanooga assembly plants. |
| Hazmat Certification Pipeline Investment | Qualified driver scarcity for lithium-ion transport constrains EV battery supply chain capacity. |
| Autonomous Yard Management Deployment | AI-driven gate automation collapses trailer dwell times at vehicle processing centers. |
| Aftermarket Parts Network Densification | Aging US vehicle fleets expand addressable demand for same-day service parts fulfillment. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, contract carrier fleet managers, and aftermarket distribution executives anchored the qualitative base. Primary interview insights combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA regulatory filings, and USMCA compliance documentation. Bottom-up service line modeling and top-down corridor demand estimation provided cross-check triangulation.
Scenario-bracketing around EPA emissions implementation timing and EV production ramp rates bounded the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer tier, technology application, and delivery mode. CAGRs derived from production volume forecasts, content-per-vehicle logistics intensity assumptions, and modal shift elasticity parameters. Battery supply chain flows and cross-border trade corridor utilization served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, diesel price volatility, or US-Mexico trade policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and OEM outsourcing patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market