
 Electric Vehicle Repair Service Market | 2026-2036
Electric Vehicle Repair Service Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Repair Service Market Foresight
Aftermarket service revenue is rewriting profit allocation across the automotive value chain as OEMs capture recurring revenue streams previously lost to independent garages. Tesla Service Center dominates proprietary diagnostic access and over-the-air update revenue pools. Robert Bosch leverages its global parts distribution network to supply independent repair shops with EV-compatible components. BMW anchors premium positioning through certified technician programs and specialized battery handling equipment.
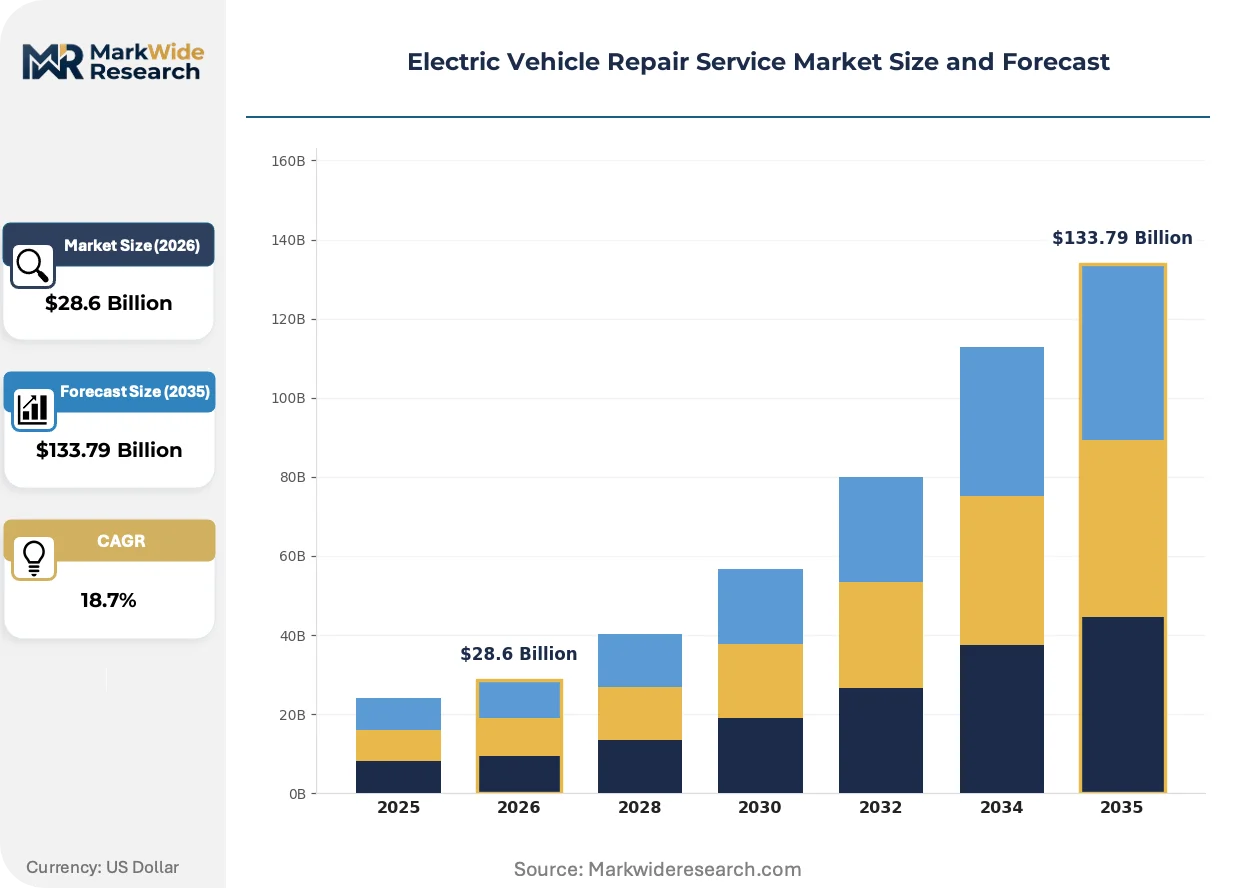
An electric vehicle repair service encompasses the maintenance, diagnostic, and restoration of battery-electric and plug-in hybrid vehicles, requiring high-voltage safety certification, thermal management expertise, and software calibration capabilities for systems operating at 400-800 volts. Its primary commercial purpose is to extend vehicle operational life, ensure safety compliance, and minimize downtime for electrified fleets and individual owners. Battery replacement commands the largest share of service value given cell degradation curves and warranty complexity, while software update services represent the fastest-expanding margin pool as automakers monetize feature activation and cybersecurity patches. Fleet operators constitute the most concentrated demand segment due to centralized procurement, volume scheduling, and total cost of ownership optimization requirements.
The US National Highway Traffic Safety Administration enforces repair data access rules under the REPAIR Act, while the EPA administers battery recycling standards through emerging hazardous waste frameworks; the EU's F-Gas Regulation and Battery Regulation mandate refrigerant handling protocols and recycled content thresholds that reshape workshop equipment investments. China's MIIT sets national EV service technician certification standards and GB technical specifications for high-voltage operations. Stakeholders must monitor regulatory divergence on data ownership and right-to-repair provisions, as these will determine whether independent shops gain diagnostic parity with captive OEM networks or face structural exclusion from profitable service categories.
Market Dynamics
Fleet electrification mandates are compressing maintenance cycles and forcing service providers to absorb 400-800 volt high-voltage safety protocols at scale. The collision of proprietary OEM diagnostic architectures with right-to-repair regulatory pressure is fragmenting profit pools between captive networks and independent shops.
Growth Catalysts
- California's Advanced Clean Trucks rule:Commercial operators must electrify heavy-duty fleets by 2036, creating concentrated demand for preventive maintenance contracts and battery health monitoring systems.
- Shanghai's procurement bias:Government fleet tenders now require domestic-certified service infrastructure, accelerating workshop upgrades across China's eastern coastal corridor.
- Thermal management expertise:Liquid-cooled battery architectures demand specialized coolant handling and fire suppression capabilities that command premium labor rates.
Market Restraints
- Lithium supply concentration:Cell manufacturing clusters in Sichuan and Qinghai provinces create geographic vulnerability for replacement battery availability and pricing volatility.
- Proprietary diagnostic access:Tesla Service Center maintains exclusive over-the-air calibration tools that independent garages cannot replicate without violating software licensing terms.
- High-voltage safety equipment:Insulated tool sets, arc-flash protection, and Class 0 electrical gloves require capital outlays that strain single-location repair shops.
Strategic Opportunities
- India's BIS certification pathway:The Bureau of Indian Standards is drafting EV technician competency frameworks that first-movers can shape before mandatory rollout.
- Second-life battery refurbishment:Degraded automotive cells retain capacity for stationary storage, creating circular economy revenue streams for workshops with cell-testing infrastructure.
- Mobile service vans:Fleets in Germany's industrial corridors are contracting on-site maintenance to minimize vehicle downtime and depot congestion.
Industry Challenges
- High-voltage safety certification timelines:Germany's KBA and France's CNIL maintain divergent training hour requirements that complicate cross-border technician mobility.
- Software-hardware integration complexity:Battery management system firmware updates must synchronize with vehicle control modules, requiring diagnostic platforms that bridge multiple OEM protocols.
- Legacy ICE skill displacement:Internal combustion engine specialists face retraining costs and wage compression during the transition period.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Repair Service Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $133.79 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Battery Replacement, Collision Repair, Software Update, Brake Service End User: Fleet Operators, Private Vehicle Owners, Ride-Sharing Services, Corporate Fleets Technology: Charging Hardware, Diagnostic Tools, Repair Equipment, Software Platforms Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses |
| Companies Covered | Mercedes-Benz, Volkswagen, Tesla Service Center, Hyundai Motor, Toyota Motor, Robert Bosch, BMW, BYD, LKQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Repair Service Market Shifts & Advancements
Diagnostic technology is collapsing the boundary between physical repair and remote software intervention, redistributing value from labor hours to data-enabled subscriptions. This shift is compressing traditional garage revenue models while opening margin pools for cybersecurity and predictive analytics.
Over-the-air update infrastructure is collapsing the distinction between maintenance and feature commerce, enabling automakers to monetize range extensions and performance unlocks remotely. Fleet operators in California's Central Valley are adopting subscription-based battery health monitoring that replaces scheduled physical inspections. The structural consequence is collapsing independent shops' access to recurring revenue streams previously tied to oil changes and brake pad replacements.
The EU's F-Gas Regulation mandates refrigerant recovery equipment and technician certification for heat pump thermal management systems, forcing workshop capital allocation toward climate-controlled storage and leak detection hardware. Germany's KBA has aligned national implementation with the EU Battery Regulation's recycled content thresholds, affecting how service centers handle end-of-life cells. Workshops in Stuttgart's manufacturing corridor are responding by partnering with certified recyclers to secure material traceability documentation.
Fleet procurement departments are unbundling service contracts from vehicle acquisition, creating transparent benchmark pricing for battery replacement and thermal system maintenance. Third-party service aggregators in the Netherlands are displacing OEM captive networks for routine maintenance among municipal bus operators. This pattern is most visible in Rotterdam's port logistics cluster, where electrified drayage truck fleets have consolidated vendor relationships to three independent providers with specialized high-voltage capabilities.
Electric Vehicle Repair Service Market Segmentation
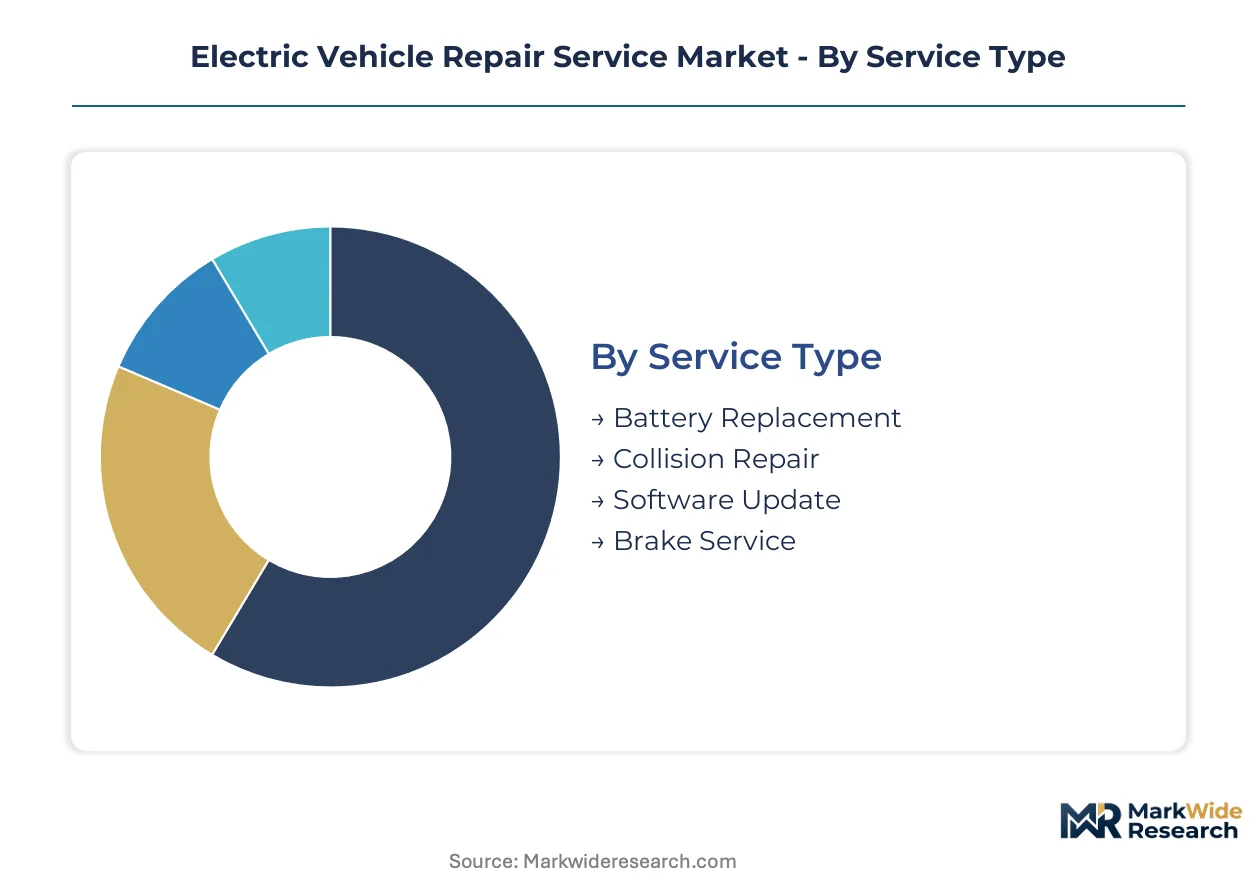
Segmentation in the electric vehicle repair service market determines capital allocation for high-voltage safety infrastructure and technician certification pathways. Service providers must align workshop capabilities with specific voltage architectures and end-use operational intensity.
Service Type:
Use cases span from scheduled preventive maintenance to catastrophic failure recovery, each demanding distinct equipment certification and labor skill profiles.
- Battery Replacement:Cell module extraction and pack reassembly require thermal runaway containment protocols and nitrogen inerting systems. Fleet operators in California's Central Valley are consolidating procurement for battery health monitoring to optimize replacement timing and minimize downtime.
- Collision Repair:Structural aluminum welding and high-voltage system isolation dominate post-accident restoration workflows. Certified shops in Germany's KBA network command premium labor rates for arc-flash protection compliance and specialized frame straightening equipment.
- Software Update:Over-the-air calibration and cybersecurity patch deployment redistribute value from physical labor to subscription revenue models.
- Brake Service:Regenerative braking system integration with friction components requires electronic parking brake recalibration tools.
Established volume favors battery replacement; emerging adoption favors software update services.
End User:
Customer concentration shapes scheduling predictability and contract pricing power across the service network.
- Fleet Operators:Centralized procurement and volume-based maintenance contracts enable total cost of ownership optimization through predictive analytics platforms. Municipal bus operators in Rotterdam's port logistics cluster have consolidated vendor relationships to three independent providers with specialized high-voltage capabilities.
- Corporate Fleets:Sustainability reporting requirements drive transparent service documentation and carbon footprint tracking for maintenance activities.
- Private Vehicle Owners:Warranty dependency and convenience proximity determine shop selection for routine service intervals.
- Ride-Sharing Services:High utilization rates compress maintenance cycles and prioritize rapid turnaround over cost minimization.
Contract concentration favors fleet operators; margin expansion favors corporate fleets.
Technology:
Equipment categories reflect the collision between physical repair tooling and digital diagnostic infrastructure.
- Diagnostic Tools:Proprietary OEM scan tools and open-protocol aftermarket platforms compete for workshop capital allocation. Tesla Service Center maintains exclusive over-the-air calibration access that independent garages cannot replicate without software licensing violations.
- Repair Equipment:Insulated tool sets, lift tables with high-voltage isolation, and battery handling cranes constitute mandatory workshop investments.
- Charging Hardware:On-site DC fast charging installation enables depot-based maintenance without range anxiety during service completion.
- Software Platforms:Predictive maintenance algorithms and fleet management integration command recurring subscription revenue.
Capital intensity favors diagnostic tools; recurring revenue expansion favors software platforms.
Vehicle Type:
Platform voltage and thermal architecture complexity stratify service capability requirements across mobility segments.
- Commercial Vehicles:800-volt architectures and liquid-cooled battery packs demand specialized coolant handling and fire suppression infrastructure. California's Advanced Clean Trucks rule is compressing maintenance cycles for heavy-duty electrified fleets.
- Buses:Depot-based charging infrastructure and centralized fleet management enable scheduled preventive maintenance at scale.
- Passenger Cars:Volume density in China's eastern coastal cities supports BYD and NIO service network specialization.
- Two-Wheelers:Swappable battery architectures reduce on-vehicle service requirements while shifting value to exchange station maintenance.
Service value concentration favors commercial vehicles; volume scaling favors passenger cars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes EV repair services through dense domestic service networks, while the United States channels demand through fragmented independent shops and captive OEM centers. Germany prioritizes certified technician pathways and thermal management specialization. Fleet electrification mandates in California and procurement biases in Shanghai reshape geographic service infrastructure investments.
United States
Fleet operators in California's Central Valley are consolidating preventive maintenance contracts for heavy-duty electrified trucks under the state's Advanced Clean Trucks rule. The EPA tailpipe regulations and NHTSA repair data access rules under the REPAIR Act pressure service providers toward high-voltage safety certification. Los Angeles and San Francisco anchor the densest concentration of certified EV repair facilities.
China
BYD and NIO operate dense service networks across Shanghai and the eastern coastal corridor where government procurement mandates domestic-certified infrastructure. The MIIT sets national EV service technician certification standards and GB technical specifications for high-voltage operations. Shenzhen and Hangzhou host the largest concentration of battery replacement and thermal management service centers.
Germany
The KBA enforces divergent training hour requirements for high-voltage safety certification that complicate cross-border technician mobility within the EU. The EU F-Gas Regulation and Battery Regulation mandate refrigerant handling protocols and recycled content thresholds for workshop equipment. Stuttgart's manufacturing corridor workshops partner with certified recyclers to secure material traceability documentation.
India
The Bureau of Indian Standards is drafting EV technician competency frameworks that first-movers can shape before mandatory rollout. Central government PLI scheme incentives for electric mobility accelerate fleet operator demand for preventive maintenance contracts. Maharashtra and Gujarat host emerging service clusters around automotive manufacturing hubs in Pune and Ahmedabad.
Japan
METI coordinates national standards for battery recycling and thermal management system maintenance across the archipelago. The country's national automotive regulator enforces strict high-voltage safety protocols for workshop certification. The Kanto region around Tokyo and the Chubu region around Nagoya concentrate the largest certified EV service networks.
Electric Vehicle Repair Service Market Competitive Landscape
Capability concentration sits with OEM-captive networks holding proprietary diagnostic access; scale advantage sits with independent parts distributors and multi-brand service aggregators. The market structures around three tiers: automaker-owned service centers controlling software-calibration revenue, independent high-voltage specialists capturing fleet contracts, and legacy parts distributors retrofitting for EV-compatible components. Dominant competitive moves include strategic partnerships between battery recyclers and service networks, plus geographic expansion of certified technician training programs.
Within the OEM-captive tier, Tesla Service Center and Mercedes-Benz exemplify proprietary diagnostic control and over-the-air update revenue capture. Robert Bosch occupies a position bridging independent repair shops with EV-compatible component distribution through its global parts network. These three anchors represent divergent strategic archetypes: software-lockout monetization, premium certified-service positioning, and open-ecosystem parts supply.
| Leading Market Players |
|---|
| Mercedes-Benz |
| Volkswagen |
| Tesla Service Center |
| Hyundai Motor |
| Toyota Motor |
| Robert Bosch |
| BMW |
| BYD |
| LKQ Corporation |
| Others |
Supply & Pricing Matrix
Workshop capacity underutilization in Germany's KBA-certified network is forcing independent service providers to absorb high-voltage equipment depreciation across thinner transaction volumes, compressing labor rate premiums while OEM-captive centers capture software-calibration subscription revenue.
Pricing Analysis
Long-term preventive maintenance contracts dominate fleet procurement, with municipal operators in California's Central Valley locking in multi-year battery health monitoring agreements. Three-tier pricing structure across OEM-certified, independent high-voltage specialist, and legacy garage retrofit levels reflects certification grade divergence and thermal management capability. Cost compression in the independent tier is intensifying because proprietary diagnostic access restrictions limit margin expansion. Fleet operators exhibit lowest price sensitivity due to total cost of ownership optimization requirements, while private vehicle owners drive hardest bargaining on out-of-warranty repairs.
Supply Chain Analysis
Cell manufacturing feedstock concentrates in China's Sichuan and Qinghai provinces, with South Korea and Japan anchoring cathode active material refining. Replacement battery availability draws from these three production clusters, while insulated tool sets and arc-flash protection equipment sources from Germany and the United States. Single-source vulnerability around lithium carbonate processing creates geographic concentration risk for North American and European workshops. Distribution runs through automaker captive networks for proprietary components and open-ecosystem parts distributors for standardized high-voltage hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as fleet electrification mandates compress maintenance cycles and force capital deployment into certified technician pipelines.
For Market Incumbents: Insulate proprietary diagnostic revenue streams by deepening software-lockout architectures before right-to-repair regulatory pressure forces data access parity. Accelerate backward integration into battery refurbishment capabilities to capture circular economy value pools emerging from second-life cell applications.
For New Entrants and Emerging Players: India's BIS certification pathway offers underpenetrated white-space before mandatory technician competency frameworks take effect. Target mobile service van deployments for Germany's industrial corridors where on-site maintenance contracts minimize fleet downtime. Pursue fleet operator direct procurement relationships rather than OEM channel dependency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software platform providers with predictive maintenance algorithm subscriptions. Long-term viability favors acquisition targets with certified high-voltage training infrastructure and established recycler partnerships for material traceability documentation. Watch for inflection when independent shop consolidation accelerates in response to divergent national certification hour requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Certification Program Expansion | KBA and MIIT alignment on technician mobility standards reduces cross-border operational friction for multi-national service networks. |
| Battery Refurbishment Infrastructure Investment | EU Battery Regulation recycled content thresholds create captive supply of traceable cells for stationary storage applications. |
| Mobile Service Van Fleet Deployment | Rotterdam's port logistics cluster demonstrates demand concentration for on-site thermal system maintenance without depot congestion. |
| Software Platform Integration Partnership | Predictive maintenance algorithms from fleet management systems command recurring subscription revenue independent of physical labor. |
| Recycling Network Vertical Integration | Stuttgart's manufacturing corridor workshops secure material traceability documentation through certified recycler partnerships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and vehicle production databases. Conversations with fleet procurement managers, high-voltage safety trainers, aftermarket parts distributors, and OEM service operations heads informed demand-side segmentation. Bottom-up technician certification capacity estimates triangulate against top-down fleet electrification mandate timelines across the analysis window.
Forecast inputs include service type segmentation, voltage architecture evolution, and regional regulatory divergence on right-to-repair provisions. Modeled dimensions span vehicle class, propulsion architecture, end-user concentration, and certification tier. CAGRs derive from installed base projections and service interval compression factors specific to thermal management system complexity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery recyclers or software platform entrants would shift outcomes. Cross-checking against NHTSA repair data access rule implementation timelines and MIIT certification standard revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Vehicles for Disabled Market
Automotive Services
Singapore Car Rental Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Car Vending Machine Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Automotive Retail Market
Automotive Services
US Car Wash Services Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Global Car Wash Market
Automotive Services
Mobility Scooters Market
Automotive Services
Cab Services Market
Automotive Services
GCC Car Rental Market