
 North America Limestone Market | 2026-2036
North America Limestone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Limestone Market Intelligence
High-calcium specification upgrades are redrawing competitive boundaries in the North America limestone market. Carmeuse leverages its captive quarry network to sustain supply security for steel and chemical customers across the Great Lakes. Graymont Limited anchors western production through integrated kilns in British Columbia and the US Mountain West. Mississippi Lime Company differentiates via specialized high-purity grades for pharmaceutical and food-grade applications.
North America limestone comprises sedimentary carbonate rock containing minimum 50% calcium carbonate by weight, typically processed through calcination, pulverization, or wet grinding to achieve specified particle distributions and reactivity indices for industrial use. Crushed limestone dominates volume flows into cement production and road base construction, where scale economies compress margins and favor quarry-to-plant logistics integration. Chemical limestone commands premium positioning in glass manufacturing and environmental flue gas treatment, while dolomitic limestone retains structural importance in agriculture and specialty metallurgy where magnesium content delivers functional value.
OSHA workplace exposure limits and EPA National Ambient Air Quality Standards constrain quarry expansion timelines and mandate dust suppression investments across US operations. Health Canada and provincial regulators enforce parallel standards in Ontario and Quebec, creating cross-border compliance complexity for integrated producers like Lhoist Group and Holcim Limited. Stakeholders must monitor evolving carbon border adjustment mechanisms and state-level low-carbon procurement rules that will reconfigure competitive access to public infrastructure contracts.
Market Dynamics
EPA National Ambient Air Quality Standards are compressing quarry expansion timelines across the United States, forcing capital reallocation toward dust suppression and emission control infrastructure while simultaneously elevating compliance costs for smaller operators.
Growth Catalysts
- Low-carbon cement mandates:State-level procurement rules in California and New York prioritize low-carbon clinker alternatives, pulling high-calcium limestone into Portland cement substitution formulations.
- Flue gas desulfurization retrofits:Coal-fired power plants across the Ohio River Valley require chemical-grade limestone for scrubber upgrades under Clean Air Act enforcement.
- Permian Basin drilling intensity:Oilfield demand for proppant-grade limestone in hydraulic fracturing operations concentrates procurement in the Texas-Louisiana Gulf Coast corridor.
Market Restraints
- Diesel price volatility:Quarry extraction and over-the-road haulage depend on diesel input costs that fluctuate with crude oil markets, squeezing margin predictability for crushed stone producers.
- Permitting concentration risk:Ontario and Quebec provincial regulators enforce parallel air quality standards to EPA rules, creating cross-border compliance complexity for integrated Great Lakes operators.
- Slag substitution in steel:Electric arc furnace operators substitute ground granulated blast furnace slag for limestone flux in secondary steelmaking, eroding volume in traditional metallurgical applications.
Strategic Opportunities
- Carbon capture utilization:Mineral carbonation processes using waste limestone fines offer revenue streams from CO2 sequestration credits under emerging state-level carbon accounting frameworks.
- Food-grade purity vertical:Pharmaceutical and nutritional supplement manufacturers seek ultra-high-purity calcium carbonate with certified heavy metal limits below standard industrial grades.
- Rail-served distribution hubs:Unit train loading facilities on BNSF and Union Pacific corridors enable 500-mile radius delivery to inland construction markets without diesel price exposure.
Industry Challenges
- Geotechnical engineering talent scarcity:Quarry planning and slope stability analysis require specialized mining engineers whose training pipelines have narrowed as petroleum engineering programs expanded.
- Legacy kiln refractory integration:Vertical shaft lime kiln operators face capital-intensive rebuild cycles when transitioning to higher-temperature operational profiles required for specialty chemical grades.
- OSHA silica compliance timelines:Respirable crystalline silica monitoring and engineering control implementation demand 18-24 month facility modification schedules that delay capacity ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Limestone Market |
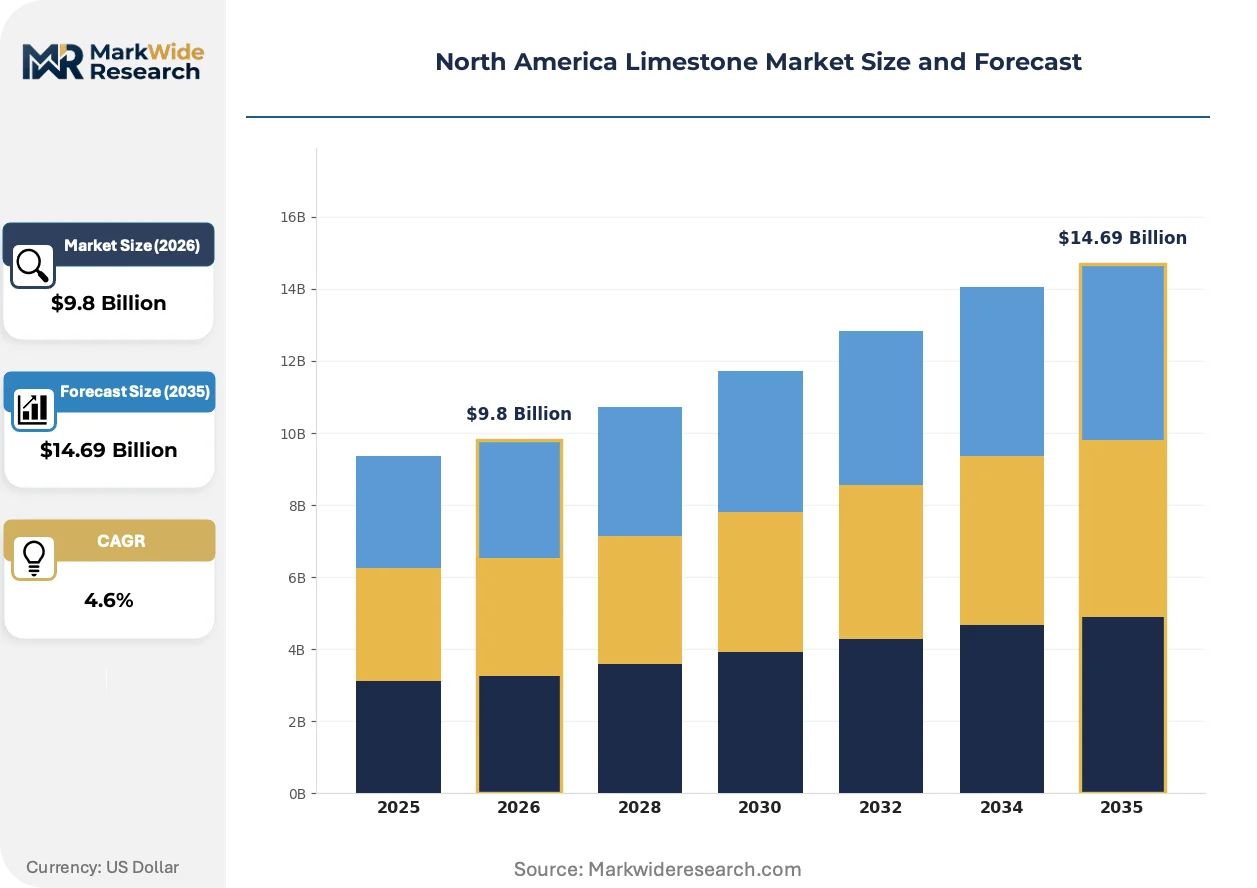
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Limestone, Chemical Limestone, High-Calcium Limestone, Dolomitic Limestone End Use Industry: Cement Production, Construction, Glass Manufacturing, Agriculture Supplier Type: Quarries, Distributors, Online Retailers, Direct Manufacturers Size: Small-Scale, Medium-Scale, Large-Scale, Extra-Large |
| Companies Covered | Holcim Limited, United States Lime & Minerals Inc., Carmeuse, Mississippi Lime Company, Imerys, Graymont Limited, CEMEX, Mineral Technologies Inc., Lhoist Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Limestone Market Strategic Shifts & Innovations
Calcination technology and emission control systems are converging to redefine operational economics for North American limestone processors. Three developments are compressing legacy cost structures while opening premium product categories.
Flash calcination using suspension preheaters is supplanting traditional rotary kiln configurations in new capacity installations. Cement and lime producers in the US Mountain West adopt this technology for 30% thermal efficiency gains. The shift is compressing fuel cost differentials between coastal and interior production locations.
EPA's evolving New Source Performance Standards for greenhouse gas emissions from industrial kilns are mandating carbon capture readiness in permit applications. Greenfield projects in Texas and Louisiana now incorporate amine scrubber infrastructure footprints. Chemical-grade limestone producers with captive CO2 offtake agreements gain preferential financing terms.
Long-term offtake contracting is displacing spot market procurement for high-volume construction customers. Ready-mix concrete and asphalt paving contractors in the Southeast are locking in 36-60 month supply agreements with fixed escalators. This behavior concentrates purchasing power among national aggregates distributors with multi-quarry networks.
North America Limestone Market Segmentation
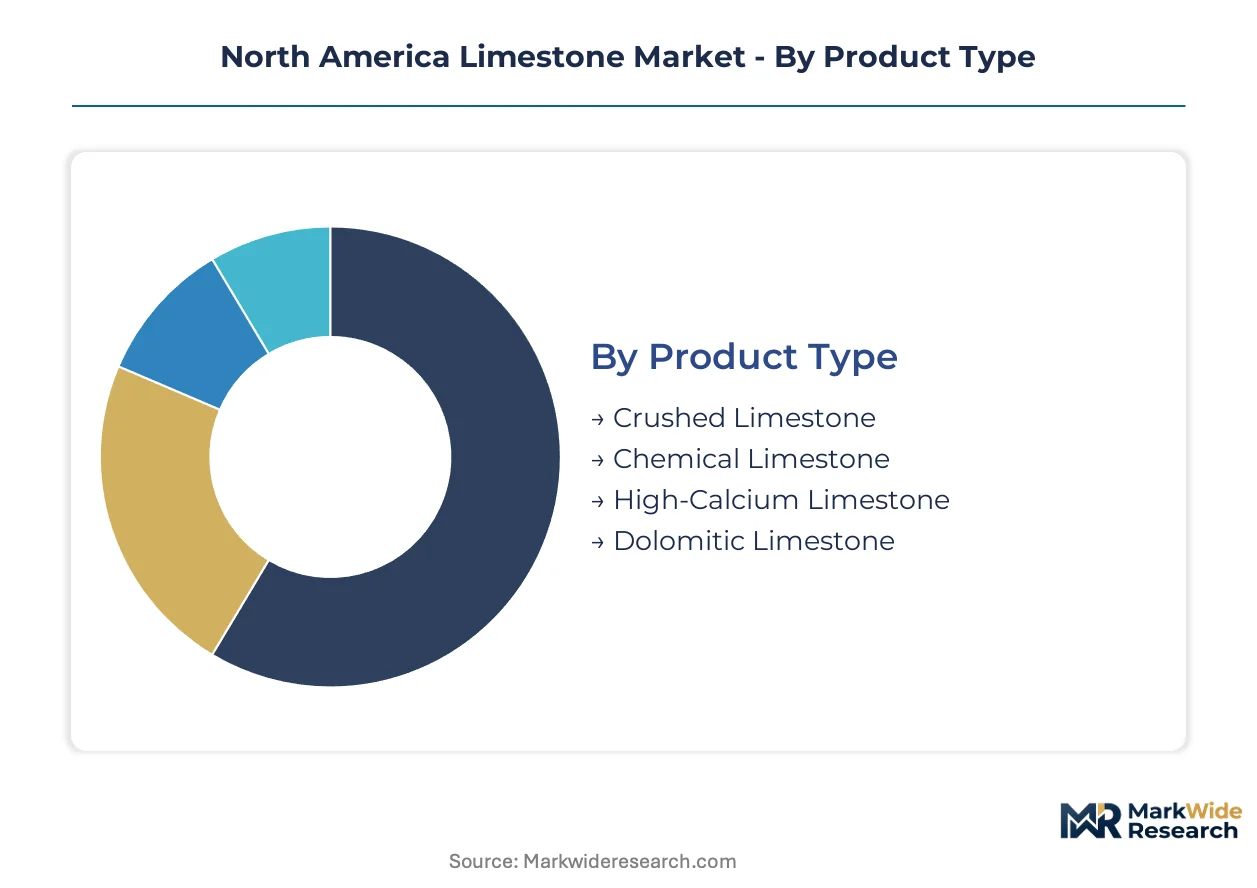
Product specifications and delivery channels in the North America limestone market diverge sharply by calcium purity, particle size, and reactivity requirements. Cement producers demand bulk crushed material via rail and barge, while pharmaceutical and food-grade buyers require certified chemical limestone through specialized distributors.
Product Type:
Channel flows split between high-volume construction material moving through quarry-direct rail contracts and specialty grades circulating through chemical distributors with certified handling protocols.
- Crushed Limestone:Coarse aggregate processed to specified gradations for concrete and asphalt applications dominates tonnage flows. Texas and Louisiana Gulf Coast cement plants and road contractors pull the majority through unit train and barge terminals. Diesel price volatility compresses margins for truck-dependent regional suppliers.
- Chemical Limestone:High-purity calcium carbonate meeting ASTM C911 specifications for flue gas desulfurization and glass melting furnaces. Ohio River Valley power plant scrubber retrofits under Clean Air Act enforcement concentrate procurement. EPA emission standards mandate consistent reactivity indices that favor vertically integrated producers with captive kiln control.
- High-Calcium Limestone:Minimum 95% CaCO3 content for specialty metallurgy and chemical manufacturing. Steel mini-mills in the Great Lakes region specify this grade for flux applications where slag chemistry tolerances are tight.
- Dolomitic Limestone:Magnesium carbonate content between 5-20% delivers soil pH buffering with added magnesium nutrition. Agricultural distributors across the US Corn Belt and Canadian Prairie provinces stock this variety for row crop applications.
By volume, Crushed Limestone leads. By growth pace, Chemical Limestone is climbing the fastest.
End Use Industry:
Cost tier stratification separates commodity construction material from premium chemical and food-grade specifications with certified impurity limits.
- Cement Production:Portland cement manufacturers consume the largest limestone tonnage as calcium feedstock for clinker kilns. California and New York state procurement rules now prioritize low-carbon clinker alternatives, pulling high-calcium limestone into supplementary cementitious material formulations. Carmeuse and Graymont have expanded Great Lakes capacity to serve this shifting specification demand.
- Construction:Road base, concrete aggregate, and rip-rap applications specify crushed limestone by ASTM C33 and AASHTO M147 gradations. The Southeast ready-mix market has shifted toward 36-60 month supply agreements with fixed escalators, concentrating purchasing power among multi-quarry distributors.
- Glass Manufacturing:Soda-lime glass furnaces require low-iron chemical limestone to prevent color contamination. Container glass plants in Ohio and Pennsylvania source through long-term contracts with specified silica and alumina limits.
- Agriculture:Soil amendment applications favor dolomitic limestone for magnesium-deficient soils in the Corn Belt and calcium limestone for eastern US pastures with lower magnesium requirements. Seasonal demand peaks drive short-term pricing volatility.
Cement Production anchors volume. Construction is expanding most quickly as infrastructure spending accelerates.
Supplier Type:
Customer type determines channel selection — national accounts with predictable volume favor direct manufacturer relationships, while fragmented agricultural and small construction buyers route through distributor networks.
- Quarries:Captive extraction sites with integrated crushing and screening capacity serve cement and asphalt plants within 100-mile truck haul radius. Rail-served quarry terminals on BNSF and Union Pacific corridors extend market reach to 500-mile inland construction zones.
- Distributors:Regional aggregates dealers with multi-source supply networks consolidate small-lot procurement for ready-mix contractors and agricultural retailers. Inventory pooling reduces price exposure for buyers with irregular demand patterns.
- Online Retailers:Bagged agricultural limestone and specialty soil amendments move through e-commerce channels serving hobby farms and landscaping contractors. Delivery logistics constrain bulk material viability in this channel.
- Direct Manufacturers:Integrated lime and chemical carbonate producers like Mississippi Lime Company bypass distribution for pharmaceutical and food-grade customers requiring chain-of-custody documentation.
Quarries dominate tonnage. Direct Manufacturers are gaining share fastest in premium purity segments.
Size:
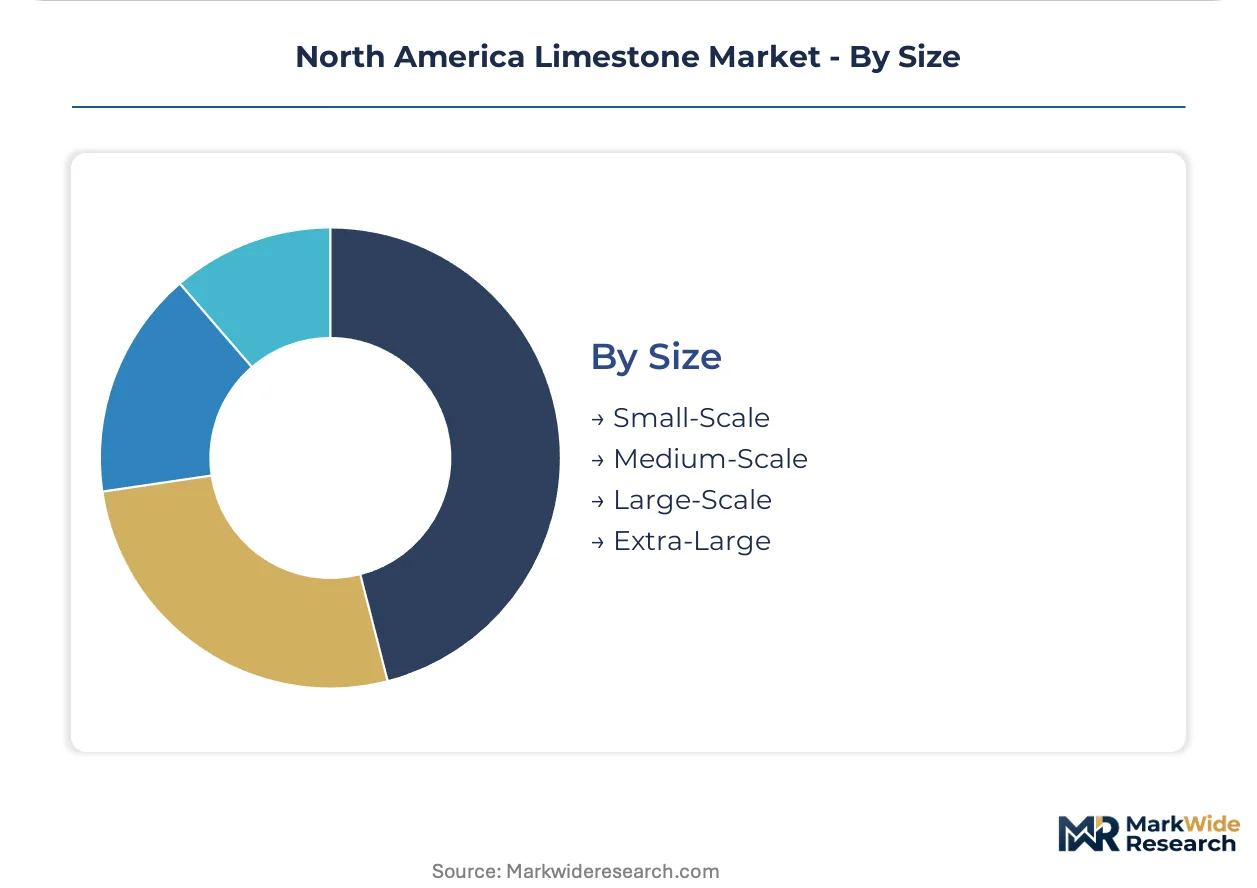
Volume scale determines equipment investment intensity and regulatory compliance burden across extraction and processing operations.
- Large-Scale:Multi-million-ton annual production from rail-served sites with automated crushing and screening circuits. These facilities amortize EPA-mandated dust suppression and emission control capital across substantial output bases.
- Extra-Large:Continental-scale operations with captive marine terminal access and integrated shipping fleets. Capital intensity and permitting complexity create substantial barriers to new entrants at this tier.
- Medium-Scale:Regional quarry operations serving 50-200 mile truck haul markets with batch-plant and road contractor customers. Diesel price exposure concentrates margin risk for this tier.
- Small-Scale:Local agricultural and landscaping material suppliers with mobile crushing equipment and limited fixed infrastructure. OSHA silica compliance timelines disproportionately burden these operators with 18-24 month facility modification requirements.
Large-Scale operations lead by volume. Extra-Large facilities are expanding most quickly as consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America limestone trade flows reflect deep integration between extraction capacity in the United States and industrial demand across all three member economies. Cross-border supply chains move high-calcium grades from Great Lakes quarries into Canadian steel mills and Mexican cement plants, while Gulf Coast terminals handle export volumes to Caribbean construction markets.
United States
Texas and Louisiana anchor domestic consumption through petrochemical complex expansion and Permian Basin drilling activity. EPA National Ambient Air Quality Standards constrain new quarry permits in the Ohio River Valley, forcing producers toward emission control retrofits. The Great Lakes corridor concentrates steel flux and chemical-grade supply, with rail terminals linking Minnesota and Michigan extraction to Indiana and Illinois manufacturing.
Canada
Ontario and Quebec cement producers import high-calcium limestone from Michigan and New York quarries under integrated North American supply contracts. Health Canada and provincial regulators enforce silica exposure limits parallel to OSHA standards, creating compliance symmetry for cross-border operators. British Columbia maintains captive western supply through integrated kiln operations serving Pacific Northwest construction markets.
Mexico
Nuevo León and northern border states consume limestone for cement clinker and steel production tied to US-Mexico manufacturing integration. Mexican environmental regulators under SEMARNAT implement air quality standards converging with EPA benchmarks, elevating capital requirements for new extraction permits. The Bajío Region hosts expanding automotive supplier parks pulling dolomitic limestone for foundry applications.
North America Limestone Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions, producing a tiered structure where scale economies separate national distributors from regional quarry operators. The vendor base concentrates around three strategic archetypes: integrated multinational cement-lime conglomerates with captive quarry networks, independent specialty chemical producers with purity-focused verticals, and regional aggregates distributors serving construction markets through multi-source procurement. Dominant competitive moves include rail-served terminal expansion to extend market radius and long-term offtake contracting to lock construction customer volumes.
Within the multinational tier, Holcim Limited and CEMEX exemplify integrated cement-lime conglomerates with quarry-to-plant logistics control. Carmeuse and Lhoist Group occupy positions as specialty chemical producers with high-purity verticals serving steel and environmental applications. Among independent North American operators, United States Lime & Minerals Inc. represents the regional scale archetype with concentrated southwestern extraction assets.
| Leading Market Players |
|---|
| Holcim Limited |
| United States Lime & Minerals Inc. |
| Carmeuse |
| Mississippi Lime Company |
| Imerys |
| Graymont Limited |
| CEMEX |
| Mineral Technologies Inc. |
| Lhoist Group |
| Others |
Cost & Logistics Intelligence
EPA National Ambient Air Quality Standards and OSHA silica exposure limits gate both supply qualification and price differentiation simultaneously, forcing capital-intensive compliance investments that separate large-scale rail-served operators from truck-dependent regional suppliers while compressing margins for smaller quarries unable to amortize dust suppression infrastructure across high tonnage.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the North America limestone market. Three-tier pricing structure across premium, standard, and economy levels separates food-grade certified chemical limestone from construction-grade crushed material and agricultural dolomitic varieties. Cost compression in standard crushed stone is intensifying because diesel price volatility squeezes truck-dependent regional suppliers serving 50-200 mile haul markets. Cement producers with unit train contracts exhibit lowest price sensitivity, while small-scale agricultural retailers face acute margin pressure from irregular demand patterns and limited volume leverage.
Supply Chain Analysis
Inventory cycles compress to 7-14 days for high-calcium chemical grades serving flue gas desulfurization retrofits, while construction aggregate maintains 30-60 day stockpiles at rail terminals. Supply concentrates in the United States, Canada, and Mexico through integrated quarry-to-plant networks. Production draws from diesel fuel, ammonium nitrate explosives, and steel grinding media as primary input dependencies. Single-source vulnerability runs through the Texas-Louisiana Gulf Coast corridor where Permian Basin drilling concentrates proppant-grade procurement. Distribution runs through BNSF and Union Pacific rail corridors with barge terminals on the Mississippi River system and Great Lakes marine access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across supplier tiers creates niche opportunities as low-carbon cement mandates pull high-calcium limestone into supplementary cementitious material formulations, opening specialty grade positions between commodity construction supply and integrated chemical producer dominance.
For Market Incumbents: Secure rail-served terminal expansion along Union Pacific and BNSF corridors to extend 500-mile market radius beyond diesel-dependent truck haul zones. Defend against ground granulated blast furnace slag substitution in steel flux applications by deepening captive kiln control over reactivity indices. Prioritize EPA carbon capture readiness infrastructure in greenfield permit applications to lock preferential financing terms for chemical-grade capacity additions.
For New Entrants and Emerging Players: Food-grade purity certification gaps in pharmaceutical and nutritional supplement supply chains offer white-space entry points where incumbents under-serve certified heavy metal limit requirements. Target ultra-high-purity calcium carbonate verticals with chain-of-custody documentation protocols bypassing distributor networks for direct manufacturer relationships. Pursue mineral carbonation process development using waste limestone fines to capture CO2 sequestration credit revenue streams under emerging state-level carbon accounting frameworks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional aggregates distributors holding multi-quarry networks in the US Southeast and Mountain West. Five-to-ten year viability hinges on positioning for infrastructure spending acceleration and low-carbon procurement rule expansion across state transportation departments. Monitor California and New York state-level low-carbon cement mandate implementation velocity as the inflection signal for high-calcium limestone premiumization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Served Terminal Expansion | Unit train loading facilities on BNSF and Union Pacific corridors enable 500-mile radius delivery without diesel price exposure. |
| Carbon Capture Readiness Infrastructure | Amine scrubber footprints in Texas and Louisiana greenfield projects secure preferential financing under EPA New Source Performance Standards. |
| Food-Grade Purity Certification | Ultra-high-purity calcium carbonate with certified heavy metal limits commands premium positioning in pharmaceutical and nutritional supplement manufacturing. |
| Long-Term Offtake Contracting | 36-60 month supply agreements with fixed escalators concentrate purchasing power among national aggregates distributors with multi-quarry networks. |
| Mineral Carbonation Process Development | Waste limestone fines utilization for CO2 sequestration credits opens revenue streams under state-level carbon accounting frameworks. |
Research Approach
Initial hypotheses were tested against primary input from quarry operations managers, cement plant procurement directors, flue gas desulfurization engineers, and agricultural distributor category buyers and refined through secondary validation against EPA enforcement databases, OSHA compliance records, state transportation department procurement filings, and railroad waybill data. Bottom-up volume estimates from quarry-level production capacity and top-down demand calibration from end-use industry consumption patterns were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates volume drivers by calcium purity tier, particle size specification, end-use industry concentration, and regional production hub access. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic construction spending indices and petrochemical complex expansion timelines. Industry-specific forecast inputs include Permian Basin drilling intensity projections and Clean Air Act enforcement pacing for power plant scrubber retrofits.
Underlying assumptions cover EPA regulatory trajectory continuity, diesel price band stability, and infrastructure spending authorization levels, with deviation risk concentrated in carbon border adjustment mechanism implementation timing and electric arc furnace slag substitution rates in secondary steelmaking. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Unexpanded Perlite Market