
 Strategic Mineral Materials Market | 2026-2036
Strategic Mineral Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Strategic Mineral Materials Market Analytics
The EU Critical Raw Materials Act is consolidating procurement priorities across European automotive and renewable energy supply chains. Glencore leverages its cobalt trading infrastructure to sustain long-term offtake relationships with cathode producers. Albemarle Corporation dominates lithium brine extraction in South America's salt flat regions and extends its refining footprint into Asian battery manufacturing zones.
Strategic mineral materials encompass rare earth elements, lithium compounds, cobalt materials, and tantalum products with purity grades typically exceeding 99.5 percent, extracted through hard-rock mining, brine evaporation, or ion-adsorption clay leaching for use in permanent magnets, battery cathodes, and high-temperature alloys. Rare earth elements anchor the highest value-per-kilogram segment due to their irreplaceable magnetic properties in electric drivetrains, while lithium compounds represent the fastest-expanding category as automotive OEMs scale cylindrical and prismatic cell formats. Electronics applications retain mature demand profiles for tantalum capacitors, whereas renewable energy deployments are shifting margin pools toward neodymium-iron-boron magnet supply chains.
The US EPA and SEC climate disclosure rules, alongside China's MEE environmental compliance mandates, are tightening extraction permits and forcing capital allocation toward lower-carbon processing routes. REACH registration requirements in Europe further constrain market access for unverified tantalum and cobalt suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which processing technologies will secure preferential offtake terms.
Market Dynamics
The EU Critical Raw Materials Act is forcing cathode manufacturers to reroute supply chains away from single-source dependencies, while China's MEE environmental compliance mandates compress extraction permits and redirect capital toward lower-carbon processing infrastructure.
Growth Catalysts
- IRA clean vehicle tax credits:US automotive OEMs are accelerating domestic lithium and cobalt sourcing to qualify for $7,500 consumer incentives, tightening offtake timelines for North American feedstock projects.
- Permanent magnet demand in electric drivetrains:Neodymium-iron-boron alloys anchor torque density in 800V architectures, pulling rare earth processing capacity toward automotive-grade purity standards.
- Jiangxi rare earth corridor expansion:Ion-adsorption clay leaching operations in southern China are scaling hydrometallurgical separation capacity to capture downstream magnet manufacturing margin.
Market Restraints
- Lithium carbonate price volatility:Spot market swings exceeding 300% annually destabilize project financing for Australian hard-rock spodumene converters and South American brine expansions alike.
- Democratic Republic of Congo cobalt concentration:Artisanal mining exposure in the DRC concentrates 70% of global cobalt supply, amplifying ESG audit complexity and offtake rejection risk for unverified material.
- Substitute magnet materials:Ferrite and aluminum-nickel-cobalt alloys displace rare earth content in low-torque auxiliary motors, capping neodymium price elasticity in cost-sensitive automotive applications.
Strategic Opportunities
- EU Green Deal industrial funding:The European Battery Alliance and Net-Zero Industry Act are channeling state aid toward Finnish and Portuguese lithium conversion facilities, creating first-mover advantages for integrated cathode precursors.
- Solid-state battery chemistry convergence:Sulfide electrolyte architectures demand ultra-high-purity lithium metal, opening premium pricing tiers for thin-film deposition-grade feedstocks.
- Direct shipping ore bypass:Australian miners are constructing spodumene concentrators with integrated lithium hydroxide circuits, capturing margin previously lost to Chinese chemical conversion.
Industry Challenges
- Metallurgical engineering talent scarcity:Solvent extraction and electrowinning expertise concentrates in aging workforces at legacy copper and nickel operations, constraining rare earth separation plant commissioning.
- REACH registration timelines:ECHA substance dossier preparation for novel tantalum and cobalt compounds extends 18-24 months, delaying European market access for non-EU refiners.
- Legacy ERP integration with traceability platforms:Cobalt and tantalum smelters face middleware complexity connecting ISO 14001 environmental systems to blockchain-based conflict mineral tracking demanded by automotive OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strategic Mineral Materials Market |
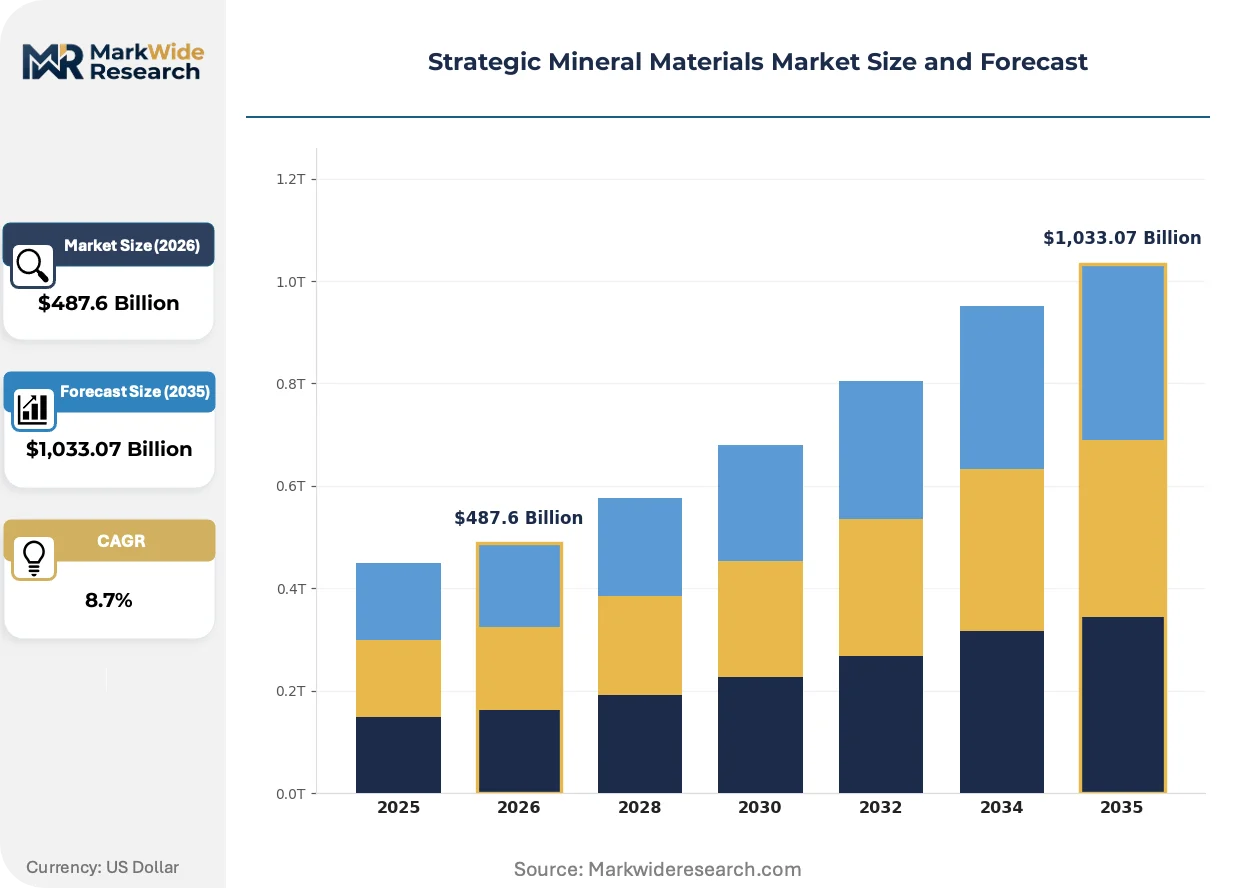
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rare Earth Elements, Lithium Compounds, Cobalt Materials, Tantalum Products Application: Electronics, Renewable Energy, Automotive, Defense End User: Manufacturers, Technology Firms, Automotive OEMs, Government Agencies Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Specialty Retailers |
| Companies Covered | Glencore, Anglo American plc, Vale, Rio Tinto Group, BHP Group Limited, Albemarle Corporation, Freeport-McMoRan Inc., China Minmetals Corporation, MP Materials Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strategic Mineral Materials Market Evolving Landscape
Processing technology leaps and regulatory disclosure mandates are compressing the gap between extraction and cathode manufacturing, eliminating intermediate trading layers that historically captured arbitrage margin.
Direct lithium extraction from geothermal brines is electrifying project economics in California's Salton Sea and Germany's Upper Rhine Graben. Controlled Thermal Resources and Vulcan Energy are deploying selective adsorption and electrochemical intercalation to bypass multi-year evaporation ponds. This technology is electrifying the competitive position of European and North American projects against incumbent South American producers.
China's MEE has imposed wastewater discharge limits on rare earth separation facilities in Jiangxi and Inner Mongolia that exceed prior GB standards by an order of magnitude. Smelters must retrofit ammonia-free precipitation circuits or face permit revocation. Magnet manufacturers in Ningbo and Baotou are absorbing 15-20% processing cost increases to secure compliant feedstock, passing margin pressure to wind turbine and automotive tier-one suppliers.
Automotive OEMs are consolidating cathode material procurement through equity stakes in conversion facilities rather than arm's-length offtake. Tesla, BMW, and Volkswagen have each announced binding supply agreements with lithium hydroxide producers that include technical collaboration clauses and quality audit rights. This behavioral shift is most visible in binding offtake structures for European gigafactory clusters, where OEMs demand 99.97% battery-grade purity with quarterly ESG verification.
Strategic Mineral Materials Market Segmentation
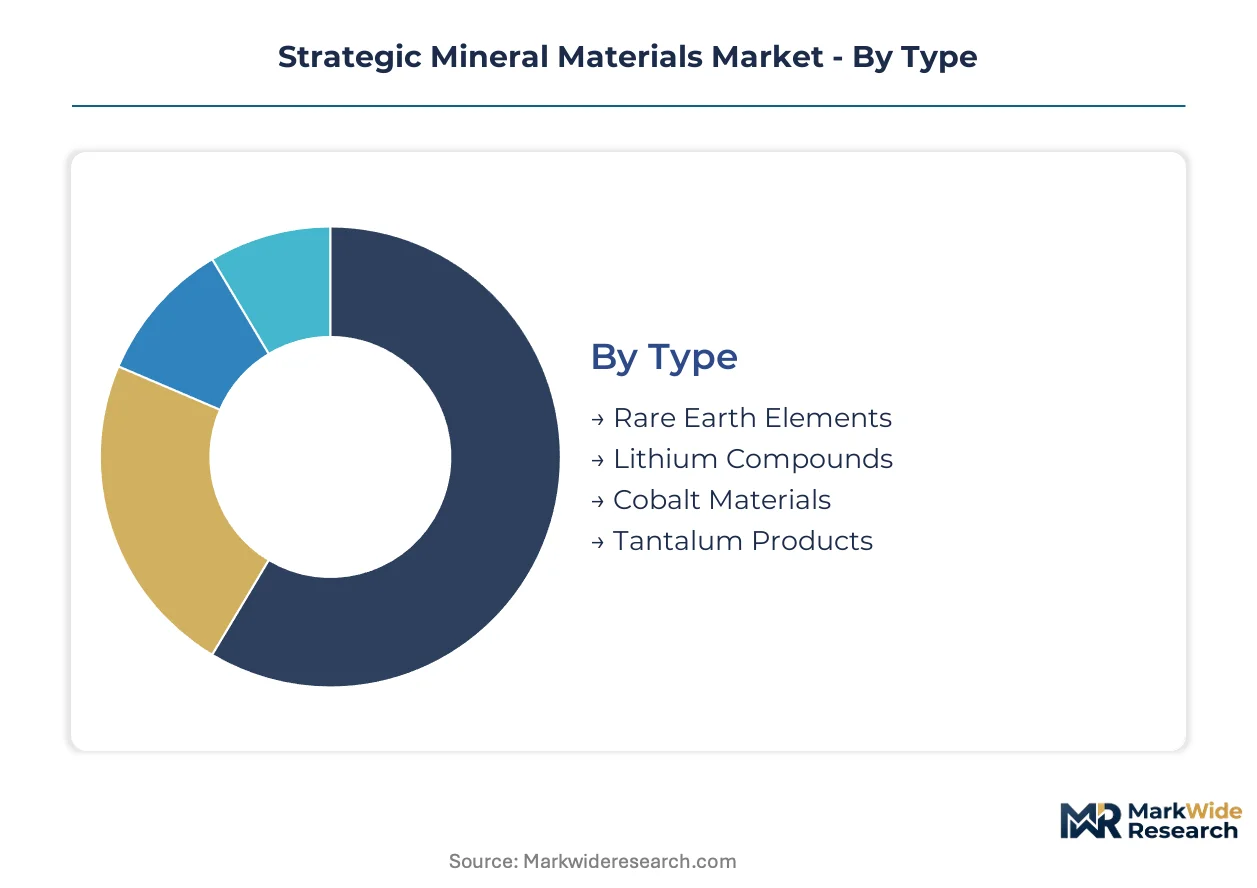
Segmentation in strategic mineral materials reveals how supply chain control points shift across material chemistry and end-use specifications. Cathode-grade lithium commands divergent procurement protocols from defense-grade tantalum, while rare earth magnet alloys face distinct qualification hurdles in automotive versus wind turbine applications.
Type:
Rare earth separation capacity concentrates in China's Jiangxi and Inner Mongolia corridors, with ion-adsorption clay deposits anchoring global heavy rare earth supply.
- Rare Earth Elements:Neodymium, praseodymium, dysprosium, and terbium constitute the magnet-grade subset essential for torque-dense electric drivetrains. China's MEE wastewater discharge mandates are forcing ammonia-free precipitation retrofits at separation facilities, elevating processing costs for compliant material. Defense contractors and wind turbine OEMs compete for limited heavy rare earth output from southern Chinese clay deposits.
- Lithium Compounds:Battery-grade lithium carbonate and lithium hydroxide differentiate by sodium and magnesium impurity thresholds, with hydroxide preferred for high-nickel cathode chemistries. Direct extraction technologies in California's Salton Sea and Germany's Upper Rhine Graben are bypassing multi-year evaporation timelines, threatening incumbent South American brine economics.
- Cobalt Materials:Cobalt sulfate and cobalt metal serve battery cathodes and aerospace superalloys respectively, with the former requiring stringent ESG verification under EU battery passport rules.
- Tantalum Products:Capacitor-grade tantalum powder and wire demand conflict-free sourcing documentation under US Dodd-Frank and EU conflict mineral regulations.
Rare earth elements absorb the bulk of installed capacity; lithium compounds are expanding most quickly.
Application:
Application-driven purity specifications fragment procurement, with automotive battery-grade material commanding premium spreads over industrial-grade feedstock.
- Electronics:Tantalum capacitors in smartphones and computing hardware require 99.99% purity with guaranteed conflict-free provenance. REACH registration timelines for novel tantalum compounds extend 18-24 months, constraining European market access for non-EU refiners.
- Renewable Energy:Neodymium-iron-boron magnets in offshore wind turbines demand corrosion-resistant coatings and guaranteed heavy rare earth content for high-temperature stability. China's Jiangxi corridor expansion targets this segment with integrated magnet manufacturing capacity.
- Automotive:Cylindrical and prismatic battery cells consume lithium hydroxide and cobalt sulfate at 99.97% purity with quarterly ESG verification under OEM binding offtake structures.
- Defense:Samarium-cobalt magnets and tantalum components for avionics and missile systems require domestic sourcing quotas under US Defense Production Act authorities.
Automotive applications command the steepest price premiums; renewable energy deployments are climbing the fastest.
End User:
End-user scale determines contract structure, with automotive OEMs consolidating procurement through equity stakes rather than arm's-length offtake.
- Manufacturers:Cathode precursor producers and magnet alloy fabricators purchase feedstock under long-term contracts with price linkage to London Metal Exchange or Fastmarkets indices.
- Technology Firms:Consumer electronics assemblers prioritize conflict-free tantalum certification and rare earth traceability to satisfy ESG disclosure requirements.
- Automotive OEMs:Tesla, BMW, and Volkswagen have secured binding lithium hydroxide supply with technical collaboration clauses and quality audit rights for European gigafactory clusters.
- Government Agencies:Defense stockpiling programs and strategic reserve acquisitions operate outside commercial pricing, with US National Defense Stockpile and EU strategic autonomy initiatives redirecting supply.
Automotive OEMs dominate forward contract volumes; government agencies are gaining share fastest through strategic stockpiling mandates.
Distribution Channel:
Channel structure reflects material value density, with high-value rare earth and lithium compounds bypassing intermediary layers.
- Direct Sales:Integrated miners with captive conversion capacity ship battery-grade lithium hydroxide and cobalt sulfate directly to cathode plants under multi-year offtake agreements.
- Distributors:Regional metal traders stock tantalum and specialty cobalt alloys for just-in-time delivery to electronics contract manufacturers.
- Online Marketplaces:Spot lithium carbonate and spodumene concentrate trade on digital platforms, amplifying price volatility that destabilizes project financing.
- Specialty Retailers:Small-volume rare earth and tantalum products for research laboratories and prototype development circulate through niche chemical suppliers.
Direct sales capture the majority of lithium and cobalt volume; online marketplaces are expanding most quickly for spot price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baotou's rare earth processing corridor anchors global magnet alloy supply, while lithium extraction clusters in South America's salt flats and Australia's hard-rock belts reshape cathode feedstock flows across three continents.
China
Electric vehicle production in Ningbo and Shenzhen consumes neodymium-iron-boron magnets at unprecedented scale. The MEE's wastewater discharge mandates force ammonia-free precipitation retrofits across Jiangxi separation facilities. Baotou's integrated magnet manufacturing corridor absorbs 15-20% processing cost increases to secure compliant feedstock.
Australia
Spodumene concentrate from Western Australia's Greenbushes and Pilgangoora operations feeds Asian hydroxide converters. The country's Critical Minerals Facility channels state financing toward integrated lithium chemical circuits. Queensland's emerging hard-rock projects target direct shipping ore bypass to capture margin lost to Chinese conversion.
United States
Defense contractors in California and Texas compete for samarium-cobalt magnet quotas under Defense Production Act authorities. The EPA and SEC climate disclosure rules tighten extraction permits for domestic rare earth projects. California's Salton Sea geothermal brine operations deploy selective adsorption to challenge South American lithium economics.
Chile
Atacama Desert brine evaporation supplies battery-grade lithium carbonate to Asian cathode manufacturers. The country's national mining regulator imposes freshwater extraction limits that compress expansion timelines. Antofagasta's chemical conversion corridor faces margin pressure from direct extraction technologies in North America and Europe.
Germany
Automotive OEMs in Stuttgart and Munich secure binding lithium hydroxide offtake for European gigafactory clusters. The EU Critical Raw Materials Act and REACH registration requirements constrain market access for unverified suppliers. The Upper Rhine Graben's geothermal direct extraction projects threaten incumbent brine economics with faster commissioning timelines.
Strategic Mineral Materials Market Competitive Landscape
The competitive structure tilts toward integrated miners with captive conversion capacity and trading houses with offtake infrastructure. Diversified majors and pure-play specialists coexist in a tiered configuration where scale and ESG verification credentials determine contract access. Three archetypes dominate: diversified mining conglomerates with multi-commodity trading arms, integrated lithium specialists controlling brine-to-hydroxide value chains, and rare earth pure-plays with separation technology advantages. Competitive moves concentrate on equity stakes in conversion facilities and binding technical collaboration clauses that preempt spot market exposure.
Among diversified Swiss- and UK-based trading houses, Glencore and Anglo American exemplify the conglomerate archetype through cobalt and multi-commodity positioning. Albemarle Corporation occupies a position as the integrated lithium specialist archetype with South American brine dominance. MP Materials Corp. represents the rare earth pure-play model with Mountain Pass extraction and developing separation capabilities.
| Leading Market Players |
|---|
| Glencore |
| Anglo American plc |
| Vale |
| Rio Tinto Group |
| BHP Group Limited |
| Albemarle Corporation |
| Freeport-McMoRan Inc. |
| China Minmetals Corporation |
| MP Materials Corp. |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement consolidation through equity stakes in conversion facilities anchors contract-based long-term offtake as the dominant pricing model, with cathode-grade purity thresholds and ESG verification tiers stratifying lithium hydroxide and cobalt sulfate valuations.
Pricing Analysis
Battery-grade yield performance anchors value-based pricing tiers, with 99.97% purity lithium hydroxide commanding substantial premiums over industrial-grade feedstock. Price differentiation hinges on sodium impurity thresholds and quarterly ESG audit compliance under EU battery passport rules. Cost compression in standard-grade material is intensifying because Chinese MEE wastewater mandates force ammonia-free precipitation retrofits. Defense contractors exhibit the lowest price sensitivity due to domestic sourcing quotas, while electronics assemblers face acute margin pressure from REACH registration delays.
Supply Chain Analysis
Rare earth separation feedstock rests on Chinese ion-adsorption clay deposits in Jiangxi and Inner Mongolia, Australian spodumene concentrate from Western Australia's Greenbushes and Pilgangoora operations, and Chilean brine evaporation in the Atacama Desert. Solvent extraction circuits, electrowinning infrastructure, and hydrometallurgical separation capacity constitute critical processing dependencies. Single-source vulnerability concentrates in the Democratic Republic of Congo's artisanal cobalt mining exposure. Distribution runs through direct multi-year offtake agreements from integrated miners to cathode plants, bypassing intermediary trading layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Critical Raw Materials Act erects a cost-of-compliance barrier that rewards players with verified supply chains and REACH-registered substances, locking out speculative entrants lacking ESG audit infrastructure.
For Market Incumbents: Deploy ammonia-free precipitation retrofits at existing separation facilities to preempt MEE permit revocation in China's Jiangxi corridor. Deepen upstream control over South American brine assets before direct extraction technologies in California's Salton Sea and Germany's Upper Rhine Graben erode incumbent economics. Consolidate equity stakes in Finnish and Portuguese lithium conversion facilities to capture EU Green Deal industrial funding. For New Entrants and Emerging Players: Defense contractors facing domestic sourcing quotas under US Defense Production Act authorities represent the most penetrable buyer archetype for rare earth pure-plays. Geothermal direct extraction projects in North America and Europe offer faster commissioning timelines against incumbent brine economics. Pursue technical collaboration clauses with automotive OEMs that include quality audit rights rather than arm's-length spot market exposure. For Investors and Strategic Acquirers: The window for entry favors integrated lithium specialists with captive brine-to-hydroxide value chains and rare earth separation technology advantages. Long-term viability hinges on positioning ahead of solid-state battery chemistry convergence demanding ultra-high-purity lithium metal. Watch for binding offtake announcements from European gigafactory clusters as the inflection signal for premium pricing tier capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Albemarle Corporation's South American salt flat dominance secures captive lithium carbonate supply against spot volatility. |
| Ammonia-Free Precipitation Retrofit | Chinese MEE wastewater mandates force separation facility upgrades, elevating processing costs for compliant rare earth output. |
| Direct Extraction Technology Deployment | Controlled Thermal Resources and Vulcan Energy bypass multi-year evaporation timelines in California's Salton Sea corridor. |
| EU Conversion Facility Equity Stakes | Tesla, BMW, and Volkswagen secure binding lithium hydroxide offtake with technical collaboration clauses for gigafactory clusters. |
| Conflict-Free Tantalum Certification | Electronics assemblers satisfy Dodd-Frank and EU conflict mineral regulations through blockchain-based provenance tracking. |
Research Methodology
Document review covered customs and trade data from the US International Trade Commission and Eurostat, SEC 10-K filings from diversified mining conglomerates, and ECHA substance dossier databases, complemented by interviews with cathode precursor procurement managers, rare earth separation plant engineers, and automotive OEM supply chain directors. Primary fieldwork with lithium brine project developers and magnet alloy fabricators was cross-checked against Fastmarkets and London Metal Exchange pricing indices. Bottom-up project pipeline assessments and top-down end-use demand modeling were triangulated to validate volume estimates.
Segment-level outputs across the analysis window reflect modeling by material type, application purity specification, end-user contract structure, and regional processing corridor. CAGRs were derived from regression analysis against electric vehicle production forecasts and renewable energy deployment trajectories. Industry-specific inputs included binding offtake announcement tracking, MEE permit revocation timelines, and Defense Production Act quota allocations.
Revisions become necessary when regulatory divergence between jurisdictions accelerates, direct extraction technologies achieve commercial scale ahead of modeled timelines, or artisanal mining exposure in the DRC triggers expanded ESG audit requirements. A small set of named triggers—EU battery passport implementation pace, Chinese environmental enforcement severity, and solid-state battery chemistry adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Fluorspar Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Limestone Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Industrial Diamond Market