
 Mineral Salt Ingredients Market | 2026-2036
Mineral Salt Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Salt Ingredients Market Outlook
Buyer concentration in food and beverage manufacturing is broadening as mid-sized processors and private-label brands diversify their supplier bases beyond traditional incumbents. Cargill, Inc. leverages its integrated supply chain from mining to packaged ingredients to serve this fragmented demand. Jungbunzlauer Suisse AG specializes in citrate-mineral compounds that address clean-label sodium reduction trends. K+S Aktiengesellschaft anchors European industrial salt supply through its domestic evaporite deposits and refinery network.
Mineral salt ingredients comprise crystalline or processed inorganic compounds—primarily sodium, potassium, magnesium, and calcium salts—extracted through solar evaporation, vacuum refining, or mechanical mining, with purity grades ranging from technical to pharmacopeia-compliant. These ingredients function as flavor modulators, preservatives, nutrient carriers, process aids, and chemical feedstocks across food, water treatment, pharmaceutical, and cosmetic applications. Food-grade sea salt and rock salt dominate volume, while pharmaceutical-grade refined salts command the deepest margin pools due to USP and EP certification requirements. Himalayan salt occupies a niche premium position in cosmetic and specialty food channels, though its production scale remains constrained by single-source geography.
FDA food additive regulations and USP monograph standards govern mineral salt purity, labeling, and therapeutic claims in the United States, while REACH and EFSA frameworks in Europe impose strict contaminant limits and environmental disclosure obligations on salt processors. Compliance with these overlapping regimes now determines market access for exporters and shapes R&D priorities around heavy-metal reduction and sustainable extraction. Stakeholders must monitor evolving pharmacopeia harmonization between USP, EP, and JP standards, as divergence in monograph specifications threatens to fragment formulation strategies and supplier qualification protocols.
Market Dynamics
Clean-label sodium reduction mandates across packaged food sectors are forcing mineral salt suppliers to reconfigure their product portfolios around citrate and chloride compounds that maintain functionality at lower sodium loads. This regulatory pressure intersects with EU F-Gas Regulation compliance costs to reshape capital allocation priorities.
Growth Catalysts
- EFSA sodium reduction guidelines:Packaged food manufacturers in France and Italy are accelerating reformulation timelines to meet 2025 targets, pulling demand for potassium chloride and magnesium sulfate substitutes.
- Pharmaceutical-grade certification expansion:USP and EP monograph harmonization efforts are opening cross-border qualification pathways for Indian and Chinese refined salt exporters.
- Evaporite mining automation:German and Polish producers are deploying sensor-based sorting to cut energy intensity per ton of food-grade output.
Market Restraints
- Single-source Himalayan rock salt dependency:Pakistan's Khewra mine supplies nearly all premium pink salt for cosmetics and specialty foods, creating geographic concentration risk.
- REACH environmental disclosure burdens:Salt processors face escalating compliance costs for heavy-metal testing and supply chain traceability documentation.
- Membrane electrolysis substitution:Chlor-alkali producers are bypassing mined salt entirely for synthetic sodium hydroxide and chlorine production.
Strategic Opportunities
- Brazilian pharmaceutical formulators:ANVISA's accelerated API registration pathways are attracting EP-certified salt suppliers seeking South American manufacturing partnerships.
- Cell-cultured meat nutrient media:Precision fermentation startups require pharmaceutical-grade magnesium and calcium salts at volumes currently unmet by incumbent suppliers.
- Direct-to-brand e-commerce channels:Specialty salt producers are bypassing traditional ingredient distributors to capture margin from craft food manufacturers.
Industry Challenges
- Pharmacopeia auditor scarcity:USP and EP certification bodies face backlogs exceeding 18 months for new salt grade qualifications.
- Legacy evaporator retrofit requirements:European salt refineries must replace coal-fired thermal systems to meet EU Green Deal emissions targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Salt Ingredients Market |
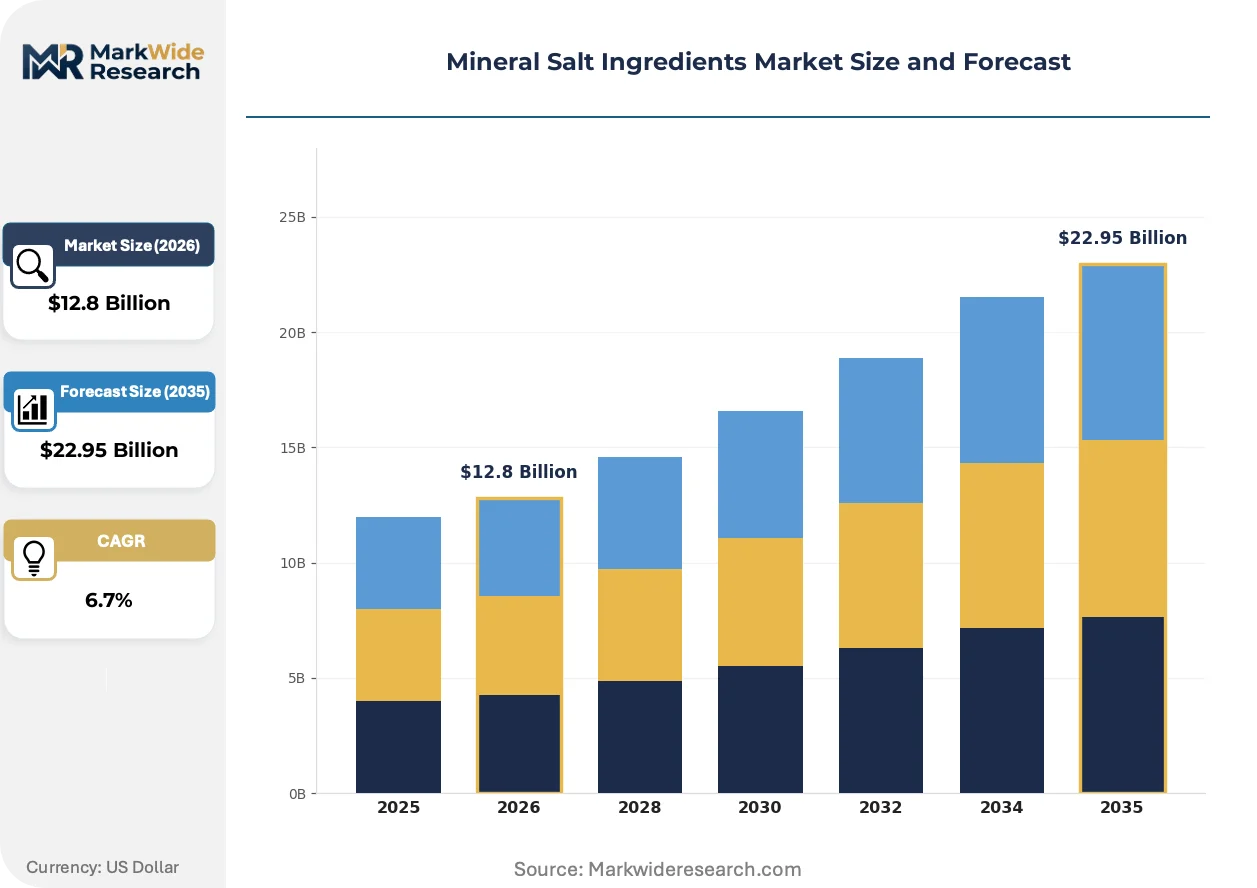
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sea Salt, Rock Salt, Table Salt, Himalayan Salt Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Seasoning, Water Treatment, Cosmetics, Pharmaceuticals Packaging Type: Bags, Containers, Bulk, Sachets |
| Companies Covered | Tate & Lyle PLC, Corbion N.V., Cargill, Inc., Minerals Technologies Inc., Jungbunzlauer Suisse AG, K+S Aktiengesellschaft, Archer Daniels Midland Company, Akzo Nobel N.V., Compass Minerals International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Salt Ingredients Market Strategic Shifts
Processing technology convergence with sustainability verification systems is compressing the gap between industrial and food-grade salt production economics. Suppliers are racing to deploy low-carbon extraction methods before carbon border adjustments penalize conventional operations.
Membrane filtration-crystallization hybrid systems are consolidating multiple refining stages into single-unit operations for high-purity magnesium and potassium salts. Pharmaceutical formulators in Switzerland and Germany are adopting these systems to reduce batch-to-batch variability. The technology is consolidating smaller vacuum-refining operators into integrated multi-product facilities capable of serving both food and drug monograph requirements.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in mechanical salt harvesting operations across Spain and Italy. Salt producers face retrofit deadlines for ammonia-based cooling systems or risk production quota restrictions. Coastal solar evaporation sites in Sicily and the Algarve are most affected, with several operators pursuing geothermal heat integration to maintain throughput.
Ingredient sourcing teams at mid-sized food manufacturers are compressing supplier qualification cycles from 24 months to 12 months to match private-label launch velocities. Direct material sampling and third-party audit pooling are displacing traditional distributor-mediated verification. This pattern is most visible in German and Dutch contract manufacturing, where co-manufacturers now demand upfront salt certification documentation before contract signing.
Mineral Salt Ingredients Market Segmentation
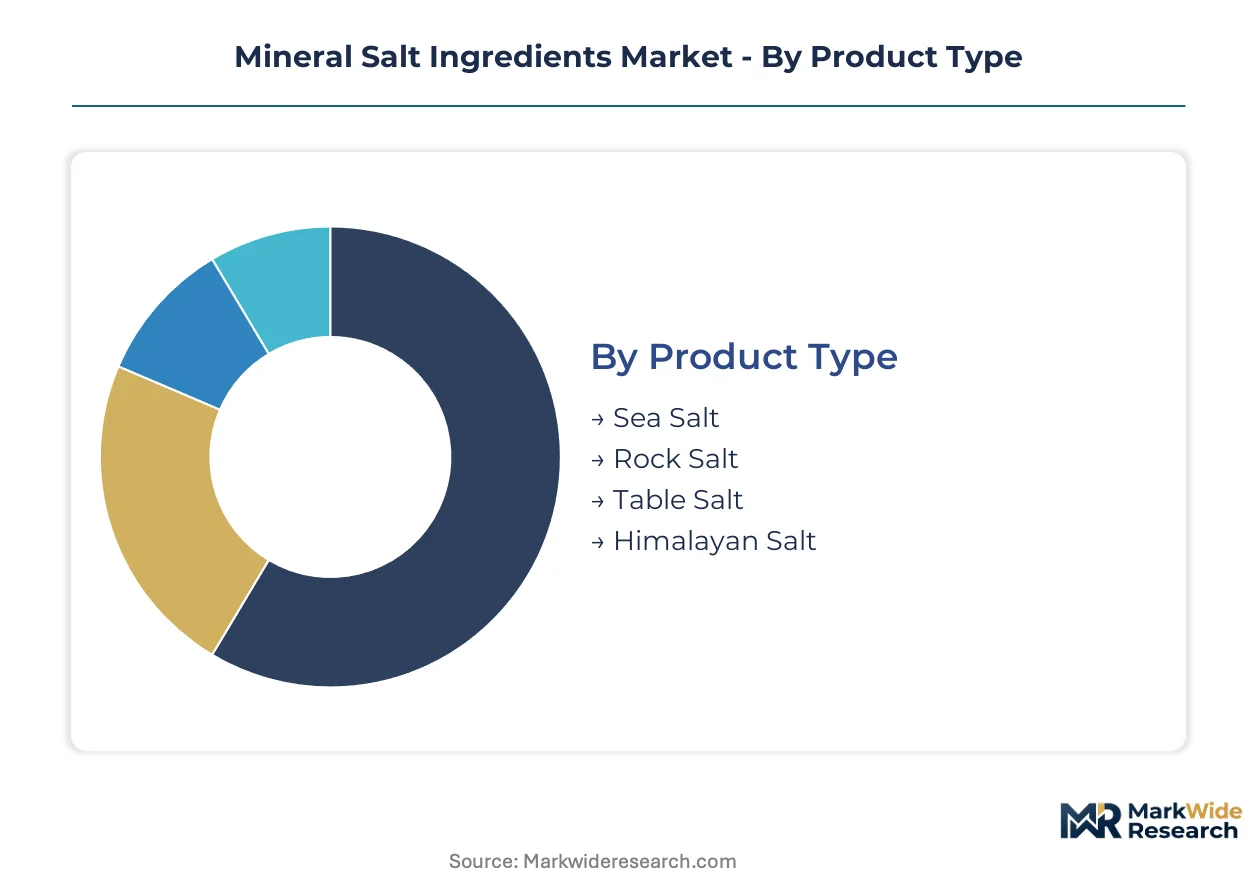
Mineral salt suppliers must navigate divergent certification pathways across product categories. USP and EP monographs govern pharmaceutical grades, while FDA and EFSA frameworks apply to food applications. Each segment carries distinct margin structures and qualification timelines that reshape supplier portfolio strategies.
Product Type:
Certification burdens vary sharply across extraction methods, with evaporative and mined sources facing different contaminant testing protocols under REACH and FDA regulations.
- Sea Salt:Solar-evaporated sodium chloride from coastal ponds retains trace minerals that influence flavor modulation in processed foods. French and Italian seasoning manufacturers favor Sicilian and Guérande harvests for clean-label positioning, though climate variability constrains annual output consistency.
- Rock Salt:Mechanically extracted halite deposits supply de-icing and chemical feedstock markets with minimal processing. German evaporite mining operations in Lower Saxony anchor European industrial supply, leveraging automated sorting to meet technical-grade specifications.
- Table Salt:Vacuum-refined sodium chloride achieves uniform crystal size for household distribution. Iodization mandates in India and Pakistan drive fortification demand, requiring potassium iodate integration at refinery stage.
- Himalayan Salt:Pink-hued halite from Pakistan's Khewra mine commands premium positioning in cosmetic scrubs and specialty foods. Single-source geography creates supply vulnerability, with Indian border logistics determining export reliability.
Leading the category by volume: Rock Salt. Growing fastest: Himalayan Salt.
Grade:
Margin pools stratify by purity threshold, with pharmacopeia compliance commanding multiple cost premiums over technical specifications.
- Food Grade:Refined salts meeting Codex Alimentarius and FDA purity limits serve seasoning, preservation, and leavening functions. EFSA sodium reduction guidelines are accelerating potassium chloride substitution in French and Dutch processed meat formulations.
- Industrial Grade:Technical sodium chloride for chlor-alkali and water softening applications tolerates higher calcium and magnesium content. Membrane electrolysis adoption is eroding demand, with synthetic caustic soda displacing salt-derived feedstocks.
- Pharmaceutical Grade:USP and EP monograph compliance requires heavy-metal testing below 10 ppm and documented batch traceability. Swiss and German formulators pay steep premiums for magnesium sulfate and calcium chloride excipients in parenteral applications.
- Cosmetic Grade:Micronized salts with controlled particle distribution enable exfoliant and bath product functionality. ANVISA registration requirements in Brazil are opening South American demand for EP-certified Himalayan and Dead Sea variants.
Pharmaceutical Grade captures the deepest margin pools. Food Grade dominates absolute volume.
Application:
End-use concentration determines whether suppliers compete on certification depth or logistical scale.
- Food Seasoning:Sodium chloride and potassium-based substitutes modulate flavor, preserve shelf stability, and enable texture control in baked goods. Private-label brands in Germany and the Netherlands are compressing supplier qualification cycles to match product launch velocities.
- Water Treatment:Ion-exchange regeneration and disinfection byproduct generation consume bulk industrial grades. Municipal utilities in Poland and Spain prioritize cost efficiency over purity, favoring domestic rock salt over imported alternatives.
- Cosmetics:Exfoliant scrubs, bath soaks, and mineral muds leverage trace element content for marketing differentiation. Direct-to-brand e-commerce channels are displacing traditional distributors for craft formulators.
- Pharmaceuticals:Tablet diluents, parenteral electrolytes, and API synthesis require documented pharmacopeia compliance. Cell-cultured meat nutrient media represents an emerging demand cluster unmet by incumbent suppliers.
Food Seasoning anchors volume demand. Pharmaceuticals show the steepest expansion trajectory.
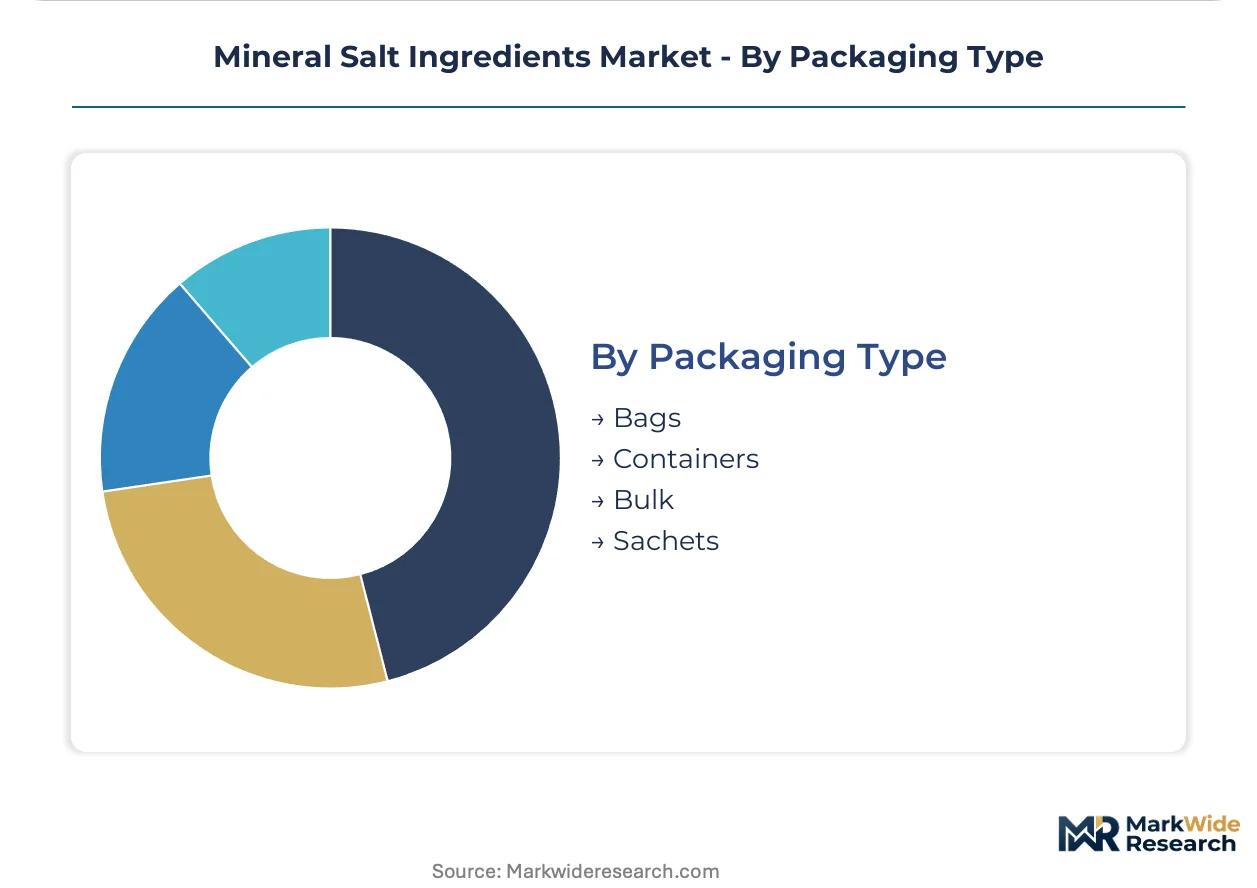
Packaging Type:
Format selection reflects customer scale and contamination risk tolerance across supply chain touchpoints.
- Bags:Multi-layer polymer or paper sacks serve mid-volume food manufacturers and regional distributors. German co-manufacturers increasingly demand pre-certified packaging to accelerate contract onboarding.
- Containers:Rigid drums and totes protect pharmaceutical and cosmetic grades from moisture ingress. Swiss formulators specify UN-certified containers for magnesium and calcium salt excipients.
- Bulk:Unpackaged tanker and vessel shipments minimize per-unit cost for chlor-alkali and water treatment operators. Port logistics at Hamburg and Rotterdam determine European industrial salt competitiveness.
- Sachets:Single-serve packets target foodservice and travel retail channels. Italian and Spanish operators are retrofitting form-fill-seal lines to meet EU Green Deal packaging waste targets.
Bulk shipments dominate tonnage. Sachets are gaining share fastest in premium foodservice segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mineral salt ingredients concentrates in industrial clusters where food processing, pharmaceutical manufacturing, and water treatment infrastructure overlap. Germany anchors European procurement consolidation around certified suppliers, while regulatory divergence between US FDA and EU EFSA frameworks shapes regional qualification strategies.
Germany
Industrial salt users and pharmaceutical formulators in Lower Saxony and North Rhine-Westphalia are consolidating procurement around EP-certified suppliers. The EU F-Gas Regulation accelerates retrofit deadlines for coal-fired evaporator systems at domestic refineries. K+S Aktiengesellschaft leverages its evaporite mining network near Hanover to serve chlor-alkali and food-grade markets simultaneously.
United States
Packaged food manufacturers and municipal water utilities drive bulk sodium chloride consumption across the Midwest and Southeast. FDA food additive regulations and USP monograph standards govern purity thresholds for fortification and therapeutic applications. Compass Minerals International Inc. operates mechanical mining and solar evaporation sites across Utah and Louisiana to serve regional industrial demand.
France
Seasoning manufacturers in Brittany and Provence prioritize Guérande and Sicilian solar-evaporated sea salt for clean-label positioning. EFSA sodium reduction guidelines pull demand for potassium chloride substitutes in processed meat reformulation. French co-manufacturers compress supplier qualification cycles to match private-label launch velocities in the Nord-Pas-de-Calais food processing belt.
India
Iodization mandates and expanding processed food sectors drive refined salt demand across Maharashtra and Gujarat. FSSAI standards govern food-grade purity while CDSCO frameworks apply to pharmaceutical excipient imports. Domestic refineries near Mumbai and Ahmedabad face qualification backlogs as USP and EP certification bodies struggle with auditor scarcity.
Brazil
ANVISA's accelerated API registration pathways attract EP-certified salt suppliers seeking South American manufacturing partnerships. Pharmaceutical formulators in São Paulo and Rio de Janeiro require documented batch traceability for parenteral applications. Brazilian mineral salt consumption concentrates in the Southeast, where chemical and food processing clusters overlap near the Santos port complex.
Mineral Salt Ingredients Market Competitive Environment
European producers anchor the premium-grade tier; North American operators hold scale-driven positions in bulk industrial supply. The vendor base stratifies across three functional layers: integrated mining-to-ingredient conglomerates, citrate-mineral compound specialists, and regional evaporite refiners. Competitive maneuvering centers on pharmacopeia certification expansion and low-carbon processing technology licensing.
Within the integrated supply tier, Cargill, Inc. and K+S Aktiengesellschaft exemplify backward control from extraction through packaged ingredients. Jungbunzlauer Suisse AG occupies a specialist position addressing clean-label sodium reduction trends. These three entities represent divergent strategic postures: captive mineral sourcing, continental refinery networks, and citrate-compound formulation expertise respectively.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Corbion N.V. |
| Cargill, Inc. |
| Minerals Technologies Inc. |
| Jungbunzlauer Suisse AG |
| K+S Aktiengesellschaft |
| Archer Daniels Midland Company |
| Akzo Nobel N.V. |
| Compass Minerals International Inc. |
| Others |
Value Chain & Pricing Dynamics
Pharmacopeia-certified laboratory technicians in Switzerland and Germany command wage premiums that widen spreads between pharmaceutical-grade and technical-grade mineral salt pricing tiers. Labor-cost differentials between certified refinery operations and standard evaporative processing directly determine margin capture across premium and economy market segments.
Pricing Analysis
Volume-mass dominance in industrial-grade rock salt contrasts with margin concentration in pharmaceutical and cosmetic grades. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified excipients from food-grade refined salts and bulk technical sodium chloride. Certification depth and batch traceability documentation drive price differentiation, with Swiss and German formulators paying steep premiums for parenteral-grade magnesium sulfate. Cost compression in industrial grades is intensifying because membrane electrolysis substitutes erode chlor-alkali demand. Municipal water utilities exhibit highest price sensitivity, while pharmaceutical formulators demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Skilled workforce availability in German evaporite mining regions and Polish refinery corridors anchors European pharmaceutical-grade production capacity. Supply concentrates in Pakistan for Himalayan pink salt, Germany for evaporite-derived industrial grades, and India for iodized table salt. Raw material dependencies draw from Khewra mine halite deposits, North Sea evaporite formations, and coastal solar evaporation ponds. Single-source vulnerability around Pakistani Himalayan salt creates structural supply risk. Distribution runs through Rotterdam and Hamburg port logistics for bulk industrial shipments, with certified container networks serving pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
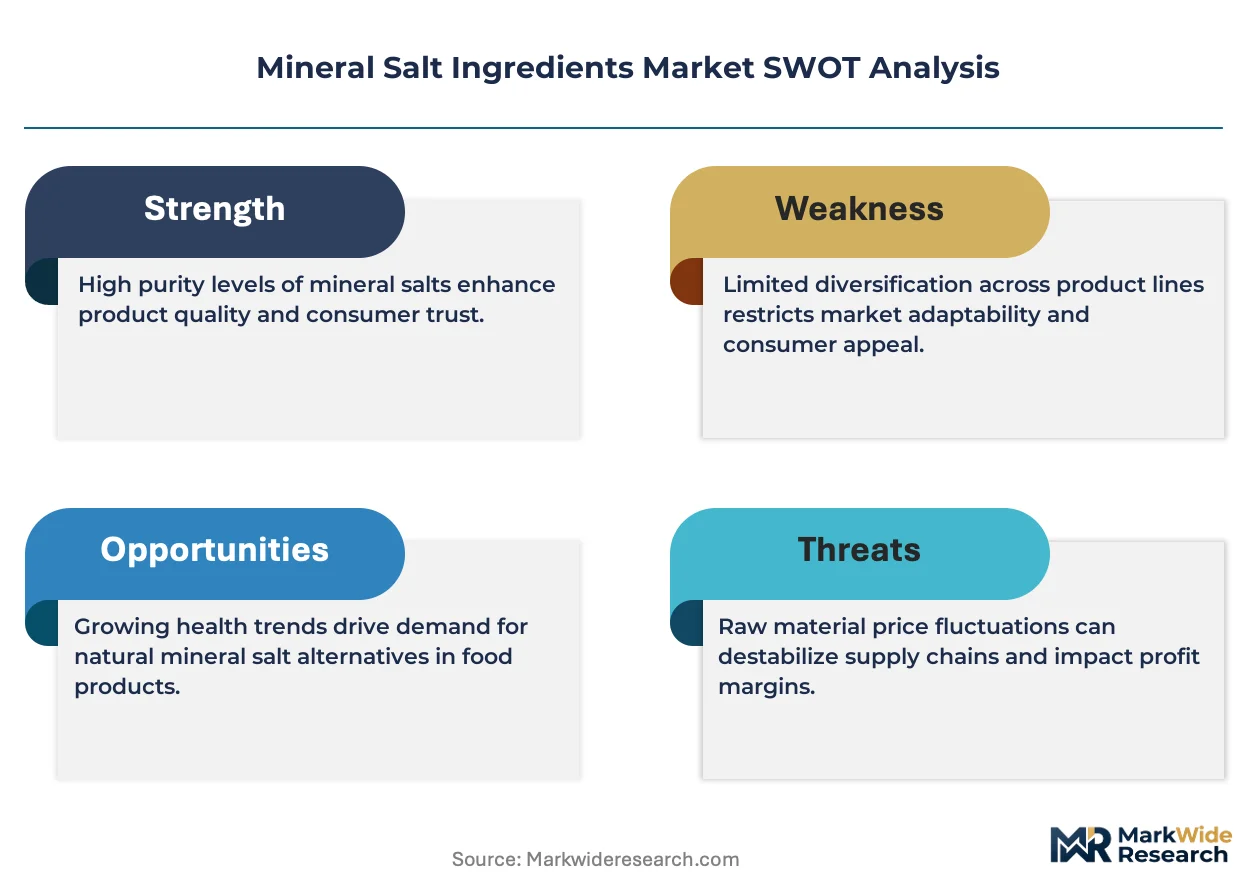
EU F-Gas Regulation compliance costs and REACH disclosure burdens are forcing smaller evaporite refiners toward exit or acquisition, consolidating the vendor base around scaled operators with capital for green retrofit programs.
For Market Incumbents: Extend pharmacopeia certification coverage into emerging demand clusters such as cell-cultured meat nutrient media and Brazilian ANVISA-registered pharmaceutical markets. Invest in captive supply of low-carbon extraction technologies to defend against carbon border adjustment penalties. Backward integration into geothermal heat systems for Sicilian and Algarve solar evaporation sites secures throughput advantages as EU Green Deal emissions deadlines approach. For New Entrants and Emerging Players: Mid-sized craft food manufacturers seeking direct-to-brand e-commerce channels represent an underserved buyer archetype bypassing traditional ingredient distributors. Precision fermentation startups requiring pharmaceutical-grade magnesium and calcium salts at volumes unmet by incumbent suppliers offer white-space entry. Co-manufacturer qualification documentation services in German and Dutch contract manufacturing corridors provide a defensible go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with EP-certified regional refiners possessing retrofit-ready low-carbon processing infrastructure given EU F-Gas Regulation phase-down acceleration. Five-to-ten-year viability favors operators with demonstrated pharmacopeia auditor relationships and documented batch traceability systems. Monitor ANVISA registration pathway velocity as inflection indicator for South American pharmaceutical-grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeia Certification Expansion | USP and EP monograph harmonization opens cross-border qualification for Indian and Chinese exporters. |
| Low-Carbon Extraction Technology Licensing | Geothermal heat integration at Sicilian solar evaporation sites maintains throughput under EU F-Gas deadlines. |
| Direct-to-Brand E-Commerce Channel Development | Specialty salt producers capture margin from craft food manufacturers bypassing traditional distributors. |
| Cell-Cultured Meat Nutrient Media Partnership | Precision fermentation startups require pharmaceutical-grade salts at volumes unmet by incumbent suppliers. |
| ANVISA Registration Pathway Investment | Accelerated API registration in Brazil attracts EP-certified suppliers seeking South American manufacturing partnerships. |
Study Parameters
Trade databases, pharmacopeia monograph repositories, and EU regulatory filing records formed the secondary backbone for mineral salt ingredient market sizing. Primary interviews with salt refinery operations managers, pharmaceutical excipient procurement leads, food manufacturer R&D directors, and cosmetic formulator sourcing heads combined with secondary validation. Bottom-up triangulation across extraction method volumes and top-down cross-check against end-use consumption patterns anchored value estimates.
Historical trendline analysis across solar evaporation output, mechanical mining yields, and vacuum refining capacity established baseline growth trajectories. Segmentation modeling incorporated grade tier, extraction method, end-use application, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Forecast inputs included EFSA sodium reduction guideline implementation velocity and EU F-Gas Regulation retrofit compliance timelines.
Revisions become necessary when pharmacopeia auditor backlogs exceed qualification capacity, carbon border adjustment mechanisms penalize conventional extraction, or single-source Himalayan supply disruptions materialize. Forecasts reflect documented assumptions around regulatory harmonization progress and clean-label reformulation adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Potash Ores Market