
 Kyanite Market | 2026-2036
Kyanite Market Size, Share, and Industry Trends Forecast 2026-2036
Kyanite Market Foresight
ISO 9001 quality management certification is unwinding the competitive field by filtering out artisanal producers lacking documented process controls. Imerys Refractory Minerals leverages its captive mineral reserves in France and Madagascar to sustain long-term supply security for European refractory makers. Great Wall Mineral anchors its position through integrated mining-to-milling operations in China's Liaoning province, while Alroko GmbH & Co KG competes on technical specification breadth for German engineering clients.
Kyanite is an aluminosilicate mineral with the chemical formula Al₂SiO₅, characterized by its anisotropic hardness and transformation to mullite at temperatures exceeding 1300°C, a property that makes it indispensable for high-performance refractory linings in blast furnaces and kilns. The refractories application segment dominates current offtake volumes given steel sector consumption patterns, while ceramics and electronics applications are gaining structural importance as thermal management requirements intensify in semiconductor packaging substrates. Powder and granule forms command premium positioning over blocks and slabs due to their versatility in precision casting and spray-applied lining systems.
EPA emissions standards for heavy industry and REACH chemical registration requirements in Europe are tightening allowable impurity thresholds in refractory minerals, directly elevating testing and certification costs for suppliers. India's BIS quality marks and China's GB standards for refractory materials are creating parallel compliance tracks that fragment market access protocols across major demand centers. Stakeholders must monitor evolving mullite substitution economics and regional mineral beneficiation investments to calibrate long-term raw material sourcing strategies.
Market Dynamics
Aluminosilicate feedstock procurement is tightening furnace lining specifications across steel and cement sectors, with EPA and REACH compliance regimes forcing refractory producers to document impurity thresholds and process controls that artisanal suppliers cannot meet.
Growth Catalysts
- REACH chemical registration:European refractory makers must source certified aluminosilicate minerals, filtering out undocumented suppliers and consolidating procurement among ISO 9001-certified producers.
- Steel sector consumption:Blast furnace rebuild cycles in India and China are accelerating offtake of mullite-forming kyanite for high-temperature lining systems.
- PLI scheme for specialty minerals:India's production-linked incentive program is redirecting supply chain flows toward domestic refractory manufacturing capacity.
Market Restraints
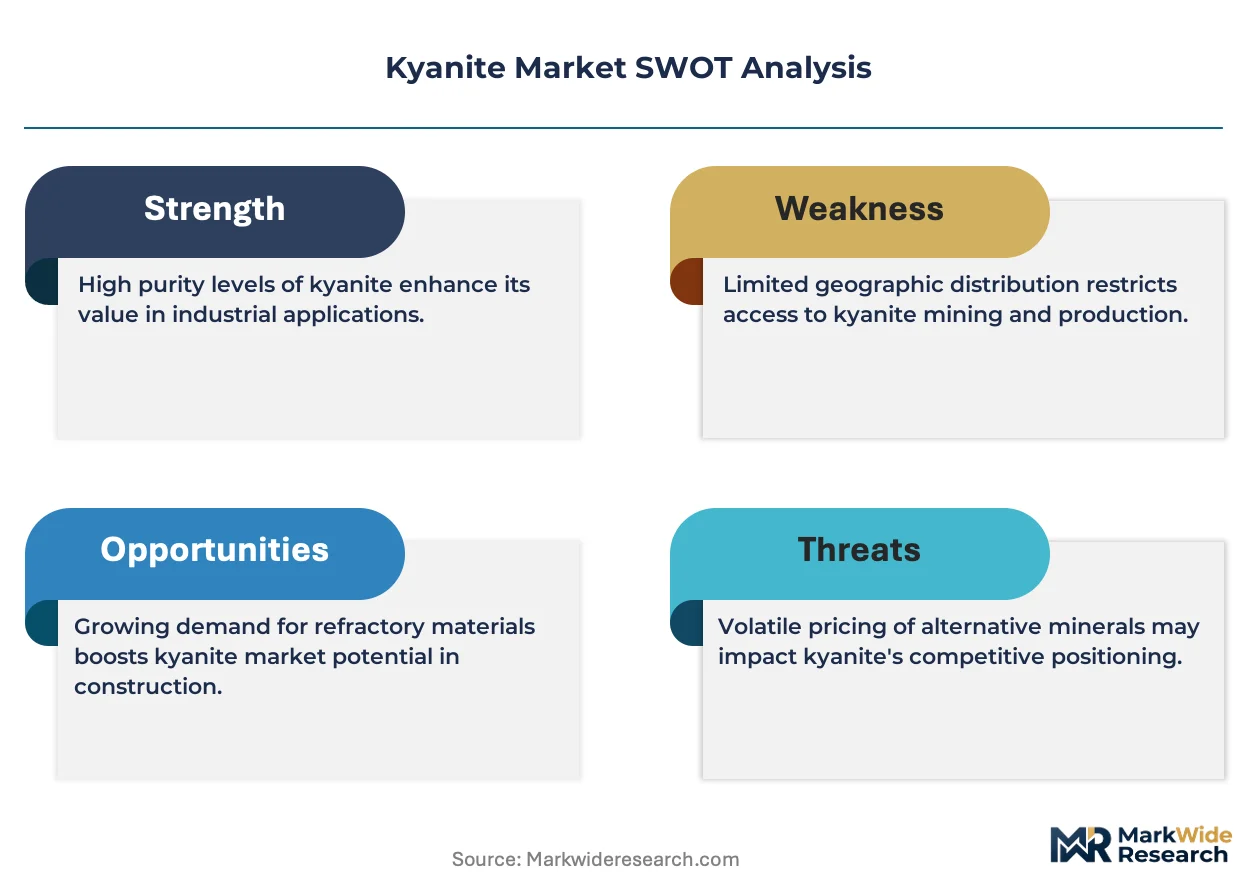
- Energy cost volatility:Calcination and milling operations face input cost pressure from natural gas and electricity price swings in European production zones.
- Madagascar supply concentration:Captive mineral reserve dependence creates geographic risk for European refractory makers relying on single-source feedstock security.
- Fused mullite substitution:Synthetic alternatives threaten natural kyanite positioning in premium refractory applications where thermal shock resistance requirements moderate.
Strategic Opportunities
- Semiconductor packaging substrates:Thermal management requirements in electronics are opening structural demand for precision-grade kyanite powders in ceramic substrates.
- Spray-applied lining systems:Granule and powder form factors are capturing premium positioning over blocks in precision casting applications.
- BIS quality mark expansion:India's Bureau of Indian Standards certification creates parallel compliance tracks that favor early-mover suppliers with documented beneficiation investments.
Industry Challenges
- ISO 9001 documentation gaps:Artisanal producers lack process control records required by European refractory procurement teams, creating supply qualification bottlenecks.
- Dual carbon compliance:China's MIIT emissions targets and EU CBAM carbon border adjustments are forcing simultaneous reconfiguration of mining-to-milling operations across export-oriented supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kyanite Market |
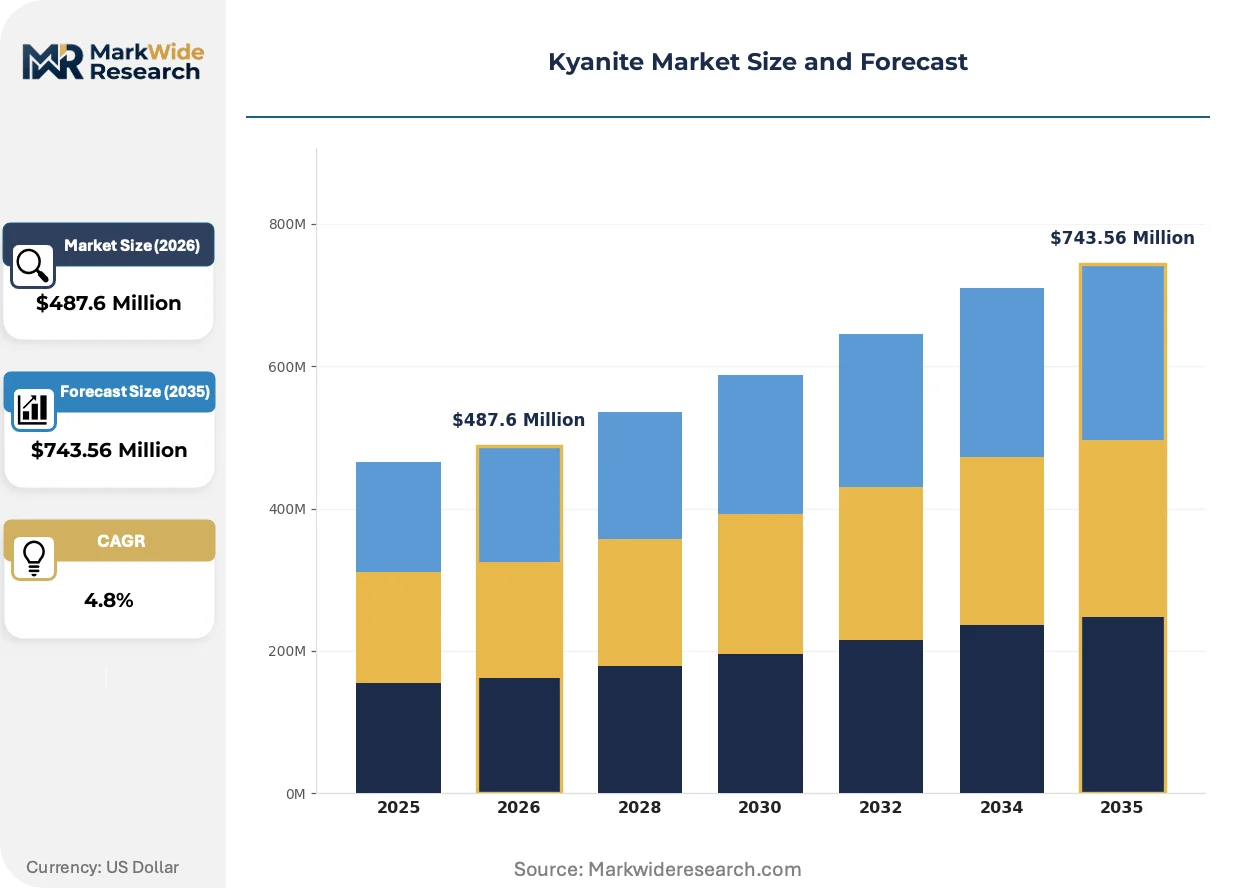
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminosilicate, Synthetic Kyanite, Mica, Other Minerals Application: Refractories, Ceramics, Glass, Electronics End User: Manufacturing, Construction, Aerospace, Automotive Form: Powder, Granules, Blocks, Slabs |
| Companies Covered | Kyanite Mining Corporation, Imerys Refractory Minerals, Great Wall Mineral, Anand Talc, Alroko GmbH & Co KG, Henan Tongbaishan Refractory, Resco Products, Inc., LKAB Minerals, Yilong Refractory Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kyanite Market Shifts & Advancements
Synthetic mullite and precision beneficiation technologies are compressing traditional supply hierarchies, while regulatory fragmentation across EPA, REACH, and BIS regimes is segmenting market access protocols by certification tier rather than mineral quality alone.
Advanced thermal shock testing protocols are displacing legacy visual inspection methods for kyanite grade classification. German engineering clients now mandate documented phase transformation data at 1300°C for blast furnace lining contracts. This technical specification breadth is compressing supplier margins for producers lacking in-house calcination analytics.
EPA emissions standards for heavy industry are tightening allowable impurity thresholds in refractory minerals, directly elevating testing and certification costs for US-bound suppliers. Steel producers in the Great Lakes region are responding by consolidating procurement among vendors with pre-certified beneficiation streams. This regulatory friction is segmenting the North American supply base into EPA-compliant and non-compliant tiers.
Buyer concentration among integrated steel mills is compressing switching cycles for refractory lining contracts. Procurement teams in India's Maharashtra and Gujarat clusters now demand multi-year supply agreements with embedded price adjustment clauses tied to alumina content. This contractual evolution is locking out spot-market suppliers lacking long-term mineral reserve commitments.
Kyanite Market Segmentation
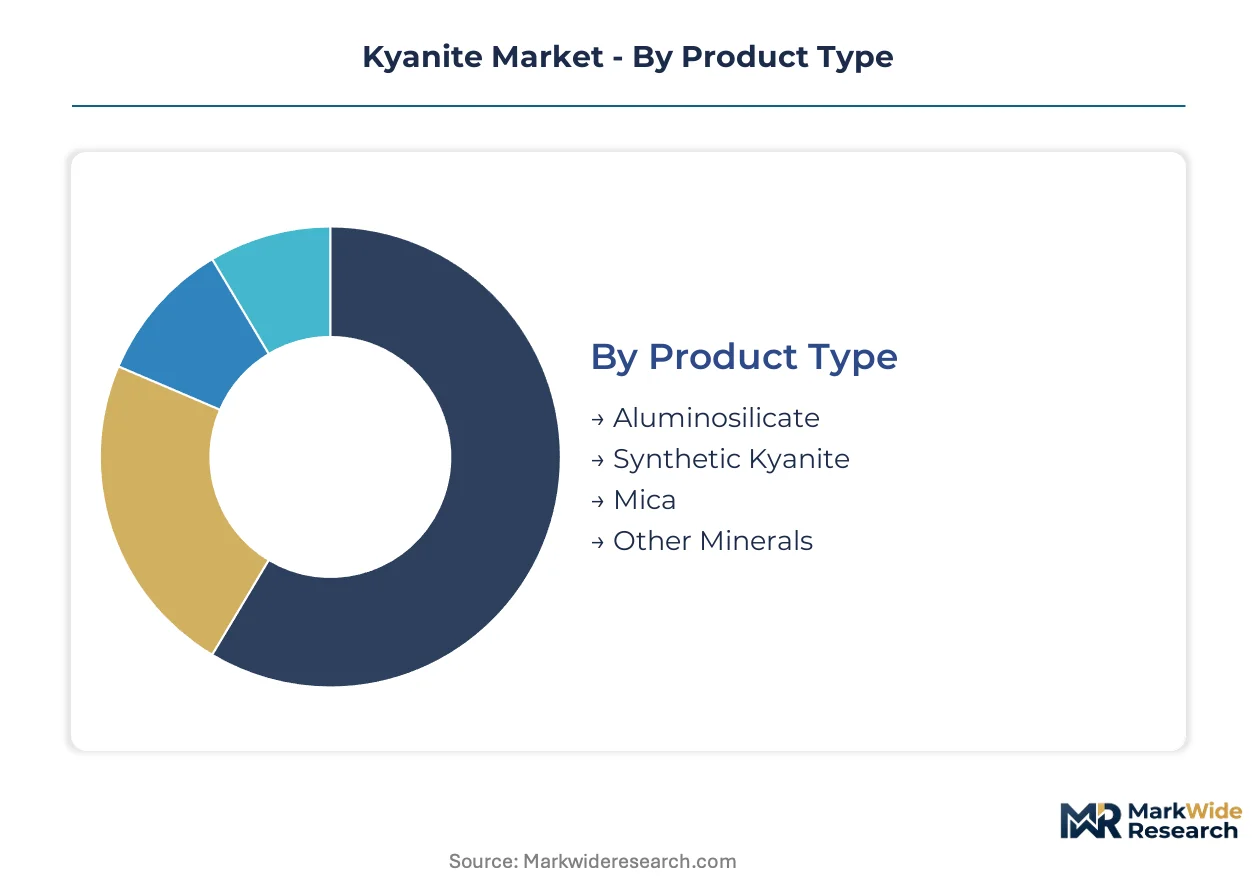
Kyanite market segmentation reveals how substitution economics and regulatory compliance reshape procurement patterns across mineral grades and form factors. Understanding these divides exposes where synthetic alternatives threaten natural mineral positioning and where beneficiation investments defend market share.
Product Type:
Aluminosilicate feedstocks face divergent substitution pressures, with synthetic alternatives compressing margins in standardized specifications while natural mineral reserves retain pricing power in premium thermal shock applications.
- Aluminosilicate:Natural kyanite and related minerals transform to mullite above 1300°C, delivering the thermal stability that blast furnace operators in India and China specify for rebuild cycles. EPA and REACH impurity thresholds are elevating testing costs for undocumented suppliers, consolidating procurement among ISO-certified producers with captive beneficiation streams.
- Synthetic Kyanite:Laboratory-engineered alternatives replicate phase transformation properties with tighter chemical consistency, threatening natural mineral positioning where thermal shock resistance requirements moderate. German engineering clients now mandate documented phase transformation data, compressing margins for producers lacking in-house calcination analytics.
- Mica:Layered silicate mineral serves complementary insulation roles in high-temperature electrical applications, with demand concentrating in semiconductor packaging substrates where dielectric properties matter.
- Other Minerals:Sillimanite and andalusite polymorphs offer alternative aluminosilicate chemistry for specialized refractory formulations, competing on regional availability and calcination economics.
Aluminosilicate retains volume leadership; synthetic kyanite holds the steepest expansion curve.
Application:
Application segments stratify by thermal management intensity, with steel sector procurement dominating current offtake while electronics applications command premium positioning through precision beneficiation requirements.
- Refractories:Blast furnace and kiln lining systems consume the majority of kyanite volume, with India's PLI scheme redirecting supply chains toward domestic manufacturing capacity. Multi-year procurement contracts with alumina-content price adjustment clauses are locking out spot-market suppliers lacking long-term mineral reserve commitments.
- Electronics:Semiconductor packaging substrates demand precision-grade powders with documented impurity profiles, opening structural demand growth as thermal management requirements intensify in chip fabrication. BIS quality mark expansion creates compliance advantages for early-mover suppliers with certified beneficiation investments.
- Ceramics:Technical ceramic manufacturers specify kyanite for thermal shock resistance in kiln furniture and investment casting shells, with spray-applied lining systems favoring granule and powder form factors.
- Glass:Container and flat glass producers utilize kyanite in regenerator checkerwork and furnace crown applications, competing for supply against steel sector procurement teams.
Refractories commands current volume; electronics claims the most rapid demand acceleration.
End User:
End user concentration reflects industrial restructuring patterns, with integrated steel mills consolidating procurement power while aerospace qualification protocols create supplier lock-in effects.
- Manufacturing:Refractory producers and ceramic fabricators drive bulk mineral demand, with procurement teams in India's Maharashtra and Gujarat clusters demanding embedded price adjustment mechanisms.
- Construction:Cement kiln operators specify aluminosilicate linings for clinker production, facing EPA emissions standards that tighten allowable impurity thresholds in mineral feedstocks.
- Aerospace:Jet engine component casting requires premium-grade kyanite with documented trace element profiles, creating long qualification cycles that protect incumbent suppliers.
- Automotive:Catalytic converter substrate manufacturers and foundry operations consume precision-grade powders, with thermal management specifications rising in electric vehicle battery enclosure applications.
Manufacturing absorbs the largest share; aerospace maintains the tightest supplier qualification barriers.
Form:
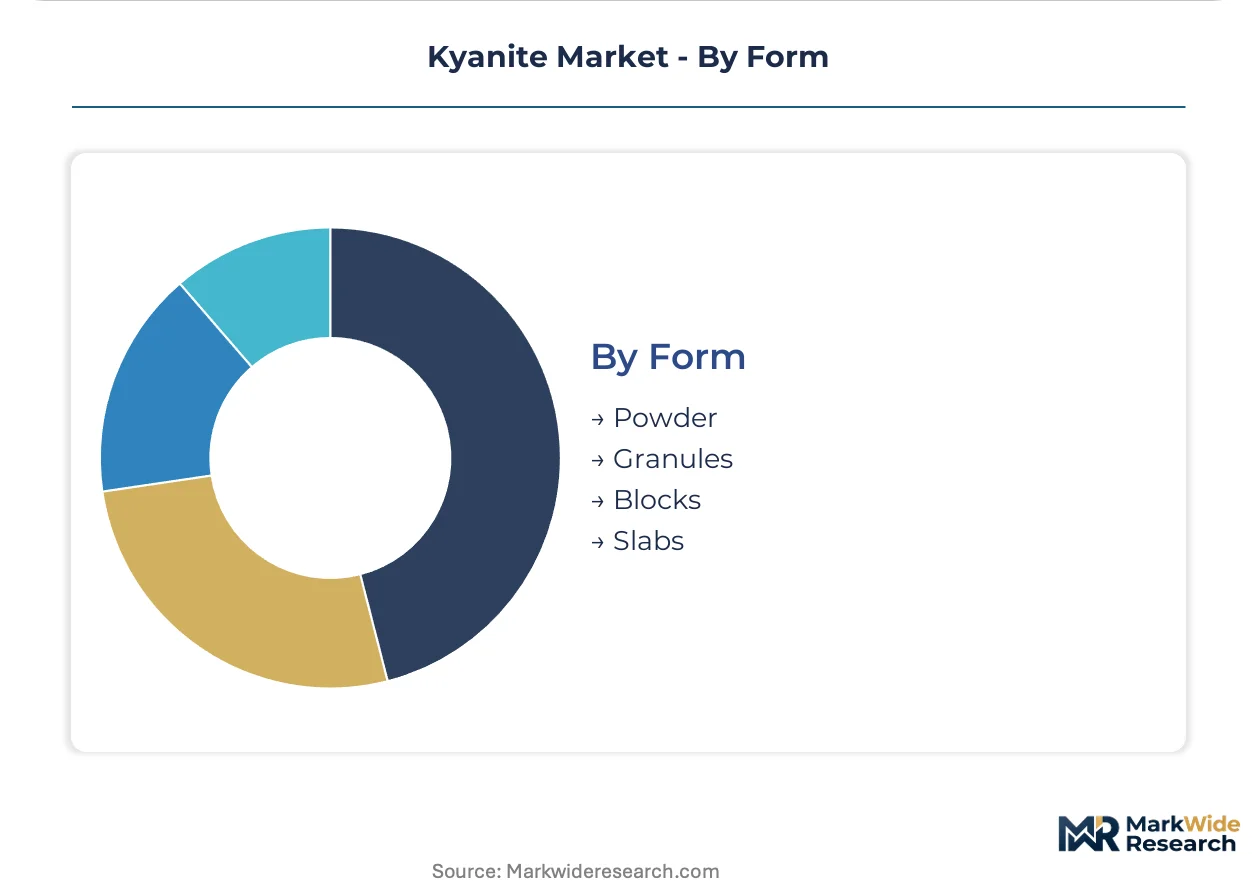
Form factor segmentation tracks processing economics, with powder and granule premiums reflecting beneficiation intensity while block and slab volumes depend on mining scale and transportation logistics.
- Powder:Precision beneficiation to sub-micron particle sizes enables spray-applied lining systems and ceramic substrate fabrication, commanding the steepest price premiums. Great Lakes steel producers consolidate procurement among vendors with pre-certified beneficiation streams.
- Granules:Intermediate sizing suits precision casting investment shells and gunning applications, capturing premium positioning over blocks through versatility in automated application systems.
- Blocks:Raw mineral blocks serve traditional refractory fabrication with lower processing overhead, competing on delivered cost to regional brick and monolithic producers.
- Slabs:Massive cut stone finds limited specialty applications in laboratory furnace construction and artistic ceramic kilns, with volume constrained by handling logistics.
Powder leads value capture; granules expand share fastest in automated application systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel mills and cement producers concentrate procurement power across four major demand centers, each responding to distinct regulatory regimes and industrial restructuring patterns. Geographic sourcing strategies now pivot on carbon border compliance and domestic beneficiation incentives rather than traditional cost arbitrage.
India
Blast furnace rebuild cycles in Maharashtra and Gujarat clusters are accelerating offtake of mullite-forming kyanite. The PLI scheme for specialty minerals redirects supply chains toward domestic refractory manufacturing capacity. Procurement teams in the Mumbai-Pune corridor now demand multi-year agreements with alumina-content price adjustment clauses.
China
Liaoning province mining-to-milling operations anchor supply security for domestic steel sector consumption. MIIT dual carbon targets and GB standards for refractory materials force simultaneous reconfiguration of export-oriented supply chains. Yangtze River Delta ceramic substrate fabricators are sourcing precision-grade powders for semiconductor packaging applications.
United States
Great Lakes steel producers consolidate procurement among vendors with pre-certified beneficiation streams under EPA emissions standards. Blast furnace operators in Indiana and Ohio face tightening allowable impurity thresholds in refractory minerals. The EPA compliance tier is segmenting the North American supply base into certified and non-certified categories.
Germany
Ruhr Valley refractory makers source REACH-registered aluminosilicate feedstocks with documented process controls. ECHA chemical registration requirements filter out undocumented suppliers, consolidating procurement among ISO 9001-certified producers. Technical specification breadth for blast furnace lining contracts now mandates documented phase transformation data at 1300°C.
France
Imerys leverages captive mineral reserves to sustain long-term supply security for European refractory makers. REACH compliance regimes and EU Green Deal carbon border adjustments reshape sourcing economics for domestic steel and cement sectors. Auvergne-Rhône-Alpes industrial clusters prioritize suppliers with integrated mining-to-calcination capabilities.
Kyanite Market Competitive Landscape
Player mix skews toward integrated mining-to-milling operators and specialized refractory mineral traders with technical specification breadth. Market structure concentrates around three strategic archetypes: captive reserve holders with in-house beneficiation, regional traders with certification documentation capabilities, and precision powder specialists serving electronics applications. Dominant competitive moves include backward integration into mining assets and geographic expansion to secure EPA- and REACH-compliant feedstock streams.
Among European-based mineral suppliers, Imerys Refractory Minerals and Alroko GmbH & Co KG exemplify the certification-driven tier, with the former representing captive reserve security and the latter occupying a position defined by technical specification breadth for engineering clients. Great Wall Mineral anchors the Asia-Pacific production vector, its Liaoning province presence exemplifying integrated mining-to-milling scale. These three entities represent the spectrum from reserve-backed supply security to specification-intensive trading.
| Leading Market Players |
|---|
| Kyanite Mining Corporation |
| Imerys Refractory Minerals |
| Great Wall Mineral |
| Anand Talc |
| Alroko GmbH & Co KG |
| Henan Tongbaishan Refractory |
| Resco Products, Inc. |
| LKAB Minerals |
| Yilong Refractory Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with alumina-content indexation lock in supply access for Great Lakes steel producers while compressing margin visibility for spot-market suppliers lacking captive mineral reserves. India's PLI scheme beneficiaries now demand embedded price adjustment clauses that transfer calcination cost volatility upstream to beneficiation operators.
Pricing Analysis
Cost-plus contracts with alumina-content indexation dominate procurement between Maharashtra steel mills and Liaoning province suppliers. Price differentiation hinges on ISO 9001 certification tier and documented phase transformation data at 1300°C. Pricing pressure stems from fused mullite substitution in moderate thermal shock applications. Integrated steel mills exhibit lowest price sensitivity; spot-market ceramic fabricators face acute margin compression.
Supply Chain Analysis
China and India anchor mining-to-milling capacity, while Madagascar and France provide captive reserve security for European refractory makers. Feedstock flows draw from kyanite ore, calcined mullite intermediates, and precision beneficiation chemicals. Single-source vulnerability concentrates in Madagascar's export dependence for EU REACH-compliant supply. Distribution runs through integrated refractory producers and specialized mineral traders with certification documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated steel mills in India and the Great Lakes region, with procurement teams consolidating multi-year supply agreements that lock out fragmented spot-market suppliers.
For Market Incumbents: Compound captive reserve security through backward integration into Madagascar or Liaoning mining assets. Invest in in-house calcination analytics to defend margin position against synthetic mullite substitution. Prioritize BIS quality mark pre-certification to capture India's PLI scheme procurement flows before compliance documentation requirements harden. For New Entrants and Emerging Players: Precision beneficiation services for semiconductor packaging substrates represent an under-served service layer where incumbent mineral traders lack electronics-grade process controls. Target Yangtze River Delta ceramic substrate fabricators with documented impurity profiling capabilities. Lead with spray-applied lining system compatibility as the technical wedge against block-and-slab incumbents. For Investors and Strategic Acquirers: ISO-certified mid-tier beneficiation operators with latent electronics-grade capacity present the most compelling acquisition target archetype. Long-term viability favors suppliers with dual EPA-REACH compliance exposure across North American and European steel sectors. Watch for BIS quality mark expansion announcements as the inflection signal for India's supply chain redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining Assets | Madagascar and Liaung reserves secure long-term feedstock access against REACH compliance bottlenecks. |
| Electronics-Grade Beneficiation Investment | Precision powder capacity captures semiconductor packaging substrate demand from Yangtze Delta fabricators. |
| Multi-Regional Certification Stacking | Simultaneous EPA, REACH, and BIS compliance unlocks procurement from steel mills across three continents. |
| Spray-Applied Lining System Compatibility | Granule and powder form factors displace blocks in automated refractory application systems. |
| Long-Term Offtake Agreement Structuring | Alumina-content indexation transfers calcination cost risk while locking out spot-market competitors. |
Research Methodology
Operator-level perspectives from blast furnace procurement managers, refractory plant engineers, mineral beneficiation technicians, and ceramic substrate R&D directors anchored the qualitative base. Primary fieldwork combined with secondary validation against customs trade data, SEC 10-K filings from listed refractory producers, BIS certification registries, and ECHA REACH registration databases. Bottom-up volume estimates from individual mining operations triangulated against top-down steel sector consumption models.
Sensitivity analysis tested forecast robustness across alternative mullite substitution rates and regulatory compliance cost scenarios over the projection horizon. The analytical framework modeled segmentation across mineral grade tier, end-use application, form factor, and regional production hub. CAGRs were derived from fitted growth curves applied to steel sector rebuild cycle timing and electronics thermal management demand trajectories. Key inputs included blast furnace lining replacement schedules and semiconductor packaging substrate fabrication capacity expansion plans.
Forecasts assume regulatory continuity in EPA emissions standards, REACH chemical registration requirements, and India's PLI scheme implementation; material policy shifts would require re-modeling. Specific risks include fused mullite technology cost breakthroughs, carbon border adjustment mechanism expansion, and artisanal supplier documentation gap closures. Recalibration cycles align with material shifts in steel sector procurement consolidation patterns and electronics-grade beneficiation capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Barite Mining Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Perlite Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Talc Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Boron Minerals and Chemicals Market