
 Bentonite Market | 2026-2036
Bentonite Market Size, Share, and Industry Trends Forecast 2026-2036
Bentonite Market Analysis
REACH compliance in Europe is decoupling low-purity bentonite suppliers from premium supply chains, forcing capital-intensive purification upgrades across the value chain. Minerals Technologies Inc. leverages its integrated mining and processing footprint to sustain cost advantages in API-grade output. Wyo-Ben, Inc. anchors its competitive position through captive reserves in Wyoming's Northern Black Hills district. Imerys competes by extending its specialty minerals portfolio into cosmetic-grade bentonite for European personal care formulators.
Bentonite is a colloidal, absorbent aluminium phyllosilicate clay composed primarily of montmorillonite, with sodium and calcium variants distinguished by their base-exchange capacity and swelling index; it forms thixotropic gels in aqueous suspension, making it indispensable for viscosity control and fluid loss prevention in industrial processes. Sodium bentonite dominates drilling fluid formulations due to superior swelling capacity, while calcium bentonite leads binding agent applications in iron ore pelletization where lower swelling suffices. API grade commands the largest volume share in petroleum end-use, though food grade and cosmetic grade segments concentrate margin pools through stringent purity certifications and smaller batch production economics.
The US EPA regulates bentonite in drilling applications through discharge standards under the Clean Water Act, while the FDA governs food-grade and cosmetic-grade purity thresholds for direct consumer contact. Europe's ECHA enforces REACH registration for montmorillonite-based substances, creating documentation burdens that favor larger producers with dedicated regulatory affairs capacity. India's BIS mandates ISI certification for bentonite used in foundry and drilling applications, shaping import quality filters. Stakeholders must monitor evolving frac-fluid disclosure rules in Texas and North Dakota, as chemical transparency mandates reshape procurement specifications and supplier qualification protocols.
Market Dynamics
REACH registration requirements in Europe are decoupling low-purity bentonite suppliers from premium supply chains, forcing capital-intensive purification upgrades that reshape competitive positioning across the value chain.
Growth Catalysts
- Drilling fluid demand:Petroleum operators in the United States and Middle East are pulling higher-performance sodium bentonite for extended-reach horizontal wells, tightening API-grade specifications.
- REACH compliance:ECHA documentation mandates favor producers with dedicated regulatory affairs capacity, consolidating supply relationships around certified European importers.
- Iron ore pelletization:Steelmakers in Brazil and Australia require calcium bentonite binders with consistent base-exchange capacity to meet sintering efficiency targets.
Market Restraints
- Wyoming supply concentration:Global sodium bentonite availability hinges on Northern Black Hills mining districts, creating single-source vulnerability for API-grade formulations.
- Energy input volatility:Natural gas and diesel costs drive drying and grinding operations, compressing margins for non-integrated processors.
- Substitute materials:Polymer-based synthetic drilling fluids from engineered chemistry suppliers are capturing share in high-temperature well applications.
Strategic Opportunities
- Cosmetic-grade expansion:European personal care formulators seek montmorillonite with heavy metal certification below FDA thresholds, opening premium batch-production economics.
- India foundry demand:BIS-mandated ISI certification for bentonite in metal casting creates qualified-supplier scarcity that integrated miners can exploit.
- Green chemistry alignment:EU Green Deal bio-based material preferences position natural clay additives favorably against synthetic alternatives in packaging and agriculture.
Industry Challenges
- Geologist and process engineer scarcity:Wyoming mining districts face talent competition from lithium and rare earth operations, delaying expansion timelines.
- API certification backlog:Testing queue congestion at accredited laboratories extends product qualification cycles for new mine entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bentonite Market |
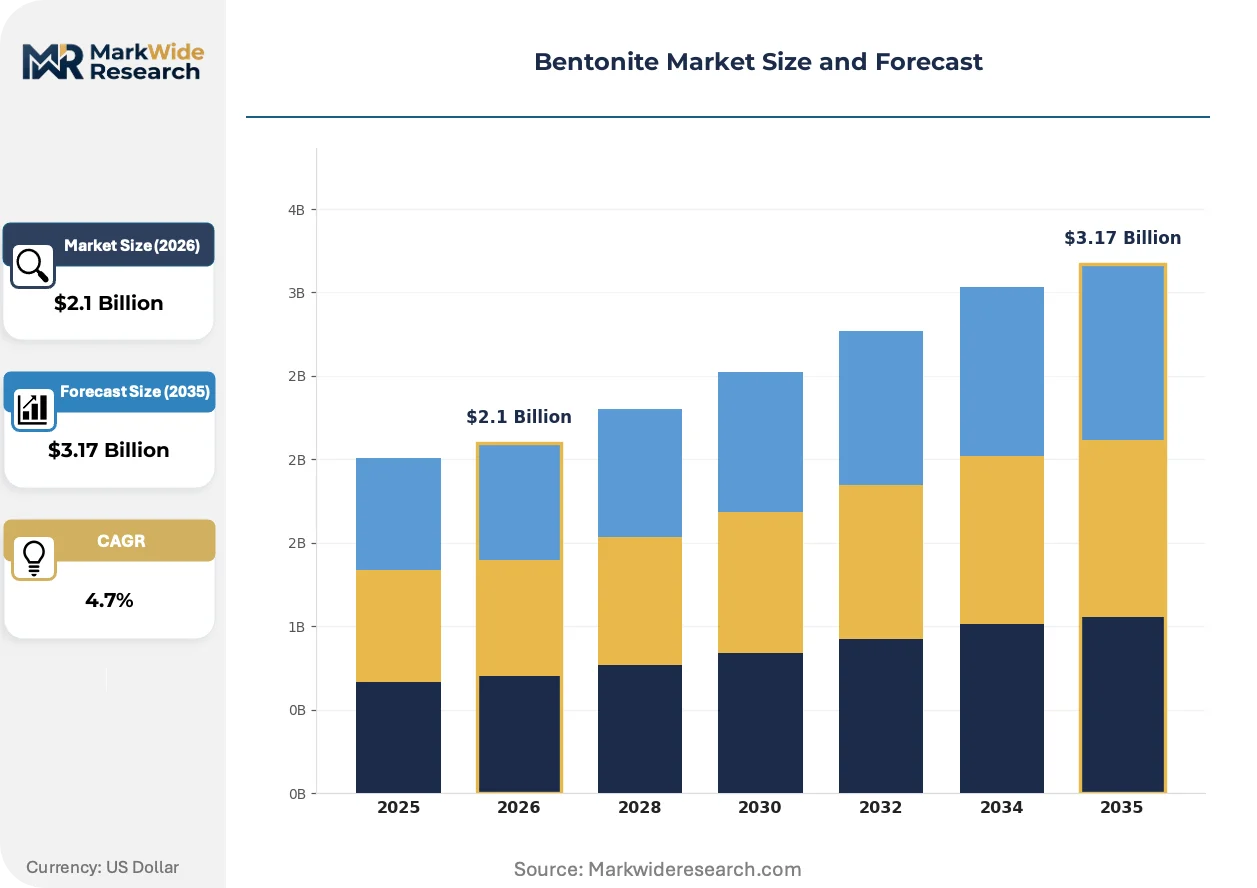
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bentonite, Calcium Bentonite, Potassium Bentonite, Magnesium Bentonite End Use Industry: Petroleum, Construction, Agriculture, Pharmaceuticals Grade: API Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Drilling Fluids, Binding Agents, Sealants, Absorbents |
| Companies Covered | Clariant, Black Hills Bentonite, LLC, Minerals Technologies Inc., American Colloid Company, Kunimine Industries Co., Ltd., Wyo-Ben, Inc., Ashapura Group of Companies, Halliburton Co., Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bentonite Market Emerging Trajectories
Processing technology is modularizing around smaller-scale, regional purification units that reduce transport costs and enable faster response to grade-specific demand spikes.
Surface modification chemistry for organophilic bentonite is modularizing around silane coupling and quaternary ammonium treatments that expand compatibility with oil-based drilling fluids. Offshore rig operators in the Gulf of Mexico are specifying these grades for deepwater pressure conditions. The shift is compressing demand for unmodified sodium bentonite in premium applications.
Texas Railroad Commission frac-fluid disclosure rules now mandate chemical transparency for all additives above threshold volumes. Operators must submit supplier qualification documentation that includes bentonite source mine and processing location. This is reshaping procurement specifications toward vertically integrated producers with captive Wyoming reserves.
Direct mine-to-formulator contracting is displacing layered distributor networks in cosmetic and food-grade segments. European personal care brands now require batch traceability to specific Wyoming or Turkish extraction sites. This pattern is most visible in German and French markets where EFSA purity audits have intensified.
Bentonite Market Segmentation
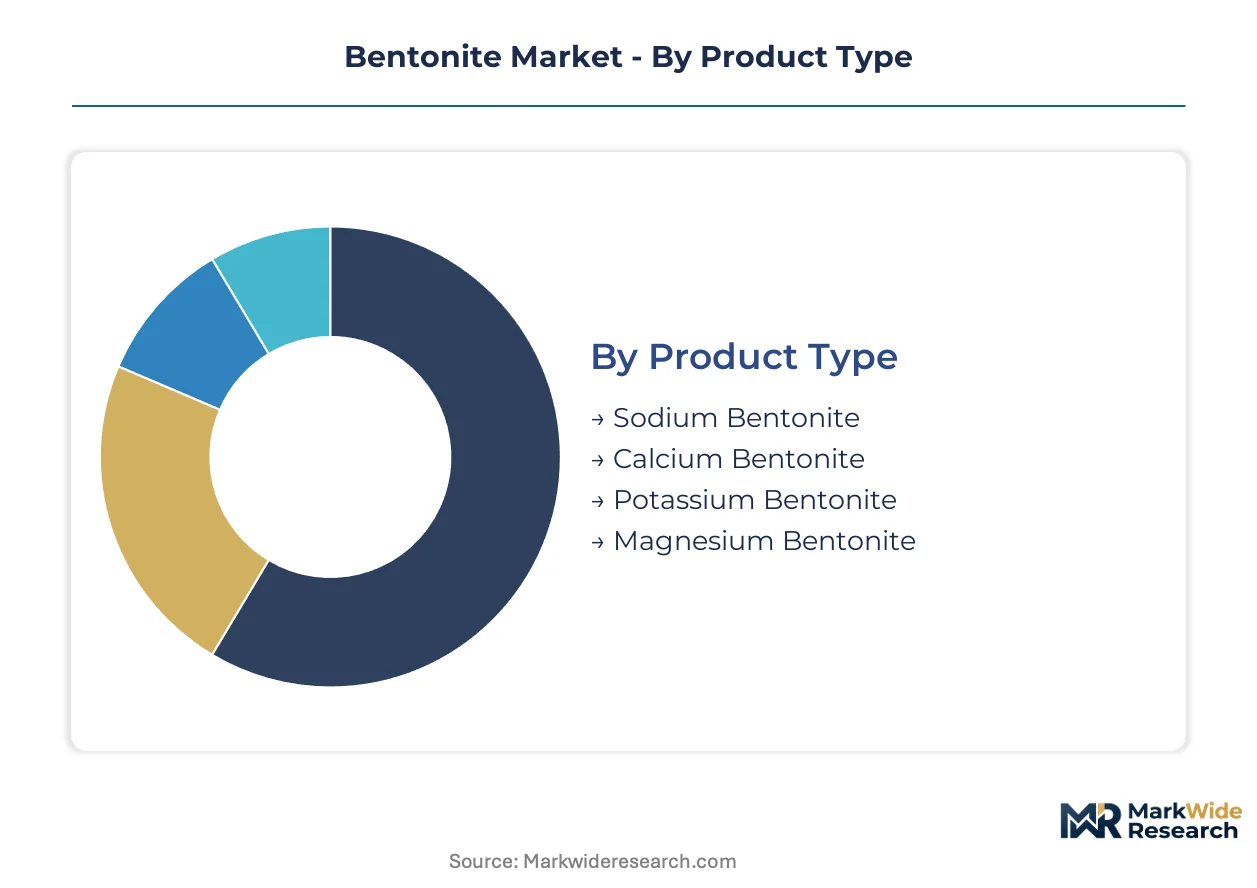
Bentonite's commercial value hinges on grade-specific certification thresholds that gate access to premium end-uses. Each segmentation dimension carries distinct regulatory burdens that reshape supplier economics and customer qualification cycles.
Product Type:
API certification demands diverge sharply across ion-exchange variants, with sodium bentonite facing the most stringent documentation for petroleum applications.
- Sodium Bentonite:High-swelling montmorillonite with superior colloidal properties in aqueous suspension. Petroleum operators in Texas and North Dakota specify this variant for extended-reach horizontal wells, tightening purity requirements under Railroad Commission disclosure rules.
- Calcium Bentonite:Lower base-exchange capacity produces reduced swelling indices suitable for binding applications. Brazilian and Australian steelmakers concentrate demand here for iron ore pelletization, where consistent sintering efficiency overrides swelling performance.
- Potassium Bentonite:Intermediate ionic properties serve specialized foundry applications in India under BIS-mandated ISI certification protocols.
- Magnesium Bentonite:Niche agricultural conditioning segment with limited API pathway, primarily sourced from Turkish deposits for European soil amendment formulators.
Leading the category by volume: Sodium Bentonite. Growing fastest: Calcium Bentonite as Brazilian steel capacity expands.
End Use Industry:
Customer procurement power varies enormously, with petroleum majors demanding captive mine traceability while construction buyers prioritize cost over documentation depth.
- Petroleum:Drilling fluid formulators dominate absolute tonnage. Wyoming-sourced sodium bentonite with API certification commands supply chain priority as Railroad Commission rules mandate chemical transparency.
- Construction:Geotechnical sealant and slurry wall applications absorb calcium grades. Project-scale procurement from Brazilian infrastructure developers drives regional sourcing patterns.
- Agriculture:Soil amendment and feed pellet binding use lower-purity calcium variants. Turkish suppliers capture European demand under EFSA feed additive guidelines.
- Pharmaceuticals:Excipient and detoxification applications require FDA drug master file submissions. Batch-scale economics favor integrated miners with dedicated regulatory affairs capacity.
Highest margin capture: Pharmaceuticals. Steepest expansion trajectory: Petroleum as Permian Basin drilling intensity sustains.
Grade:
Certification tier directly determines pricing architecture, with API and food grades separating from industrial grades through laboratory testing queues.
- API Grade:American Petroleum Institute specifications govern viscosity and fluid loss in drilling applications. Wyoming producers with integrated testing laboratories sustain qualification advantages as accredited facility backlogs extend.
- Food Grade:FDA and EFSA purity thresholds for direct consumer contact mandate heavy metal certification below specified thresholds. European personal care brands now require batch traceability to specific extraction sites.
- Industrial Grade:Foundry and construction applications tolerate higher impurity loads. Indian BIS certification creates qualified-supplier scarcity that shapes import filters.
- Cosmetic Grade:Heavy metal thresholds stricter than FDA minimums open premium batch-production economics for German and French formulators.
Dominant by volume: API Grade. Gaining share fastest: Cosmetic Grade as clean beauty positioning intensifies.
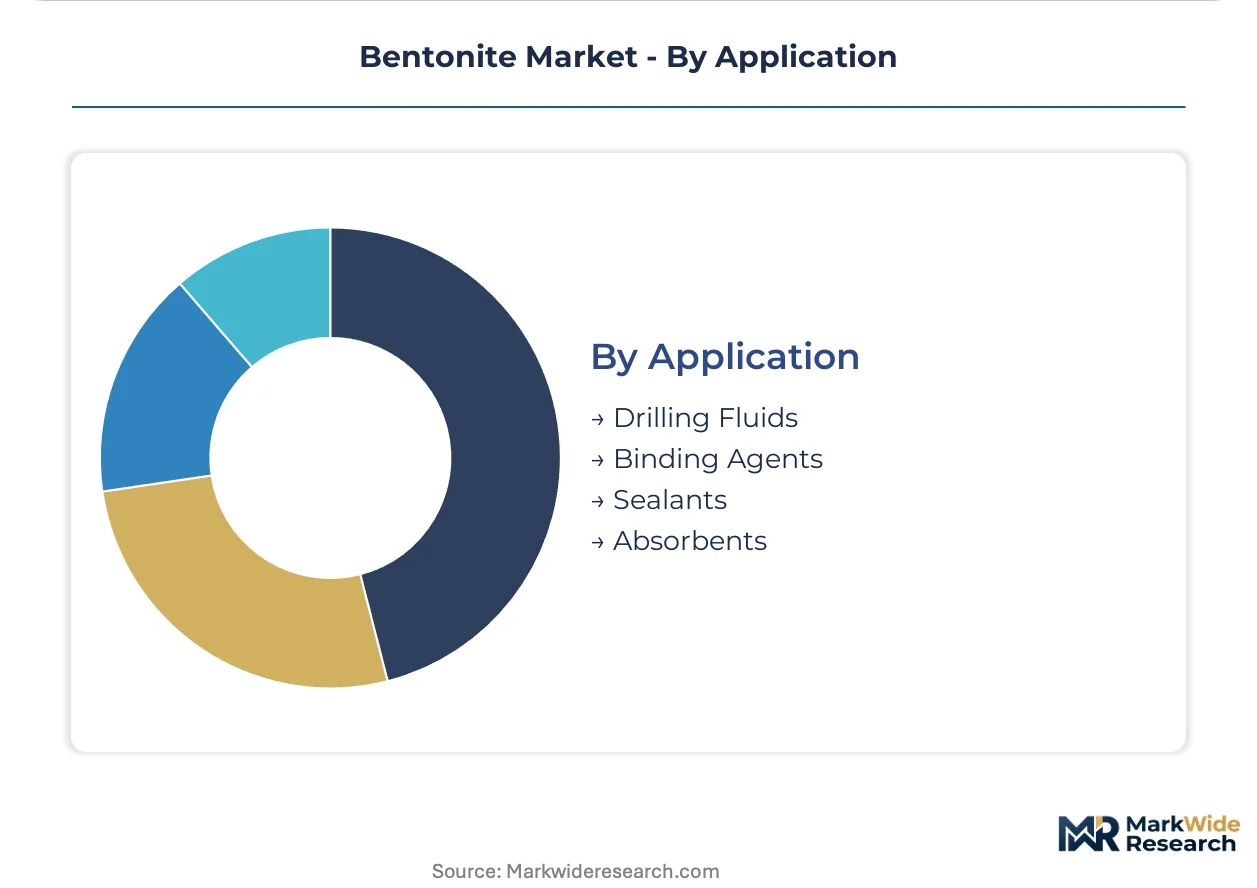
Application:
Functional performance requirements segment the market by rheological specification depth, with drilling fluids demanding the most intensive quality assurance.
- Drilling Fluids:Thixotropic gel formation and fluid loss prevention govern petroleum extraction economics. Gulf of Mexico offshore operators increasingly specify organophilic surface-modified grades for deepwater pressure conditions.
- Binding Agents:Iron ore pelletization in Brazil and Australia consumes calcium bentonite with calibrated base-exchange capacity. Sintering efficiency targets drive consistent specification enforcement.
- Sealants:Geotechnical containment and pond lining applications use lower-cost calcium variants with sufficient swelling for hydraulic barrier performance.
- Absorbents:Spill remediation and cat litter markets prioritize cost-effective calcium grades with rapid liquid uptake characteristics.
Largest volume position: Drilling Fluids. Climbing fastest: Binding Agents as Australian iron ore exports sustain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wyoming's Powder River Basin tax-incentive zones concentrate sodium bentonite mining operations, anchoring global API-grade supply chains. Special economic zones in Gujarat and Minas Gerais accelerate processing capacity buildouts for regional foundry and steel markets.
United States
Permian Basin drilling operators in Texas and North Dakota drive API-grade sodium bentonite consumption for extended-reach horizontal wells. The Texas Railroad Commission mandates chemical transparency for frac-fluid additives above threshold volumes, forcing mine-to-processing traceability documentation. Wyoming's Northern Black Hills district hosts the bulk of captive mining operations serving petroleum majors with integrated supply chains.
Brazil
Steelmakers in Minas Gerais and Pará consume calcium bentonite binders for iron ore pelletization as export capacity expands. ANVISA governs food-grade purity thresholds for agricultural applications, filtering import quality standards. The Quadrilátero Ferrífero mining cluster near Belo Horizonte concentrates domestic bentonite blending operations for sintering efficiency targets.
India
Foundries in Maharashtra and Tamil Nadu pull bentonite for metal casting under BIS-mandated ISI certification protocols. The central government's PLI scheme for specialty chemicals incentivizes domestic purification upgrades. Gujarat's Kutch district hosts processing infrastructure serving western Indian industrial corridors with construction-grade material.
Germany
Personal care formulators in North Rhine-Westphalia and Bavaria source cosmetic-grade montmorillonite with heavy metal certification below FDA thresholds. ECHA enforces REACH registration for montmorillonite-based substances, consolidating supply relationships around certified importers. The Cologne-Düsseldorf corridor concentrates batch-scale blending operations for clean beauty brands.
Australia
Pilbara iron ore exporters in Western Australia specify calcium bentonite binders with calibrated base-exchange capacity for sintering efficiency. The country's national mining regulator enforces environmental discharge standards for tailings management, shaping procurement specifications. Perth-based mineral traders coordinate Pacific Rim supply chains linking Turkish and Chinese processors to Australian steelmakers.
Bentonite Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification segments. The vendor base stratifies around integrated miners with captive Wyoming reserves, regional processors serving single-country markets, and specialty chemical distributors handling cosmetic-grade batch logistics. Three archetypes dominate: upstream-integrated miners controlling extraction and API certification, midstream purifiers upgrading industrial grades for food and pharmaceutical compliance, and downstream formulators blending surface-modified variants for oil-based drilling fluids. Competitive moves center on backward integration into Wyoming mining districts and capacity expansion in Indian BIS-certified processing.
Among diversified mineral conglomerates, Clariant and Imerys exemplify portfolio-broad strategies spanning multiple specialty clay segments. Wyo-Ben, Inc. occupies a position representing captive-reserve pure-plays with Northern Black Hills extraction assets. These three anchors illustrate the structural tension between geographic concentration in Wyoming and regulatory-driven purification investments in Europe and India.
| Leading Market Players |
|---|
| Clariant |
| Black Hills Bentonite, LLC |
| Minerals Technologies Inc. |
| American Colloid Company |
| Kunimine Industries Co., Ltd. |
| Wyo-Ben, Inc. |
| Ashapura Group of Companies |
| Halliburton Co. |
| Imerys |
| Others |
Supply Flow & Price Mechanics
Family-owned Wyoming mining operations with multi-generational reserve holdings anchor supply discipline through controlled release of API-grade inventory, translating geological scarcity into pricing power that resists spot-market volatility. Their refusal to accelerate extraction rates despite petroleum operator pressure sustains premium realizations for sodium bentonite with documented Northern Black Hills provenance.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines reward processors maintaining finished-goods inventory near Permian Basin drilling clusters. Three-tier pricing structure across API-certified premium, food-grade standard, and industrial economy levels segments buyers by documentation burden tolerance. Cost compression in industrial-grade supply is intensifying because Turkish and Chinese exporters are expanding calcium bentonite pelletization volumes. Construction contractors in Brazilian infrastructure projects exhibit the highest price sensitivity, while Gulf of Mexico offshore operators demonstrate minimal elasticity for organophilic surface-modified grades.
Supply Chain Analysis
Freight costs from Wyoming's Powder River Basin to Texas railheads add twelve to eighteen percent to delivered API-grade material, favoring processors with unit-train loading facilities. Supply concentrates in the United States, Turkey, and India, with Wyoming sodium bentonite feeding petroleum applications while Turkish calcium grades serve European agriculture. Mining operations draw from diesel fuel, natural gas for drying, and ammonium compounds for surface modification chemistry. Single-source vulnerability runs through Northern Black Hills mining districts where geologist scarcity delays expansion timelines. Distribution runs through vertically integrated petroleum service companies with captive blending facilities near active drilling permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Wyoming mining districts has become the decisive competitive race, with processors securing reserve positions to guarantee API certification continuity as Railroad Commission traceability rules harden.
For Market Incumbents: Cement supply security through long-term lease arrangements with family-owned Wyoming reserve holders before geologist talent competition from lithium operations intensifies. Expand in-house testing laboratory capacity to bypass accredited facility backlogs that delay new product qualification. Synthetic polymer drilling fluid substitutes from engineered chemistry suppliers represent the primary substitution threat requiring performance-based differentiation. For New Entrants and Emerging Players: Enter via BIS-certified processing capacity in Gujarat's Kutch district, where foundry demand under ISI protocols creates qualified-supplier scarcity that integrated miners have not fully exploited. Cosmetic-grade montmorillonite for German and French personal care formulators offers the most penetrable premium segment. Direct mine-to-formulator contracting with batch traceability documentation provides the essential go-to-market credential. For Investors and Strategic Acquirers: API certification backlog clearance at accredited laboratories is the leading indicator that new mine entrants will achieve product qualification and challenge incumbent pricing power. Long-term viability hinges on reserve life exceeding twenty years with demonstrated compliance continuity across EPA discharge standards and REACH documentation. Target processors with captive Wyoming reserves and established Railroad Commission supplier qualification protocols. Watch for frac-fluid disclosure rule expansions beyond Texas and North Dakota as the signal for traceability documentation becoming a non-negotiable procurement filter.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wyoming Reserves | Captive Northern Black Hills extraction secures API-grade supply continuity under Railroad Commission rules. |
| Capacity Expansion in BIS-Certified Processing | Gujarat-based ISI-compliant facilities capture foundry demand from Maharashtra and Tamil Nadu metal casters. |
| Surface Modification Chemistry Investment | Organophilic grade production qualifies supply for Gulf of Mexico deepwater pressure specifications. |
| Long-term Supply Agreement with Steelmakers | Calibrated base-exchange capacity contracts lock in Brazilian and Australian iron ore pelletization volumes. |
| Cosmetic-Grade Purification Upgrade | Heavy metal certification below FDA thresholds opens premium batch economics for European clean beauty brands. |
Methodological Framework
Independent corroboration across plant managers at Wyoming processing facilities, procurement leads at Permian Basin petroleum operators, and distribution channel partners in European personal care supply chains underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at surface modification chemistry specialists and regulatory affairs staff at REACH-registered importers combined with secondary validation from SEC 10-K filings, customs and trade data, and American Petroleum Institute certification records. Bottom-up volume estimates from grade-specific production capacities triangulate against top-down demand assessments from end-use industry consumption patterns.
Comparable-period anchoring to historical API-grade pricing and volume trajectories established the forecast window baseline across the analysis window. The analytical framework models segmentation dimensions including ion-exchange variant, end-use industry, certification grade tier, and regional production hub. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and substitution dynamics. Forecast inputs incorporate petroleum drilling intensity projections, Brazilian steel capacity expansion schedules, and European REACH documentation burden evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained natural gas price volatility affecting drying operations and accelerated synthetic polymer substitution in high-temperature well applications. Forecasts reflect assumptions regarding Wyoming reserve depletion rates, geologist labor market competition, and accredited laboratory capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Solar Salt Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
North America Silica Sand Market