
 Mineral Wool Material Market | 2026-2036
Mineral Wool Material Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Wool Material Market Analysis
Modular insulation panel systems is restructuring buyer choice across commercial and industrial construction, replacing loose-fill installations with pre-configured assemblies that cut on-site labor. ROCKWOOL International leverages its stone wool expertise to dominate high-temperature industrial applications. Johns Manville anchors North American distribution through extensive contractor networks and specification relationships. Saint-Gobain differentiates via integrated building envelope solutions that bundle mineral wool with complementary membranes and sealants.
Mineral wool material comprises inorganic fibers manufactured from molten rock, slag, or glass at temperatures exceeding 1,400°C, yielding a non-combustible matrix with thermal conductivity ratings typically between 0.030 and 0.045 W/m·K and service temperatures up to 750°C depending on fiber composition. Glass wool holds mature volume leadership in residential and light commercial thermal insulation where cost sensitivity dominates specification decisions. Rock wool commands premium positioning in fire protection and industrial process insulation where non-combustibility requirements exclude organic alternatives. Slag wool competes on raw material cost advantage in regions with proximate steel production, though its application scope narrows against stricter purity standards.
REACH and the EU Green Deal shape product chemistry and embodied carbon thresholds for mineral wool sold across European markets, while the EPA and OSHA set airborne fiber exposure limits that govern manufacturing protocols and installation practices in the United States. Building codes in Germany, France, and Poland now mandate minimum insulation performance tiers that directly expand addressable mineral wool volume in retrofit and new construction. Stakeholders must monitor evolving carbon border adjustment mechanisms and national renovation wave commitments that will recalibrate competitive positioning between domestic production and import supply.
Market Dynamics
Building energy performance mandates across the European Union are compressing specification timelines and forcing rapid material substitution in retrofit and new construction pipelines.
Growth Catalysts
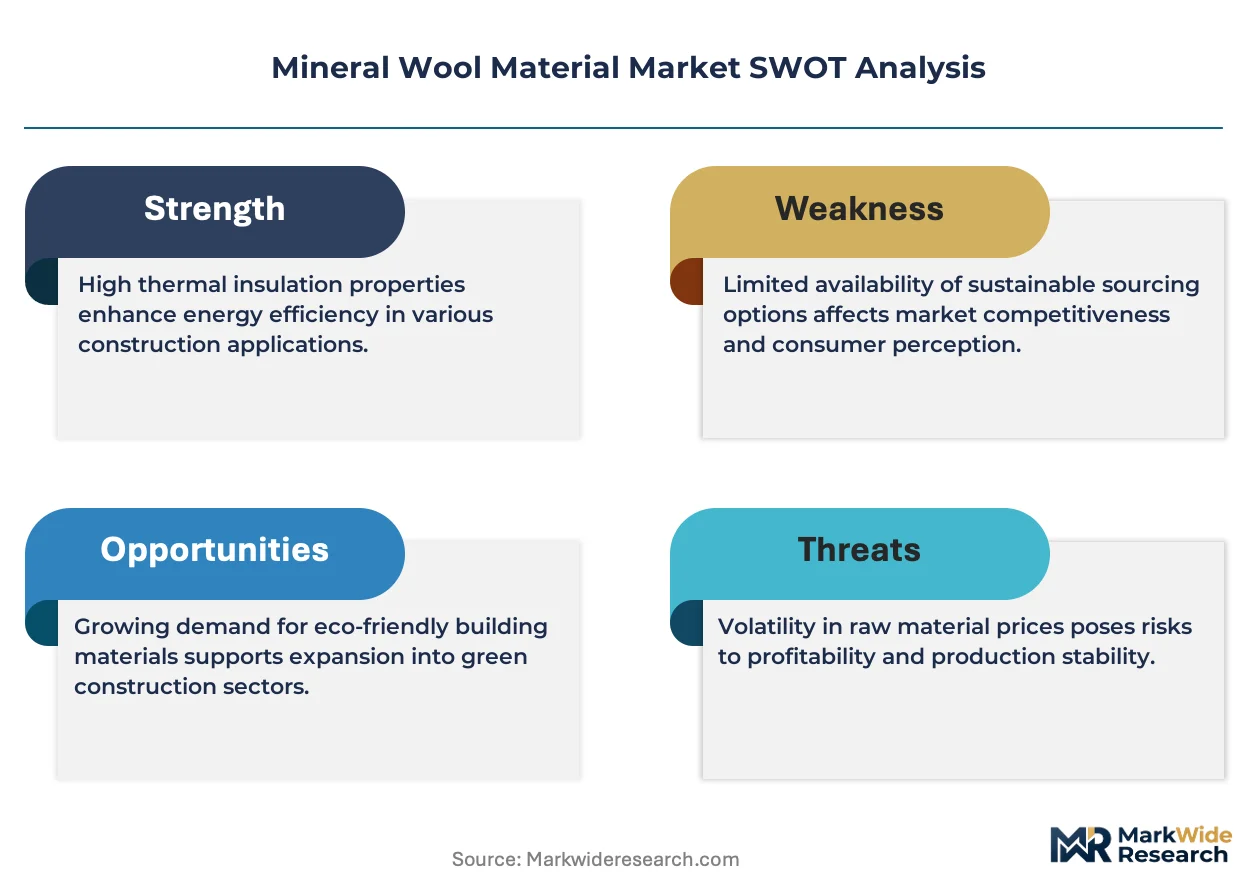
- EU Green Deal renovation wave:Binding national targets for building stock decarbonization are mandating mineral wool installation rates that outpace organic insulation alternatives in Germany, France, and Poland.
- Non-combustibility requirements:Updated fire safety codes for high-rise residential and commercial towers are excluding plastic foam insulants from facade and cavity applications.
- Industrial process heat recovery:Steel, cement, and chemical manufacturers are specifying rock wool for exhaust duct and furnace insulation above 600°C service temperatures.
Market Restraints
- Basalt and slag input cost volatility:Proximity to steel production centers determines raw material economics, leaving distant manufacturers exposed to freight-adjusted cost spikes.
- Airborne fiber exposure limits:OSHA permissible exposure limits and REACH registration requirements impose capital-intensive abatement systems on older production lines.
- Polyisocyanurate substitution in light commercial:Higher R-value per inch and thinner profile requirements are displacing glass wool in roof assemblies where space constraints dominate.
Strategic Opportunities
- Prefabricated building envelope panels:Offsite construction manufacturers in the Netherlands and Scandinavia are integrating mineral wool cores into factory-built wall and roof cassettes.
- Carbon border adjustment positioning:Domestic European producers with verified low-embodied-carbon processes will capture margin premiums as CBAM phases in for construction materials.
- Data center thermal management:Fire-safe containment of lithium-ion battery energy storage systems is creating specification pull for rock wool barrier systems.
Industry Challenges
- Installation certification bottlenecks:Qualified contractor scarcity in Eastern European markets is extending project timelines and raising labor cost premiums.
- Legacy building stock assessment complexity:Moisture diagnostics and structural compatibility studies are adding 15-25% soft cost overhead to deep retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Wool Material Market |
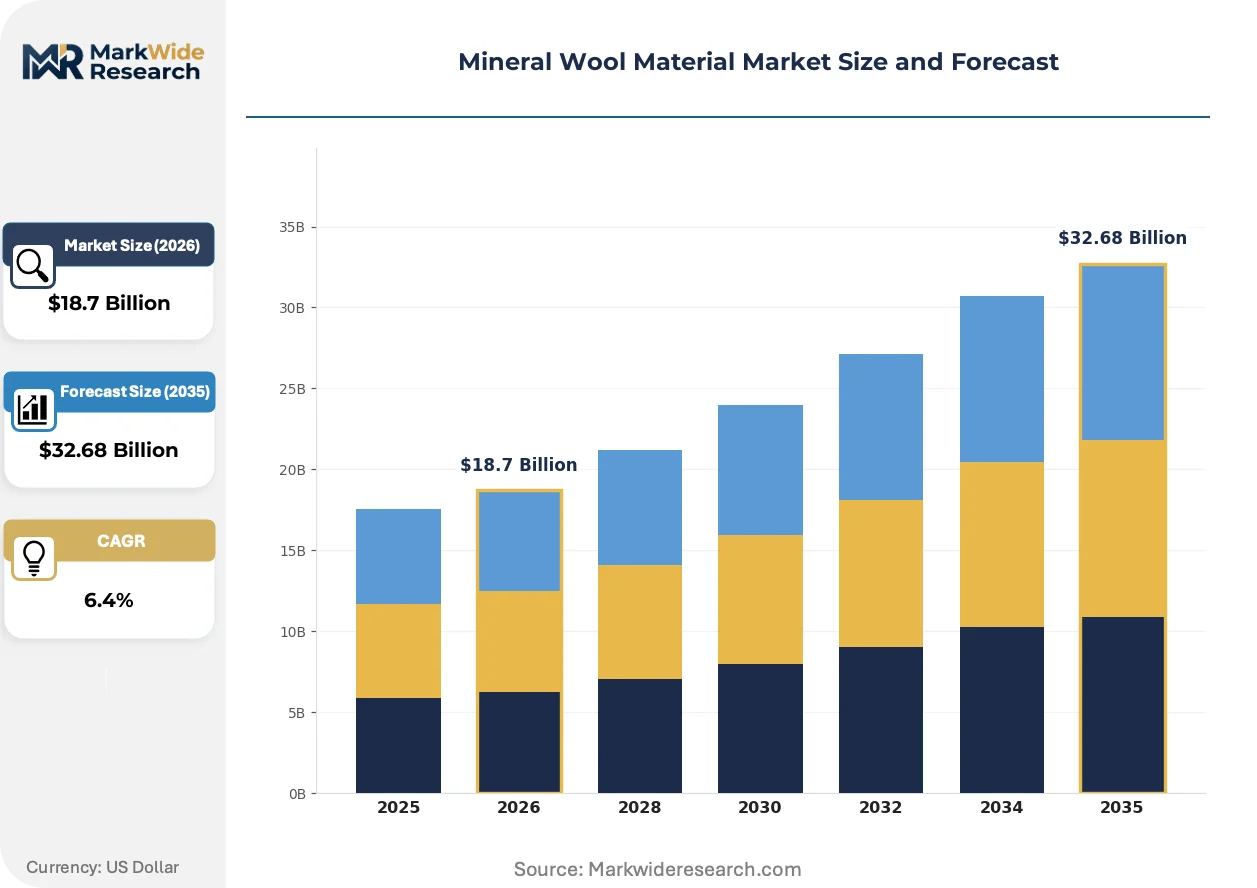
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rock Wool, Glass Wool, Slag Wool, Stone Wool Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Building Materials End User: Construction, Automotive, Marine, Appliances Form: Board, Blanket, Loose Fill, Pre-formed |
| Companies Covered | Knauf Insulation, Luyang Energy-Saving Materials Co., Ltd, ROCKWOOL International, GAF Materials Corporation, Shandong Wiskind Architectural Steel Co., Ltd, Saint-Gobain, Johns Manville, KCC Corporation, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Wool Material Market Emerging Trajectories
Product chemistry, manufacturing process efficiency, and installation methodology are undergoing simultaneous transformation as regulatory pressure tightens and labor availability contracts.
Bio-based binder formulations are converging with traditional phenolic resin systems in glass wool production, yielding lower formaldehyde emissions without sacrificing fiber cohesion. Residential builders in Nordic markets are specifying these products for passive house certification compliance. The technology is converging with automated blowing and injection equipment, compressing installation labor hours by 30-40% in attic and cavity wall applications.
REACH Annex XVII restrictions on formaldehyde-releasing substances are forcing reformulation of legacy binder chemistries across European manufacturing footprints. Industrial consequence includes accelerated R&D spend and qualification delays for modified product lines. Germany's Federal Institute for Risk Assessment and France's ANSES are driving the most stringent interpretation timelines, pushing manufacturers to front-load compliance investments.
Specification decisions are migrating from general contractors to envelope consultants and energy modelers who prioritize whole-building performance over unit cost. Design-build firms and integrated project delivery consortia are consolidating material selection authority in pre-construction phases. This concentration is most visible in commercial office and multifamily residential developments in the Netherlands and Belgium where performance guarantees now dominate procurement criteria.
Mineral Wool Material Market Segmentation
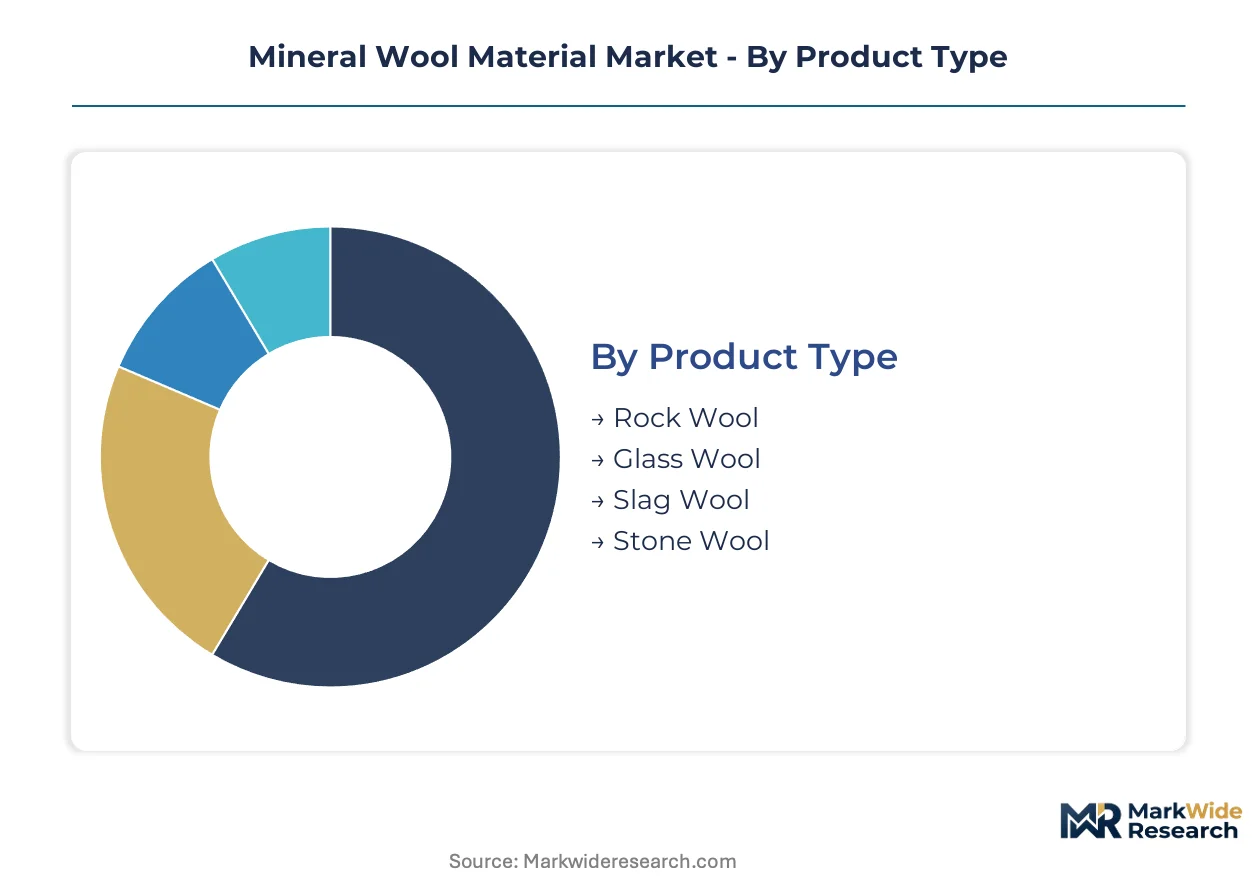
Mineral wool manufacturers configure production assets around fiber chemistry and thermal performance tiers. Specification decisions cascade through product type, application intensity, end-use durability requirements, and installation form factors.
Product Type:
Capital intensity peaks in stone wool and rock wool production where electric arc furnaces and spinners demand the heaviest upfront equipment investment.
- Rock Wool:Basalt-based fibers formed at temperatures exceeding 1,450°C deliver non-combustibility ratings critical for high-rise facade systems. German and French building codes now mandate rock wool for cavity barriers in residential towers exceeding 11 meters.
- Glass Wool:Recycled glass cullet and sand feed continuous rotary processes optimized for thermal conductivity between 0.030 and 0.040 W/m·K. Residential attic retrofits across Poland concentrate volume demand as national renovation wave subsidies accelerate uptake.
- Slag Wool:Steel blast furnace byproduct streams lower raw material costs where mills operate proximate to insulation plants.
- Stone Wool:Premium positioning in industrial process insulation above 600°C service temperatures.
Most installed capacity flows through glass wool. Expansion is steepest in rock wool.
Application:
Performance specifications diverge sharply across thermal, acoustic, and fire-rated use cases.
- Thermal Insulation:Energy modeling for commercial envelopes drives specification toward lambda values below 0.035 W/m·K. Netherlands-based passive house developers are bundling mineral wool with airtight membranes to hit 15 kWh/m²·year targets.
- Fire Protection:Intumescent barriers and cavity fire stops require melt temperatures above 1,000°C. UK and Irish high-rise remediation programs are stripping combustible cladding and substituting rock wool fire breaks.
- Acoustic Insulation:Open-fiber matrices absorb airborne sound across 500-4,000 Hz frequency ranges.
- Building Materials:Composite boards and prefabricated sandwich panels integrate mineral wool cores.
Thermal applications anchor volume. Fire protection is climbing the fastest.
End User:
Construction sector procurement dominates, though transportation and appliance OEMs impose distinct certification regimes.
- Construction:Deep retrofit programs across Germany, France, and Poland are consuming board and blanket forms at rates exceeding new construction pipelines. EU Green Deal national building performance targets are compressing payback period calculations for insulation upgrades.
- Automotive:Engine compartment heat shields and NVH packages require lightweight, compression-resistant mats.
- Marine:IMO fire safety codes mandate A-60 rated bulkhead insulation for passenger vessels.
- Appliances:Oven cavities and water heater jackets specify biosoluble fiber grades.
Construction absorbs the majority of output. Marine retrofit cycles are expanding most quickly.
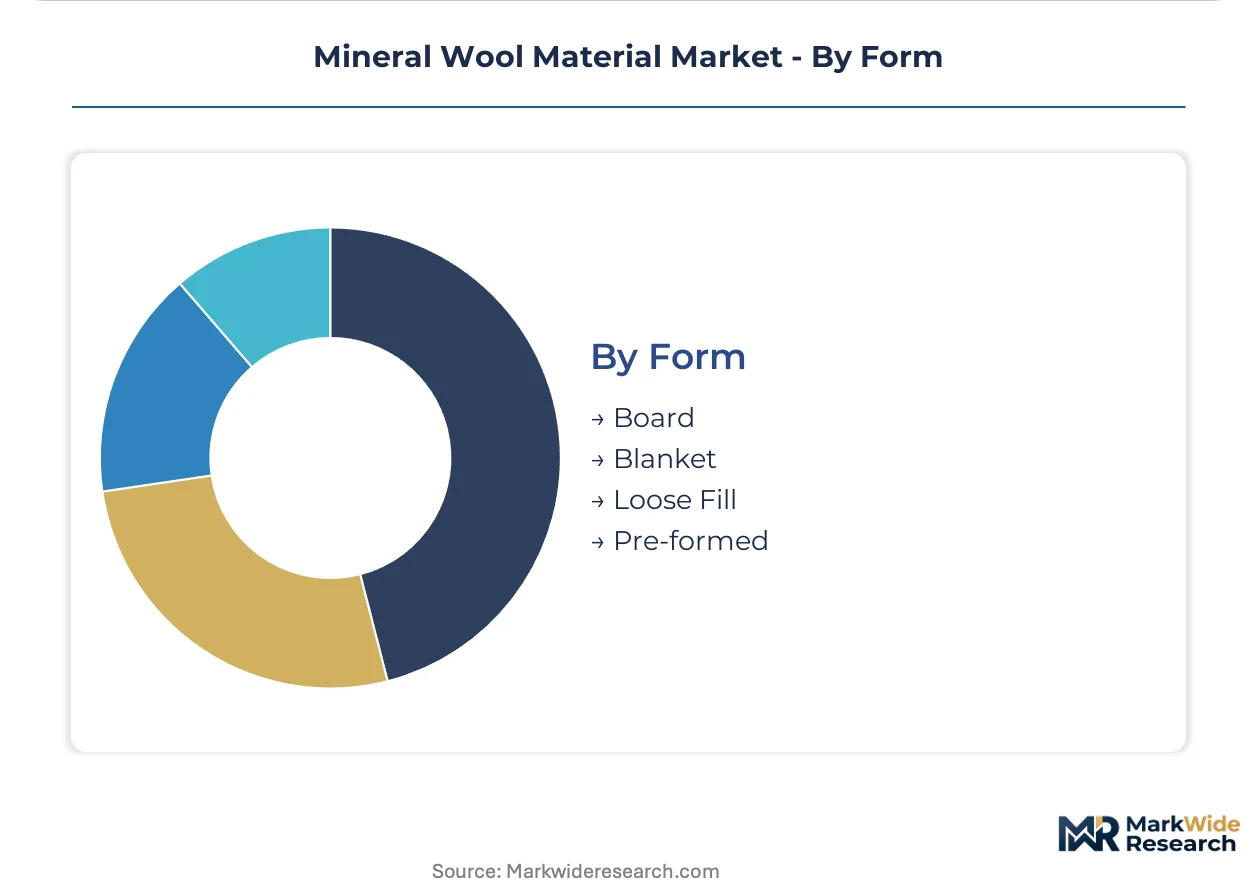
Form:
Installation labor availability is reshaping form factor preferences toward pre-configured solutions.
- Board:Rigid compression-molded panels suit flat roof and external wall applications. Scandinavian offsite construction factories are cutting board stock to precise envelope dimensions in controlled conditions.
- Blanket:Flexible rolls drape over irregular substrates and pipework. Industrial maintenance crews in Belgian chemical plants specify aluminum-faced blankets for turbine and vessel insulation.
- Loose Fill:Blown attic applications dominate residential retrofits where truss spacing varies.
- Pre-formed:Factory-cut pipe sections and vessel wraps reduce site fabrication hours.
Board and blanket forms command the bulk of capacity. Pre-formed segments are gaining share fastest as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale mineral wool production originated in Germany during the late nineteenth century, establishing Central Europe as the foundational geography for fiber-forming technology and thermal insulation standards that subsequently diffused across industrializing economies.
Germany
The Federal Institute for Risk Assessment enforces Europe's most stringent formaldehyde emission thresholds for glass wool binders. The national building energy efficiency ordinance mandates minimum U-values that accelerate mineral wool deployment in deep retrofit programs. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate both manufacturing capacity and specification engineering expertise for high-performance facade systems.
United States
OSHA permissible exposure limits for respirable crystalline silica govern rock wool production protocols and installation contractor certification requirements. The EPA's evolving stance on embodied carbon in construction materials is reshaping procurement criteria for federal building projects. Manufacturing concentration in the Midwest and Southeast supplies residential and commercial construction pipelines through extensive distributor networks anchored in Chicago and Atlanta metropolitan areas.
China
The Ministry of Ecology and Environment's dual carbon goals are tightening energy efficiency standards for industrial process insulation and commercial building envelopes. Steel blast furnace slag availability in Hebei and Shandong provinces sustains cost-competitive slag wool production for domestic infrastructure investment. Yangtze River Delta construction markets are specifying higher-grade rock wool for high-rise residential towers under updated fire safety codes.
Poland
National renovation wave subsidies are channeling EU Green Deal funding into residential attic and cavity wall retrofits at volumes exceeding new construction mineral wool demand. The country's building code alignment with EU energy performance directives mandates thermal conductivity thresholds that favor glass wool specification. Manufacturing facilities in Silesia and Greater Poland regions serve both domestic markets and export demand from neighboring Baltic states.
France
ANSES interpretation timelines for REACH Annex XVII restrictions are accelerating binder chemistry reformulation investments across manufacturing footprints. The RE2020 environmental regulation imposes carbon caps on new construction that elevate mineral wool's competitive position against higher-embodied-carbon alternatives. Industrial concentration in Hauts-de-France and Auvergne-Rhône-Alpes supports specification relationships with Paris-region envelope consultants and passive house developers.
Mineral Wool Material Market Vendor Landscape
The competitive structure tilts toward integrated building materials conglomerates with captive mineral wool production capacity and established specification relationships with envelope engineers. Three archetypes occupy distinct competitive terrain: stone wool specialists with high-temperature industrial expertise, glass wool volume leaders serving residential retrofit markets, and diversified building envelope integrators bundling insulation with complementary membranes and sealants. Dominant competitive moves include backward integration into raw material supply and strategic partnerships with offsite construction manufacturers for prefabricated panel systems.
Among European-headquartered specialists, ROCKWOOL International and Saint-Gobain exemplify divergent strategic postures. ROCKWOOL International anchors the stone wool archetype with furnace technology optimized for basalt fiber formation. Saint-Gobain occupies the integrated envelope position, representing the bundled-solution model that combines mineral wool with complementary building performance layers. Johns Manville represents the North American distribution-heavy model, with specification relationships and contractor network density as core competitive infrastructure.
| Leading Market Players |
|---|
| Knauf Insulation |
| Luyang Energy-Saving Materials Co., Ltd |
| ROCKWOOL International |
| GAF Materials Corporation |
| Shandong Wiskind Architectural Steel Co., Ltd |
| Saint-Gobain |
| Johns Manville |
| KCC Corporation |
| Owens Corning |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between fire-rated rock wool and commodity glass wool manifests in both pricing power and supply chain configurations. Premium rock wool commands specification premiums through non-combustibility certification under Germany's building energy efficiency ordinance and France's RE2020 carbon caps, while glass wool volumes flow through price-sensitive residential retrofit channels in Poland where national renovation wave subsidies compress margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs mineral wool transactions. Premium tiers anchor in fire protection certification and industrial temperature ratings, while economy positioning serves residential attic retrofits where Polish and German subsidy programs drive volume. Price differentiation hinges on thermal conductivity performance and REACH Annex XVII binder compliance. Cost compression in standard-grade glass wool is intensifying because slag input volatility and freight-adjusted basalt economics squeeze distant manufacturers. Residential retrofit contractors in Poland exhibit highest price sensitivity; envelope consultants in the Netherlands and France show lowest sensitivity as performance guarantees dominate procurement.
Supply Chain Analysis
Regional distribution centers in Germany, Poland, and France operate hub-and-spoke patterns feeding contractor networks and offsite construction factories. Manufacturing concentrates in Germany's North Rhine-Westphalia and Bavaria clusters, Poland's Silesia region, and France's Hauts-de-France. Raw material supply draws from steel blast furnace slag in Hebei and Shandong provinces, basalt deposits near European production sites, and recycled glass cullet streams. Single-source vulnerability persists in high-purity basalt fiber feedstock for rock wool furnaces. Distribution runs through specification-engineering relationships with envelope consultants and direct-to-contractor channels for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mineral wool market functions as a regulatory compounder where EU Green Deal renovation wave mandates and tightening fire safety codes mechanically expand addressable volume regardless of cyclical construction activity.
For Market Incumbents: Lock in specification relationships with envelope consultants and passive house developers before REACH Annex XVII compliance investments fully mature. Prioritize backward integration into basalt and slag supply to insulate margin from freight-adjusted cost spikes. Defend against polyisocyanurate substitution in light commercial roof assemblies by bundling mineral wool with airtight membranes for whole-building performance guarantees. For New Entrants and Emerging Players: EU Green Deal national renovation wave targets in Poland open a window for specialized installation service providers addressing qualified contractor scarcity. Target data center lithium-ion battery containment and marine A-60 retrofit cycles where specification pull outpaces supply. Enter through prefabricated panel partnerships with Netherlands and Scandinavian offsite construction manufacturers rather than competing for commodity board volumes. For Investors and Strategic Acquirers: Asymmetric upside sits with stone wool specialists possessing verified low-embodied-carbon processes ahead of carbon border adjustment mechanism phase-in. Five-to-ten-year viability favors manufacturers with integrated building envelope bundling capabilities and established specification engineering relationships. Monitor national renovation wave subsidy allocation rates as the inflection indicator for retrofit demand acceleration versus new construction substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Supply | Captive feedstock secures margin against freight-adjusted cost volatility in rock wool production. |
| Prefabricated Panel Partnership | Offsite construction factories in Netherlands integrate mineral wool cores into factory-built wall cassettes. |
| REACH Annex XVII Compliance Investment | Front-loaded reformulation spend qualifies modified binder chemistries for German and French markets. |
| Carbon Border Adjustment Positioning | Verified low-embodied-carbon processes capture margin premiums as CBAM phases in for construction materials. |
| Installation Certification Program | Qualified contractor pipelines in Eastern Europe compress project timelines and reduce labor cost premiums. |
Methodological Framework
Coverage spans Germany, France, Poland, the United States, and China, with primary inputs from each market combined with secondary validation. Primary interviews engaged plant managers at mineral wool manufacturing facilities, procurement leads at downstream construction OEMs, envelope consultants specifying facade systems, and distribution channel partners serving retrofit contractors. Secondary sources included customs and trade data, EU ECHA REACH registration databases, building code regulatory filings, and SEC 10-K disclosures from listed building materials conglomerates. Bottom-up volume modeling triangulated against top-down construction spend allocation across thermal, acoustic, and fire protection applications.
Rate-of-change decomposition separated volume drivers from price mix effects across the projection horizon. Segmentation dimensions modeled include fiber chemistry tier, application intensity, end-use durability requirements, installation form factor, and regional regulatory cluster. CAGRs derived from construction pipeline forecasts, national renovation wave commitment schedules, and industrial process heat recovery capital expenditure patterns. Industry-specific inputs incorporated EU Green Deal national building performance target trajectories and OSHA permissible exposure limit enforcement trends.
Revisions become necessary when EU carbon border adjustment mechanism implementation timelines shift, national renovation wave subsidy allocations deviate from committed levels, or REACH Annex XVII restriction scopes expand beyond current formaldehyde-releasing substance categories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Micronized Salt Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Dolomite Mining Market