
 Mediterranean Sea Salt Micro-Mineral Complexes Market | 2026-2036
Mediterranean Sea Salt Micro-Mineral Complexes Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Sea Salt Micro-Mineral Complexes Market Insights
Premium flake and crystalline grades is collapsing the gap between commodity salt and high-value mineral ingredients. Salins Group leverages integrated solar evaporation across Aigues-Mortes to sustain year-round output of magnesium-rich complexes. SaltWorks anchors North American distribution of Mediterranean-origin micro-mineral salts through direct-to-manufacturer channels. Maldon Crystal Salt Company differentiates on artisanal harvesting credentials that command positioning in cosmetic formulation supply chains.
Mediterranean Sea Salt Micro-Mineral Complexes comprise sodium chloride matrices co-precipitated with bioavailable magnesium, potassium, calcium, and trace iodine through controlled solar or vacuum evaporation of seawater, typically achieving total dissolved mineral contents of 3-8 percent beyond NaCl. These complexes function primarily as natural mineral fortificants, texture modifiers, and electrolyte balancers across food, pharmaceutical, and personal care matrices. Crystalline salt and flake salt occupy the highest margin tiers due to slower evaporation kinetics that preserve ionic lattice structures preferred by nutraceutical and cosmetic formulators. Solar evaporation dominates volume output across coastal Spain, Sicily, and southern France, while vacuum evaporation and electrodialysis are displacing traditional methods for pharmaceutical-grade specifications requiring heavy metal thresholds below 0.1 ppm.
EMA purity standards for pharmaceutical-grade mineral salts, REACH registration requirements for imported marine-derived substances, and EU Green Deal carbon accounting rules for coastal extraction operations collectively elevate compliance costs while advantaging established Mediterranean basin producers with legacy evaporation infrastructure. BIS and FDA parallel pathways for trace mineral content labeling create dual-certification burdens for exporters targeting India and the United States. Stakeholders must monitor evolving heavy metal testing protocols and carbon border adjustment mechanisms to determine whether backward integration into controlled evaporation assets or partnership with certified harvesters offers superior route-to-market economics.
Market Dynamics
EU Green Deal carbon accounting rules for coastal extraction operations are compressing margins for uncontrolled solar evaporation while advantaging legacy Mediterranean basin producers with certified infrastructure and documented supply chains.
Growth Catalysts
- Nutraceutical fortification mandates:Functional food formulators in Spain and Italy are expanding procurement of magnesium-rich salt complexes for electrolyte-balanced sports nutrition and senior dietary supplements.
- REACH registration tailwinds:Pre-registered marine-derived substances under ECHA frameworks accelerate market access for established harvesters versus new importers facing compliance backlogs.
- Solar evaporation infrastructure:Traditional salt flat operations in Andalusia and Sicily yield premium micro-mineral retention that vacuum methods cannot replicate for cosmetic-grade specifications.
Market Restraints
- Heavy metal input volatility:Seawater contamination from industrial discharge near Barcelona and Marseille ports creates batch-to-batch variation in lead and cadmium levels.
- Geographic supply concentration:Over 60 percent of pharmaceutical-grade output depends on three coastal evaporation zones in southern France and eastern Spain.
- Rock salt substitution pressure:Mechanically extracted halite from Pakistan and Chile undercuts Mediterranean-origin material in commodity food processing applications.
Strategic Opportunities
- Portuguese Atlantic expansion:Unexploited salt pans in the Algarve region offer EU-certified production capacity with lower carbon intensity than eastern Mediterranean competitors.
- Electrodialysis-pharma convergence:Coupling membrane separation with pharmaceutical-grade crystallization opens heavy metal thresholds below 0.1 ppm for injectable mineral therapies.
- Direct-to-manufacturer channels:Bypassing ingredient distributors through qualified supplier programs reduces working capital cycles for North American nutraceutical contract manufacturers.
Industry Challenges
- Evaporation artisan skill scarcity:Master salt harvesters capable of judging crystal formation kinetics for flake-grade output are retiring faster than apprenticeship programs replace them.
- Dual-certification timeline compression:Simultaneous BIS and FDA trace mineral content validation for Indian and US market entry extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Sea Salt Micro-Mineral Complexes Market |
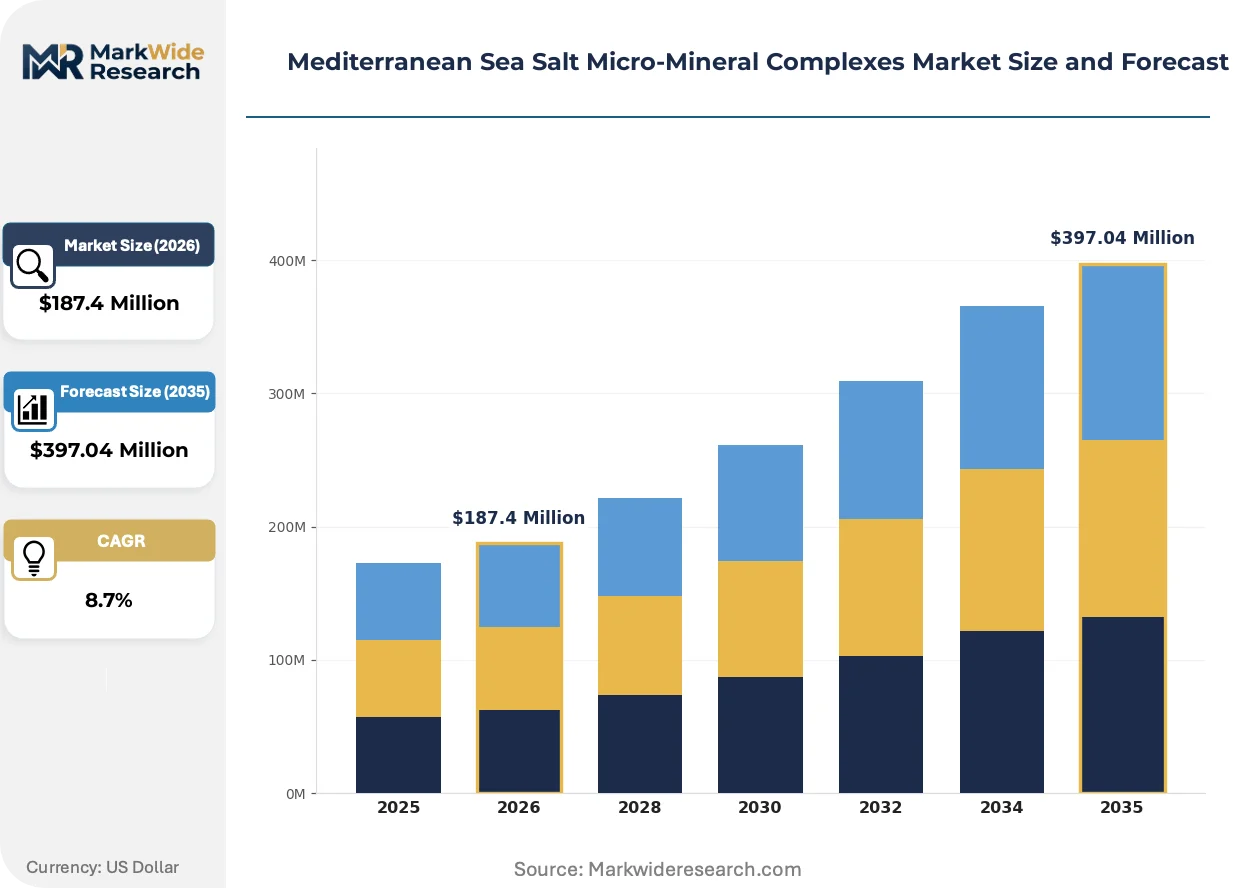
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Salt, Fine Grain Salt, Coarse Grain Salt, Flake Salt, Block Salt Formulation Technology: Natural Harvesting, Vacuum Evaporation, Solar Evaporation, Spray Drying, Freeze Drying, Electrodialysis Application: Food Processing, Animal Nutrition, Cosmetic Formulations, Water Treatment, Pharmaceutical Ingredients End User: Food & Beverage Manufacturers, Nutraceutical Companies, Personal Care Producers, Agriculture Specialists |
| Companies Covered | Salins Group, Salinera Española, SaltWorks, Cargill Salt, Compass Minerals, K+S Aktiengesellschaft, Infosa, Maldon Crystal Salt Company, Cheetham Salt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Sea Salt Micro-Mineral Complexes Market Trends and Innovations
Controlled crystallization technologies and carbon-border compliance systems are redrawing competitive boundaries between artisanal harvesters and industrial processors across Mediterranean supply chains.
Electrodialysis reversal systems paired with precision crystallization chambers are miniaturizing pharmaceutical-grade production footprints. Mid-scale nutraceutical manufacturers in northern Italy and southern Germany are adopting containerized units at twice the pace of 2022 baselines. This distributed processing architecture is miniaturizing the economies of scale that historically favored centralized solar evaporation complexes.
F-Gas Regulation phase-down schedules under EU climate frameworks are banning hydrofluorocarbon-based cooling in vacuum evaporation facilities. Industrial salt processors must retrofit to ammonia or CO2 refrigeration cycles by 2030. Pharmaceutical-grade vacuum evaporation in coastal France faces the steepest retrofit burden due to older installed bases.
Ingredient buyers are consolidating supplier panels around carbon-accounted supply chains. Major cosmetic formulators in Barcelona and Milan now require documented kg-CO2-eq per kilogram of mineral salt. This audit-driven procurement behavior favors Andalusian solar operations with photovoltaic-powered pumping over Italian vacuum facilities on carbon-intensive grids.
Mediterranean Sea Salt Micro-Mineral Complexes Market Segmentation
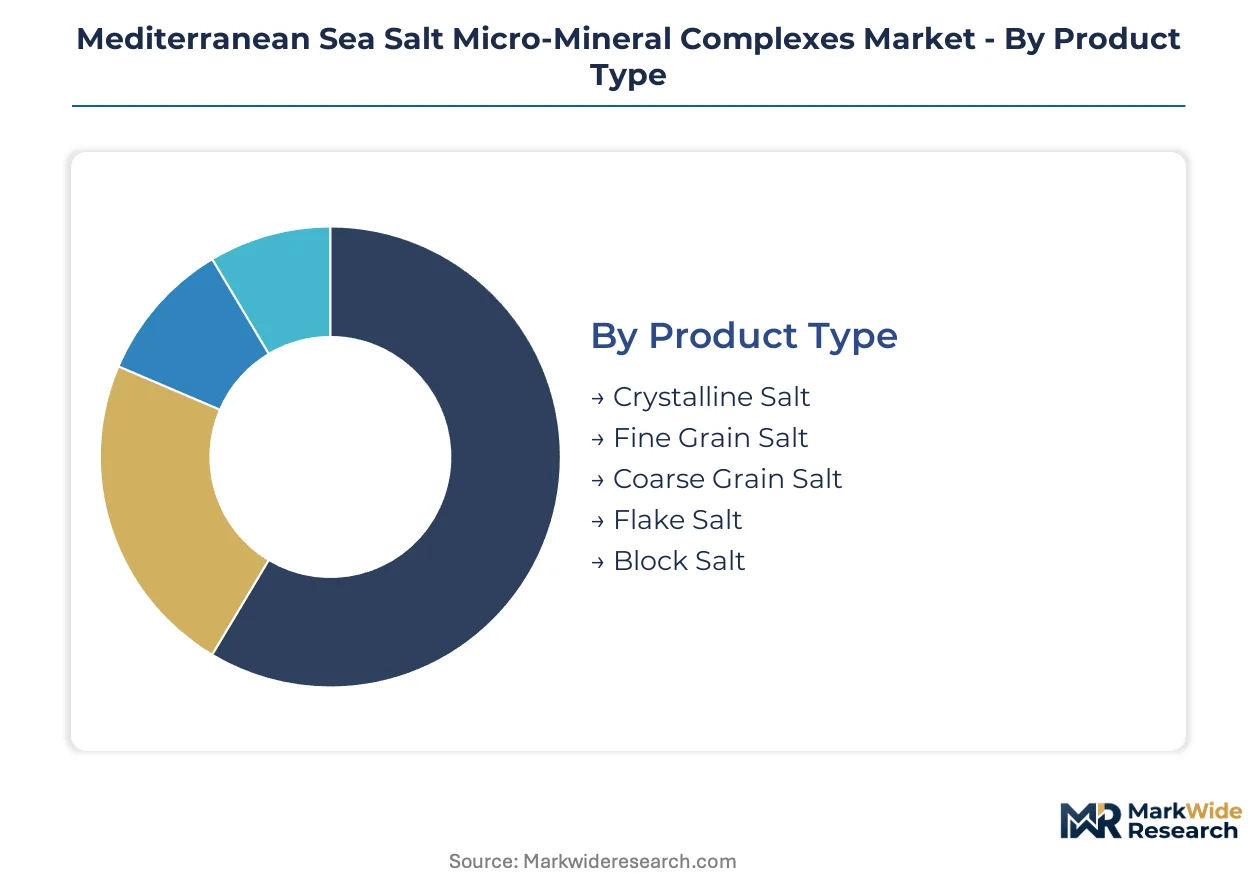
Segmentation in Mediterranean Sea Salt Micro-Mineral Complexes reveals how crystallization kinetics and harvesting infrastructure create divergent margin profiles across nutraceutical, cosmetic, and pharmaceutical supply chains. Regulatory thresholds for heavy metal content and carbon intensity increasingly sort buyers into distinct procurement tiers based on end-use certification requirements.
Product Type:
EMA and FDA pharmaceutical-grade specifications create a three-tier purity hierarchy that stratifies pricing power across crystalline structures.
- Crystalline Salt:Slow solar evaporation in Andalusian salt flats preserves intact ionic lattices with 3-8% retained magnesium and potassium. Pharmaceutical formulators in Barcelona and Milan pay premiums for documented heavy metal thresholds below 0.1 ppm.
- Flake Salt:Delicate pyramid structures form under precise humidity-controlled harvesting conditions mastered by artisans in Aigues-Mortes and Sicily. Cosmetic brands specify flake geometry for exfoliant formulations where particle size determines skin-feel performance.
- Fine Grain Salt:Rapid vacuum evaporation yields uniform particle distribution for rapid dissolution in sports nutrition powders.
- Coarse Grain Salt:Intermediate solar evaporation cycles produce robust crystals for grinder-fill retail applications.
- Block Salt:Compressed solar-evaporated masses serve water softening systems and livestock mineral licks.
Crystalline salt handles the majority of throughput; flake salt is expanding most quickly on share.
Formulation Technology:
Carbon accounting under EU Green Deal rules advantages harvesting methods with documented renewable energy inputs over fossil-powered industrial processing.
- Solar Evaporation:Traditional salt flat operations in southern Spain and Sicily achieve premium micro-mineral retention through 30-90 day natural cycles. Photovoltaic-powered pumping systems in Algarve operations now deliver the lowest kg-CO2-eq per kilogram in European supply.
- Vacuum Evaporation:Controlled temperature reduction in sealed chambers produces pharmaceutical-grade consistency but faces F-Gas Regulation retrofit deadlines for hydrofluorocarbon cooling replacement by 2030.
- Natural Harvesting:Direct collection of surface bloom crystals preserves maximum trace element diversity for artisanal food positioning.
- Electrodialysis:Membrane separation enables heavy metal thresholds below 0.1 ppm for injectable mineral therapies.
- Spray Drying:Atomization and rapid thermal processing converts brine to powder for instant beverage applications.
- Freeze Drying:Sublimation preserves volatile organic compounds for specialty cosmetic extracts.
Solar evaporation retains the largest installed capacity; electrodialysis is climbing the fastest as pharmaceutical specifications tighten.
Application:
End-use certification requirements split procurement between food-grade tolerances and pharmaceutical-grade validation timelines.
- Food Processing:Sodium reduction mandates in Spain and Italy drive substitution of mechanically extracted halite with magnesium-enriched Mediterranean alternatives in cured meat and bread applications.
- Pharmaceutical Ingredients:EMA monograph compliance for mineral supplements requires batch-level heavy metal documentation that only vacuum and electrodialysis methods consistently deliver.
- Cosmetic Formulations:Exfoliant and bath salt applications prioritize crystal geometry and trace mineral diversity over purity metrics.
- Animal Nutrition:Livestock mineral premixes specify calcium-magnesium ratios for dairy cattle productivity optimization.
- Water Treatment:Ion exchange regeneration cycles consume block salt in industrial softening systems.
Food processing commands the greatest volume; pharmaceutical ingredients are gaining share fastest on regulatory tailwinds.
End User:
Procurement sophistication separates multinational formulators with dedicated supplier qualification programs from regional processors buying through distribution.
- Nutraceutical Companies:Electrolyte-balanced formulations for senior dietary supplements and sports nutrition drive magnesium-rich salt complex demand from contract manufacturers in northern Italy and southern Germany.
- Personal Care Producers:Barcelona and Milan formulators now require carbon-accounted supply chains with documented kg-CO2-eq per kilogram, favoring Andalusian solar operations.
- Food & Beverage Manufacturers:Clean-label positioning motivates replacement of refined table salt with trace-element-retained alternatives in premium packaged goods.
- Agriculture Specialists:Precision livestock nutrition programs specify mineral-enriched salt blocks for herd health management.
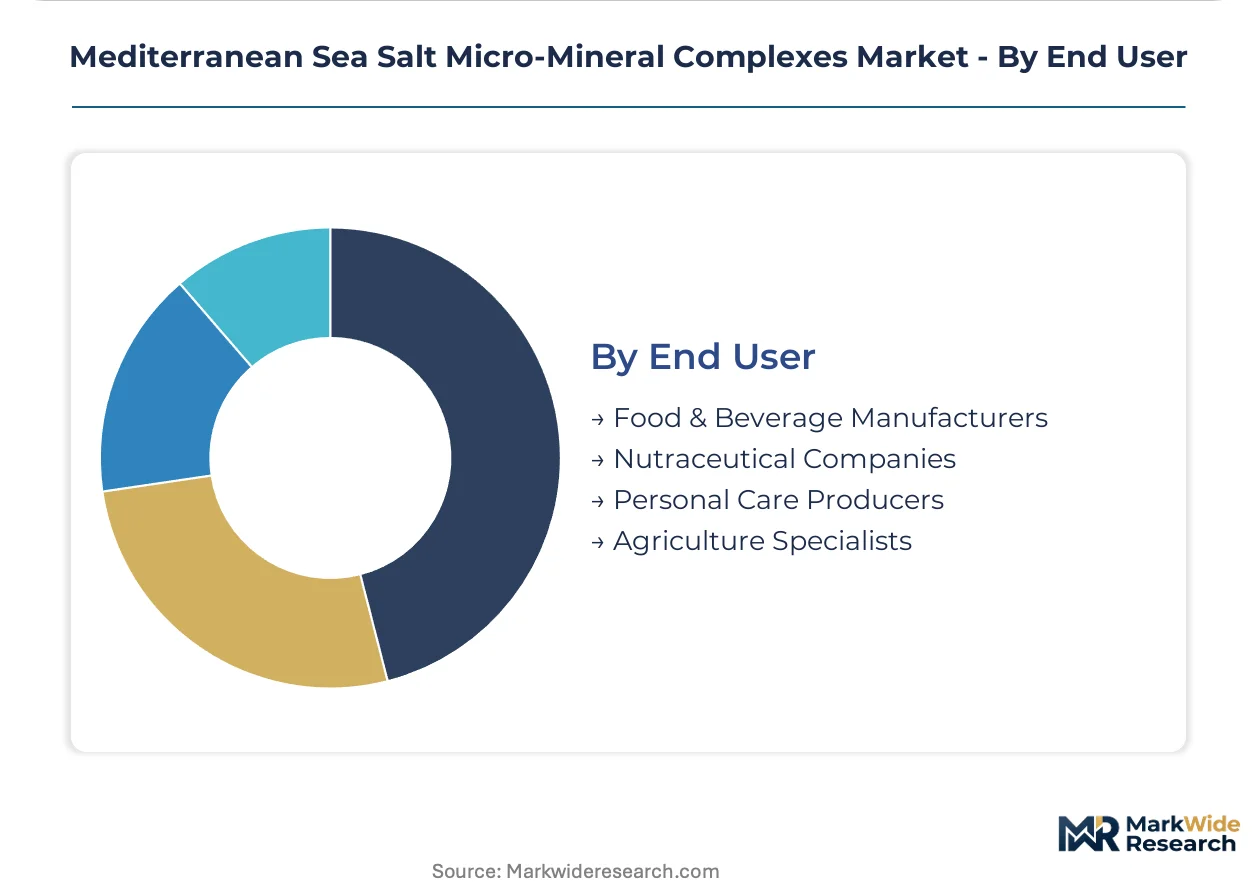
Food and beverage manufacturers represent the largest buyer base; nutraceutical companies show the steepest expansion trajectory on functional fortification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across Mediterranean salt-producing nations reveal a structural surplus concentrated in solar-evaporation zones, with intra-EU trade flows dominating value movement while North American and Asian buyers absorb premium-grade flake and crystalline output.
Spain
Andalusian salt flats in Cádiz and Huelva provinces generate the bulk of EU pharmaceutical-grade micro-mineral complexes, with Salinera Española operating integrated solar facilities that feed Barcelona and Milan cosmetic formulators. EMA heavy metal thresholds below 0.1 ppm shape batch certification protocols. The Guadalquivir basin evaporation zones are expanding photovoltaic-powered pumping to meet carbon-accounted procurement mandates from French and Italian buyers.
France
Aigues-Mortes saltworks in the Camargue region supply magnesium-rich flake grades to Paris-based luxury cosmetic houses and German nutraceutical contract manufacturers. F-Gas Regulation phase-down deadlines force vacuum evaporation retrofits by 2030, compressing margins for older coastal facilities. The Occitanie cluster is consolidating artisan harvesting expertise through regional apprenticeship programs to address master salt worker retirements.
Italy
Sicilian solar salt pans near Trapani and Marsala retain trace mineral diversity prized by Milan personal care formulators specifying carbon-accounted supply chains. REACH registration for marine-derived substances accelerates market access versus non-EU importers. The Po Valley nutraceutical manufacturing corridor is absorbing expanding volumes of electrolyte-balanced salt complexes for senior dietary supplement formulations.
Portugal
Algarve salt pans offer unexploited EU-certified production capacity with lower carbon intensity than eastern Mediterranean competitors, attracting sustainability-focused procurement from northern European buyers. The national agricultural regulator enforces trace mineral labeling standards that align with BIS and FDA parallel pathways. Faro and Tavira sub-regions are developing photovoltaic-integrated evaporation infrastructure to serve German and Dutch food processing demand.
Greece
Messolonghi salt flats produce coarse and block grades primarily for domestic water treatment and livestock mineral applications, with limited flake output reaching Italian cosmetic supply chains. National pharmaceutical regulators are harmonizing heavy metal testing protocols with EMA monograph requirements. Peloponnese evaporation zones face competitive pressure from mechanized halite imports in commodity food salt segments.
Mediterranean Sea Salt Micro-Mineral Complexes Market Competitive Landscape
Concentration sits with integrated solar evaporation operators possessing legacy infrastructure and documented carbon accounting. The vendor base spans three tiers: multinational mineral conglomerates with diversified salt portfolios, regional Mediterranean specialists controlling coastal evaporation assets, and artisan harvesters commanding cosmetic-grade flake premiums. Strategic moves center on backward integration into certified evaporation zones and partnership structures that lock in carbon-accounted supply chains for North American nutraceutical buyers.
Within the regional specialist tier, Salins Group and Salinera Española exemplify integrated solar evaporation archetypes anchored in French and Spanish coastal zones. SaltWorks occupies a position bridging Mediterranean-origin procurement with North American direct-to-manufacturer distribution channels. Maldon Crystal Salt Company represents the artisan harvesting archetype, with positioning in cosmetic formulation supply chains driven by credentials rather than scale. These three entities illustrate the competitive divergence between volume-driven mineral processing and premium-grade trace mineral retention.
| Leading Market Players |
|---|
| Salins Group |
| Salinera Española |
| SaltWorks |
| Cargill Salt |
| Compass Minerals |
| K+S Aktiengesellschaft |
| Infosa |
| Maldon Crystal Salt Company |
| Cheetham Salt |
| Others |
Pricing and Supply Chain Analysis
Mechanically extracted halite from Pakistan and Chile displacing Mediterranean-origin material in commodity food processing simultaneously compresses pricing floors in bulk sodium chloride tiers while redirecting procurement gravity toward certified solar evaporation zones where EMA heavy metal documentation commands pharmaceutical-grade premiums.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across crystalline and flake salt tiers, with price differentiation driven by certification level (EMA monograph compliance versus food-grade tolerances) and volume scale. Cost compression in fine grain vacuum-evaporated grades is intensifying because F-Gas Regulation retrofit deadlines force capital expenditure absorption by coastal French processors. Contract manufacturers in northern Italy exhibit highest price sensitivity due to working capital constraints, while Paris-based luxury cosmetic houses demonstrate least sensitivity given geometry-specific flake requirements.
Supply Chain Analysis
Container availability constraints on Barcelona-Marseille trade lanes elevate inbound logistics costs for North American nutraceutical distributors sourcing Mediterranean-origin micro-mineral complexes. Supply concentrates in Spain, France, and Italy, with raw material dependencies on seawater intake quality, photovoltaic pumping infrastructure, and artisan harvesting labor pools. Single-source vulnerability sits with master salt worker retirements outpacing apprenticeship replacements. Distribution runs through qualified supplier programs that bypass ingredient distributors for direct-to-manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as EU Green Deal carbon accounting rules force margin compression on uncontrolled solar evaporation, creating acquisition opportunities for legacy infrastructure owners with documented supply chains.
For Market Incumbents: Consolidate artisan harvesting expertise through regional apprenticeship programs in Occitanie and Sicily to address master salt worker retirements threatening flake-grade output. Acquire photovoltaic-integrated evaporation assets in Portugal's Algarve region to preempt sustainability-focused procurement shifts by German and Dutch buyers.
For New Entrants and Emerging Players: Lead with electrodialysis-pharma convergence targeting injectable mineral therapy specifications requiring heavy metal thresholds below 0.1 ppm, a white-space segment where vacuum evaporation incumbents face F-Gas retrofit distraction. Penetrate Portuguese Atlantic expansion zones with carbon-accounted supply chain positioning for northern European nutraceutical contract manufacturers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional Mediterranean specialists controlling coastal evaporation infrastructure without pharmaceutical-grade certification depth. Long-term viability over a five-to-ten year window favors targets with backward integration into solar assets and EMA monograph compliance capabilities. Watch electrodialysis adoption rates among mid-scale Italian and German nutraceutical manufacturers as inflection signal for distributed processing displacement of centralized solar complexes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Evaporation Assets | Salins Group's Aigues-Mortes solar infrastructure secures year-round magnesium-rich complex output for cosmetic formulators. |
| Electrodialysis-Pharma Convergence | Membrane separation technology enables heavy metal thresholds below 0.1 ppm for injectable mineral therapy applications. |
| Direct-to-Manufacturer Channel Development | SaltWorks bypasses ingredient distributors to reduce working capital cycles for North American nutraceutical contract manufacturers. |
| Photovoltaic-Pumping Infrastructure Deployment | Algarve salt pans achieve lowest kg-CO2-eq per kilogram to meet carbon-accounted procurement mandates from Milan formulators. |
| Artisan Harvesting Apprenticeship Programs | Occitanie regional initiatives address master salt worker retirements threatening pyramid-structure flake salt output for exfoliant formulations. |
Research Methodology
The analysis maps solar evaporation, vacuum evaporation, and electrodialysis sub-sectors, each validated through salt flat operations managers, nutraceutical contract manufacturing procurement leads, cosmetic formulation R&D directors, and pharmaceutical regulatory affairs specialists. Primary interview findings triangulated against ECHA REACH registration databases, EU customs trade data for marine-derived substances, SEC filings of diversified mineral conglomerates, and EMA monograph documentation for pharmaceutical-grade mineral salts. Bottom-up volume builds from identified evaporation zone capacities reconciled with top-down demand estimates from end-use application segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models crystallization kinetics, formulation technology, application requirements, and end-user procurement sophistication as core segmentation dimensions. CAGRs derived from historical growth rate analysis adjusted for regulatory tailwinds and substitution dynamics. Forecast inputs incorporate F-Gas Regulation phase-down schedules and carbon border adjustment mechanism implementation timelines as structural demand shifters.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated electrodialysis cost reduction would require recalibration. Forecasts reflect documented assumptions regarding seawater contamination stability near Barcelona and Marseille ports and master salt worker replacement rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Kyanite Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Solar Salt Market