
 India Feed Minerals Market | 2026-2036
India Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
India Feed Minerals Market Outlook
Copper sulfate is shifting toward chelated organic trace minerals as Indian livestock producers seek higher bioavailability at lower inclusion rates. BASF SE leverages its global micronutrient formulation expertise to supply Indian premix manufacturers with standardized mineral complexes. Cargill Inc anchors its position through backward integration into regional sourcing networks for limestone and dicalcium phosphate. Kemin Industries differentiates via specialized mineral absorption technologies tailored to tropical heat stress conditions in Indian poultry operations.
Feed minerals comprise inorganic and organic compounds—iron, zinc, manganese, copper, selenium, and iodine—typically supplied as sulfates, oxides, carbonates, or chelated forms at inclusion rates from 0.1 to 200 ppm depending on species requirements, manufactured through precipitation, crystallization, or complexation processes, and function primarily to prevent deficiency disorders while optimizing feed conversion efficiency in livestock. The minerals segment leads volume owing to mandatory supplementation norms across commercial operations, while amino acids represent the fastest-expanding category as Indian aqua feed producers adopt lysine and methionine fortification for shrimp and fish diets. Dairy farms command the dominant end-user share due to organized sector expansion under Operation Flood legacy cooperatives, though aquaculture applications are gaining traction along coastal Andhra Pradesh and Odisha.
BIS feed grade standards and FSSAI contaminant limits govern mineral purity specifications and maximum allowable heavy metal residues in premix formulations, while the CEA and state pollution control boards enforce effluent discharge norms that raise processing costs for domestic sulfate manufacturers. The PLI scheme for animal husbandry inputs channels subsidy support toward integrated mineral premix facilities with captive grinding and blending capacity. Stakeholders must monitor how BIS alignment with CODEX Alimentarius standards reshapes import eligibility for chelated trace mineral sources from European suppliers.
Market Dynamics
PLI scheme subsidies for animal husbandry inputs are redirecting capital toward integrated mineral premix facilities with captive grinding and blending capacity, compressing import dependence for chelated trace mineral sources.
Growth Catalysts
- FSSAI feed safety standard tightening:Dairy farms across Maharashtra and Gujarat are expanding mineral supplementation programs to meet contaminant limit compliance, pulling demand for standardized premix formulations.
- Operation Flood legacy cooperatives:Organized dairy sector expansion under cooperative structures mandates mineral fortification across commercial herds, locking in baseline volume requirements.
- Chelated organic trace minerals:Poultry operations in Telangana and Andhra Pradesh are adopting copper sulfate alternatives for higher bioavailability at reduced inclusion rates.
Market Restraints
- Heavy metal residue compliance:BIS feed grade specifications and FSSAI maximum allowable limits raise purification costs for domestic sulfate manufacturers processing mineral ores.
- Limestone and dicalcium phosphate sourcing concentration:Regional sourcing networks for calcium and phosphorus inputs create vulnerability to state-level mining permit delays.
- Inorganic mineral price volatility:Sulfate and oxide feedstock costs fluctuate with base metal exchange pricing, compressing margin stability for premix blenders.
Strategic Opportunities
- Coastal Andhra Pradesh and Odisha aquaculture:Shrimp and fish feed producers are adopting lysine and methionine fortification, creating parallel mineral premix demand for aqua nutrition.
- CEA effluent discharge norm alignment:State pollution control board compliance investments position early movers for preferred supplier status with integrated dairy cooperatives.
- Tropical heat stress formulations:Specialized mineral absorption technologies tailored to poultry operations in Tamil Nadu offer differentiation against standard premix imports.
Industry Challenges
- CODEX Alimentarius alignment timelines:BIS standard revision schedules create uncertainty for European chelated mineral import eligibility, delaying procurement decisions.
- Crystallization process engineering talent:Domestic premix manufacturing scale-up requires skilled technicians for precipitation and complexation operations, with limited specialized training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Feed Minerals Market |
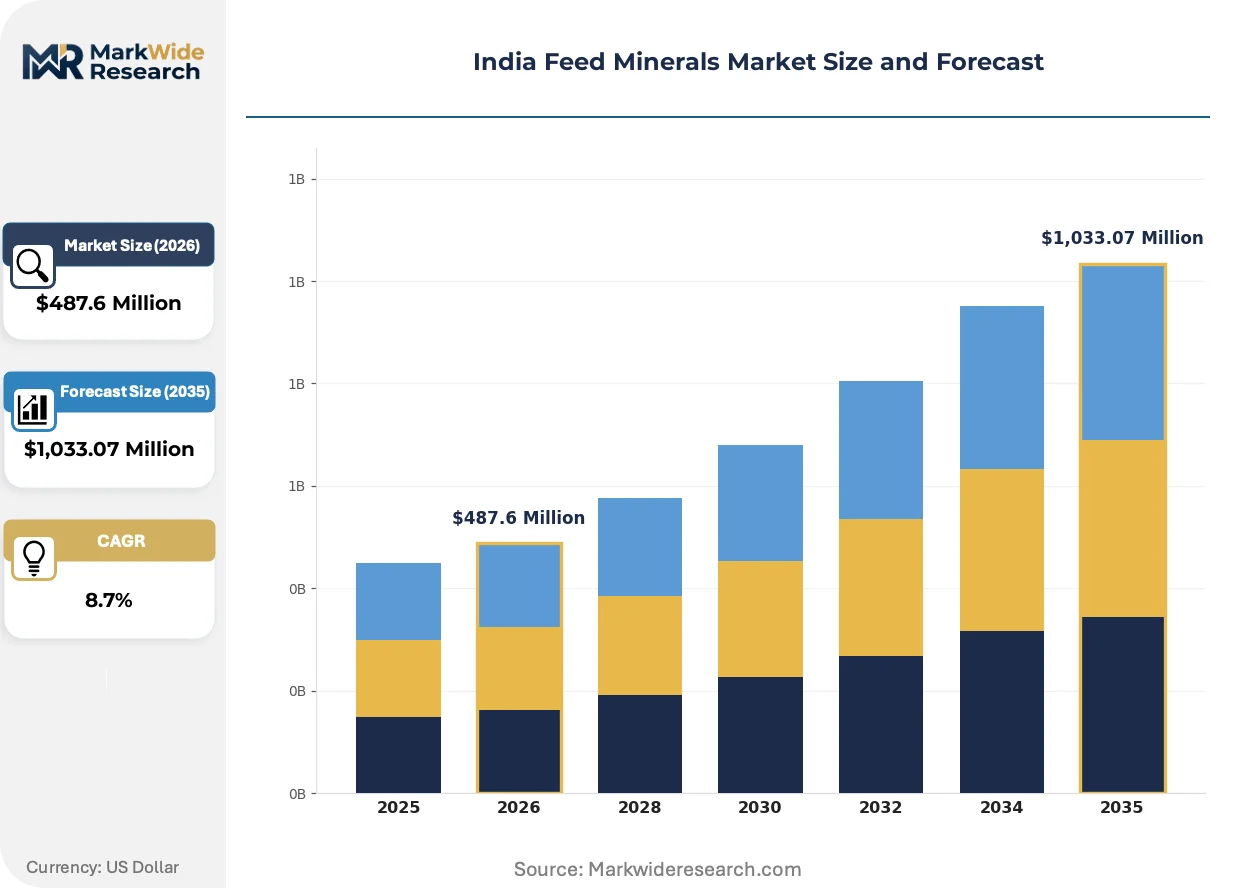
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Minerals, Enzymes End User: Dairy Farms, Poultry Farms, Aquaculture, Swine Farms Application: Animal Nutrition, Feed Supplements, Growth Promoters, Health Enhancers Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Adisseo, Alltech Inc, Archer Daniels Midland Co, BASF SE, Cargill Inc, Kemin Industries, Novus International Inc, Solvay S.A., Evonik India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Feed Minerals Market Strategic Shifts
Chelated organic trace minerals are compressing traditional sulfate formulations as livestock producers prioritize feed conversion efficiency over raw material cost minimization.
Organic copper and zinc complexes bind minerals to amino acids or hydroxy analogs, improving intestinal absorption rates in heat-stressed poultry flocks. Broiler operations across Tamil Nadu and Telangana are accelerating adoption to reduce excreted mineral waste and environmental loading. This transition is overtaking inorganic sulfate dominance in premix specifications for export-oriented poultry supply chains.
FSSAI contaminant limits for heavy metal residues in premix formulations are tightening maximum allowable thresholds for lead, cadmium, and arsenic. Domestic manufacturers must upgrade precipitation and crystallization infrastructure to meet purity specifications, raising capital intensity for sulfate producers. Dairy cooperatives in Gujarat and Maharashtra are responding by consolidating supplier lists toward integrated premix facilities with captive laboratory certification capacity.
Commercial feed mills are unbundling mineral premix procurement from complete feed contracts, shifting toward direct relationships with specialized blenders. Large poultry integrators in Andhra Pradesh are establishing specifications for chelated mineral inclusion rates separate from base feed pricing. This pattern concentrates most visibly in organized sector operations with in-house nutritionist teams capable of formulating custom premix orders.
India Feed Minerals Market Segmentation
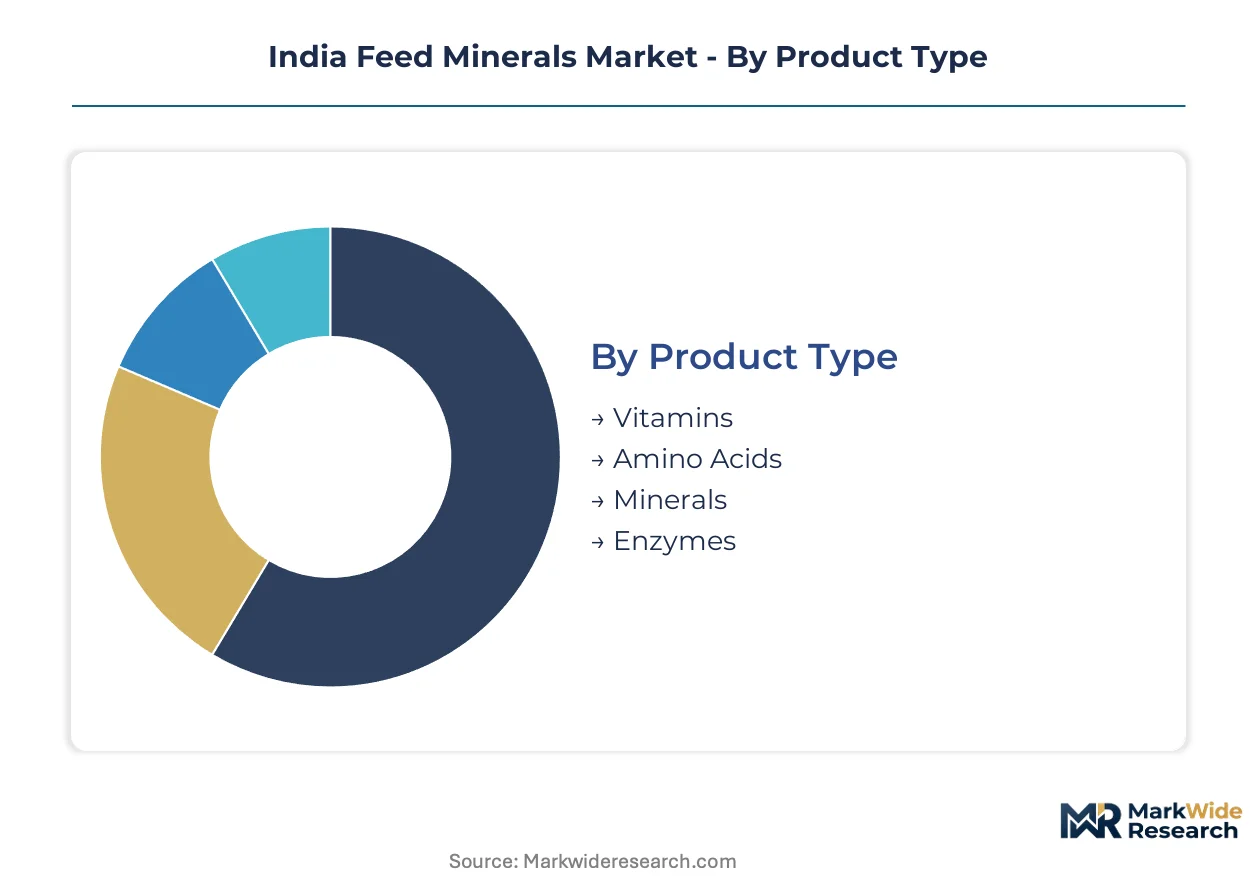
Segmentation in the India Feed Minerals Market reveals how capital deployment, regulatory compliance, and species-specific nutrition requirements fragment demand across distinct supply channels. Understanding these divides helps suppliers align manufacturing scale with end-user procurement patterns.
Product Type:
Capital intensity varies sharply across this category, with chelation infrastructure and crystallization capacity demanding the heaviest upfront investment.
- Minerals:Inorganic sulfates, oxides, and carbonates require precipitation and grinding facilities, while chelated organic forms need complexation reactors. Dairy cooperatives in Gujarat and Maharashtra mandate mineral fortification under FSSAI standards, locking in baseline volume for integrated premix manufacturers with captive laboratory certification.
- Amino Acids:Lysine and methionine production relies on fermentation biotechnology and downstream crystallization. Shrimp feed producers along coastal Andhra Pradesh and Odisha are accelerating lysine-methionine fortification, pulling parallel mineral premix demand for balanced aqua nutrition formulations.
- Vitamins:Fat-soluble and water-soluble vitamin synthesis demands multi-step chemical processing with strict BIS purity compliance.
- Enzymes:Phytase and carbohydrase production requires microbial fermentation platforms with temperature-controlled downstream recovery.
Minerals absorb the bulk of installed capacity; amino acids are expanding most quickly.
End User:
Customer scale and procurement sophistication create tiered service requirements across species-specific operations.
- Dairy Farms:Organized sector cooperatives under Operation Flood legacy structures negotiate long-term premix contracts with integrated suppliers. FSSAI contaminant limits for heavy metal residues are consolidating supplier lists toward facilities with in-house testing capacity in Gujarat and Maharashtra.
- Poultry Farms:Broiler integrators in Telangana and Andhra Pradesh unbundle mineral procurement from complete feed contracts, establishing direct specifications for chelated inclusion rates. Tropical heat stress conditions in Tamil Nadu operations drive adoption of specialized absorption technologies.
- Aquaculture:Shrimp and fish feed producers require mineral premixes compatible with lysine-methionine fortification protocols.
- Swine Farms:Commercial pig operations in northeastern clusters demand zinc and copper complexes for growth promotion within BIS feed grade limits.
Dairy farms command the dominant procurement volume; aquaculture applications are climbing the fastest.
Application:
Functional purpose determines formulation complexity and margin structure across the value chain.
- Animal Nutrition:Basal mineral supplementation prevents deficiency disorders across commercial herds and flocks. Standardized premix formulations for dairy cooperatives in Maharashtra emphasize calcium-phosphorus ratios aligned with FSSAI feed safety standards.
- Feed Supplements:Targeted mineral complexes address specific physiological stressors. Poultry operations in Tamil Nadu deploy heat-stress formulations combining organic trace minerals with electrolyte balancing.
- Growth Promoters:Copper and zinc complexes at regulated inclusion rates optimize feed conversion efficiency in broiler operations.
- Health Enhancers:Selenium and iodine fortification supports immune function and reproductive performance in breeding stock.
Animal nutrition captures the foundational demand base; feed supplements are gaining share fastest.
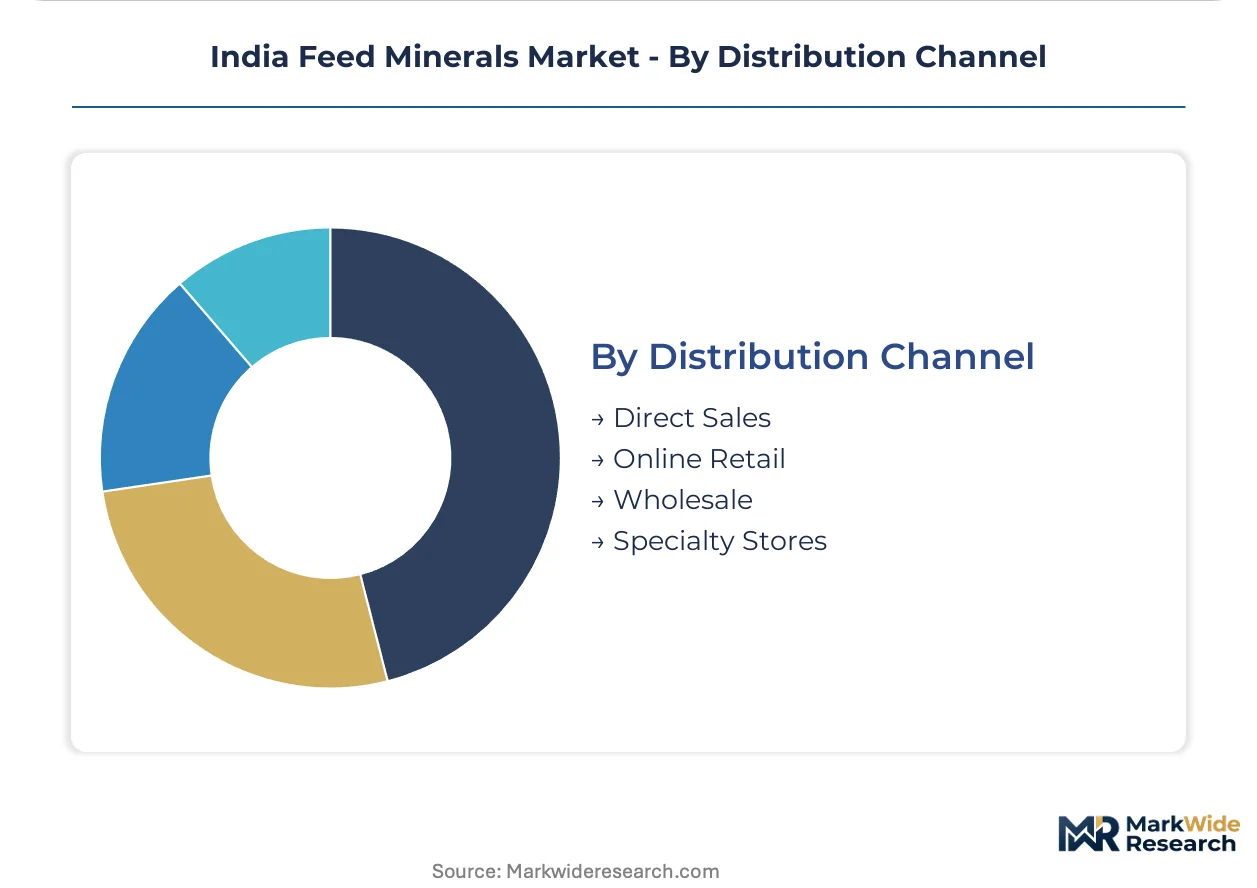
Distribution Channel:
Channel economics reflect customer scale, geographic dispersion, and technical service requirements.
- Direct Sales:Large poultry integrators and dairy cooperatives negotiate specification-driven contracts with premix manufacturers. Direct relationships allow custom chelated mineral inclusion rates separate from base feed pricing, concentrating among operations with in-house nutritionist teams.
- Wholesale:Regional distributors aggregate demand from mid-scale commercial farms across mineral-dense belts. Telangana and Andhra Pradesh poultry belts rely on wholesale channels for standardized sulfate and oxide premix formulations.
- Online Retail:E-commerce platforms serve smallholder farmers with packaged mineral supplements in secondary markets.
- Specialty Stores:Veterinary supply outlets provide technical guidance alongside premix sales in dairy-intensive districts.
Direct sales anchor volume for organized sector procurement; wholesale channels are expanding most quickly into emerging poultry belts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for feed minerals concentrates in states with dense commercial livestock operations and organized dairy cooperatives. FSSAI compliance requirements and PLI scheme subsidies are reshaping regional supply chain investments.
Maharashtra
Organized dairy cooperatives under Operation Flood legacy structures drive bulk premix procurement. FSSAI contaminant limits for heavy metal residues are consolidating supplier lists toward integrated facilities with captive laboratory certification. Pune and Nashik districts host expanding mineral premix manufacturing capacity serving western India dairy belts.
Gujarat
Commercial dairy herds mandate mineral fortification under cooperative procurement standards. BIS feed grade specifications govern calcium-phosphorus ratios in standardized formulations. Anand and Surat clusters anchor premix supply networks for cross-border trade into Rajasthan and Madhya Pradesh.
Telangana
Broiler integrators unbundle mineral procurement from complete feed contracts, establishing direct specifications for chelated inclusion rates. PLI scheme subsidies redirect capital toward integrated grinding and blending facilities. Hyderabad-centered poultry belts accelerate adoption of organic trace mineral alternatives to copper sulfate.
Andhra Pradesh
Coastal shrimp feed producers adopt lysine-methionine fortification, pulling parallel mineral premix demand for balanced aqua nutrition. CEA effluent discharge norms raise processing costs for domestic sulfate manufacturers. Visakhapatnam and Nellore districts concentrate aqua feed milling capacity with specialized mineral formulation requirements.
Tamil Nadu
Tropical heat stress conditions drive adoption of specialized mineral absorption technologies in broiler operations. Poultry farms prioritize feed conversion efficiency over raw material cost minimization. Coimbatore and Salem industrial corridors host premix blenders serving export-oriented poultry supply chains.
India Feed Minerals Market Competitive Environment
Capacity expansion dominates the current landscape as PLI scheme subsidies channel investment toward integrated mineral premix facilities with captive grinding and blending capability. The vendor base spans multinational chemical conglomerates, domestic premix specialists, and integrated feed mill operations. Three archetypes anchor competitive positioning: global micronutrient formulators with standardized complex supply, regional premix blenders with backward integration into limestone and phosphate sourcing, and specialized technology providers with tropical heat stress formulations. Geographic expansion and portfolio diversification toward chelated organic trace minerals represent the dominant competitive moves.
Within the global formulator tier, BASF SE and Cargill Inc exemplify multinational chemical and agricultural conglomerates leveraging global micronutrient expertise and regional sourcing networks respectively. Kemin Industries occupies a position among specialized technology providers with absorption technologies tailored to tropical conditions. These three companies represent distinct strategic archetypes: standardized mineral complex supply, backward integration into regional raw material networks, and differentiated formulation capabilities for environmental stressors.
| Leading Market Players |
|---|
| Adisseo |
| Alltech Inc |
| Archer Daniels Midland Co |
| BASF SE |
| Cargill Inc |
| Kemin Industries |
| Novus International Inc |
| Solvay S.A. |
| Evonik India Private Limited |
| Others |
Value Chain & Pricing Dynamics
Chelated organic trace mineral premiums against commodity sulfate formulations bifurcate procurement economics, with FSSAI-certified integrated facilities commanding price premiums while regional blenders compete on limestone and dicalcium phosphate sourcing efficiency. This tier divergence manifests in supply chain configurations: premium premix manufacturers maintain captive grinding and laboratory certification capacity, whereas economy-tier suppliers depend on wholesale distribution networks across Telangana and Andhra Pradesh poultry belts.
Pricing Analysis
Volume-driven commodity sulfates trade on thin margins against premium chelated complexes capturing value through bioavailability claims. Price differentiation rests on FSSAI contaminant certification tiers and backward integration into regional phosphate rock networks. Pricing pressure intensifies in sulfate segments as base metal exchange volatility feeds through feedstock costs. Smallholder farmers through online retail channels exhibit highest price sensitivity; organized dairy cooperatives in Gujarat and Maharashtra prioritize certification compliance over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Pune, Hyderabad, and Coimbatore anchor hub-and-spoke patterns serving dairy cooperatives and poultry integrators with contrasting service requirements. Domestic manufacturing draws from limestone deposits in Rajasthan and Madhya Pradesh, while chelated mineral precursors rely on fermentation-derived amino acid inputs from coastal biotechnology clusters. Single-source vulnerability concentrates in crystallization equipment and specialized complexation reactor supply. Distribution runs through direct sales contracts for organized sector buyers and wholesale aggregators for mid-scale commercial farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI heavy metal residue limits function as a cost-of-compliance moat, consolidating supplier lists toward integrated premix facilities with captive laboratory certification and compressing margin viability for unqualified regional blenders.
For Market Incumbents: Deploy certification leverage to consolidate dairy cooperative contracts in Maharashtra and Gujarat before BIS-CODEX alignment timelines clarify import eligibility rules. Expand captive grinding capacity under PLI scheme subsidies to outcompete European chelated mineral imports on landed cost. Counter inorganic price volatility through long-term offtake agreements with Rajasthan limestone processors. For New Entrants and Emerging Players: Begin with coastal Andhra Pradesh and Odisha aquaculture nutrition, where lysine-methionine fortification protocols create parallel mineral premix demand without entrenched incumbent relationships. Target shrimp feed mill technical specifications for balanced aqua nutrition formulations. Establish direct mill relationships bypassing wholesale channel markups through on-site formulation support. For Investors and Strategic Acquirers: Re-rating potential sits with integrated premix manufacturers possessing captive crystallization infrastructure given PLI scheme subsidy capture and FSSAI compliance consolidation. Long-term viability favors facilities combining mineral grinding, chelation capacity, and in-house testing under single-site economics. Monitor BIS-CODEX alignment announcement timing as signal for European import displacement acceleration and domestic capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Mining | Rajasthan and Madhya Pradesh quarry control secures calcium input cost stability for dairy premix suppliers. |
| Chelated Mineral Complexation Capacity Addition | Complexation reactor installation enables organic trace mineral production competing with BASF and Kemin formulations. |
| FSSAI Laboratory Certification Investment | In-house heavy metal testing capability qualifies suppliers for Gujarat and Maharashtra cooperative procurement lists. |
| Long-term Supply Agreement with Poultry Integrators | Direct Telangana and Andhra Pradesh broiler contracts reduce wholesale channel dependence and price volatility exposure. |
| Joint Venture with Coastal Aqua Feed Mills | Andhra Pradesh shrimp feed partnerships parallel lysine-methionine fortification with specialized mineral premix supply. |
Study Parameters
Independent corroboration across premix manufacturer production data, dairy cooperative procurement records, and FSSAI compliance filings underwrites the qualitative findings in this study. Primary interviews with plant managers at integrated grinding facilities, procurement leads at Operation Flood cooperatives, distribution channel partners in Telangana poultry belts, and technical R&D directors at chelation technology providers supplied operational context. Secondary validation drew from BIS feed grade standards documentation, FSSAI contaminant limit notifications, CEA effluent discharge guidelines, PLI scheme subsidy disbursement records, and customs data on chelated mineral imports. Bottom-up capacity and consumption estimates triangulated against top-down industry association aggregates.
Comparable-period anchoring to historical mineral premix consumption patterns across the projection horizon enabled baseline calibration. The analytical framework modeled segmentation across mineral type (inorganic sulfates versus organic chelates), end-user species (dairy, poultry, aquaculture, swine), application function (basal nutrition versus targeted supplementation), and distribution channel (direct sales versus wholesale). CAGRs derived from fitted growth curves incorporating PLI scheme investment trajectories, FSSAI enforcement intensity assumptions, and species-specific herd expansion rates. Industry-specific forecast inputs included broiler integration rates in Andhra Pradesh and cooperative milk procurement volumes in Gujarat.
Underlying measurement precision varies by segment; organized dairy cooperative procurement data carries tighter precision than dispersed smallholder poultry farm consumption estimates. Forecasts reflect documented assumptions regarding BIS-CODEX alignment timing, PLI scheme continuation, and base metal price trajectory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Talc Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Limestone Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Perlite Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Mineral Adsorbent Market