
 Middle East Feed Minerals Market | 2026-2036
Middle East Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Minerals Market Foresight
Veterinary nutritionist shortages across the Gulf is bifurcating the Middle East Feed Minerals Market into integrated operations with in-house formulation teams and smaller farms dependent on imported premix suppliers. Cargill, Incorporated leverages its Jeddah distribution hub to sustain just-in-time mineral deliveries to Saudi dairy cooperatives. BASF SE anchors the premium micronutrient segment with chelated trace mineral portfolios tailored to heat-stressed ruminants. Evonik Industries AG competes through methionine-integrated mineral premixes that optimize amino acid balance in broiler diets.
Feed minerals comprise inorganic and organic compounds including calcium, phosphorus, magnesium, zinc, copper, manganese, selenium, and iron, typically formulated at inclusion rates between 0.01% and 2% of total ration weight to correct dietary deficiencies and support metabolic function in livestock. The primary commercial purpose centers on optimizing growth rates, reproductive performance, and immune competence in intensively managed animal production systems. The minerals category dominates product type revenue due to irreplaceable bulk demand for macro-minerals in dairy and feedlot operations, while amino acids represent the fastest-growing product type as producers prioritize precision protein formulation to reduce nitrogen excretion. Powder form leads volume shipments across the region's compound feed mills, though liquid mineral suspensions gain share in automated broiler drinking water systems.
SFDA veterinary feed regulations in Saudi Arabia and MOHAP import certification requirements in the UAE mandate heavy metal limits and active ingredient declarations on all mineral premix labels, effectively screening out uncertified suppliers from Asian export channels. The Emirates Authority for Standardization and Metrology enforces UAE-specific maximum permissible levels for selenium and fluorine in commercial mineral supplements, pushing distributors toward documented supply chain verification. Stakeholders must monitor pending Gulf Standardization Organization harmonization talks that could unify tolerance limits across GCC member states and reshape cross-border premix trade documentation requirements.
Market Dynamics
Veterinary nutritionist shortages across the Gulf are splitting the Middle East Feed Minerals Market into integrated operations with captive formulation teams and smaller farms tethered to imported premix distributors. This structural divide is reshaping competitive positioning and margin capture across the value chain.
Growth Catalysts
- SFDA Veterinary Feed Directives:Saudi Arabia's tightening traceability mandates for imported premixes are screening out uncertified Asian suppliers, creating protected market space for compliant distributors.
- Heat-stressed ruminant nutrition:Chelated trace mineral portfolios tailored to thermal stress conditions are commanding premium positioning in Saudi dairy cooperatives and UAE feedlot operations.
- Integrated poultry complex expansion:Abu Dhabi and Al Ain poultry clusters are scaling automated mineral supplementation through drinking water systems, driving volume demand for liquid mineral suspensions.
Market Restraints
- Import certification bottlenecks:MOHAP heavy metal testing and active ingredient verification timelines in the UAE extend premix clearance by 4-8 weeks, compressing working capital cycles for distributors.
- Macro-mineral price volatility:Phosphate rock and limestone feedstock costs fluctuate with global fertilizer market swings, destabilizing margin forecasts for bulk mineral compounders.
- Single-source premix dependency:Smaller Saudi dairy farms outside the central belt rely on Jeddah-distributed imports with no local blending capacity, exposing operations to supply interruption risk.
Strategic Opportunities
- Oman and Bahrain underpenetration:These markets lack integrated premix manufacturing, creating first-mover advantage for distributors establishing local formulation facilities.
- Gulf Standardization Organization harmonization:Pending GCC-wide tolerance limits for selenium and fluorine would streamline cross-border documentation and unlock economies of scale in regional supply chains.
- Methionine-mineral convergence:Amino acid-integrated premixes that optimize nitrogen utilization are displacing standalone mineral additives in precision broiler nutrition programs.
Industry Challenges
- Veterinary nutritionist scarcity:The Gulf region produces fewer than 50 qualified feed formulators annually, forcing producers to rely on supplier technical services rather than independent ration design.
- Dual certification complexity:Premix suppliers must maintain separate SFDA and MOHAP compliance dossiers with divergent heavy metal thresholds and label declaration formats.
- Automated system integration:Liquid mineral suspension adoption in broiler drinking water lines requires retrofitting legacy batch mixing infrastructure with precision dosing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Minerals Market |
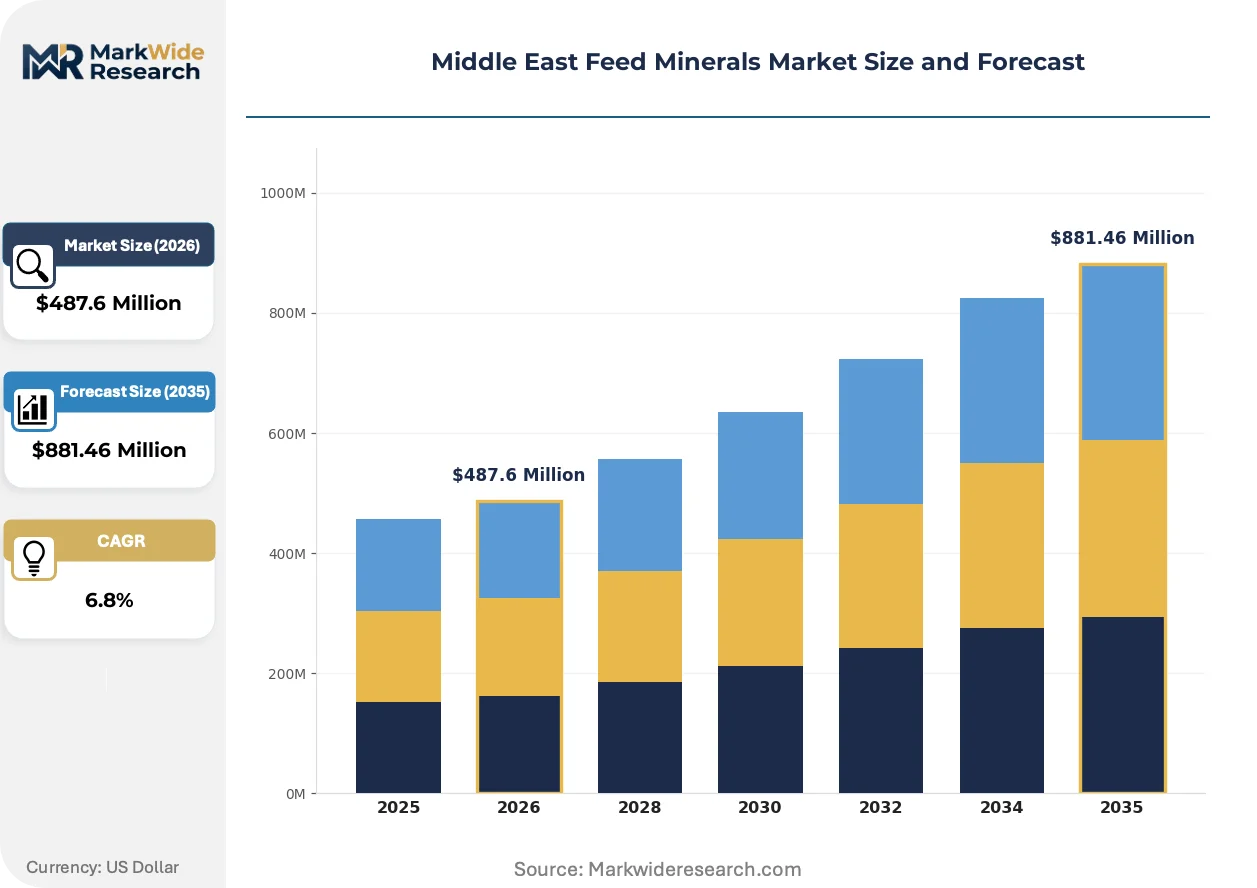
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Probiotics Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Pellets Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Adisseo, BASF SE, Cargill, Incorporated, Evonik Industries AG, Kemin Industries, Inc., ADM, Alltech, Berg+Schmidt GmbH & Co. KG, DSM-Firmenich, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Minerals Market Shifts & Advancements
Chelated trace mineral technologies and precision dosing automation are compressing traditional mineral supplementation economics across Middle East livestock operations. These shifts are forcing premix suppliers to reposition around technical service depth rather than commodity volume.
Organic trace mineral chelates utilizing glycinate and methionine complexes are decomposing the historical dominance of inorganic sulfate and oxide forms in dairy and poultry rations. Saudi dairy cooperatives with in-house nutrition teams are adopting these bioavailable alternatives at accelerating rates. This technology transition is decomposing price-based procurement models and compressing margins for suppliers locked in commodity mineral production.
SFDA and MOHAP are tightening veterinary feed directive enforcement through blockchain-anchored import documentation and real-time heavy metal screening at port of entry. These regulatory layers are raising compliance costs for uncertified premix channels. Smaller Saudi farms without dedicated regulatory affairs staff are consolidating purchases through compliant distributors to avoid clearance delays.
Buyer concentration among integrated poultry and dairy operations is compressing supplier negotiation cycles and unbundling technical advisory services from product pricing. Large UAE poultry complexes near Al Ain now contract mineral premix supply separately from nutritional consulting. This procurement pattern shift is most visible in the Abu Dhabi feed corridor where three processors account for the majority of regional mineral volume.
Middle East Feed Minerals Market Segmentation
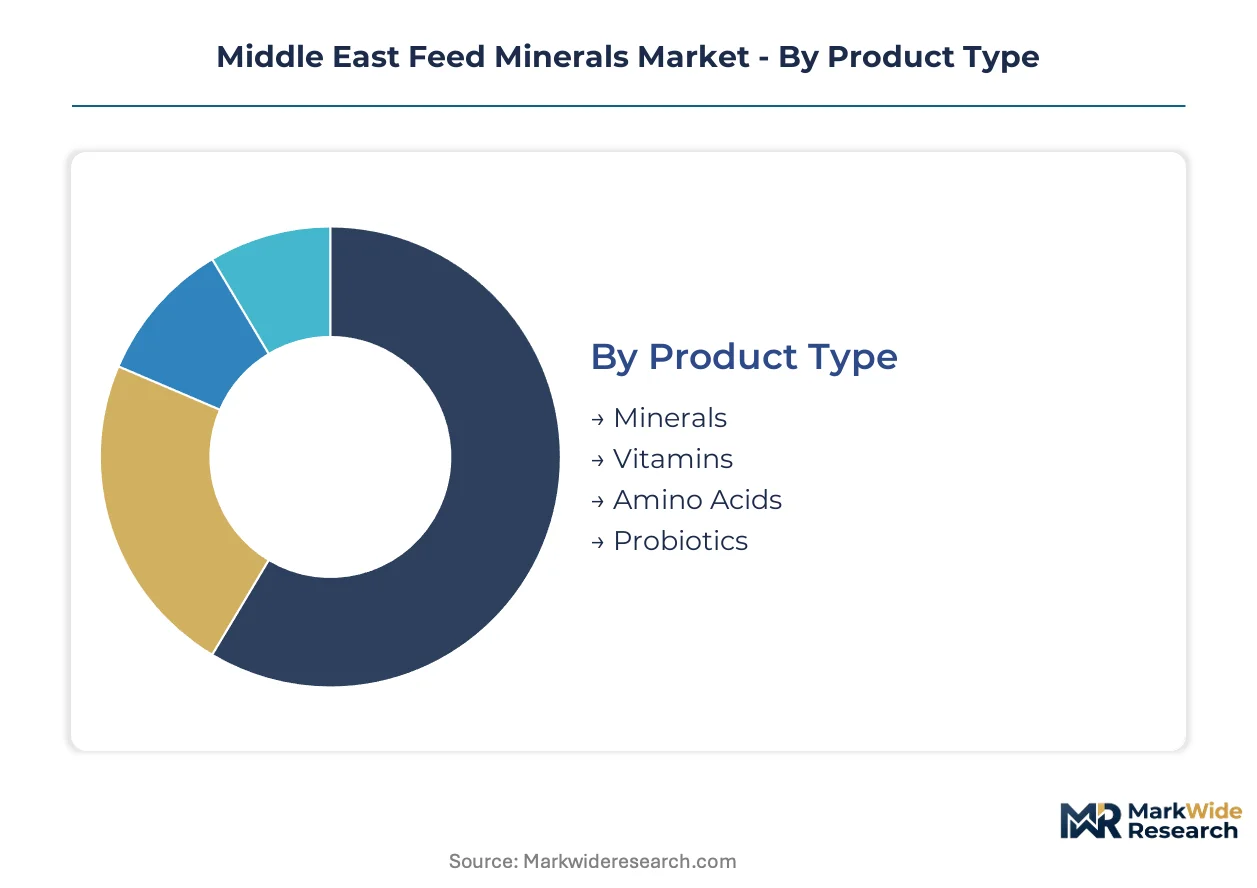
Segmentation in the Middle East Feed Minerals Market reveals distinct procurement patterns between Saudi Arabia's dairy belt and the UAE's integrated poultry corridors. Each dimension exposes structural divides between large-scale operations with captive formulation capacity and smaller farms dependent on imported premix channels.
Product Type:
Saudi Arabia's central dairy belt drives domestic mineral demand through bulk macro-mineral procurement, while amino acid premixes flow disproportionately through UAE re-export channels serving precision broiler operations.
- Minerals:Macro-minerals including calcium, phosphorus, and magnesium dominate compound feed formulations across Saudi dairy cooperatives. Bulk limestone and phosphate rock sourcing concentrates around Jeddah distribution hubs serving the central belt, with SFDA heavy metal screening creating compliance barriers for uncertified import channels.
- Amino Acids:Methionine-integrated mineral premixes optimize nitrogen utilization in UAE broiler operations near Al Ain. Precision protein formulation reduces environmental excretion while improving feed conversion ratios in heat-stressed conditions.
- Vitamins:Fat-soluble and water-soluble vitamin premixes stabilize metabolic function in intensive production systems.
- Probiotics:Direct-fed microbial additives support gut health in antibiotic-reduced rations across Gulf poultry complexes.
Minerals hold the largest share; momentum sits with amino acids.
Application:
Cost tier differentiation separates premium mineral programs in integrated UAE poultry complexes from commodity supplementation in smaller Saudi ruminant operations.
- Poultry:Automated drinking water mineral systems in Abu Dhabi and Al Ain complexes drive liquid suspension adoption. Broiler operations prioritize chelated trace minerals for thermal stress mitigation, with MOHAP certification requirements filtering supplier pools.
- Ruminants:Saudi dairy cooperatives deploy bulk macro-mineral blends for lactation support and reproductive performance. Heat-stressed feedlot operations in the UAE demand premium bioavailable trace mineral forms.
- Swine:Limited regional production restricts dedicated mineral formulation to specialized import channels.
- Aquaculture:Marine and freshwater species in Gulf coastal operations require specialized mineral premixes with modified bioavailability profiles.
Poultry commands the dominant application share; ruminant mineral sophistication is climbing fastest.
Form:
Volume concentration in powder form reflects legacy compound feed mill infrastructure, while liquid adoption tracks automation investment in integrated broiler operations.
- Powder:Standard mineral premixes flow through Saudi and UAE compound feed mills at inclusion rates between 0.01% and 2% of ration weight. Batch mixing infrastructure across the Gulf favors dry form handling for macro-mineral incorporation.
- Liquid:Suspended mineral concentrates enable precision dosing in automated broiler drinking water systems. Al Ain poultry clusters retrofit legacy infrastructure with inline metering equipment.
- Granules:Flowable granular forms reduce dust exposure in manual handling operations.
- Pellets:Compressed mineral pellets support slow-release applications in ruminant nutrition programs.
Powder retains volume leadership; liquid form is expanding most quickly.
Distribution Channel:
Customer type bifurcation concentrates direct sales among integrated operations with captive procurement teams, while distributor networks capture fragmented smaller farm demand.
- Direct Sales:Large Saudi dairy cooperatives and UAE poultry processors negotiate mineral premix supply directly with multinational suppliers. Technical service integration and volume commitments characterize these relationships.
- Distributors:Jeddah-based import distributors serve smaller Saudi farms outside the central belt with SFDA-compliant premix portfolios. Working capital cycles compress under extended MOHAP clearance timelines.
- Online Retail:Digital procurement channels emerge for standardized mineral supplements in smaller livestock operations.
- Wholesalers:Bulk mineral traders supply commodity macro-minerals to regional compounders without captive sourcing.
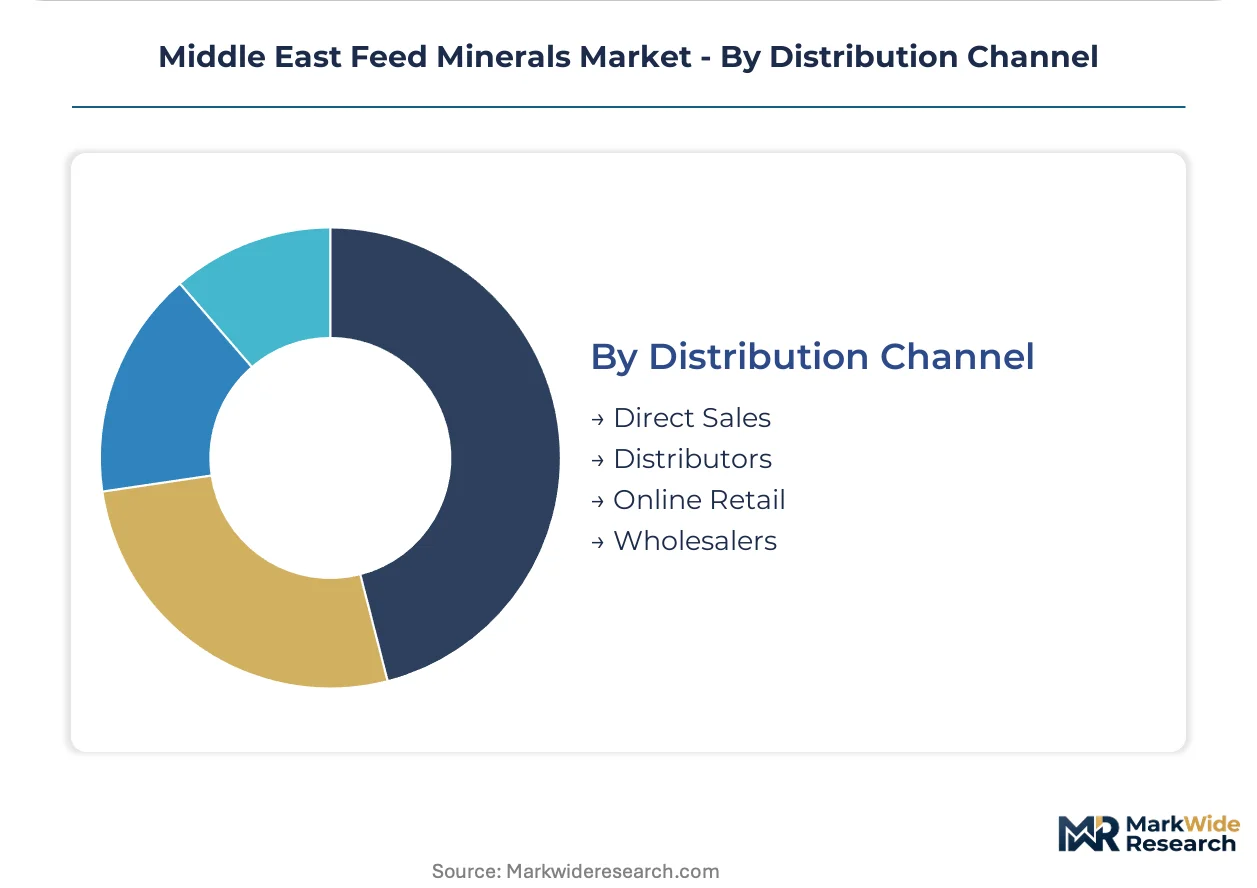
Direct sales capture the largest value share; distributor networks are gaining operational scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE consume feed minerals through fundamentally different operational models. Saudi dairy cooperatives favor bulk macro-mineral procurement for ruminant nutrition, while UAE poultry complexes prioritize precision amino acid-integrated premixes for automated systems. This consumption-mix differential shapes supplier strategies across the Gulf.
Saudi Arabia
Central dairy belt cooperatives drive demand for limestone and phosphate rock blends supporting lactation performance. SFDA veterinary feed directives mandate blockchain-anchored import documentation and real-time heavy metal screening at Jeddah port. Riyadh-based feed mills and Qassim dairy clusters concentrate procurement through compliant distributors with local formulation teams.
United Arab Emirates
Integrated poultry operations near Abu Dhabi and Al Ain scale automated drinking water mineral systems for broiler thermal stress mitigation. MOHAP import certification requirements enforce UAE-specific selenium and fluorine tolerance limits with 4-8 week clearance timelines. Dubai serves as the regional re-export hub for precision protein premixes flowing to smaller Gulf markets.
Oman
Emerging dairy and poultry sectors generate nascent demand without domestic premix manufacturing infrastructure. The country's national food security initiatives subsidize imported mineral inputs for livestock expansion programs. Muscat and Salalah port zones attract distributors establishing local blending capacity to serve underpenetrated Peninsular farms.
Qatar
Intensive dairy and camelid operations in Al Khor and Al Rayyan municipalities require specialized heat-stress mineral formulations. National veterinary regulations align with GCC standardization drafts while maintaining separate import permit systems. Doha-based logistics operators consolidate premix shipments to minimize per-unit clearance costs.
Kuwait
Small-scale poultry and ruminant farms depend on re-export channels through Saudi and UAE distributors. The national agriculture authority enforces mineral supplement labeling requirements without domestic testing infrastructure. Jahra and Wafra agricultural zones concentrate demand among operations with limited captive formulation capability.
Middle East Feed Minerals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East Feed Minerals Market. Multinational suppliers with Jeddah distribution hubs and chelated trace mineral portfolios capture premium positioning in Saudi dairy cooperatives. Regional distributors with MOHAP compliance dossiers serve fragmented UAE poultry demand. Strategic moves center on backward integration into local formulation facilities and technology licensing for precision dosing automation.
Within the integrated multinational tier, Cargill, Incorporated and BASF SE anchor supply relationships with large-scale cooperatives. Cargill leverages its Jeddah hub for just-in-time mineral deliveries to Saudi central belt operations. BASF occupies a position exemplifying premium micronutrient positioning through bioavailable trace mineral forms. Evonik Industries AG represents the amino acid-mineral convergence archetype, with methionine-integrated premixes aligning with UAE broiler precision nutrition trends.
| Leading Market Players |
|---|
| Adisseo |
| BASF SE |
| Cargill, Incorporated |
| Evonik Industries AG |
| Kemin Industries, Inc. |
| ADM |
| Alltech |
| Berg+Schmidt GmbH & Co. KG |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Jeddah distribution hub scale economies compress per-unit logistics costs for bulk mineral compounders serving Saudi dairy cooperatives, simultaneously anchoring regional price floors and concentrating procurement power among integrated operations with captive formulation teams. This structural concentration bifurcates the Middle East Feed Minerals Market into volume-anchored contract tiers for large buyers and premium-priced spot channels for fragmented farm demand.
Pricing Analysis
Long-term offtake contracts dominate mineral premix procurement among Saudi dairy cooperatives and UAE poultry complexes, locking in volume commitments against fluctuating phosphate rock and limestone feedstock costs. Price differentiation separates SFDA-certified distributors with blockchain-anchored documentation from uncertified import channels facing extended clearance timelines. Cost compression in commodity macro-mineral tiers intensifies as global fertilizer market swings destabilize margin forecasts. Smaller Saudi farms outside the central belt exhibit highest price sensitivity due to single-source premix dependency and working capital constraints.
Supply Chain Analysis
Saudi Arabia and the UAE anchor regional mineral premix supply, with Jeddah serving as the primary distribution hub for bulk limestone and phosphate rock blends while Dubai functions as the re-export corridor for precision amino acid-integrated formulations. Feedstock sourcing draws from global phosphate rock deposits and regional limestone quarries, with chelated trace mineral complexes imported from European specialty manufacturers. Single-source dependency among smaller Saudi farms without local blending capacity creates supply interruption vulnerability. Distribution runs through direct sales channels for integrated operations and Jeddah-based distributor networks for fragmented farm demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East Feed Minerals Market is positioned for cyclical recovery as Gulf Standardization Organization harmonization talks advance, potentially unifying selenium and fluorine tolerance limits across GCC member states and unlocking regional supply chain economies.
For Market Incumbents: Fortify compliance infrastructure against tightening SFDA and MOHAP veterinary feed directives by investing in blockchain-anchored import documentation systems and local formulation capacity in underpenetrated Oman and Bahrain markets. Backward integration into chelated trace mineral manufacturing protects margin position as bioavailable forms displace commodity sulfates and oxides. For New Entrants and Emerging Players: Differentiate on precision dosing automation for liquid mineral suspensions in UAE broiler drinking water systems, targeting the Al Ain poultry cluster's retrofitting wave as the most penetrable application segment. Establish MOHAP compliance dossiers early to capture distributor consolidation among smaller farms seeking clearance certainty. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors with captive local formulation teams serving fragmented Saudi dairy demand outside the central belt. Acquisition targets should demonstrate technical service depth rather than commodity volume positioning. The signal to watch is GSO harmonization implementation timing as the inflection indicator for cross-border premix trade documentation rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Local Formulation Facility Establishment | Captures margin from Jeddah-imported premixes in underpenetrated Oman and Bahrain markets. |
| Chelated Trace Mineral Portfolio Expansion | Commands premium positioning in Saudi dairy cooperatives adopting heat-stress nutrition programs. |
| Blockchain-Anchored Compliance Documentation | Accelerates SFDA and MOHAP clearance timelines for distributors screening out uncertified competitors. |
| Precision Dosing Automation Partnership | Aligns with UAE poultry complex retrofitting of legacy batch mixing infrastructure for liquid suspensions. |
| Amino Acid-Integrated Premix Development | Captures nitrogen utilization optimization demand in precision broiler nutrition programs near Al Ain. |
Research Methodology
A spread of perspectives from veterinary nutritionists at Saudi dairy cooperatives, procurement directors at UAE poultry complexes, regulatory affairs specialists navigating SFDA and MOHAP compliance, and Jeddah-based distributor operations managers converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs and trade data, GCC veterinary directive filings, and compound feed industry association reports anchored the demand sizing. Bottom-up mineral premix volume estimates triangulated against top-down livestock production forecasts.
Segmentation dimensions modeled include product type hierarchy, application species, physical form, and distribution channel structure across the projection horizon. CAGRs were derived from trend extrapolation of livestock intensification rates and regulatory compliance cost trajectories. Forecast inputs incorporated heat-stress nutrition adoption curves and automated drinking water system penetration in broiler operations.
Material uncertainties — GSO harmonization implementation delays, phosphate rock price volatility, and veterinary nutritionist supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and feed conversion efficiency gains from chelated mineral adoption. Recalibration cycles align with material shifts in GCC standardization negotiations and macro-mineral feedstock market conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Kyanite Market