
 Global Cristobalite Market | 2026-2036
Global Cristobalite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cristobalite Market Foresight
European silica processors is realigning capacity toward synthetic cristobalite output. Sibelco leverages its Belgian mining heritage to dominate specialty silica supply chains across Western Europe. Quarzwerke Group anchors German industrial demand through integrated quarzwerke-to-refinery operations. Hoben International Limited specializes in high-temperature refractory grades for UK foundry customers.
Cristobalite is a high-temperature polymorph of silicon dioxide (SiO₂), crystallizing above 1470°C with a tetragonal structure and lower bulk density than quartz at 2.33 g/cm³. Manufacturers prize its low thermal expansion coefficient and exceptional thermal shock resistance in precision casting molds and advanced ceramics. Synthetic cristobalite commands premium positioning in electronics insulation applications where purity thresholds exceed 99.5% SiO₂. Natural cristobalite occupies mature volume pools in construction additives and building materials production. Coated cristobalite variants are gaining traction in polymer fabrication as compatibilization technology improves dispersion in thermoplastic matrices.
The EPA regulates respirable crystalline silica under 29 CFR 1910.1053, mandating engineering controls that push processors toward engineered low-dust formulations. REACH classification of crystalline silica as a Category 1A carcinogen forces reformulation in European paints and coatings segments. OSHA enforcement of permissible exposure limits sustains investment in enclosed handling systems across US ceramics manufacturing. Stakeholders must monitor regulatory divergence between EPA hazard communication standards and EU MDR requirements for medical-grade silica applications.
Market Dynamics
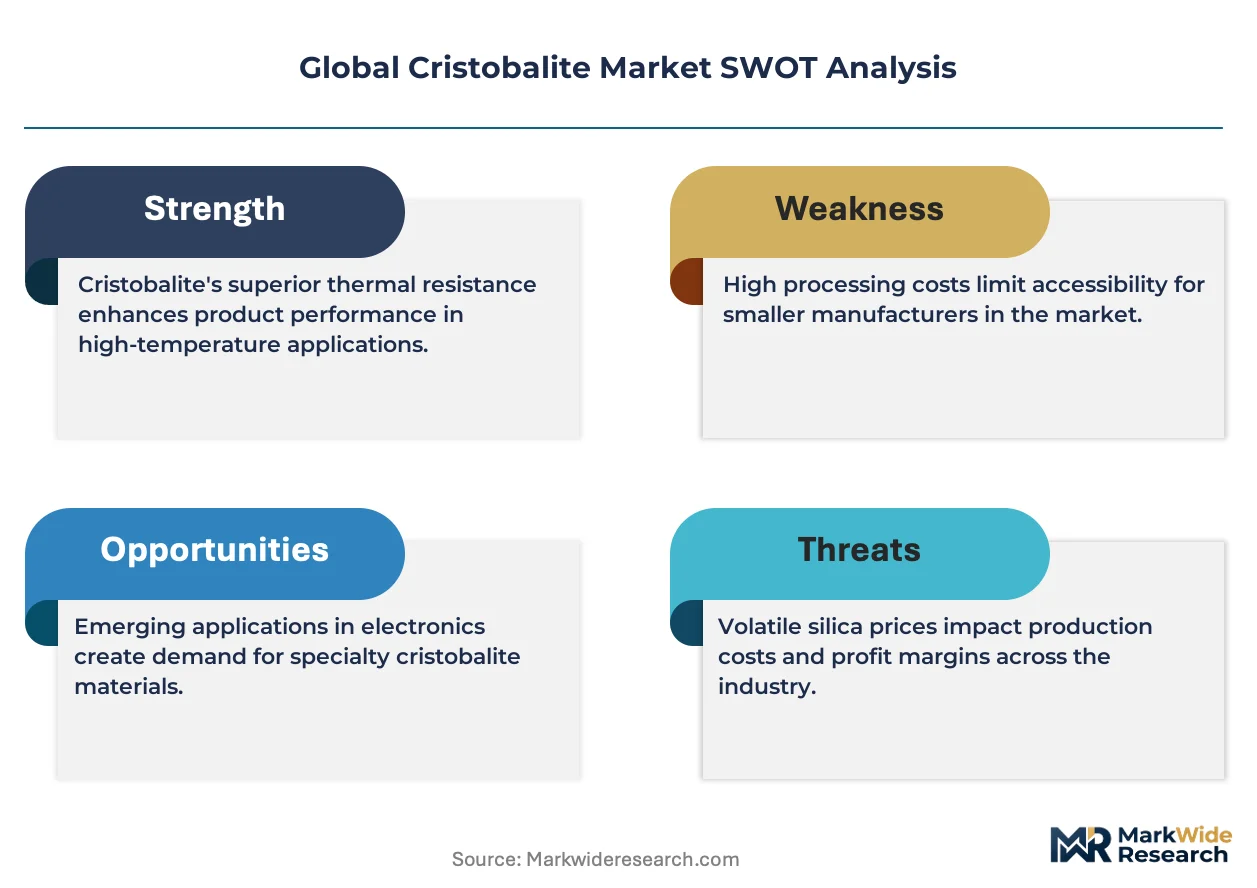
REACH classification of crystalline silica as Category 1A carcinogen is forcing European processors to reformulate product lines and migrate capacity toward engineered low-dust synthetic grades. This regulatory compression is reshaping competitive positioning across foundry, ceramics, and coatings segments simultaneously.
Growth Catalysts
- Precision casting expansion:Aerospace and automotive foundries in Germany's industrial ceramics corridor are specifying high-grade synthetic cristobalite for thermal shock-resistant mold surfaces.
- REACH-driven reformulation:The EU framework's tightened exposure limits are accelerating substitution of unprocessed quartz with coated cristobalite in paints and polymer fabrication.
- Electronics insulation demand:Semiconductor packaging manufacturers require synthetic grades exceeding 99.5% SiO₂ purity for high-temperature substrate applications.
Market Restraints
- Energy input volatility:Synthetic cristobalite production requires sustained furnace temperatures above 1470°C, making energy costs a structural margin pressure.
- Belgian supply concentration:Western European specialty silica chains depend heavily on a single heritage mining region for premium feedstock access.
- Fused silica substitution:Electronics manufacturers in some insulation tiers can substitute amorphous fused silica for crystalline cristobalite where thermal expansion tolerance permits.
Strategic Opportunities
- UK refractory upgrade cycle:British foundry operators face aging infrastructure replacement, creating white space for high-temperature grade suppliers.
- Polymer compatibilization advances:Improved dispersion technology is unifying cristobalite with thermoplastic matrices for engineered construction additives.
- OSHA enforcement tailwind:US ceramics manufacturers under 29 CFR 1910.1053 pressure represent conversion opportunity for enclosed-handling engineered formulations.
Industry Challenges
- High-temperature process engineering talent:Synthetic production requires specialized furnace operation expertise that competes with broader refractory and glass sectors.
- Dual certification complexity:Medical-grade silica applications face divergent EPA hazard communication and EU MDR documentation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cristobalite Market |
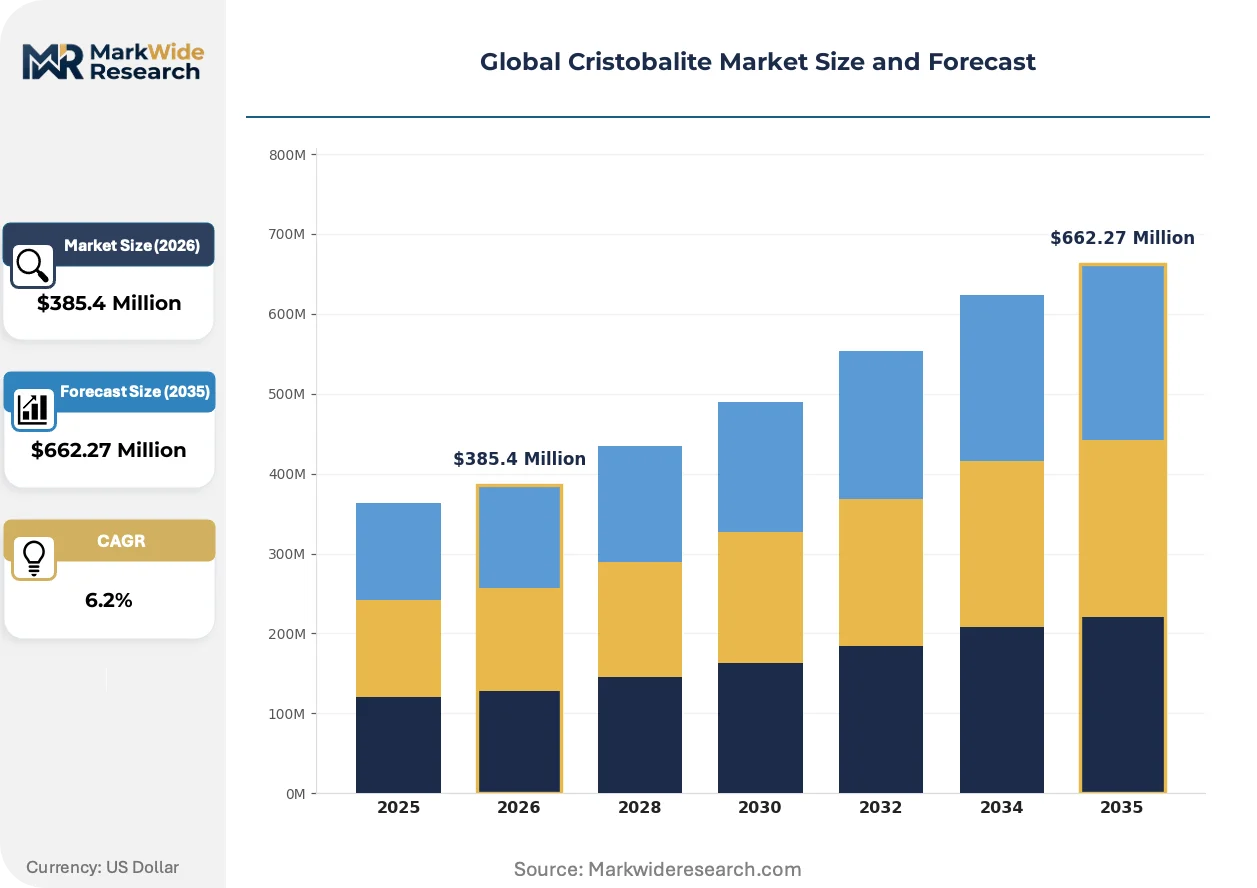
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cristobalite, Synthetic Cristobalite, High Purity Cristobalite, Coated Cristobalite Application: Construction Additives, Plastics Reinforcement, Paints & Coatings, Rubber Compounds, Electronics Insulation End User Industry: Ceramics Manufacturing, Polymer Fabrication, Chemical Processing, Electronics Assembly, Building Materials Production Packaging Type: Bulk Bags, Fiber Drums, Boxed Packaging, Loose Powder, Sealed Sacks |
| Companies Covered | Sibelco, Quarzwerke Group, Hoben International Limited, C.E.D. Process Minerals Inc., Silmer SA, Momentive, Heraeus, Jinyu Advanced Material Co., Ltd., Lianyungang Changtong Silica Powder Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cristobalite Market Shifts & Advancements
Coated cristobalite variants are unifying thermal performance with polymer processability, compressing the traditional separation between mineral fillers and engineered additives. This convergence is redrawing segment boundaries across construction and fabrication markets.
Surface functionalization chemistry is unifying cristobalite particles with silane coupling agents and polymer-specific dispersants. Thermoplastic compounders in German automotive supply chains are adopting these grades at accelerating pace. The technology is compressing raw material substitution cycles by eliminating separate compatibilization steps.
EPA enforcement under 29 CFR 1910.1053 is mandating engineering controls that elevate capital requirements for open-handling operations. US ceramics manufacturers are responding with enclosed pneumatic transfer systems and automated batching. The regulatory pressure is concentrating procurement among processors with pre-installed containment infrastructure.
Buyer specification behavior is compressing qualification cycles as end-users consolidate approved supplier lists. German industrial ceramics producers are shifting from spot purchasing to multi-year framework agreements with volume commitments. This pattern is most visible in precision casting supply chains where mold consistency requirements override price sensitivity.
Global Cristobalite Market Segmentation
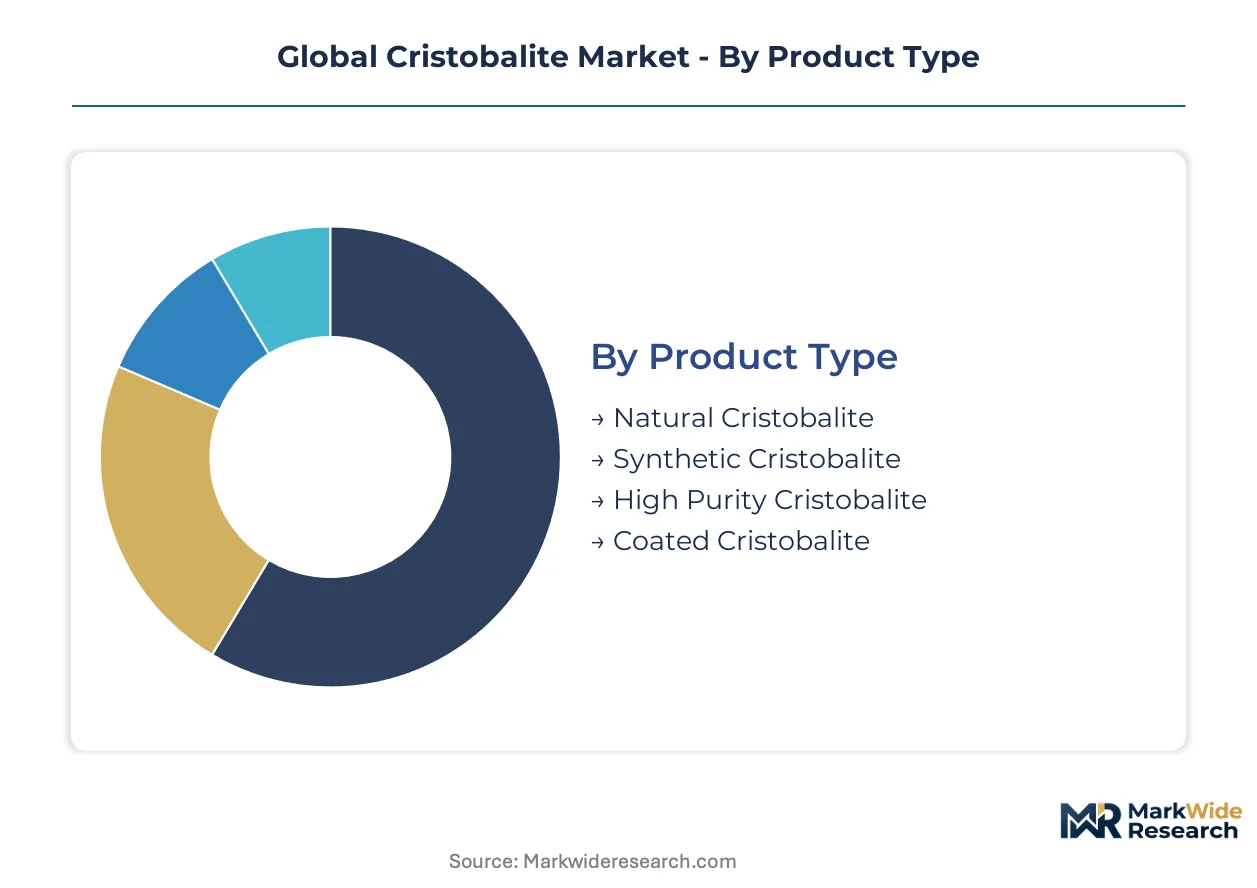
Cristobalite procurement decisions pivot on thermal performance thresholds, regulatory compliance burdens, and downstream process compatibility. Buyers segment supply by purity grade, surface chemistry, and handling format to match specific foundry, electronics, or polymer fabrication requirements.
Product Type:
Cost tier determines access to premium thermal properties and regulatory clearance.
- Natural Cristobalite:Mined silica converted through high-temperature phase transformation carries inherent mineral impurities limiting electronics use. Volume concentrates in German building materials and construction additive supply chains where cost sensitivity outweighs purity demands.
- Synthetic Cristobalite:Engineered furnace production above 1470°C delivers controlled particle morphology and consistent thermal expansion coefficients. Aerospace foundries in Germany's industrial ceramics corridor specify this grade for precision casting molds requiring thermal shock resistance.
- High Purity Cristobalite:Purification protocols achieve SiO₂ content exceeding 99.5% for semiconductor packaging substrates.
- Coated Cristobalite:Surface functionalization with silane coupling agents enables direct dispersion into thermoplastic matrices without separate compatibilization.
Volume sits with Natural Cristobalite; growth tilts toward Coated Cristobalite.
Application:
End-use thermal requirements and regulatory exposure limits reshape formulation choices.
- Construction Additives:Low-grade natural cristobalite functions as a pozzolanic extender in cementitious systems. German building materials producers absorb mature volumes under established supply contracts with limited price elasticity.
- Electronics Insulation:Synthetic grades with sub-50 ppm alkali content serve high-temperature substrate applications in semiconductor packaging. Demand concentrates where thermal expansion mismatch between silicon dies and packaging materials risks device failure.
- Plastics Reinforcement:Surface-treated grades improve dimensional stability in engineering thermoplastics.
- Paints & Coatings:REACH-driven reformulation accelerates substitution of unprocessed quartz with low-dust engineered grades.
- Rubber Compounds:Reinforcing filler applications in high-temperature gaskets and seals.
Construction Additives dominates current offtake; Electronics Insulation climbs the fastest.
End User Industry:
Customer technical capabilities and certification requirements stratify procurement patterns.
- Ceramics Manufacturing:Refractory producers in Germany's industrial corridor source synthetic grades for kiln furniture and precision casting molds. Thermal shock resistance specifications override base material costs in supplier selection.
- Electronics Assembly:Semiconductor packaging manufacturers enforce purity protocols exceeding 99.5% SiO₂ with trace element documentation. Dual certification complexity across EPA hazard communication and EU MDR documentation timelines constrains approved supplier lists.
- Polymer Fabrication:Thermoplastic compounders adopt coated grades for automotive underhood applications.
- Chemical Processing:Catalyst support and filtration media applications.
- Building Materials Production:Volume consumers with standardized quality tolerances.
Building Materials Production holds the volume base; Electronics Assembly shows the steepest expansion trajectory.
Packaging Type:
Handling automation and dust containment infrastructure dictate format selection.
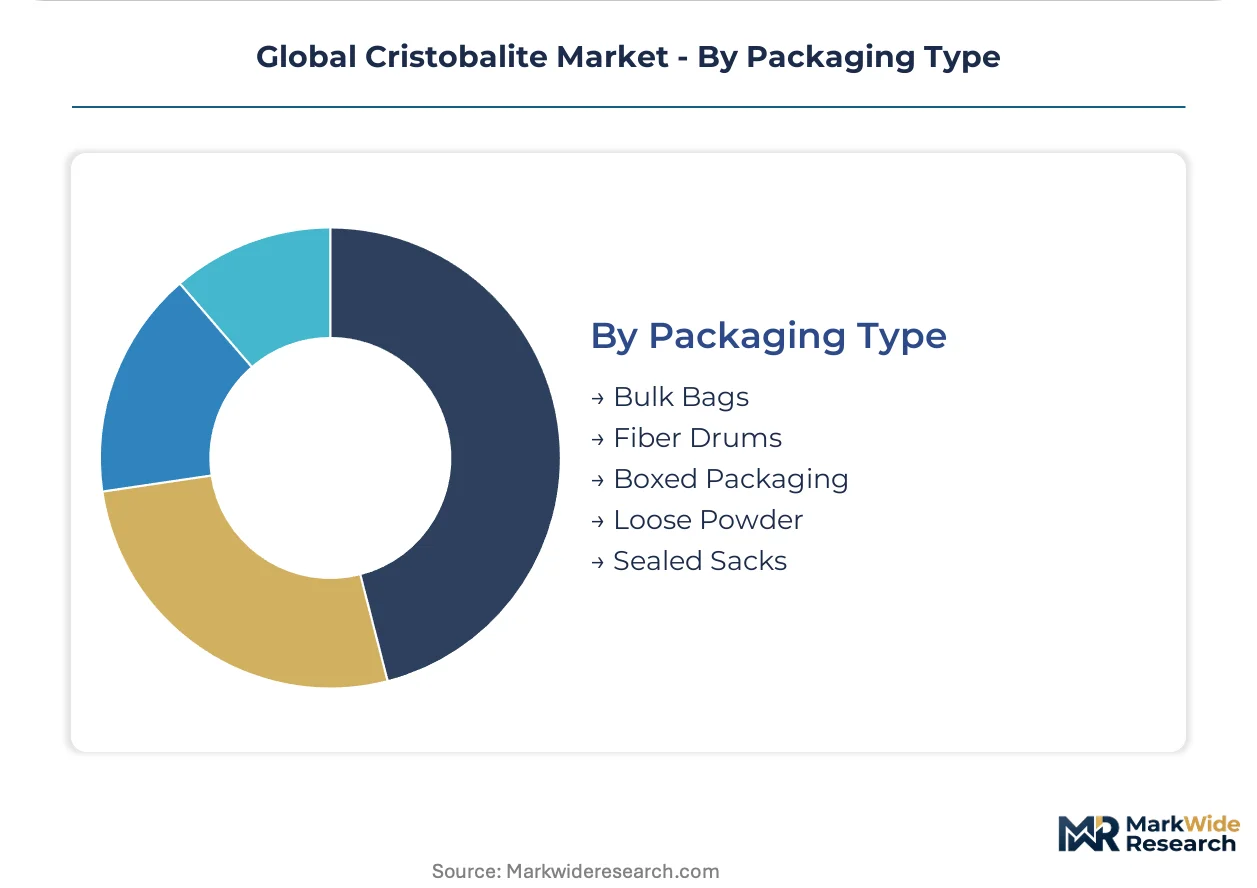
- Bulk Bags:Standardized one-tonne flexible intermediate bulk containers serve high-volume ceramics and construction customers with pneumatic unloading systems. German industrial ceramics producers favor this format for automated batching operations.
- Sealed Sacks:Multi-layer laminated packaging with welded seams contains respirable dust for REACH-compliant handling in European paints and coatings segments. ECHA classification of crystalline silica as Category 1A carcinogen elevates demand for engineered low-dust formats.
- Fiber Drums:Rigid containment for specialty electronics grades requiring moisture protection.
- Boxed Packaging:Retail-scale quantities for laboratory and pilot-scale users.
- Loose Powder:Tanker delivery to integrated processors with enclosed handling infrastructure.
Bulk Bags commands current volume; Sealed Sacks gains share fastest on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian mining heritage anchors Western European specialty silica supply chains. German industrial ceramics corridors concentrate precision casting demand. Chinese furnace capacity expands synthetic grade output for electronics insulation.
United States
OSHA enforcement under 29 CFR 1910.1053 mandates engineering controls across ceramics manufacturing. EPA hazard communication standards diverge from EU MDR requirements for medical-grade applications. Southeast industrial corridors adopt enclosed pneumatic transfer systems for dust containment compliance.
Germany
Aerospace and automotive foundries specify high-grade synthetic cristobalite for thermal shock-resistant mold surfaces. REACH classification of crystalline silica as Category 1A carcinogen forces reformulation in paints and coatings segments. The industrial ceramics corridor spanning North Rhine-Westphalia and Bavaria sources synthetic grades through multi-year framework agreements.
China
Semiconductor packaging manufacturers drive demand for synthetic grades exceeding 99.5% SiO₂ purity. GB standards and MIIT industrial policy guide high-temperature materials development. Yangtze River Delta furnace operators expand capacity for electronics insulation substrates.
United Kingdom
British foundry operators face aging infrastructure replacement cycles creating demand for high-temperature refractory grades. HSE aligns crystalline silica exposure limits with evolving EU benchmarks. Midlands and Northern England refractory producers upgrade mold material specifications.
Belgium
Heritage mining regions supply premium feedstock for Western European specialty silica chains. ECHA enforcement tightens respirable dust thresholds across downstream applications. Flanders-based processors realign capacity toward engineered low-dust synthetic output.
Global Cristobalite Market Competitive Landscape
Global majors compete with regional champions across furnace technology and regulatory compliance capabilities. The vendor base stratifies between integrated mining-to-refinery operators and specialized high-temperature grade fabricators. Three archetypes dominate: heritage mining conglomerates with Belgian feedstock access, German industrial corridor-integrated processors, and Asian furnace specialists scaling synthetic output. Competitive moves concentrate on capacity realignment toward low-dust engineered grades and multi-year supply framework negotiations with German automotive foundries.
Among heritage mining conglomerates, Sibelco occupies a position exemplifying Belgian feedstock dominance across Western European supply chains. Quarzwerke Group represents the integrated German archetype with quarzwerke-to-refinery operations anchoring industrial ceramics corridor demand. Hoben International Limited sits within the specialist tier serving UK foundry refractory requirements. These three entities illustrate the geographic stratification between Belgian feedstock access, German industrial integration, and British application specialization.
| Leading Market Players |
|---|
| Sibelco |
| Quarzwerke Group |
| Hoben International Limited |
| C.E.D. Process Minerals Inc. |
| Silmer SA |
| Momentive |
| Heraeus |
| Jinyu Advanced Material Co., Ltd. |
| Lianyungang Changtong Silica Powder Co., Ltd. |
| Others |
Supply & Pricing Matrix
German automotive foundries concentrate procurement authority through multi-year framework agreements, anchoring a contract-based long-term offtake model that privileges volume commitments over spot-market flexibility. REACH classification of crystalline silica as Category 1A carcinogen has compressed price negotiation leverage toward processors with pre-installed containment infrastructure and dual certification capabilities.
Pricing Analysis
After-sales technical support and regulatory compliance documentation are bundled into synthetic grade contracts rather than unbundled as separate line items. Three-tier pricing structure across premium, standard, and economy levels separates high-purity electronics grades exceeding 99.5% SiO₂ from foundry-specified synthetic grades and natural cristobalite for construction additives. Cost compression in natural grades is intensifying because Belgian feedstock processors face ECHA-mandated dust containment retrofit requirements. Building materials producers exhibit highest price sensitivity, while semiconductor packaging manufacturers prioritize purity thresholds over unit economics.
Supply Chain Analysis
Direct-to-foundry channels handle high-volume German industrial ceramics corridor demand, while distributor networks serve fragmented European paints and coatings segments. Supply concentrates in Belgium for premium feedstock, Germany for synthetic furnace capacity, and China for electronics-grade expansion. Production draws from high-purity quartz sand, silane coupling agents for surface functionalization, and specialized refractory furnace linings. Single-source vulnerability in Belgian mining regions exposes Western European specialty silica chains to ECHA enforcement disruptions. Distribution runs through integrated mining-to-refinery operators for bulk industrial offtake and specialty chemical distributors for coated grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-driven reformulation mandates function as a cost-of-compliance moat, elevating capital requirements for enclosed handling systems and dual certification documentation that filter out undercapitalized competitors. ECHA classification of crystalline silica as Category 1A carcinogen creates structural barriers protecting processors with pre-installed containment infrastructure.
For Market Incumbents: Cement market position through backward integration into captive high-purity quartz sand supply and capacity expansion in China's Yangtze River Delta electronics corridor. Fused silica substitution in mid-tier insulation applications threatens cristobalite volume; defend against displacement by deepening silane coupling agent R&D partnerships with German automotive compounders. For New Entrants and Emerging Players: Launch via sealed-sack distribution partnerships serving REACH-compliant European paints and coatings reformulation demand. UK foundry infrastructure replacement cycles represent the most penetrable white-space, with Midlands refractory producers upgrading aging mold specifications. Target polymer compatibilization advances in German automotive underhood applications as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors furnace specialists with synthetic grade expertise over natural cristobalite miners facing regulatory compression. Long-term viability hinges on electronics insulation purity thresholds remaining above fused silica substitution reach. Watch for OSHA enforcement acceleration under 29 CFR 1910.1053 as the signal indicating US ceramics manufacturer conversion opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Feedstock | Captive quartz sand supply secures Belgian heritage region access against ECHA concentration risk. |
| Synthetic Furnace Capacity Expansion | Yangtze River Delta installation captures semiconductor packaging purity demand from MIIT-guided industrial policy. |
| Surface Functionalization R&D Partnership | Silane coupling agent collaboration with German automotive compounders accelerates coated grade adoption. |
| Enclosed Handling Infrastructure Deployment | OSHA 29 CFR 1910.1053 compliance unlocks US ceramics manufacturer procurement qualification. |
| Dual Certification Documentation Investment | EPA hazard communication and EU MDR alignment enables medical-grade silica application access. |
Research Methodology
Trade databases, ECHA regulatory filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with refractory plant managers, silica procurement leads at German automotive foundries, distribution channel partners in Western European coatings segments, and technical R&D directors at polymer compounders. Bottom-up volume triangulation across product grades, applications, and end-user industries was validated against top-down market sizing from production capacity assessments and import-export flow analysis.
Historical trendline analysis of furnace capacity utilization, purity grade pricing spreads, and regulatory compliance cost trajectories informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type tiers, end-use thermal requirements, packaging format automation levels, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted demand curves and substitution threat assessments, with energy input volatility and REACH enforcement timelines as critical forecast sensitivity inputs.
Energy cost shocks, ECHA reclassification of exposure thresholds, and fused silica substitution acceleration in electronics insulation are the dominant revision risks to base case assumptions. Forecasts reflect documented assumptions regarding furnace technology diffusion rates and regulatory harmonization patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Potash Ores Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Slate Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Limestone Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Perlite Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Fluorspar Market