
 Unexpanded Perlite Market | 2026-2036
Unexpanded Perlite Market Size, Share, and Industry Trends Forecast 2026-2036
Unexpanded Perlite Market Analysis
Specialty mineral distribution is fragmenting across the unexpanded perlite supply chain as regional quarries bypass traditional bulk traders. Imerys S.A. leverages its European processing footprint to sustain long-term contracts with construction material formulators. Hess Perlite anchors North American supply through direct rail-to-plant logistics, while Gulf Perlite LLC competes on proximity to Middle East project sites.
Unexpanded perlite denotes the raw, thermally unprocessed volcanic glass containing two to five percent water by mass, which expands upon heating to form lightweight cellular particles used primarily as aggregate and insulation feedstock. The mineral forms from rapid cooling of acid lavas and requires controlled milling to achieve specified mesh sizes before expansion. Aggregate grades for lightweight concrete dominate volume flows, while insulation material commands premium positioning in energy-efficient building codes. Thermal insulation applications for unexpanded perlite are expanding fastest as passive construction standards tighten across temperate climates.
EPA mining discharge rules and OSHA silica exposure limits shape extraction economics and workplace compliance costs for domestic producers. REACH registration requirements in Europe restrict unexpanded perlite imports lacking full chemical safety dossiers, channeling procurement toward certified suppliers. Stakeholders must monitor evolving building energy codes and carbon border adjustments that will revalue domestic versus imported mineral sourcing.
Market Dynamics
Lightweight concrete specifications are tightening across temperate climate building codes, pulling unexpanded perlite into structural aggregate formulations that displace heavier mineral alternatives. This specification shift concentrates procurement among certified quarries capable of consistent mesh-grade delivery.
Growth Catalysts
- Passive house construction mandates:Germany's EnEV energy code and comparable standards in Austria and Switzerland require thermal bridge-free envelope materials. Unexpanded perlite feedstock for insulation-grade expanded product satisfies these performance thresholds.
- EPD-driven material selection:Construction material specifiers increasingly demand Environmental Product Declarations under EN 15804. Certified perlite quarries with verified lifecycle data capture specification-driven procurement from green building projects.
- Rail-served quarry proximity:Domestic sourcing incentives under the US Inflation Reduction Act favor minerals extracted within defined transportation radii. Direct rail loading from Wyoming and New Mexico deposits reduces delivered cost to Texas and California concrete plants.
Market Restraints
- Energy cost volatility:Expansion furnaces consume natural gas or electricity at 850-1100°C. Input energy price spikes compress margins for expander-processors captive to spot market exposure.
- Turkish supply concentration:Bergama district quarries anchor Mediterranean basin unexpanded perlite volume. Geopolitical friction or export licensing delays propagate through European and Middle Eastern supply chains.
- Substitute mineral competition:Expanded shale and clay lightweight aggregates from US domestic kilns compete on freight advantage for concrete applications less sensitive to thermal performance.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea Project concrete specifications emphasize low-density structural elements. Proximate Gulf Perlite processing capacity positions regional quarries for long-term offtake agreements.
- CSRD supply chain disclosure:EU Corporate Sustainability Reporting Directive mandates Scope 3 mineral traceability. Early-certified quarries capture premium positioning in European construction chemical formulator procurement.
- Geopolymer binder convergence:Alkali-activated cement chemistry utilizing unexpanded perlite as aluminosilicate feedstock is virtualizing traditional Portland cement displacement in precast applications.
Industry Challenges
- Silica respirable dust compliance:OSHA Permissible Exposure Limits for crystalline silica require engineered controls at milling and bagging operations. Small-scale quarries face capex barriers to automated dust suppression retrofit.
- REACH dossier completion timelines:ECHA registration for unexpanded perlite as an industrial mineral demands toxicological and ecotoxicological study compilation. Non-EU quarries without EU-based Only Representative arrangements face market exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unexpanded Perlite Market |
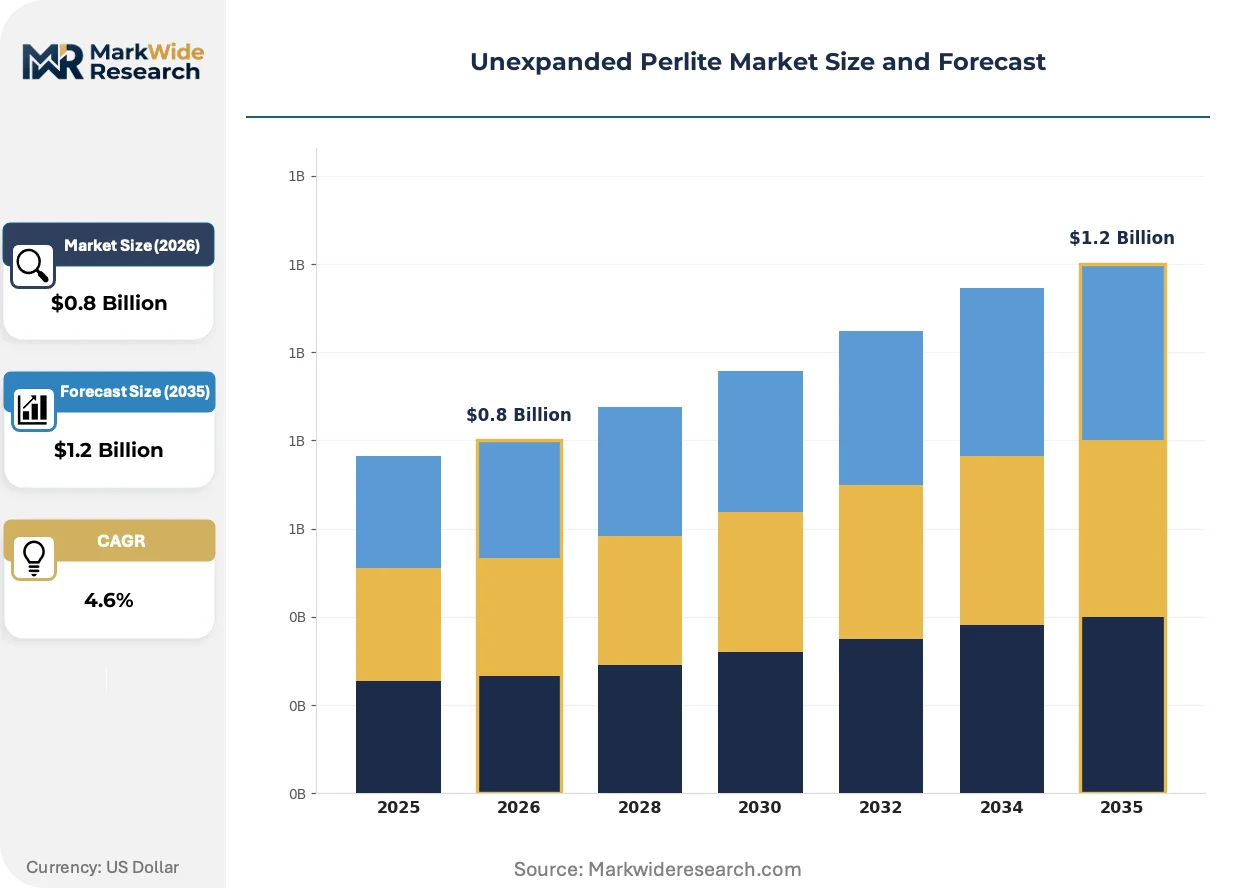
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aggregate, Insulation Material, Soil Amendment, Fillers End Use Industry: Construction, Horticulture, Manufacturing, Agriculture Application: Lightweight Concrete, Growing Media, Thermal Insulation, Fireproofing Distribution Channel: Online Retail, Bulk Supply, Direct Sales, Wholesalers |
| Companies Covered | Cornerstone Industrial Minerals, Hess Perlite, Imerys S.A., Gulf Perlite LLC, Carolina Perlite Company, Dicalite Management Group, Silbrico Corporation, Bergama Mining, Perlite-Hellas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unexpanded Perlite Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are restructuring competitive advantage around certified traceability and energy-efficient expansion rather than raw extraction scale alone.
Continuous expansion furnace control systems utilizing real-time temperature and density feedback loops are virtualizing batch kiln operations that previously required manual operator intervention. European insulation material producers deploy these systems to reduce energy intensity per cubic meter of expanded product. The technology compresses variable cost differentials between established processors and new market entrants.
REACH Article 33 disclosure obligations for Substances of Very High Concern now extend through construction product supply chains. ECHA enforcement prioritizes industrial mineral importers lacking full substance dossiers. Turkish and Greek quarries with completed registration packages capture specification lock-in from German and French formulators facing downstream liability exposure.
Long-term offtake contracting is displacing spot market purchasing among major concrete admixture producers. Buyers consolidate supplier panels to three to five certified quarries per region, trading price flexibility for volume security and EPD consistency. This concentration is most visible in the US Southwest, where Texas and Arizona ready-mix producers align procurement with rail-served Wyoming deposits under multi-year agreements.
Unexpanded Perlite Market Segmentation
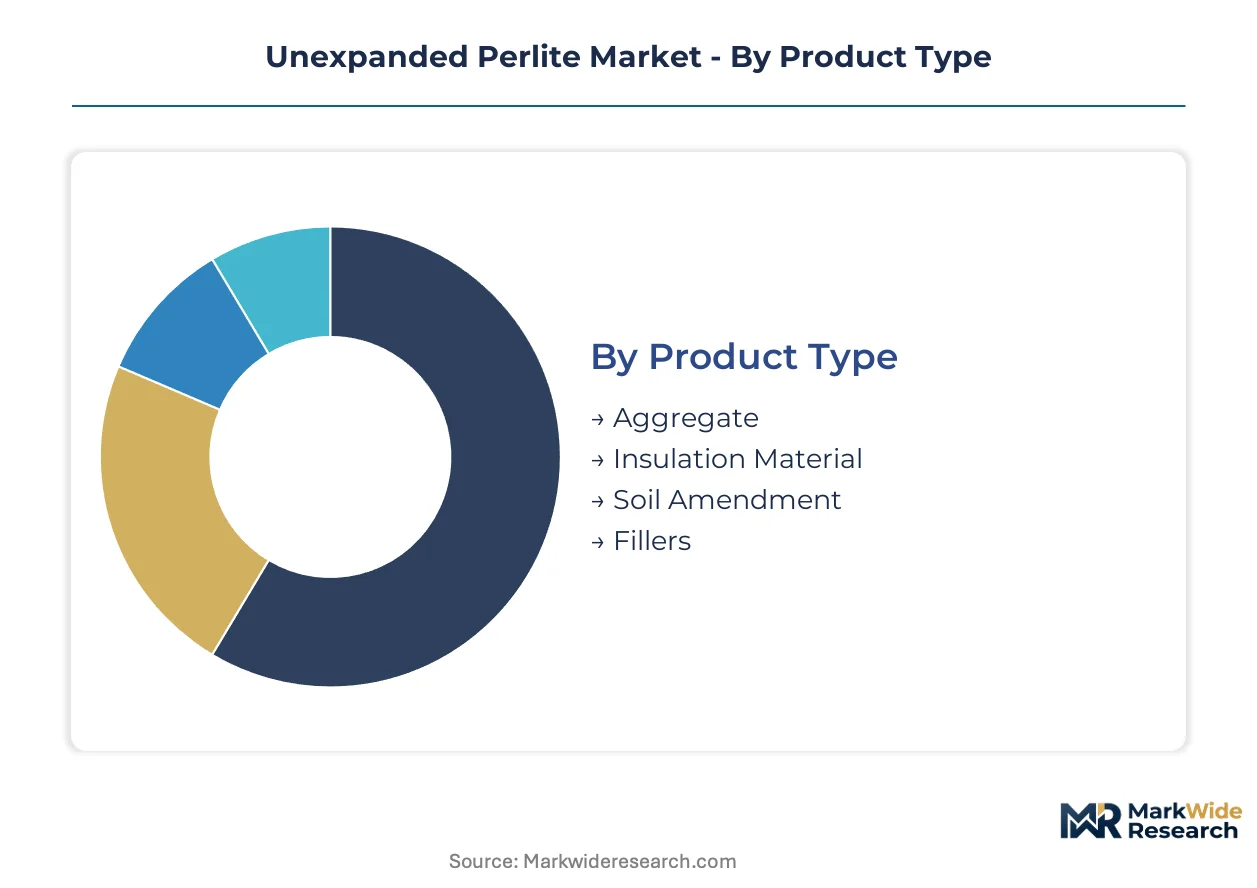
Unexpanded perlite segmentation tracks how mineral grades flow through distinct value chains before expansion. Specification requirements vary sharply between structural concrete feedstock and precision horticulture substrates. Understanding these segment boundaries clarifies where procurement power concentrates and where margin pools form.
Product Type:
Aggregate grades turn over fastest through bulk construction contracts, while soil amendment specifications cycle slowly through seasonal agricultural planning. Insulation material and fillers occupy intermediate velocity tiers tied to building code revision calendars.
- Aggregate:Coarse-crushed volcanic glass with controlled particle size distribution for concrete batching. Demand concentrates in Turkey's Bergama district and Wyoming railheads serving Texas ready-mix plants under multi-year offtake agreements tied to infrastructure project pipelines.
- Insulation Material:Fine-milled grades optimized for expansion furnace density targets in thermal envelope applications. German and Austrian passive house builders specify certified quarries with verified lifecycle data under EN 15804 EPD requirements.
- Soil Amendment:Horticultural grades with neutral pH and controlled porosity for container growing media.
- Fillers:Industrial mineral grades for construction chemicals and coatings requiring REACH dossier compliance.
Aggregate dominates installed base. Insulation material is where expansion concentrates.
End Use Industry:
Construction procurement runs on project-tied volume spikes, while horticulture and agriculture follow seasonal replenishment rhythms. Manufacturing demand fluctuates with coatings and adhesives production schedules.
- Construction:Structural lightweight concrete and thermal envelope applications driving specification-grade quarry certification. Saudi giga-projects and German EnEV-compliant buildings pull volume through certified supply chains with EPD documentation.
- Manufacturing:Industrial filler applications in construction chemicals, coatings, and fireproofing compounds requiring consistent mesh distribution and low silica variability.
- Horticulture:Professional growing media and soilless cultivation substrates.
- Agriculture:Field soil conditioning and moisture retention amendments.
Construction commands volume leadership. Manufacturing is climbing the fastest on specification premium capture.
Application:
Lightweight concrete specifications lock in multi-year supply relationships, while growing media procurement rotates seasonally. Thermal insulation and fireproofing applications track building code adoption curves across jurisdictions.
- Lightweight Concrete:Structural aggregate displacing heavier minerals in low-density concrete for high-rise and long-span applications. Texas and Arizona producers align with Wyoming rail-served deposits under IRA domestic sourcing incentives.
- Thermal Insulation:Expanded perlite for cavity fill and loose-fill applications meeting passive house energy codes. European processors deploy continuous furnace control to reduce energy intensity per cubic meter.
- Growing Media:Soilless cultivation substrates for greenhouse and nursery operations.
- Fireproofing:Spray-applied and board-stock applications in commercial construction.
Lightweight concrete anchors procurement scale. Thermal insulation is gaining share fastest on energy code tightening.
Distribution Channel:
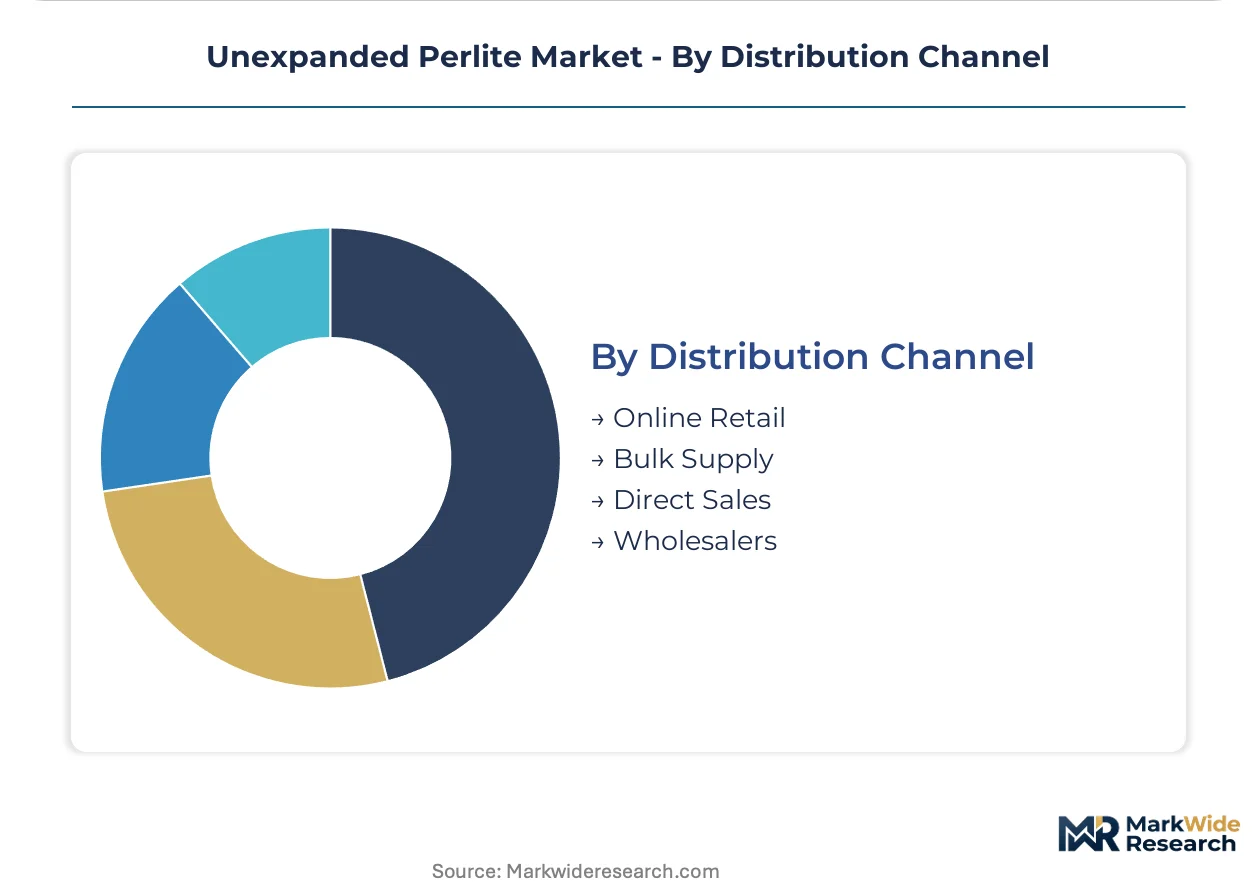
Bulk supply contracts extend across years with volume guarantees, while online retail serves spot horticulture demand. Direct sales and wholesalers occupy intermediate positions on customer scale and specification complexity.
- Bulk Supply:Rail-to-plant logistics for ready-mix concrete producers and expansion furnace operators. Hess Perlite leverages direct Wyoming rail loading to serve Southwest US plants.
- Direct Sales:Long-term offtake agreements between certified quarries and major admixture producers consolidating supplier panels to three to five sources per region.
- Online Retail:Packaged horticultural grades for professional and consumer growing media markets.
- Wholesalers:Regional mineral distributors serving smaller concrete plants and specialty manufacturers.
Bulk supply dominates tonnage flows. Direct sales is where procurement consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ankara-Izmir rail corridor moves unexpanded perlite from Bergama district quarries to Izmir Port for Mediterranean export. This infrastructure anchors Turkey's position as the dominant regional supplier. German and Austrian passive house builders source certified grades through this corridor under REACH-compliant supply chains.
United States
Wyoming's rail-served deposits feed Texas and Arizona ready-mix plants under Inflation Reduction Act domestic sourcing incentives. OSHA silica exposure limits shape milling compliance costs at western operations. The Mountain West cluster around Superior, Wyoming anchors supply for Southwest concrete producers consolidating procurement panels.
Germany
EnEV energy code mandates pull insulation-grade feedstock through certified quarries with verified EN 15804 EPD documentation. ECHA REACH enforcement prioritizes importers with complete substance dossiers. The Rhine-Ruhr industrial corridor concentrates expansion furnace operations serving passive house construction across Austria and Switzerland.
Turkey
Bergama district quarries supply Mediterranean basin volume for lightweight concrete and thermal envelope applications. Export licensing delays propagate through European supply chains during geopolitical friction periods. The Aegean coastal cluster around Izmir processes raw grades for Middle East project sites including Saudi giga-developments.
Saudi Arabia
NEOM and Red Sea Project concrete specifications emphasize low-density structural elements demanding consistent mesh-grade delivery. SFDA mineral import standards align with Gulf Cooperation Council technical regulations. The Tabuk-NEOM corridor positions proximate processing capacity for long-term offtake agreements with concrete admixture producers.
United Arab Emirates
Dubai and Abu Dhabi high-rise construction specifications drive procurement of aggregate grades displacing heavier mineral alternatives. MOHAP construction material standards incorporate thermal performance thresholds for envelope systems. The Jebel Ali industrial zone concentrates expansion capacity serving Gulf state project pipelines.
Unexpanded Perlite Market Vendor Landscape
On the supply side, the industry is consolidating around certified quarries capable of consistent mesh-grade delivery and full regulatory dossier compliance. Small-scale operators face capex barriers to automated dust suppression retrofit under OSHA and equivalent standards. Three archetypes dominate: integrated miners with direct rail logistics, regional processors serving single-country markets, and specialty distributors capturing specification premium in green building procurement. Competitive moves concentrate on long-term offtake contracting and EPD certification investment rather than spot market price competition.
Among North American integrated miners, Hess Perlite exemplifies the rail-served quarry archetype with Wyoming-based extraction. Imerys S.A. occupies a position within the European processor tier, leveraging continental processing footprint for construction material formulator contracts. Gulf Perlite LLC represents the regional proximity specialist, anchoring Middle East supply for Saudi and UAE project sites. These three patterns illustrate how geography and logistics configuration structure competitive positioning more than extraction scale alone.
| Leading Market Players |
|---|
| Cornerstone Industrial Minerals |
| Hess Perlite |
| Imerys S.A. |
| Gulf Perlite LLC |
| Carolina Perlite Company |
| Dicalite Management Group |
| Silbrico Corporation |
| Bergama Mining |
| Perlite-Hellas |
| Others |
Supply Flow & Price Mechanics
Turkish export licensing volatility determines both pricing tier spreads and supply chain shape, compressing margins for European processors dependent on Bergama district feedstock while rewarding vertically integrated operators with captive quarry access. Buyers facing REACH compliance deadlines pay premiums for certified supply chains with completed ECHA dossiers, widening the spread between documented and undocumented grades.
Pricing Analysis
Volume-discount tiering structures dominate procurement between ready-mix concrete producers and rail-served quarries, with multi-year offtake agreements locking in aggregate-grade pricing at scale. Certification premiums for EN 15804 EPD documentation and REACH dossier completion separate insulation-grade feedstock pricing from commodity aggregate tiers. Pricing pressure stems from energy cost volatility at expansion furnace operations, where natural gas exposure compresses processor margins. Ready-mix concrete producers exhibit highest price sensitivity due to project-tied bidding constraints, while passive house builders accept certification premiums for thermal performance guarantees.
Supply Chain Analysis
Upstream feedstock extraction concentrates in Turkey's Bergama district, Wyoming's rail-served deposits, and Greece's Aegean coastal quarries. Milling equipment, dust suppression systems, and rail loading infrastructure constitute critical capital dependencies. Single-source vulnerability runs through Turkish export corridors, where geopolitical friction propagates licensing delays into European supply chains. Distribution runs through bulk rail contracts to expansion furnace operators and direct sales to certified concrete admixture producers consolidating supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: REACH dossier completion and EPD certification create switching costs that lock formulators into validated supply relationships.
For Market Incumbents: Insulate market position by completing CSRD-aligned Scope 3 traceability documentation ahead of EU Corporate Sustainability Reporting Directive enforcement, and secure backward integration into rail-served quarry assets to displace spot-market exposure. Substitute mineral competition from expanded shale kilns threatens aggregate-grade margins, making captive Wyoming or Bergama district supply the priority defensive lever. For New Entrants and Emerging Players: Saudi giga-project concrete specifications for low-density structural elements represent the most penetrable entry point, given proximate Gulf Perlite processing capacity and multi-year offtake appetite. Geopolymer binder chemistry utilizing unexpanded perlite as aluminosilicate feedstock offers a second white-space angle. Go-to-market execution should emphasize direct technical sales to concrete admixture producers seeking panel diversification. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified quarries with completed REACH packages and rail logistics infrastructure. Long-term viability over the next decade hinges on regulatory compliance moats rather than extraction scale alone. Acquisition targets should display EPD certification traction and direct rail access. The signal to watch is ECHA enforcement intensity against undocumented Turkish imports, which would accelerate valuation premiums for compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail-Served Quarries | Wyoming and Bergama district deposits anchor supply security under IRA domestic sourcing incentives. |
| EPD Certification Investment | EN 15804 documentation captures specification-driven procurement from German passive house builders. |
| Long-term Offtake Contracting | Multi-year agreements with Texas ready-mix producers displace spot market price volatility exposure. |
| Continuous Furnace Technology Deployment | Real-time density feedback loops reduce energy intensity per cubic meter at European insulation processors. |
| CSRD Supply Chain Disclosure Preparation | Early Scope 3 traceability positioning captures premium procurement from EU construction chemical formulators. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with quarry operations managers, concrete admixture procurement leads, expansion furnace engineers, and EPD certification consultants; and secondary validation through ECHA registration databases, USGS mineral commodity summaries, SEC filings from listed industrial mineral processors, and EN 15804 EPD registry records. Bottom-up volume modeling across aggregate, insulation, and filler grades was triangulated against top-down construction sector mineral demand estimates.
Forecast inputs considered grade tier, end-use industry, regional production hub, and regulatory compliance status across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro construction activity indices. Energy code adoption curves, IRA domestic sourcing incentive implementation, and Saudi giga-project concrete demand schedules served as industry-specific forecast inputs.
Stress conditions across Turkish export licensing disruptions, natural gas price spikes at expansion operations, and OSHA silica compliance cost escalations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from building code acceleration or carbon border adjustment implementation. Cross-checking against USGS mineral yearbook production statistics and ECHA registration completion timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Talc Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Global and US Inorganic Salt Market