
 Industrial Salts Market | 2026-2036
Industrial Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Salts Market Outlook
Long-term supply contracts with embedded price-adjustment clauses is recalibrating how industrial salt gets sold, shifting volume risk from buyers to producers. Cargill Inc. leverages its extensive North American terminal network to control last-mile delivery economics. K+S AG anchors European deicing supply through its underground mining complex in Germany. Compass Minerals International Inc differentiates via vertically integrated solar evaporation assets in Utah and Ontario.
Industrial salts comprise sodium chloride, potassium chloride, calcium chloride, and magnesium chloride supplied in purities ranging from technical grade to food-grade specifications exceeding 99.9% NaCl content; these compounds serve as feedstock for chlor-alkali production, dust suppression, and chemical synthesis. Sodium chloride dominates volume throughput due to its irreplaceable role in caustic soda and chlorine manufacturing, though calcium chloride commands premium pricing in low-temperature deicing and concrete acceleration. Water treatment applications are expanding fastest as municipalities adopt membrane-based desalination and brine recovery systems requiring consistent salt quality.
EPA effluent limitations under the Clean Water Act, EU REACH registration requirements for chloride discharges, and China's MEE emission standards for salt-chemical clusters collectively elevate compliance costs for producers while filtering subscale competitors from tender processes. ISO 9001 and FSSC 22000 certifications now function as baseline qualifiers for food-processing and pharmaceutical-grade contracts rather than differentiators. Stakeholders must monitor evolving brine disposal regulations and carbon-intensity disclosures, as these criteria increasingly determine facility permitting and offtake agreements.
Market Dynamics
Brine purification capacity expansion across water treatment utilities is absorbing capital flows and reshaping contract structures, as EPA and EU discharge standards force municipal buyers to secure multi-year supply agreements with embedded quality clauses.
Growth Catalysts
- Membrane-based desalination:Municipal water districts in the United States are scaling reverse osmosis installations, requiring pharmaceutical-grade sodium chloride for pretreatment and membrane preservation protocols.
- REACH registration requirements:EU chloride discharge mandates are filtering subscale producers from tender processes, concentrating volume with certified suppliers capable of continuous brine quality documentation.
- Low-temperature deicing:Calcium chloride demand from northern European road maintenance authorities is accelerating as magnesium chloride loses effectiveness below minus fifteen degrees Celsius.
Market Restraints
- Natural gas price volatility:Vacuum pan refining operations in Germany and the Netherlands face margin compression when feedstock energy costs spike, forcing output curtailments during winter demand peaks.
- Solar evaporation dependency:Utah and Ontario production clusters remain vulnerable to precipitation anomalies and drought cycles that compress harvest yields unpredictably.
- Rock salt substitution ceiling:Premium-grade chemical synthesis applications cannot downgrade to crushed rock salt due to insoluble impurity thresholds, locking buyers into higher-cost supply tiers regardless of price spreads.
Strategic Opportunities
- Brine recovery systems:China's MEE emission standards for salt-chemical clusters are mandating closed-loop brine processing, creating demand for purification technology integrators and consistent feedstock suppliers.
- Pharmaceutical-grade certification:FSSC 22000 and ISO 9001 baseline requirements are widening the compliance gap between commodity and specialty producers, rewarding early certification investments with contract stickiness.
- Direct-to-utility digital platforms:Road maintenance authorities in Scandinavia are piloting algorithmic salt ordering systems that bypass traditional distributor networks, compressing lead times and capturing margin.
Industry Challenges
- Process automation talent scarcity:Solar evaporation facilities require instrumentation specialists capable of managing remote monitoring systems across dispersed pond networks, a skill set concentrated in agricultural rather than chemical engineering pipelines.
- Legacy ERP integration:Underground mining operators in Germany are struggling to retrofit SAP and Oracle systems with real-time purity tracking required by chlor-alkali customers, delaying contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Salts Market |
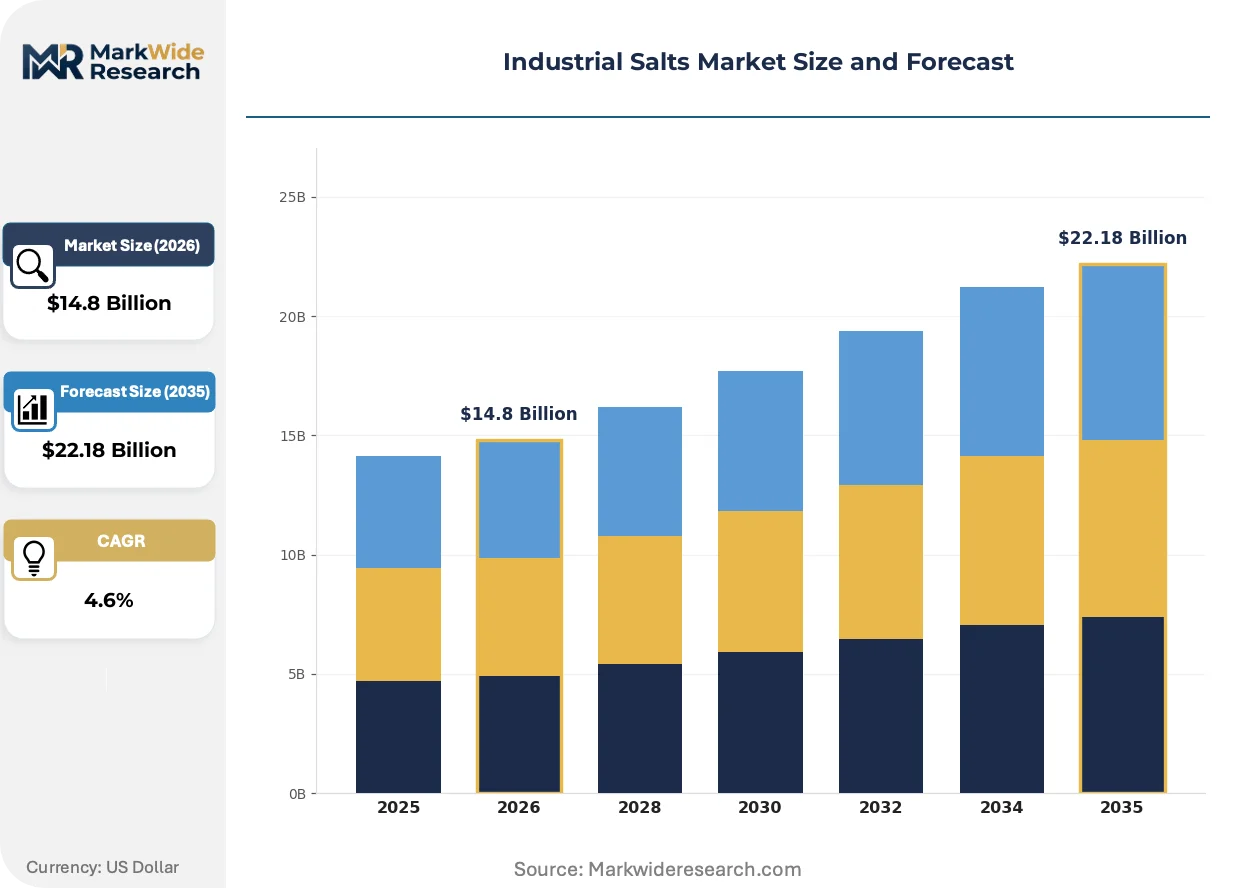
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Chloride, Potassium Chloride, Calcium Chloride, Magnesium Chloride Application: Water Treatment, Chemical Manufacturing, Deicing, Agriculture End User: Manufacturing, Food Processing, Oil & Gas, Mining Packaging Type: Bulk Bags, Drums, Bags, Sachets |
| Companies Covered | Cargill Inc., Compass Minerals International Inc, INEOS Group Ltd, K+S AG, Tata Chemicals Limited, China National Salt Industry Corporation, Nouryon Chemicals B.V., Rio Tinto PLC, Mitsui & Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Salts Market Strategic Shifts
Production technology and regulatory compliance are converging to compress the viable supplier base while elevating quality documentation requirements across all purity tiers.
Membrane electrodialysis reversal systems are absorbing investment from chlor-alkali producers seeking to reduce brine pretreatment chemical consumption. Cargill and K+S AG are piloting these installations at select North American and German facilities, replacing lime-soda softening with continuous electrodeionization. This technology is absorbing the capital that previously flowed into conventional vacuum pan expansions, reshaping capacity addition decisions.
EPA effluent limitations under the Clean Water Act are tightening total dissolved solids thresholds for industrial dischargers, forcing salt-chemical clusters in Louisiana and Texas to install zero-liquid-discharge crystallizers. The industrial consequence is a 15-20% increase in per-ton processing costs for facilities without captive brine recovery. Chlor-alkali producers in the Gulf Coast region are responding by consolidating feedstock sourcing with vertically integrated suppliers capable of certifying upstream brine provenance.
Long-term offtake agreements with embedded price-adjustment mechanisms are displacing spot market transactions for premium-grade material. Municipal water treatment authorities and regional road maintenance consortiums are locking in five to seven year contracts indexed to natural gas and transportation benchmarks, compressing the spot market to lower-purity industrial grades. This pattern is most visible in Germany and the northeastern United States, where winter deicing demand volatility previously favored flexible procurement.
Industrial Salts Market Segmentation
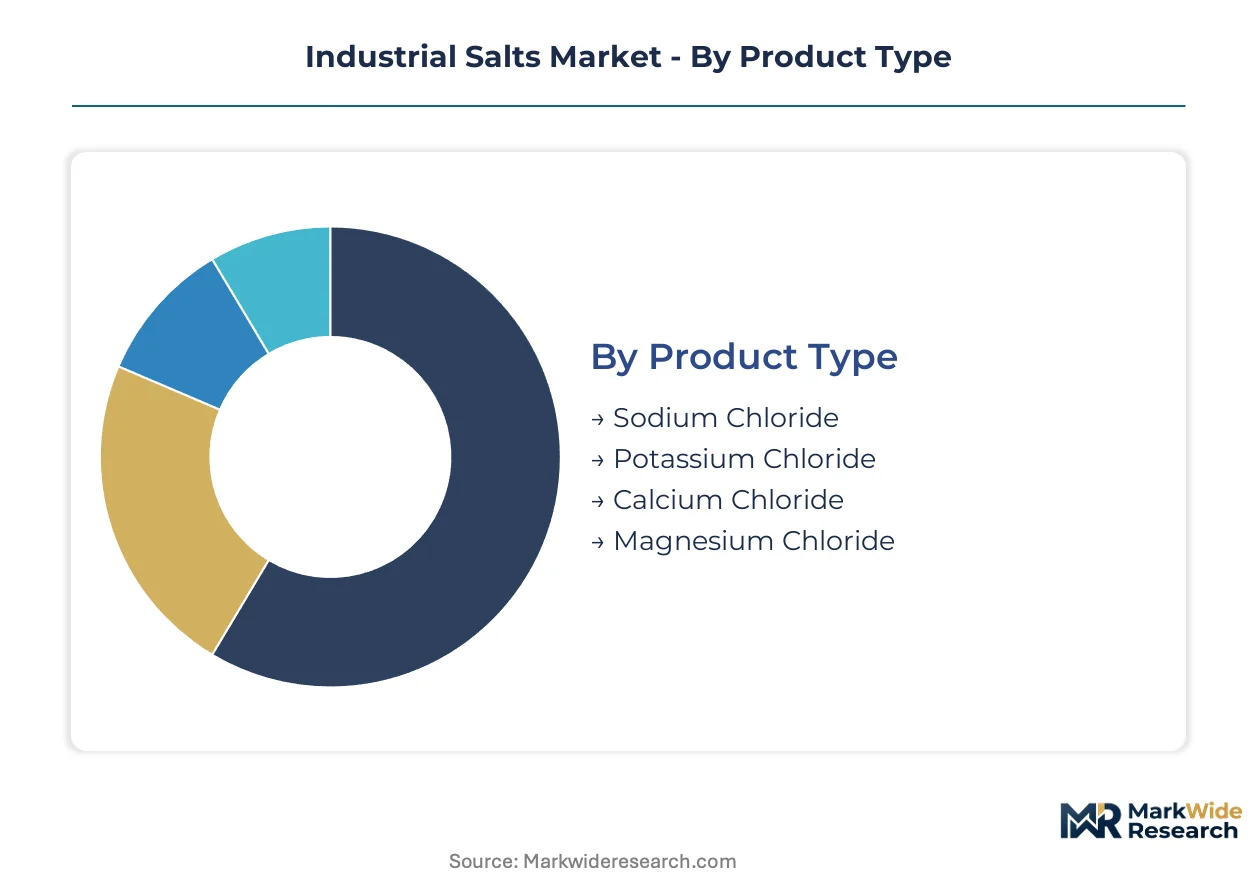
Industrial salt procurement varies sharply across purity grades, packaging formats, and delivery cadences. Buyers in chlor-alkali manufacturing demand continuous bulk supply with certified brine provenance, while road maintenance authorities prioritize seasonal availability and moisture-resistant packaging. Understanding these segment boundaries clarifies where margin concentrates and which specifications command price premiums.
Product Type:
Customization intensity spans from commodity sodium chloride with minimal specification variance to pharmaceutical-grade potassium chloride requiring batch-level documentation.
- Sodium Chloride:Technical-grade material exceeding 99% NaCl content serves as the irreplaceable feedstock for caustic soda and chlorine production. Demand concentrates in the United States and Germany where chlor-alkali capacity expansion is absorbing volume under long-term contracts with embedded natural gas price adjustments.
- Calcium Chloride:Hygroscopic flakes and pellets deliver effective deicing performance below minus fifteen degrees Celsius where magnesium chloride fails. Northern European road maintenance authorities in Norway and Sweden are expanding offtake as winter temperature volatility intensifies.
- Potassium Chloride:Agricultural fertilizer applications dominate volume, with specialty grades entering pharmaceutical and food processing supply chains under FSSC 22000 certification protocols.
- Magnesium Chloride:Dust suppression and soil stabilization applications absorb bulk shipments across mining operations in Australia and construction sites in the southwestern United States.
Leading the category by volume: Sodium Chloride. Expanding most quickly: Calcium Chloride.
Application:
Margin structure inverts across this category, with water treatment utilities paying certification premiums while agricultural buyers negotiate on delivered cost per ton.
- Water Treatment:Reverse osmosis pretreatment and membrane preservation protocols require pharmaceutical-grade sodium chloride with documented upstream brine provenance. Municipal districts in California and Texas are scaling procurement under EPA Clean Water Act discharge compliance timelines.
- Chemical Manufacturing:Chlor-alkali producers consume the largest single application volume, with membrane electrodialysis reversal systems reducing lime-soda softening chemical consumption at Gulf Coast facilities.
- Deicing:Seasonal demand spikes concentrate procurement authority with state transportation departments in Minnesota, Michigan, and New York, where stockpile management determines contract awards.
- Agriculture:Potassium chloride fertilizer applications compete on nutrient content and bulk delivery economics, with Brazilian and Indian import demand shaping spot pricing.
Steepest expansion trajectory: Water Treatment. Largest absolute volume: Chemical Manufacturing.
End User:
Procurement sophistication separates this category, with oil and gas operators demanding just-in-time bulk delivery while food processors enforce allergen-free handling protocols.
- Manufacturing:Chlor-alkali and synthetic rubber producers anchor volume through multi-year supply agreements with quality documentation requirements that filter subscale suppliers from tender processes.
- Food Processing:FDA and FSSAI compliance mandates separate technical-grade from food-grade specifications, with ISO 9001 certification functioning as a baseline qualifier rather than differentiator.
- Oil & Gas:Drilling fluid formulations and completion brines require consistent density specifications, with Permian Basin operators consolidating suppliers to reduce logistics complexity.
- Mining:Ore flotation and dust suppression applications prioritize delivered cost over purity, with Australian iron ore operations absorbing significant bulk volume.
Greatest contract stickiness: Food Processing. Fastest procurement digitization: Oil & Gas.
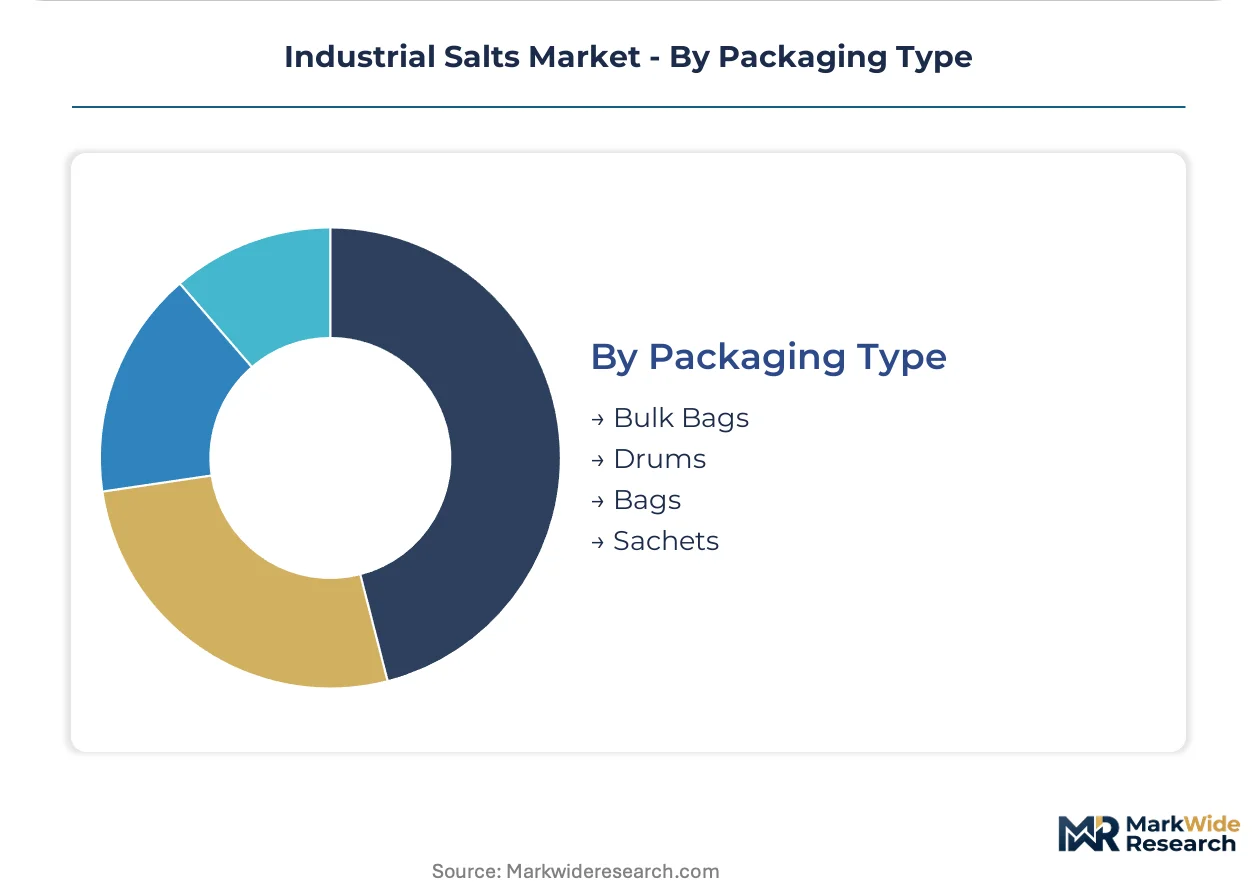
Packaging Type:
Logistics economics dominate this category, with bulk formats capturing scale efficiencies and smaller units serving dispersed consumption points.
- Bulk Bags:One-ton flexible intermediate bulk containers serve chlor-alkali producers and water treatment utilities with mechanized handling infrastructure, compressing per-unit logistics costs.
- Drums:Sealed steel and fiber containers protect hygroscopic calcium chloride from moisture absorption during extended storage, serving remote construction and mining sites.
- Bags:Twenty-five to fifty-kilogram woven polypropylene units bridge agricultural and small-scale industrial demand where bulk handling equipment is unavailable.
- Sachets:Pre-measured packets serve laboratory, pharmaceutical, and specialty food applications requiring precise dosing and contamination control.
Lowest cost per ton: Bulk Bags. Steepest growth in unit count: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces nearly one-third of global industrial salt volume yet consumes even more through chlor-alkali expansion. Germany and the United States balance substantial domestic output against chemical manufacturing demand. India and Brazil represent import-dependent growth poles where infrastructure investment is accelerating consumption.
United States
Chlor-alkali producers along the Gulf Coast consume pharmaceutical-grade sodium chloride under long-term contracts with natural gas price adjustments. EPA effluent limitations under the Clean Water Act force Louisiana and Texas salt-chemical clusters to install zero-liquid-discharge crystallizers. The Permian Basin anchors drilling brine demand, with operators consolidating suppliers to reduce logistics complexity across dispersed well pads.
Germany
K+S AG's underground mining complex in Lower Saxony supplies European deicing authorities while vacuum pan refiners serve BASF and other chemical manufacturers. EU REACH registration requirements for chloride discharges filter subscale producers from tender processes, concentrating volume with certified suppliers. The Rhine-Ruhr industrial corridor demands continuous brine quality documentation for membrane electrodialysis reversal systems.
China
China National Salt Industry Corporation dominates domestic supply as chlor-alkali capacity expansion in Shandong and Jiangsu provinces absorbs record volumes. MEE emission standards for salt-chemical clusters mandate closed-loop brine processing, elevating compliance costs for independent refiners. The Yangtze River Delta chemical parks are consolidating feedstock sourcing with vertically integrated suppliers capable of certifying upstream brine provenance.
India
Tata Chemicals Limited anchors domestic production from Gujarat solar evaporation ponds serving detergent and glass manufacturers. FSSAI compliance mandates separate technical-grade from food-grade specifications, with ISO 9001 certification functioning as a baseline qualifier for pharmaceutical contracts. The Mumbai-Pune industrial corridor imports premium-grade material for specialty chemical synthesis where domestic purity falls short.
Brazil
Potassium chloride fertilizer applications dominate import demand from Canadian and Israeli suppliers, with spot pricing shaped by Brazilian and Indian agricultural cycles. ANVISA registration requirements for pharmaceutical-grade material create compliance barriers for commodity traders. The São Paulo state chemical cluster consumes technical-grade sodium chloride for chlor-alkali production serving Latin American packaging and automotive supply chains.
Industrial Salts Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a tiered structure where vertical integration determines margin capture. Underground mining and solar evaporation operations require billion-dollar asset bases, while regional blenders and packaging specialists operate with minimal fixed capital. Three archetypes dominate: integrated miners with captive chemical customers, solar evaporation specialists with seasonal harvest cycles, and commodity traders arbitraging purity-grade spreads. Capacity consolidation and certification investments represent the dominant competitive moves, as subscale producers lose tender access under tightening discharge regulations.
Among North American integrated producers, Cargill Inc. and Compass Minerals International Inc exemplify the vertically integrated archetype, combining extraction assets with terminal networks controlling last-mile delivery economics. K+S AG occupies a parallel position in Europe, anchoring continental deicing supply through German underground mining while serving chlor-alkali feedstock demand. These three companies represent the scale-driven tier where multi-year supply agreements with embedded price-adjustment clauses are displacing spot market transactions for premium-grade material.
| Leading Market Players |
|---|
| Cargill Inc. |
| Compass Minerals International Inc |
| INEOS Group Ltd |
| K+S AG |
| Tata Chemicals Limited |
| China National Salt Industry Corporation |
| Nouryon Chemicals B.V. |
| Rio Tinto PLC |
| Mitsui & Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive brine sourcing across German underground mining complexes and Utah solar evaporation ponds anchors both supply security and pricing power for integrated producers serving chlor-alkali customers under long-term offtake agreements. This upstream control insulates contract holders from spot volatility while forcing non-integrated distributors to absorb margin compression during energy price spikes.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade sodium chloride accelerates as EPA discharge mandates force municipal water utilities to consolidate procurement with certified suppliers capable of continuous brine quality documentation. Contract-based long-term offtake agreements indexed to natural gas and transportation benchmarks dominate premium-grade transactions, while spot markets compress to lower-purity industrial grades. Price differentiation rests on FSSC 22000 certification status and documented upstream brine provenance. Road maintenance authorities exhibit highest price sensitivity due to seasonal demand volatility, whereas chlor-alkali producers accept premium pricing for supply continuity guarantees.
Supply Chain Analysis
Direct-to-utility digital platforms in Scandinavia and bulk terminal networks across North America handle divergent buyer archetypes with distinct logistics requirements. Supply concentrates in the United States, Germany, and China where chlor-alkali feedstock demand absorbs volume. Raw material dependencies center on natural gas for vacuum pan refining, solar irradiance for evaporation yields, and limestone for chemical purification. Single-source vulnerability persists where K+S AG anchors European deicing supply from its Lower Saxony mining complex. Distribution runs through integrated producer terminal networks, regional blenders, and emerging algorithmic ordering platforms bypassing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial salt procurement functions as a cost-of-compliance story where EPA effluent limitations and EU REACH registration requirements erect barrier-to-entry moats favoring certified producers with documented quality systems.
For Market Incumbents: Acquire brine recovery technology integrators and purification equipment specialists to fortify closed-loop processing capabilities as China's MEE emission standards tighten. Consolidate feedstock sourcing relationships with vertically integrated suppliers capable of certifying upstream brine provenance, defending against subscale competitors filtered from tender processes by ISO 9001 baseline requirements. For New Entrants and Emerging Players: Municipal water treatment utilities in the United States represent the most penetrable buyer segment as EPA Clean Water Act timelines force procurement consolidation with certified suppliers. Target membrane-based desalination districts in California and Texas with pharmaceutical-grade sodium chloride offerings supported by batch-level documentation protocols and direct-to-utility digital platform partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated chemical conglomerates seeking captive salt supply for chlor-alkali expansion. Long-term viability favors producers with solar evaporation assets in low-labor-cost geographies and established FSSC 22000 certification infrastructure. Monitor brine disposal regulation evolution and carbon-intensity disclosure requirements as inflection indicators determining facility permitting and offtake agreement renewal rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Recovery Systems | Closed-loop processing satisfies China's MEE emission standards while reducing per-ton chemical consumption at Gulf Coast chlor-alkali facilities. |
| Long-term Supply Agreement with Embedded Price Adjustments | Natural gas and transportation benchmarks lock in margin visibility for vacuum pan refiners facing feedstock volatility in Germany and the Netherlands. |
| Pharmaceutical-Grade Certification Investment | FSSC 22000 and ISO 9001 qualifications widen the compliance gap between commodity and specialty producers in municipal water treatment procurement. |
| Direct-to-Utility Digital Platform Launch | Algorithmic salt ordering systems in Scandinavia compress lead times and capture distributor margin previously embedded in traditional supply chains. |
| Joint Venture for Solar Evaporation Capacity Expansion | Utah and Ontario pond network partnerships diversify harvest yield exposure against precipitation anomalies and drought cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with chlor-alkali plant managers, municipal water procurement leads, road maintenance authority stockpile directors, and solar evaporation facility operators. SEC 10-K disclosures from integrated producers, EPA effluent limitation databases, EU REACH registration records, and China MEE emission standard filings provided volume and pricing benchmarks. Bottom-up facility capacity assessments triangulated against top-down chemical manufacturing demand models to reconcile supply-demand balances.
Granularity-level modeling deployed product type, application, and packaging format dimensions at the country level across the analysis window, with purity grade and certification status tracked as cross-cutting attributes. CAGRs derived from segment-specific volume trajectories weighted by natural gas price elasticity and seasonal deicing demand coefficients. Forecast inputs incorporated membrane electrodialysis reversal adoption curves and zero-liquid-discharge crystallizer installation timelines at Louisiana and Texas salt-chemical clusters.
Caveats apply where regulatory enforcement intensity, energy price volatility, or precipitation anomaly frequency could materially shift the outlook for solar evaporation yields and vacuum pan refining economics. Forecasts reflect assumptions regarding chlor-alkali capacity expansion continuity and municipal infrastructure investment durability. Periodic stress-testing of base assumptions against brine disposal regulation evolution and carbon-intensity disclosure trajectory is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Limestone Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Caustic Calcined Magnesite Market