
 Feldspar Mining Market | 2026-2036
Feldspar Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Feldspar Mining Market Insights
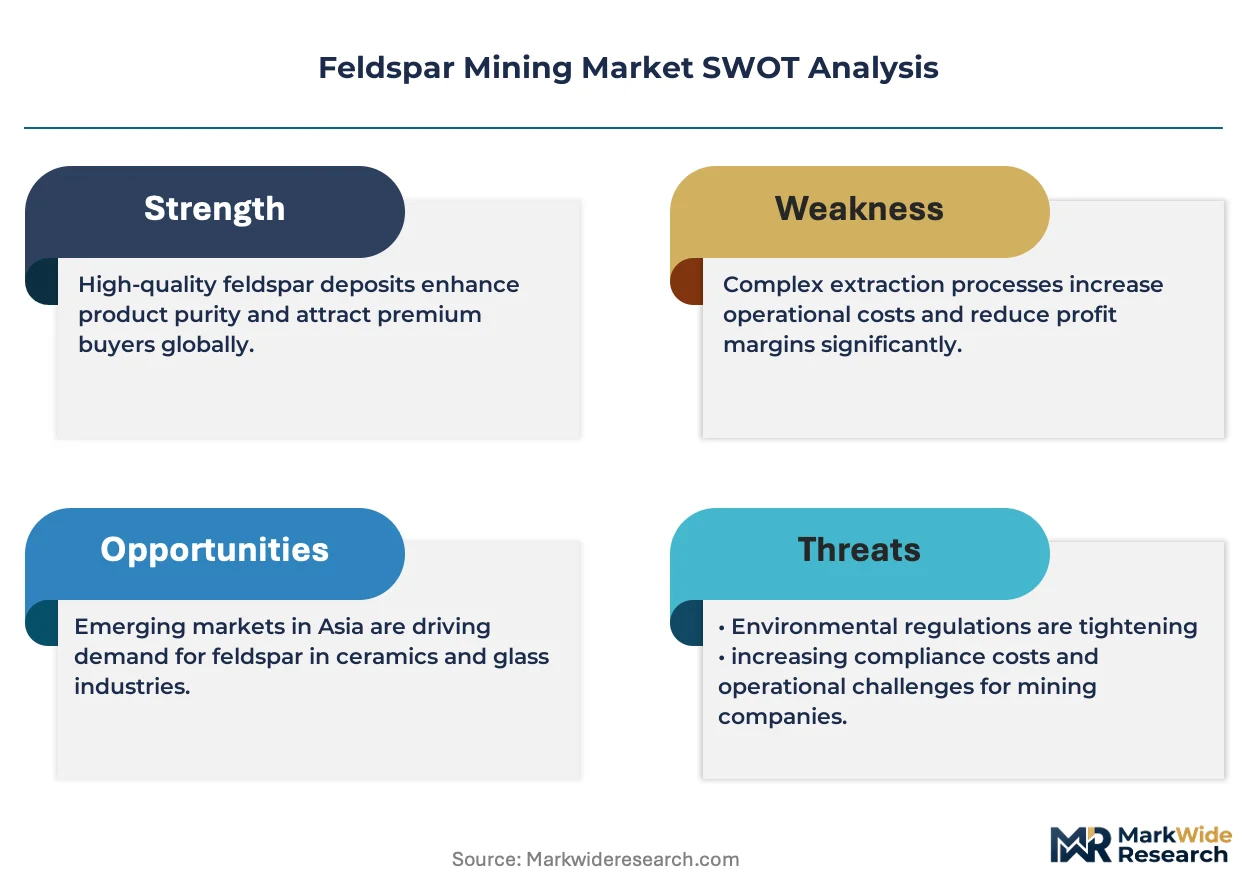
A capital-intensity divergence between integrated multinationals and regional quarry operators is collapsing as automated sorting and dry beneficiation spread through the industry. Imerys leverages captive reserves across multiple continents to sustain long-term supply contracts with float-glass manufacturers. Sibelco anchors its position through deep vertical integration into refined feldspar grades for high-performance ceramics. Quarzwerke GmbH differentiates via specialized wet-processing capabilities that command premium pricing in European coatings markets.
Feldspar comprises a group of aluminum silicate minerals—primarily orthoclase, albite, and anorthite—with K2O and Na2O fluxing oxides that lower glass and ceramic firing temperatures. Open-pit extraction dominates commercial supply due to favorable stripping ratios in pegmatite and granite-hosted deposits, though underground methods persist where overburden depth or environmental constraints limit surface disturbance. Glass manufacturing claims the largest application share by volume, driven by container and flat-glass furnace demand for alkali flux, while ceramics production retains tighter margin pools through body- and glaze-grade feldspar specifications. Fillers represent a faster-growing application segment as engineered plastics and rubber compounding seek functional mineral extenders with controlled particle size distribution.
OSHA enforces permissible exposure limits for respirable crystalline silica in US mining operations, compelling investment in dust suppression and enclosed processing systems. REACH registration requirements in Europe constrain import pathways for unrefined feldspar concentrates, favoring locally processed material with full substance dossiers. India's BIS certification mandates chemical consistency thresholds for feldspar sold into domestic ceramics and glass sectors. Stakeholders must monitor evolving tailings management standards and carbon accounting pressures that could reshape competitive economics between wet and dry processing routes.
Market Dynamics
Automated optical sorting is compressing processing costs for mid-tier quarries while OSHA silica enforcement reshapes capital allocation across North American operations. This dual pressure is redrawing competitive boundaries between integrated processors and regional suppliers.
Growth Catalysts
- Container glass furnace demand:Float-glass manufacturers in India and Turkey are locking in long-term alkali flux supply contracts. This procurement pattern secures volume pipelines for pegmatite deposit operators.
- REACH substance dossier requirements:European ceramics producers now demand fully registered refined grades. Local processors with complete ECHA documentation capture import substitution premiums.
- Dry beneficiation technology:Sensor-based ore sorting cuts water consumption by half in arid mining jurisdictions. Australian and Chilean operators deploy these systems to reduce tailings liability exposure.
Market Restraints
- Energy cost volatility:Thermal drying and grinding operations consume heavy fuel oil and electricity. Price spikes in European natural gas markets squeeze margin pools for wet-processing specialists.
- Deposit concentration in Turkey:Aegean region quarries supply two-thirds of export-grade ceramics feldspar. Any geopolitical friction or port congestion ripples through European glaze-grade supply chains.
- Substitute flux minerals:Nepheline syenite and lithium-bearing spodumene compete in specialty glass formulations. High-purity quartz sands displace feldspar in some container glass recipes.
Strategic Opportunities
- Engineered plastics compounding:Controlled particle-size feldspar fillers enhance thermoplastic stiffness and dimensional stability. Automotive underhood applications represent an untapped specification tier.
- Brazilian ceramics export growth:Domestic tile manufacturers scale output for Latin American construction markets. Local feldspar producers can displace Turkish imports through freight cost advantages.
- EU Green Deal carbon border adjustments:Low-carbon dry processing routes gain compliance premiums against wet-processed imports. Early adopters secure preferred supplier status with sustainability-mandated buyers.
Industry Challenges
- Process metallurgist scarcity:Automated plant operation demands hybrid skill sets combining mineralogy and data analytics. Training pipelines lag deployment timelines for sensor-based sorting installations.
- BIS certification timelines:Indian ceramics-grade feldspar requires chemical consistency testing that stretches six to nine months. Exporters face working capital strain during qualification periods.
- Legacy wet-plant retrofit complexity:Converting slurry-based circuits to dry beneficiation requires staged shutdowns and conveyor reconfiguration. Operational continuity risks deter mid-cap operators from modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feldspar Mining Market |
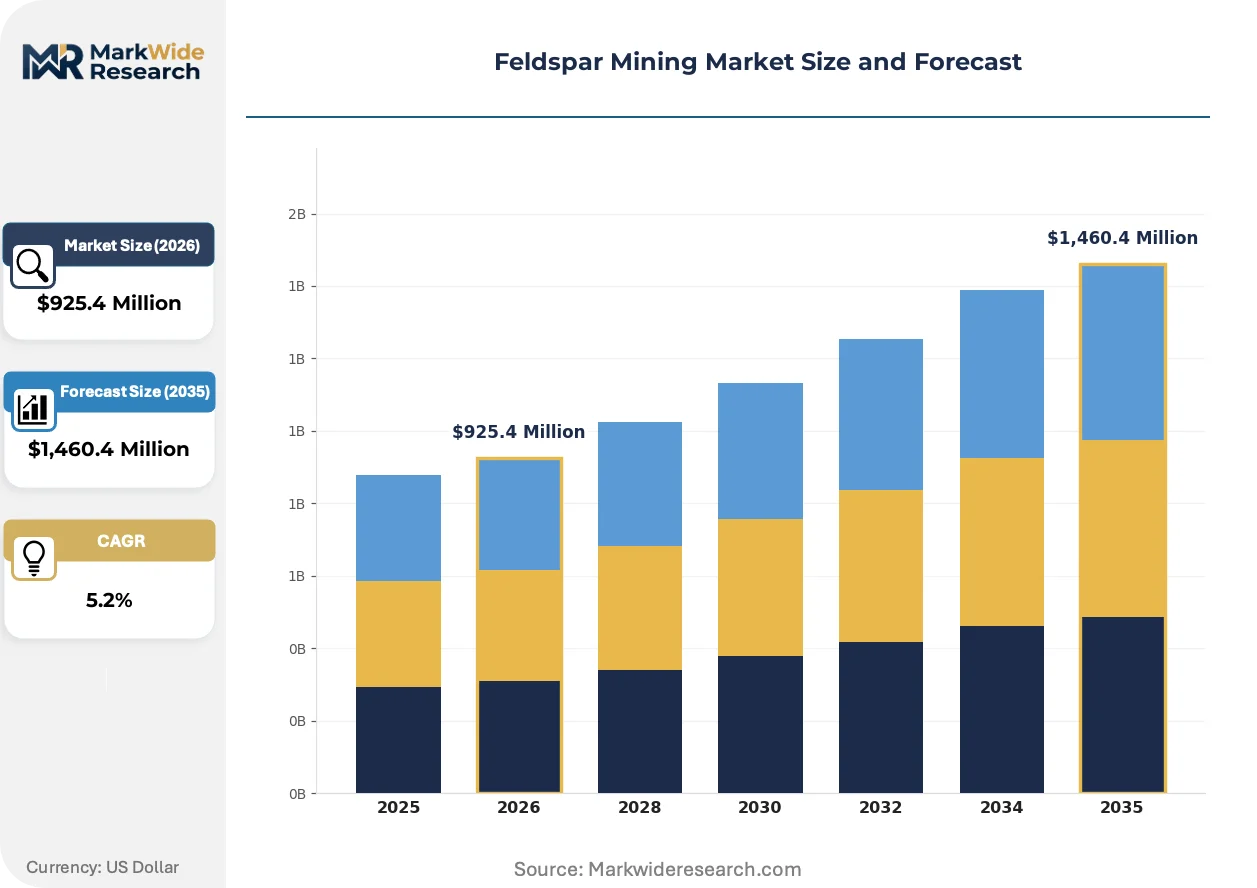
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,460.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mining Method: Open Pit, Underground, Placer, Hydraulic Application: Glass Manufacturing, Ceramics Production, Fillers, Paints Coatings, Rubber Compounding Deposit Type: Vein, Pegmatite, Alluvial, Hypabyssal End User Industry: Construction Materials, Electronics Components, Plastics Fabrication, Agriculture Minerals |
| Companies Covered | Imerys, Sibelco, The Quartz Corporation, Quarzwerke GmbH, Eczacibasi Esan, U.S. Silica Company, LB Minerals, Adolf Gottfried Tonwerke GmbH, I-Minerals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feldspar Mining Market Trends and Innovations
Digital process control and sustainability-linked procurement are rewriting operational benchmarks across extraction and refining stages. These shifts favor capital-rich operators capable of absorbing compliance and automation investments.
Sensor-based ore sorting combined with machine-vision quality control is supplanting manual hand-cobbing and dense-media separation in pegmatite processing. Major float-glass manufacturers now specify laser-diffraction particle consistency in supply contracts. This technology compression is eroding the cost advantage of labor-intensive operations in lower-wage jurisdictions.
OSHA's respirable crystalline silica enforcement has triggered enclosure mandates for crushing and grinding circuits. US operators retrofit baghouse systems and negative-pressure control rooms to meet permissible exposure limits. Smaller Appalachian quarries face disproportionate compliance burdens relative to integrated multinationals with centralized engineering resources.
Container glass producers now unbundle technical service from material supply, purchasing furnace optimization consulting separately from alkali flux tonnage. This purchasing pattern shifts margin capture toward processors with dedicated refractory and melting expertise. Indian and Southeast Asian float-glass lines lead this unbundling, driven by aggressive capacity expansion timelines and compressed supplier qualification cycles.
Feldspar Mining Market Segmentation
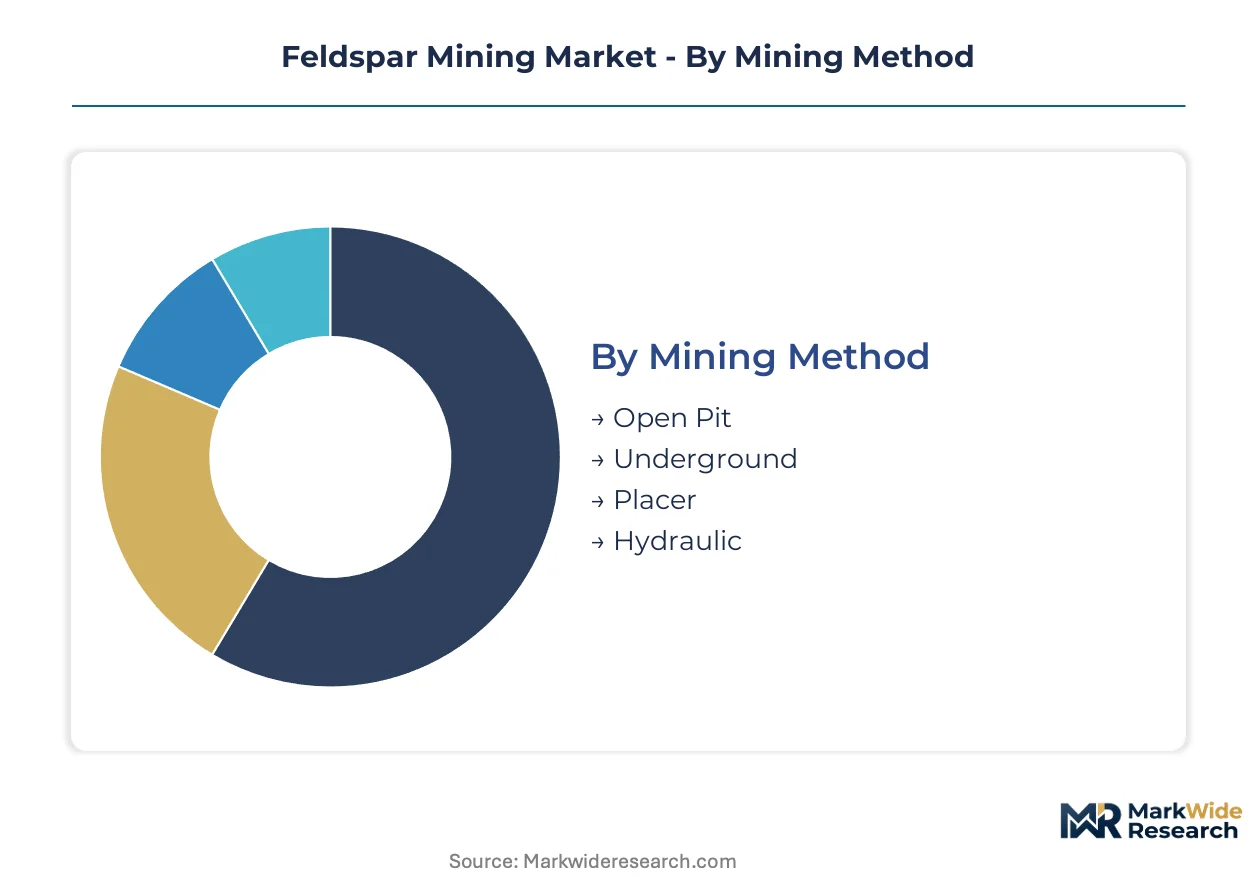
Segmentation in feldspar mining reveals where substitute minerals exert the greatest pressure and where captive geology creates defensible supply positions. Understanding these fracture lines guides capital allocation between extraction methods and downstream refining investments.
Mining Method:
Substitution pressure from nepheline syenite and synthetic fluxes hits hardest where processing costs are highest, making method selection a margin-defense decision.
- Open Pit:Strip mining of shallow pegmatite and granite-hosted deposits dominates commercial supply. Favorable stripping ratios in Aegean and Rajasthan deposits sustain cost leadership against underground alternatives. Float-glass manufacturers in Turkey and India lock in long-term supply contracts tied to open-pit output.
- Underground:Room-and-pillar extraction persists where overburden depth or environmental constraints limit surface disturbance. Appalachian operators in the US deploy this method to satisfy OSHA silica exposure mandates through enclosed processing circuits. Capital intensity runs higher, restricting participation to integrated multinationals.
- Placer:Alluvial feldspar recovery from sedimentary deposits supplies niche ceramics markets in Brazil and Argentina.
- Hydraulic:High-pressure water jets disaggregate soft host rock in limited European applications, constrained by water use permitting.
Open Pit anchors the volume base while Placer gains share at the steepest rate through Latin American construction demand.
Application:
Cost tier stratification separates commodity flux from specification-grade material, with processing intensity determining margin capture.
- Glass Manufacturing:Alkali flux demand from container and flat-glass furnaces consumes the largest volume share. Soda-lime formulations require consistent K2O and Na2O content to lower melting temperatures. Indian and Turkish float-glass lines specify laser-diffraction particle consistency in procurement contracts.
- Ceramics Production:Body- and glaze-grade specifications command tighter margins through controlled iron and titanium content. REACH-registered refined grades capture import substitution premiums in European markets. Sibelco and Imerys anchor supply through captive reserves and wet-processing capabilities.
- Fillers:Engineered plastics and rubber compounding drive expansion for functional mineral extenders with narrow particle size distribution.
- Paints Coatings:Wet-ground feldspar serves as a functional extender in architectural and industrial formulations.
- Rubber Compounding:Surface-treated grades enhance tear resistance and processing characteristics in tire manufacturing.
Glass Manufacturing retains the volume anchor while Fillers climbs the fastest through automotive underhood thermoplastic specifications.
Deposit Type:
Geographic concentration of ore quality shapes competitive economics, with certain formations enabling premium pricing through inherent purity.
- Pegmatite:Coarse-grained igneous formations yield the highest-grade ceramics feldspar with minimal iron contamination. Aegean region quarries supply two-thirds of export-grade material to European glaze manufacturers. Automated optical sorting now processes lower-grade pegmatite ore that previously required hand cobbing.
- Vein:Narrow hydrothermal deposits provide localized supply for regional glassworks in Germany and the Czech Republic.
- Alluvial:Sedimentary deposits in Brazil and Argentina feed domestic ceramics export growth.
- Hypabyssal:Shallow intrusive formations in India supply BIS-certified material for domestic container glass and tile production.
Pegmatite holds the volume base while Alluvial expands most quickly through Brazilian freight cost advantages against Turkish imports.
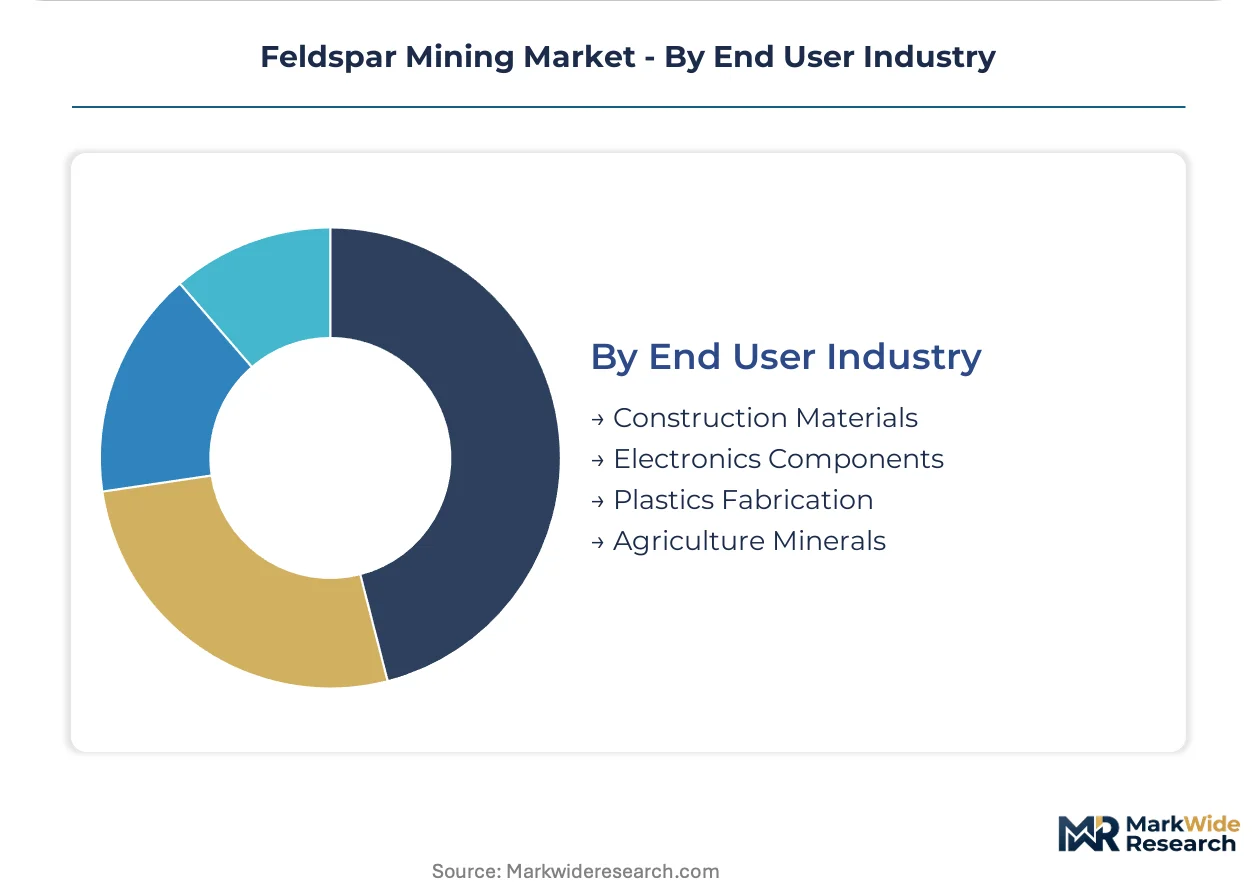
End User Industry:
Customer type segmentation exposes where technical service unbundling from material supply shifts margin capture toward processors with dedicated refractory expertise.
- Construction Materials:Tile, sanitaryware, and flat-glass demand concentrates procurement volumes across Asia-Pacific and Middle Eastern markets. Float-glass manufacturers now purchase furnace optimization consulting separately from alkali flux tonnage.
- Plastics Fabrication:Engineered thermoplastics for automotive and appliance applications specify controlled particle-size distribution for stiffness and dimensional stability.
- Electronics Components:High-purity feldspar serves in ceramic substrates and insulators with low alkali ion mobility requirements.
- Agriculture Minerals:Soil amendment applications utilize lower-grade material with minimal processing.
Construction Materials anchors the volume base while Plastics Fabrication gains share at the steepest rate through specification-grade filler demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass manufacturers in India and Turkey consume feldspar primarily as alkali flux for container and flat-glass furnaces, while European ceramics producers prioritize refined grades with full REACH dossiers for glaze applications. This consumption-mix differential shapes procurement patterns and processing investments across major mining jurisdictions.
Turkey
Aegean region pegmatite quarries supply two-thirds of export-grade ceramics feldspar to European glaze manufacturers. The country's mining licensing framework prioritizes value-added processing over raw concentrate exports. Izmir and Çanakkale provinces concentrate automated optical sorting installations that displace labor-intensive hand cobbing.
India
Container glass and tile production in Gujarat and Rajasthan drives sustained procurement of BIS-certified feldspar with consistent K2O and Na2O thresholds. The Bureau of Indian Standards mandates six-to-nine-month chemical consistency testing for domestic ceramics-grade supply. Jaipur and Udaipur districts anchor open-pit extraction with favorable stripping ratios in hypabyssal formations.
United States
Appalachian underground operations serve regional container glassworks through enclosed processing circuits that satisfy OSHA respirable crystalline silica exposure mandates. The Occupational Safety and Health Administration enforces permissible exposure limits that compel baghouse retrofits and negative-pressure control rooms. North Carolina and Virginia deposits concentrate room-and-pillar extraction where overburden depth limits surface disturbance.
Brazil
Domestic tile manufacturers in São Paulo and Minas Gerais states scale output for Latin American construction markets, creating freight cost advantages against Turkish imports. Alluvial sedimentary deposits in the country's southeast supply niche ceramics markets with minimal iron contamination. Local processors capture share from Aegean exporters through shorter supply chains to regional glaze manufacturers.
Germany
Wet-processing specialists in Bavaria and Saxony command premium pricing in European coatings markets through controlled particle size distribution. REACH registration requirements constrain import pathways for unrefined concentrates, favoring locally processed material with full ECHA substance dossiers. Quarzwerke GmbH anchors supply through specialized wet-grinding capabilities for architectural and industrial paint formulations.
Feldspar Mining Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the feldspar mining sector, with captive reserves and processing capabilities determining contract access. The structure compresses around automated sorting technology that collapses cost differentials between multinationals and mid-tier quarries. Two archetypes dominate: reserve-integrated processors with multi-continent asset bases, and wet-processing specialists with premium-grade capabilities. Competitive moves center on dry beneficiation technology licensing and long-term alkali flux supply contracts with float-glass manufacturers.
Within the integrated tier, Imerys and Sibelco exemplify reserve-backed supply positions across multiple continents, securing volume pipelines through captive geology. Quarzwerke GmbH occupies a specialist position in wet-processed grades for coatings applications. These three anchors demonstrate how processing intensity and regulatory compliance documentation separate premium-tier positioning from commodity flux supply.
| Leading Market Players |
|---|
| Imerys |
| Sibelco |
| The Quartz Corporation |
| Quarzwerke GmbH |
| Eczacibasi Esan |
| U.S. Silica Company |
| LB Minerals |
| Adolf Gottfried Tonwerke GmbH |
| I-Minerals Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles at Aegean port terminals concentrate pricing power with Turkish pegmatite operators who dictate glaze-grade feldspar premiums. This lead-time compression amplifies margin capture for integrated processors while regional quarries absorb spot-market volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between Turkish exporters and European ceramics manufacturers, locking in volume commitments that insulate against energy cost spikes. Pricing stratifies across REACH-registered refined grades, BIS-certified domestic supply, and unregistered raw concentrates. Cost compression in wet-processed tiers intensifies because natural gas price volatility squeezes European grinding operations. Container glass manufacturers exhibit lowest price sensitivity due to furnace optimization unbundling, while mid-tier tile producers in Latin America face acute margin pressure.
Supply Chain Analysis
Aegean port congestion and customs processing delays at Izmir constitute the primary logistics chokepoint for European glaze-grade supply. Production gravity centers on Turkey, India, and Brazil, with Aegean quarries feeding two-thirds of export-grade ceramics demand. Extraction draws from diesel fuel, ammonium nitrate explosives, and steel grinding media as core inputs. Single-source vulnerability runs through Turkish pegmatite concentration, where geopolitical friction or labor disruptions ripple immediately through European supply chains. Distribution runs through bulk vessel chartering to Mediterranean ports, with regional truck haulage completing last-mile delivery to ceramics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated optical sorting and dry beneficiation constitute a technological inflection that collapses historical cost advantages between integrated multinationals and mid-tier quarries, accelerating competitive disruption across extraction economics.
For Market Incumbents: Consolidate reserve positions through targeted acquisition of Rajasthan and Aegean pegmatite deposits before sensor-based sorting democratizes processing capabilities. Lock in ten-year alkali flux supply contracts with Indian and Turkish float-glass manufacturers to defend volume pipelines against nepheline syenite substitution. Prioritize REACH dossier completion for refined grades to capture European import substitution premiums as ECHA enforcement tightens. For New Entrants and Emerging Players: Technical service unbundling from material supply represents the most penetrable white-space, where incumbents under-serve furnace optimization consulting needs of Southeast Asian glass producers. Target Brazilian alluvial deposit processing for Latin American ceramics export growth, leveraging freight cost advantages against Turkish imports. Pursue joint-venture structures with local processors to bypass six-to-nine-month BIS certification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a processing-technology play because automated sorting and carbon-compliant dry beneficiation will separate winners from legacy wet-plant operators across the analysis window. Prioritize mid-cap quarries with automated optical sorting installations and captive pegmatite reserves in low-jurisdiction-risk geographies. Watch OSHA silica enforcement intensity and EU Green Deal carbon border adjustment implementation as inflection indicators for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Optical Sorting Deployment | Sensor-based ore sorting halves water consumption and collapses labor cost differentials for mid-tier operators. |
| REACH Dossier Completion | Full ECHA substance registration captures import substitution premiums in European ceramics markets. |
| Dry Beneficiation Retrofit | Conversion from wet-processing circuits reduces carbon intensity and secures EU Green Deal compliance premiums. |
| Long-term Alkali Flux Contracting | Ten-year offtake agreements with Indian and Turkish float-glass manufacturers lock in volume pipelines. |
| Technical Service Unbundling | Furnace optimization consulting sold separately from material supply shifts margin capture toward refractory expertise. |
Research Methodology
Initial hypotheses were tested against primary input from quarry operations managers, ceramics plant procurement directors, float-glass furnace engineers, and mineral processing equipment specialists and refined through secondary validation. Trade data from Turkish Statistical Institute export records, Indian Bureau of Mines production statistics, ECHA registration databases, and SEC filings of listed mining companies anchored supply-side quantification. Bottom-up reserve estimates triangulated against top-down consumption models derived from glass and ceramics production statistics.
Variance decomposition across mining method, application grade, deposit type, and end-user industry segments structured the analytical framework. CAGRs were derived from regression-based trending of historical production and consumption patterns across the projection horizon. Modeled inputs included float-glass furnace expansion timelines, BIS certification completion rates, and OSHA silica enforcement expenditure patterns.
Material uncertainties — geopolitical friction in Aegean supply corridors, energy price volatility affecting wet-processing economics, and substitute mineral penetration rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and regulatory implementation timelines. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and automated sorting deployment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Talc Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Slate Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
India Feed Minerals Market