
 North America Laser Tattoo and Striae Removal Market | 2026-2036
North America Laser Tattoo and Striae Removal Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laser Tattoo and Striae Removal Market Intelligence
Modular service bundling is pivoting how cosmetic clinics package tattoo and striae removal into multi-session subscription plans. Alma Lasers leverages its installed base of multi-platform systems to anchor recurring consumables revenue across North American dermatology practices. Sciton differentiates through physician training ecosystems that sustain premium pricing for its fractional laser portfolio.
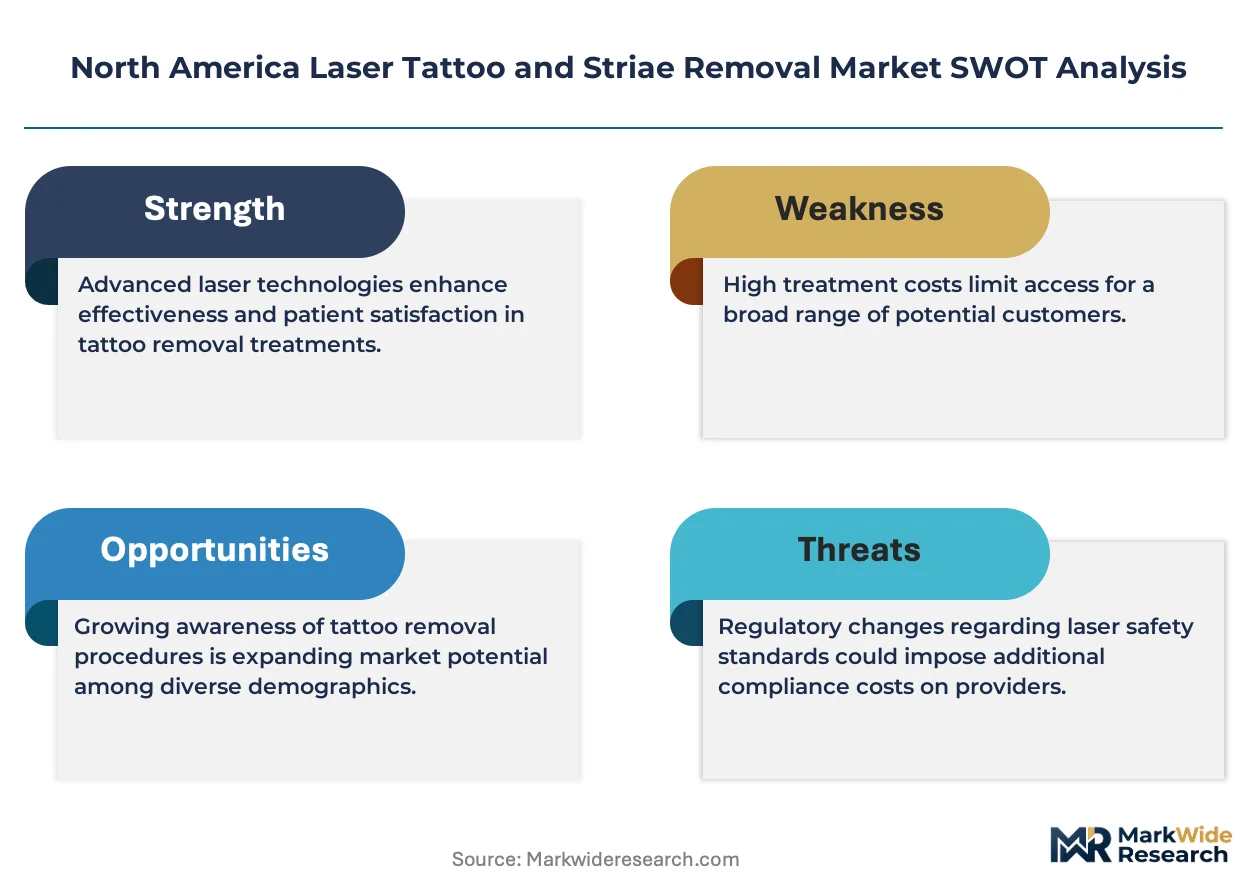
North America laser tattoo and striae removal encompasses energy-based devices that deliver concentrated light pulses at specific wavelengths—typically 532 nm to 1064 nm for pigment targeting and 1540 nm to 1550 nm for collagen remodeling in striae—to fragment dermal ink particles or induce neocollagenesis without ablating the epidermis. Picosecond lasers dominate capital expenditure flows due to shorter pulse durations that reduce thermal diffusion and treatment sessions for recalcitrant tattoo pigments. Selective photothermolysis remains the foundational technology platform, though fractional laser configurations now capture expanding share in striae revision where controlled micro-injury patterns accelerate dermal remodeling.
FDA 510(k) clearances govern device commercialization in the United States, while Health Canada Medical Device Licensing establishes parallel requirements for Canadian market entry. State-level medical board regulations in California, Texas, and Florida determine whether non-physician operators may administer laser treatments, directly influencing clinic staffing models and device utilization rates. Stakeholders must monitor evolving scope-of-practice rulings and reimbursement positioning for striae as a cosmetic versus medically indicated procedure.
Market Dynamics
Picosecond pulse technology is compressing treatment protocols and redrawing capital allocation across cosmetic dermatology practices, as shorter pulse durations fragment recalcitrant tattoo pigments with reduced thermal diffusion and session counts.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearances for new laser wavelengths reduce time-to-market for device manufacturers targeting tattoo pigment specificity.
- Cosmetic clinic consolidation:Multi-site dermatology groups in Los Angeles, New York, and Toronto are standardizing on picosecond platforms to capture recurring subscription revenue.
- Selective photothermolysis refinement:Advanced wavelength targeting at 532 nm, 755 nm, and 1064 nm expands treatable ink colors and skin type ranges.
Market Restraints
- Capital intensity barrier:Picosecond laser systems require $150,000-$300,000 upfront investment, constraining independent practice adoption.
- Supply concentration risk:Critical optical components and laser crystals concentrate among German and Japanese specialty manufacturers.
- Scope-of-practice fragmentation:State medical boards in California, Texas, and Florida impose divergent operator certification requirements, complicating multi-state clinic staffing.
Strategic Opportunities
- Canadian market underpenetration:Health Canada Medical Device Licensing creates parallel but less crowded pathways for wavelength innovations versus FDA-crowded US filings.
- Striae revision expansion:Fractional laser configurations at 1540 nm-1550 nm penetrate post-pregnancy and adolescent growth-mark demographics previously underserved by tattoo-focused marketing.
- Subscription bundling models:Multi-session payment plans for tattoo removal are migrating into striae treatment packages, locking patient lifetime value.
Industry Challenges
- Technician certification bottlenecks:State-level laser safety training requirements vary, creating compliance complexity for multi-jurisdiction operators.
- Legacy Q-switched system stranded asset risk:Practices face write-down pressure as picosecond platforms obsolete installed bases with inferior efficacy on resistant pigments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laser Tattoo and Striae Removal Market |
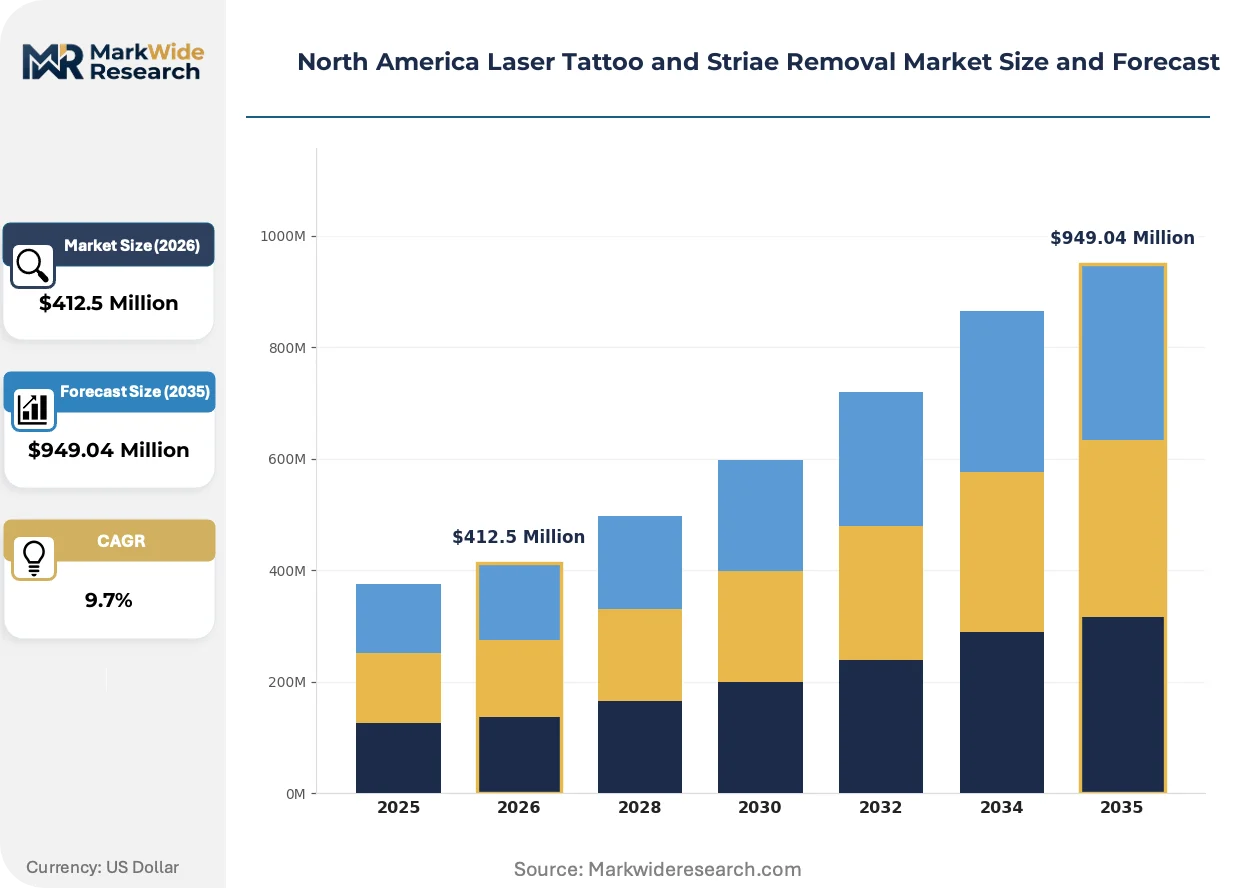
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Q-Switched Lasers, Picosecond Lasers, Erbium Lasers, CO2 Lasers Application: Tattoo Removal, Striae Removal, Pigmentation Treatment, Skin Resurfacing End User: Dermatology Clinics, Cosmetic Clinics, Hospitals, Beauty Salons Technology: Laser Ablation, Selective Photothermolysis, Fractional Laser, Non-Ablative Laser |
| Companies Covered | Schweiger Dermatology Group, Cynosure, Alma Lasers, Sciton, Lumenis, Cutera, Fotona, Lutronic, Removery, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laser Tattoo and Striae Removal Market Strategic Shifts & Innovations
Device architecture and service delivery models are converging around speed, specificity, and patient retention mechanics, with three forces now dominating competitive differentiation.
Picosecond-domain pulse generation is rewriting clinical throughput economics. Pulse durations below 500 picoseconds fragment ink particles through photomechanical rather than photothermal effects, enabling dermatology groups in Miami and Chicago to compress multi-year tattoo removal protocols into 4-6 session sequences. This compression is rewriting pricing power toward premium per-session rates while reducing total patient acquisition costs.
Health Canada Medical Device Licensing is tightening parallel with FDA 510(k) stringency for laser tattoo devices, requiring equivalent clinical evidence packages for wavelength safety and efficacy claims. Canadian manufacturers now face synchronized documentation burdens with US counterparts, compressing the historical regulatory arbitrage window. Ontario and Quebec device distributors are responding by consolidating regulatory affairs functions across both jurisdictions.
Subscription-based treatment packaging is displacing per-session fee structures across metropolitan cosmetic corridors. Los Angeles and Toronto clinics now bundle tattoo and striae removal into 12-24 month membership tiers with priority scheduling and touch-up inclusions. This shift concentrates patient lifetime value and reduces seasonal demand volatility previously endemic to elective aesthetic procedures.
North America Laser Tattoo and Striae Removal Market Segmentation
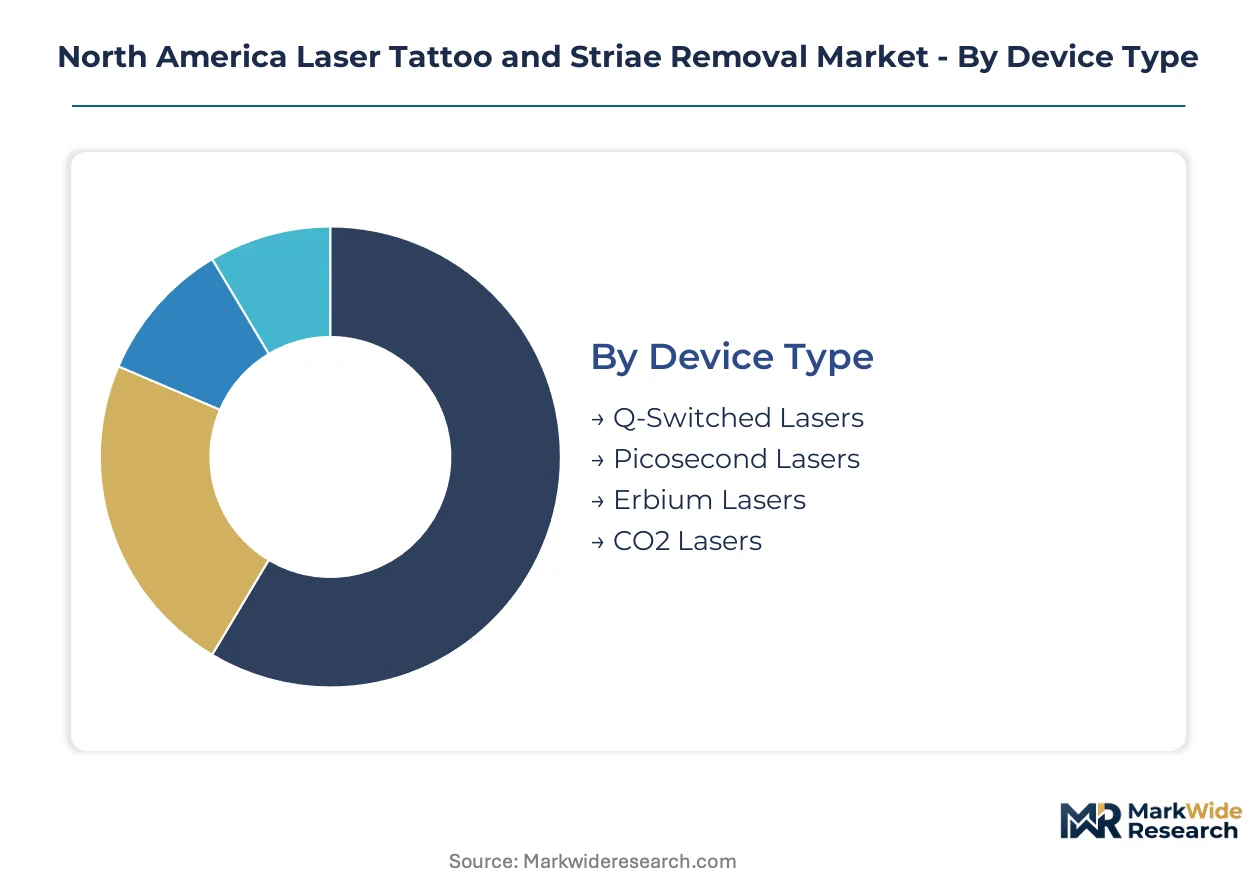
Segmentation in laser tattoo and striae removal reveals how capital flows fragment across standalone capital equipment versus embedded multi-platform systems. Understanding these splits clarifies where procurement budgets concentrate and which configurations command premium pricing power.
Device Type:
Standalone picosecond systems dominate capital-intensive deployments, while Q-switched platforms increasingly embed into modular dermatology workstations.
- Picosecond Lasers:Pulse durations below 500 picoseconds fragment ink through photomechanical effects rather than thermal diffusion. Demand concentrates in Los Angeles and New York multi-site dermatology groups seeking compressed treatment protocols for resistant pigments.
- Q-Switched Lasers:Nanosecond-domain systems remain prevalent in mid-tier cosmetic clinics where capital constraints limit picosecond adoption. Texas and Florida practices face stranded asset pressure as patient expectations shift toward faster clearance timelines.
- Erbium Lasers:2940 nm wavelength systems target striae revision through controlled epidermal ablation.
- CO2 Lasers:Ablative platforms serve deep resurfacing indications with extended recovery profiles.
Volume placements concentrate in Picosecond Lasers; the faster expansion belongs to Erbium Lasers.
Application:
Procedure bundling is reshaping how clinics position tattoo removal versus striae revision within unified service menus.
- Tattoo Removal:Multi-session pigment clearance protocols generate recurring revenue streams through membership packaging. Canadian metropolitan corridors in Toronto and Vancouver are standardizing subscription tiers for complete removal sequences.
- Striae Removal:Post-pregnancy and adolescent growth-mark demographics previously underserved by tattoo-focused marketing now drive fractional laser adoption. California and New York clinics bundle striae packages with body contouring services.
- Pigmentation Treatment:Solar lentigines and melasma protocols leverage selective photothermolysis at 532 nm and 755 nm.
- Skin Resurfacing:Ablative and non-ablative modalities address photodamage and textural irregularities.
Revenue concentration sits with Tattoo Removal; steepest expansion trajectory belongs to Striae Removal.
End User:
Staffing regulations and scope-of-practice rulings determine which settings can deploy which laser classes.
- Dermatology Clinics:Physician-supervised settings command premium pricing for complex cases requiring medical judgment. California medical board regulations restrict certain laser classes to physician operators only.
- Cosmetic Clinics:Non-physician operator permissions vary by state, with Texas and Florida permitting broader technician scope than California. These settings drive volume through aggressive membership pricing and marketing spend.
- Hospitals:Academic medical centers handle complicated cases with co-morbidities or post-surgical scarring.
- Beauty Salons:Lower-tier settings face regulatory pressure as state boards tighten laser safety certification requirements.
Capital deployment concentrates in Dermatology Clinics; patient volume expansion belongs to Cosmetic Clinics.
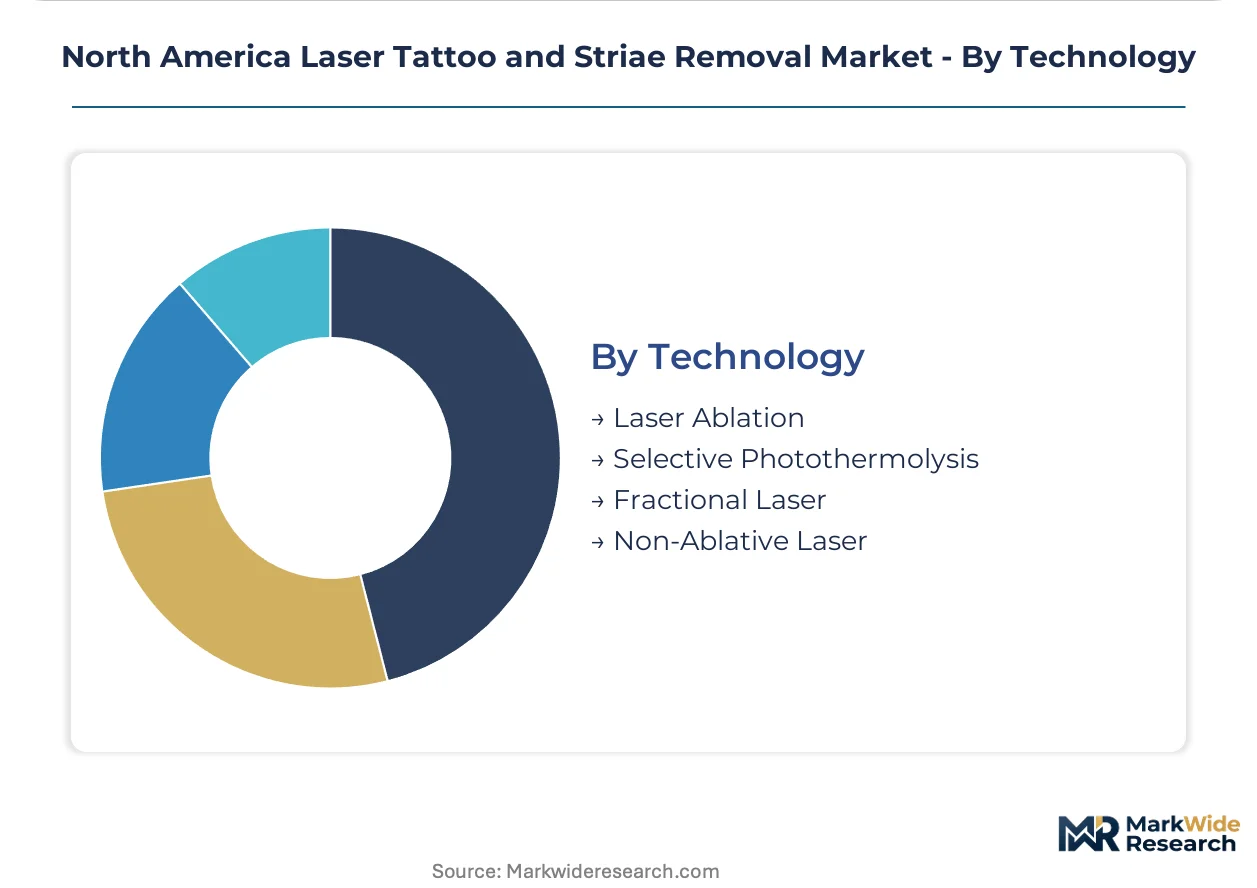
Technology:
Mechanism of action determines reimbursement positioning and regulatory pathway complexity.
- Selective Photothermolysis:Targeted chromophore absorption at specific wavelengths remains the foundational platform for pigment-specific treatments. FDA 510(k) clearances for new wavelengths continue streamlining under refined predicate device pathways.
- Fractional Laser:Controlled micro-injury patterns accelerate dermal remodeling in striae revision with reduced downtime versus ablative alternatives. Health Canada licensing is tightening equivalence requirements with FDA submissions.
- Laser Ablation:Full-thickness epidermal removal addresses severe photodamage and scarring.
- Non-Ablative Laser:Sub-epidermal heating protocols minimize recovery while requiring more sessions.
Installed base concentration sits with Selective Photothermolysis; technology transition momentum belongs to Fractional Laser.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in specialized optical component clusters across Germany and Japan, while consumption flows overwhelmingly into United States metropolitan corridors and Canadian urban centers. Mexico's emerging cosmetic clinic sector absorbs refurbished Q-switched systems as North American practices upgrade to picosecond platforms.
United States
Multi-site dermatology groups in Los Angeles and New York drive capital expenditure toward picosecond platforms with subscription-based patient retention models. FDA 510(k) clearance pathways govern wavelength innovations, compressing time-to-market for new device submissions. California medical board regulations restrict certain laser classes to physician operators only, creating staffing complexity for cosmetic clinic chains operating across state lines.
Canada
Health Canada Medical Device Licensing establishes parallel but historically less crowded pathways for wavelength innovations versus FDA-crowded US filings. Toronto and Vancouver metropolitan corridors standardize subscription tiers for complete tattoo removal sequences, locking patient lifetime value. Ontario and Quebec device distributors consolidate regulatory affairs functions across both jurisdictions as licensing stringency tightens.
Mexico
Mid-tier cosmetic clinics absorb refurbished Q-switched laser systems from United States upgrade cycles, extending equipment lifecycles in price-sensitive settings. The country's national medical device regulator oversees import licensing for aesthetic laser equipment, though enforcement varies by state jurisdiction. Mexico City and Monterrey urban corridors concentrate demand as medical tourism positioning strengthens for North American patients seeking cost-advantaged striae revision protocols.
North America Laser Tattoo and Striae Removal Market Key Industry Players
The competitive structure tilts toward diversified energy-based device manufacturers with established dermatology installed bases. Market concentration remains moderate, with tiered positioning separating premium picosecond platform specialists from legacy Q-switched providers and emerging fractional laser entrants. Three archetypes dominate: vertically integrated optical component fabricators, multi-platform aesthetic system conglomerates, and specialized tattoo removal clinic operators with captive device demand. Competitive moves center on strategic partnerships for wavelength innovation and portfolio diversification into adjacent skin resurfacing indications.
Among diversified aesthetic laser manufacturers, Cynosure, Alma Lasers, and Sciton occupy positions spanning picosecond, fractional, and multi-platform configurations. These entities represent the integrated-system archetype, anchoring recurring consumables revenue through installed base expansion across dermatology practices. Cutera and Lumenis exemplify scale-driven competitors with broad wavelength portfolios, while specialized clinic operators like Removery concentrate demand through direct ownership of treatment capacity rather than device manufacturing.
| Leading Market Players |
|---|
| Schweiger Dermatology Group |
| Cynosure |
| Alma Lasers |
| Sciton |
| Lumenis |
| Cutera |
| Fotona |
| Lutronic |
| Removery |
| Others |
Cost & Logistics Intelligence
Optical engineering talent concentration in Stuttgart and Osaka feeds labor-cost differentials that widen pricing-tier spreads between premium picosecond platforms and refurbished Q-switched alternatives. FDA 510(k) compliance burdens and Health Canada licensing fees compound these spreads, forcing mid-tier cosmetic clinics toward subscription financing or secondary equipment markets.
Pricing Analysis
Margin tightening in mid-tier cosmetic clinics reflects stranded asset pressure from picosecond platform obsolescence of legacy Q-switched systems. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised dermatology practices from technician-operated cosmetic clinics and refurbished equipment buyers. Price differentiation hinges on FDA clearance tier and bundled training certification. Cost-down pressure on standard-tier systems accelerates because Canadian distributors consolidate regulatory affairs across dual jurisdictions. Independent practices in Texas and Florida exhibit highest price sensitivity; multi-site dermatology groups in Los Angeles and New York demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in Canadian provincial procurement are reshaping sourcing for device distributors serving Ontario and Quebec hospital systems. Optical component fabrication concentrates in Germany and Japan; laser crystal supply draws from specialty manufacturers in these markets plus emerging capabilities in South Korea. Critical dependencies include neodymium-doped yttrium aluminum garnet crystals, electro-optical modulators, and precision optical coatings. Single-source vulnerability concentrates in picosecond pulse generation subsystems. Distribution runs through authorized dermatology equipment distributors with direct service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway stringency and Health Canada licensing convergence erect a cost-of-compliance barrier that protects cleared incumbents from fast-follower competition. This regulatory moat rewards early certification investment and punishes delayed market entry.
For Market Incumbents: Deepen backward integration into optical component supply through captive sourcing agreements with Stuttgart and Osaka engineering clusters. Defend installed base stickiness by embedding subscription telemetry that captures treatment protocol data, creating switching costs for cosmetic clinic customers facing picosecond platform upgrade decisions.
For New Entrants and Emerging Players: The price-point gap between premium picosecond systems and economy-tier refurbished Q-switched equipment offers white-space entry. Target Mexican cosmetic clinics absorbing US upgrade cast-offs with fractional laser configurations stripped of FDA-tier certification overhead. Pursue Health Canada-first regulatory strategy to establish clinical evidence packages before FDA submission.
For Investors and Strategic Acquirers: The window for entry favors diversified aesthetic laser manufacturers with multi-platform installed bases and recurring consumables revenue. Long-term viability hinges on wavelength innovation pipelines and physician training ecosystem lock-in. Monitor Health Canada-FDA licensing synchronization as inflection indicator for regulatory arbitrage collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for picosecond wavelength innovations strengthen first-mover positioning against predicate-device competitors. |
| Physician Training Ecosystem Expansion | Certified operator networks in California and Texas sustain premium pricing through differentiated clinical outcomes and liability protection. |
| Subscription Revenue Model Migration | Multi-session membership tiers in Los Angeles and Toronto reduce seasonal demand volatility and concentrate patient lifetime value. |
| Health Canada Parallel Licensing | Dual-jurisdiction regulatory affairs consolidation captures Canadian metropolitan corridor demand with reduced competitive filing density. |
| Fractional Laser Portfolio Extension | Striae revision capabilities at 1540 nm penetrate post-pregnancy demographics underserved by tattoo-focused device marketing. |
Research Approach
Document review covered FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, and state medical board scope-of-practice rulings, complemented by interviews with dermatology clinic operators, biomedical equipment procurement managers, and laser safety training program directors. Secondary validation drew from SEC filings of publicly traded aesthetic device manufacturers, hospital procurement database extracts, and GPO contract repositories. Bottom-up demand modeling from clinic-level equipment placement data was triangulated against top-down market sizing from manufacturer shipment disclosures.
Cross-referencing historical wavelength adoption curves with panel input from regulatory affairs specialists shaped the analytical framework across the analysis window. Segmentation dimensions modeled include device type, application indication, end-user setting, and technology mechanism of action. CAGRs were derived from equipment replacement cycle analysis and subscription revenue conversion rates. Forecast inputs incorporated Health Canada-FDA licensing synchronization timelines and state-level scope-of-practice expansion probabilities.
Underlying measurement precision varies by segment; picosecond laser placement data carries tighter precision than refurbished equipment secondary market flows. Forecasts reflect assumptions about regulatory pathway efficiency and cosmetic clinic consolidation velocity. Device recall events or wavelength-specific safety advisories could revise outlook materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
India Hair Transplant Market