
 Japan Laser Hair Removal Market | 2026-2036
Japan Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Laser Hair Removal Market Insights
Medical aesthetic clinic distribution is narrowing toward physician-supervised chains with capital for multi-wavelength platforms. Lumenis sustains its installed base through service contracts and training academies tied to university hospitals. Alma Lasers Ltd. competes by bundling diode and Nd:YAG modules for skin-type flexibility. Cutera Inc. specializes in marketing to independent dermatology practices seeking differentiated technology.
Laser hair removal employs selective photothermolysis, targeting melanin in follicles with wavelengths between 755 nm and 1064 nm while cooling epidermal tissue to prevent thermal injury; systems integrate sapphire contact cooling or cryogen spray to protect surrounding skin during energy delivery. Diode laser systems occupy the largest revenue share due to versatility across Fitzpatrick skin types I through IV. Alexandrite laser platforms lead in treatment speed for lighter skin tones, while Nd:YAG configurations dominate demand from clinics serving darker-complexion patients in Japan's multicultural urban corridors.
PMDA clearance requirements for Class IV medical lasers mandate clinical efficacy documentation and adverse-event monitoring, constraining import timelines for non-Japanese manufacturers. METI energy-efficiency guidelines and JIS C 6802 laser safety standards further shape equipment design and operator certification protocols. Stakeholders must monitor evolving reimbursement positioning for laser procedures within Japan's statutory health insurance framework.
Market Dynamics
Medical aesthetic chains in Tokyo and Osaka are consolidating procurement around multi-wavelength diode platforms, reshaping vendor relationships toward long-term service bundling and certified operator training programs.
Growth Catalysts
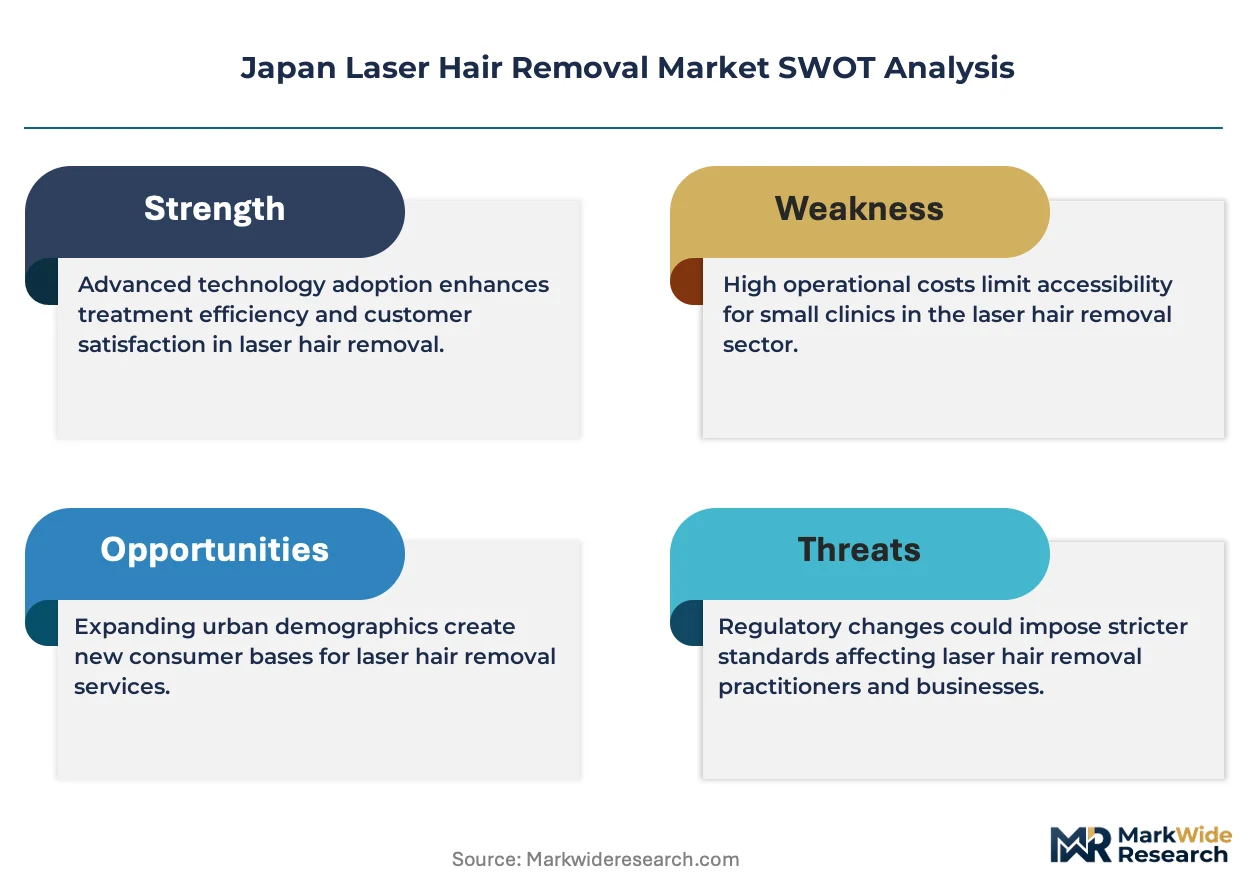
- Multi-wavelength diode technology:Clinics serving Japan's multicultural urban corridors deploy combined 755 nm alexandrite and 1064 nm Nd:YAG modules to address Fitzpatrick skin types I through VI without equipment switching.
- PMDA Class IV clearance pathways:Streamlined clinical efficacy documentation for diode laser systems accelerates market entry for manufacturers meeting adverse-event monitoring protocols.
- Osaka-Kobe medical corridor:Physician-supervised aesthetic chains concentrate capital investment in permanent hair reduction services, creating dense referral networks for advanced laser platforms.
Market Restraints
- Import equipment cost structure:Non-Japanese manufacturers face extended PMDA review timelines and yen-denominated procurement costs that compress margin recovery.
- Sapphire cooling component supply:Contact cooling systems for epidermal protection rely on concentrated optical materials sourcing, creating input volatility for system integrators.
- JIS C 6802 operator certification:Mandatory laser safety training and facility inspection protocols extend clinic onboarding periods and limit rapid capacity scaling.
Strategic Opportunities
- Fukuoka-Sapporo corridor expansion:Underpenetrated secondary metropolitan markets present whitespace for mid-tier diode platforms targeting independent dermatology practices.
- Home-use IPL convergence:Integration of professional-grade diode technology into consumer devices creates channel expansion beyond clinical settings.
- METI energy-efficiency incentives:Equipment redesigns meeting revised power consumption guidelines qualify for operational subsidy programs and accelerated depreciation schedules.
Industry Challenges
- Certified laser technician scarcity:Japan's limited pipeline of dermatology nurses with PMDA-mandated laser safety credentials constrains clinic expansion timelines.
- Legacy alexandrite system integration:Established practices with installed 755 nm platforms face capital inefficiency when upgrading to multi-wavelength configurations without trade-in pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Laser Hair Removal Market |
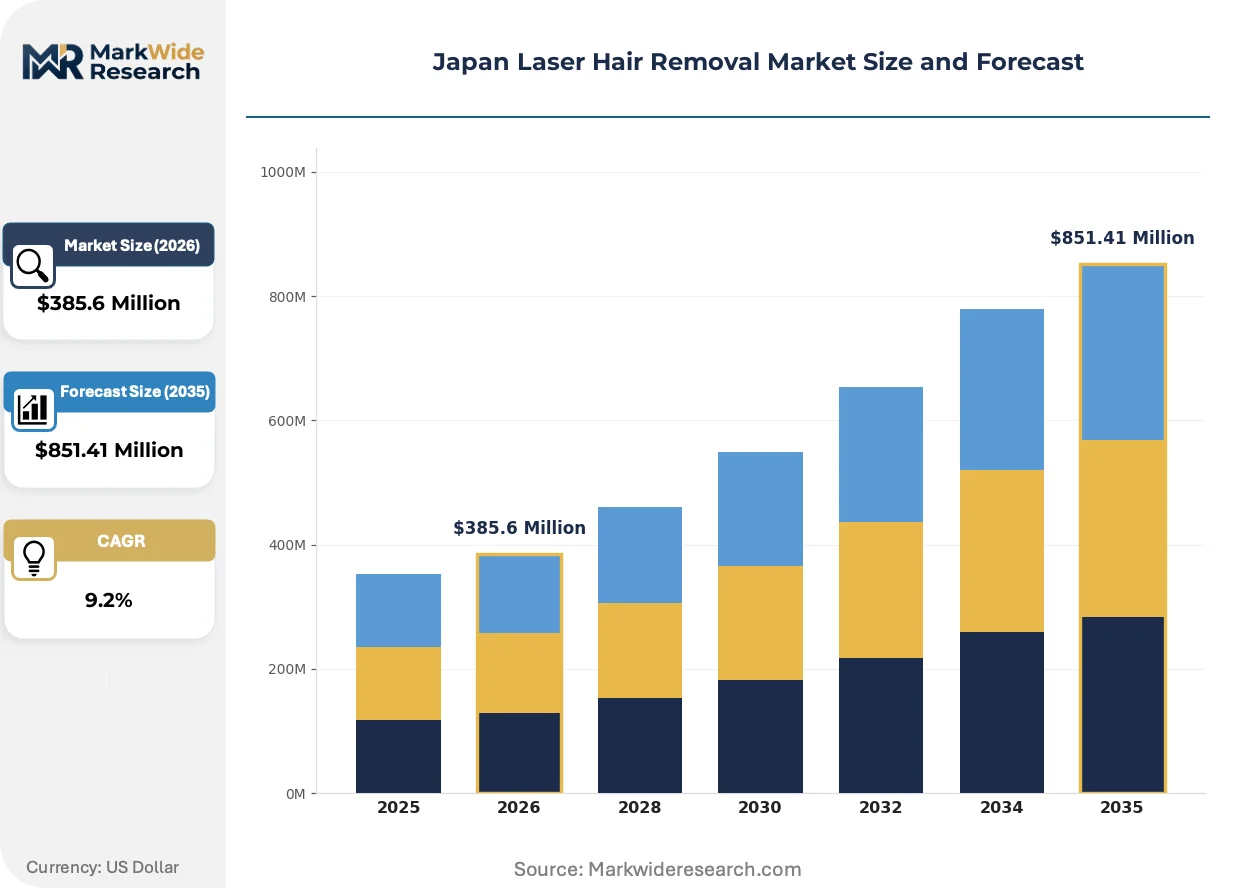
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $851.41 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, Alexandrite Laser, Nd:YAG Laser, Intense Pulsed Light End User: Clinics, Spas, Home Users, Dermatology Centers Service Type: Permanent Hair Reduction, Hair Removal Sessions, Skin Rejuvenation, Consultation Services Technology: Single Pulse, Multi-Pulse, Continuous Wave, Fractional |
| Companies Covered | Cutera Inc., Cynosure, Lumenis, Venus Concept, Sciton, Lutronic, Candela Corporation, Lynton Lasers, Alma Lasers Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Laser Hair Removal Market Trends and Innovations
Technology convergence and regulatory recalibration are compressing treatment protocols while expanding addressable patient populations across Japan's aesthetic medicine sector.
Triple-wavelength diode platforms is collapsing the distinction between skin-type-specific laser systems by integrating 755 nm, 808 nm, and 1064 nm outputs within single handpieces. Tokyo-based medical aesthetic chains are adopting these systems at accelerated replacement cycles to reduce equipment footprint. This convergence is collapsing the historical segmentation between alexandrite-dominant and Nd:YAG-dominant clinic specializations.
PMDA's 2024 guidance on real-world evidence submission for Class IV laser modifications is compressing post-market surveillance requirements for software-upgradable diode systems. Manufacturers now embed predictive maintenance algorithms to satisfy continuous safety monitoring obligations. Osaka dermatology centers are prioritizing platforms with over-the-air update capabilities to minimize regulatory downtime.
Subscription-based equipment access is displacing outright purchase models among independent practices in Nagoya and Fukuoka. Per-treatment revenue-sharing arrangements with distributors reduce upfront capital barriers for Nd:YAG platform adoption. This financing shift is most visible among dermatology practices serving darker-complexion patient segments previously excluded by equipment cost constraints.
Japan Laser Hair Removal Market Segmentation
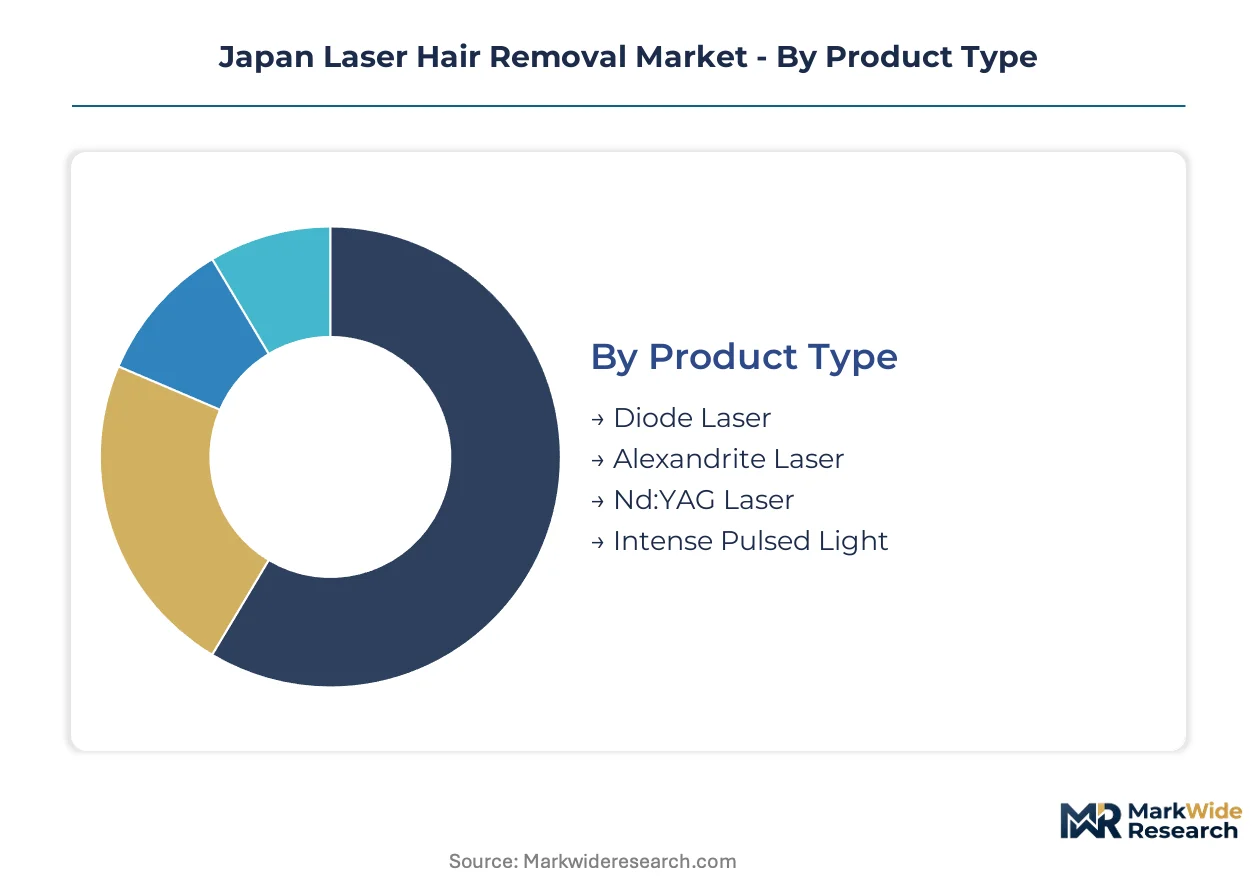
Segmentation reveals distinct service intensity profiles across Japan's laser hair removal landscape. Equipment lifecycle management and operator certification requirements vary sharply by product configuration and end-user setting.
Product Type:
After-sales-service intensity diverges significantly across laser platforms, with multi-wavelength systems demanding specialized technician deployment and calibration protocols that reshape vendor-client relationships.
- Diode Laser:These 808 nm systems integrate sapphire contact cooling and modular handpiece design for Fitzpatrick types I through IV. Tokyo medical aesthetic chains concentrate procurement here due to versatility across Japan's predominant lighter skin-tone patient base. Service contracts typically bundle predictive maintenance algorithms to satisfy PMDA continuous monitoring obligations.
- Alexandrite Laser:755 nm platforms deliver fastest treatment speeds for types I through III through larger spot sizes and higher repetition rates. Osaka dermatology centers prioritize these for high-volume permanent hair reduction workflows where throughput governs clinic economics.
- Nd:YAG Laser:1064 nm systems penetrate deeper with minimal epidermal melanin absorption, serving darker-complexion patients in Japan's multicultural urban corridors.
- Intense Pulsed Light:Broad-spectrum devices occupy lower price tiers with reduced single-treatment efficacy, attracting budget-conscious independent practices in secondary metropolitan markets.
By volume, Diode Laser leads. By growth pace, Nd:YAG is ahead.
End User:
Capital deployment patterns and regulatory compliance burdens segment sharply across customer types, with physician-supervised facilities facing distinct PMDA facility inspection protocols.
- Clinics:Physician-supervised aesthetic chains in Tokyo and Osaka dominate equipment procurement, consolidating around triple-wavelength platforms with embedded software update capabilities to minimize regulatory downtime.
- Spas:Non-medical wellness facilities operate under lighter JIS C 6802 compliance frameworks, typically deploying IPL or lower-power diode systems for maintenance-oriented hair reduction rather than permanent outcomes.
- Home Users:Consumer-grade IPL convergence creates channel expansion beyond clinical settings, with METI energy-efficiency guidelines shaping device redesigns.
- Dermatology Centers:University-affiliated facilities in the Osaka-Kobe medical corridor anchor training ecosystems and drive adoption of research-validated multi-pulse configurations.
Clinics command the largest installed base. Home Users are expanding most quickly.
Service Type:
Revenue model differentiation separates subscription-based per-treatment arrangements from upfront package sales, with financing structures reshaping patient acquisition economics.
- Permanent Hair Reduction:Clinically validated outcomes requiring multiple sessions generate recurring revenue streams and long-term patient relationships.
- Hair Removal Sessions:Individual treatment bookings attract price-sensitive consumers through promotional pricing without package commitment.
- Skin Rejuvenation:Collateral diode applications for photodamage and texture improvement expand addressable visit frequency among existing patient bases.
- Consultation Services:Fitzpatrick typing and contraindication screening create entry points for upselling multi-wavelength protocols.
Permanent Hair Reduction dominates revenue contribution. Consultation Services are gaining share fastest.
Technology:
Pulse architecture determines thermal injury risk profiles and corresponding PMDA adverse-event monitoring stringency, with software-upgradable systems compressing post-market surveillance timelines.
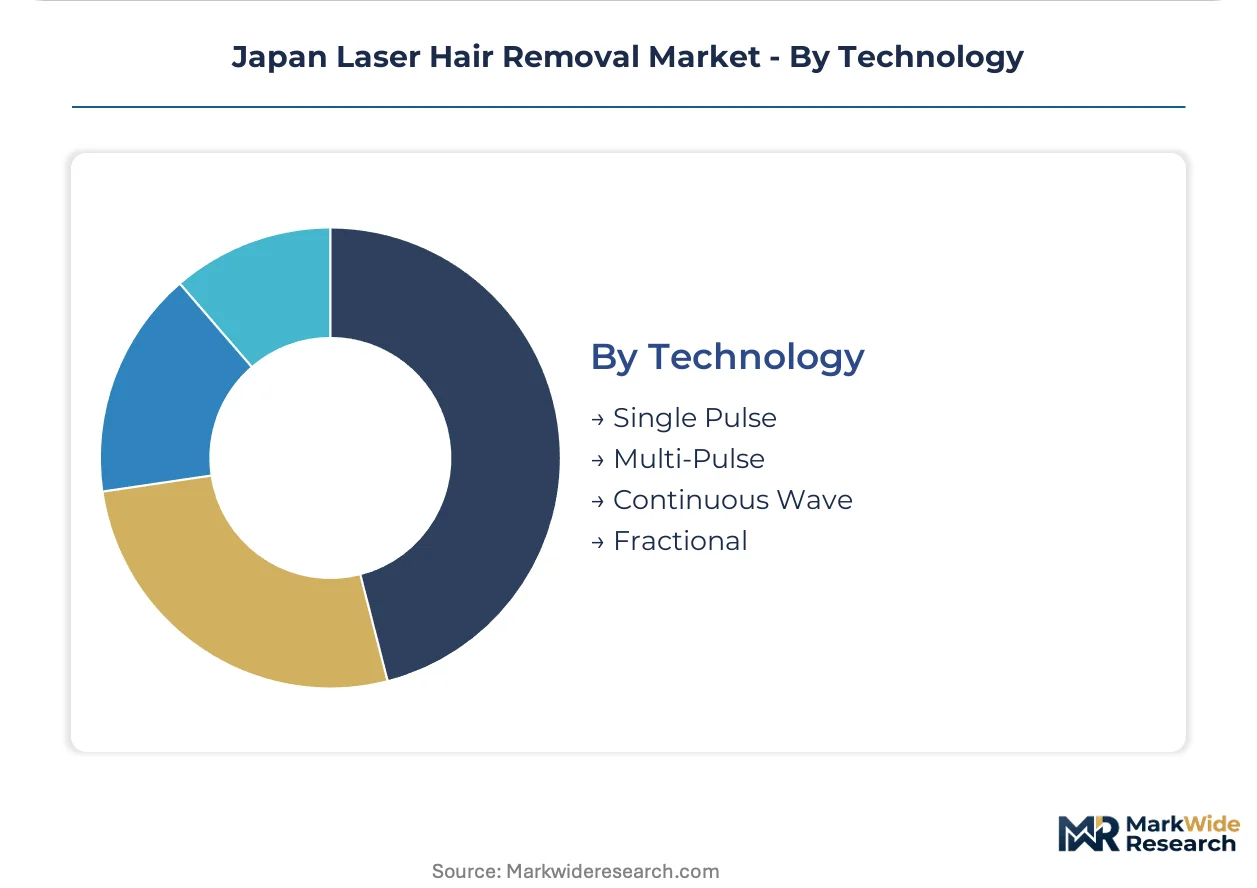
- Single Pulse:High-peak-power delivery maximizes follicular destruction per shot, requiring precise epidermal cooling integration.
- Multi-Pulse:Fractionated energy deposition with inter-pulse cooling intervals dominates premium platform configurations, enabling safer treatment of darker skin types.
- Continuous Wave:Sustained emission modes serve specialized applications with lower peak intensities.
- Fractional:Micro-beam array technology creates treatment zones with surrounding untreated tissue, accelerating recovery and expanding candidacy.
Multi-Pulse leads by clinical adoption. Fractional shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shinkansen high-speed rail network underwrites patient mobility across Japan's archipelago, concentrating aesthetic service demand within two-hour travel corridors of major metropolitan centers.
Kanto/Tokyo
Physician-supervised chains deploy triple-wavelength diode platforms to serve Fitzpatrick types I through VI in Japan's most multicultural patient corridor. METI energy-efficiency guidelines accelerate equipment replacement cycles in Shinjuku and Shibuya clinic clusters. The Tokyo-Osaka Shinkansen corridor funnels referral traffic into Ginza and Omotesando medical aesthetic hubs.
Kansai/Osaka
Independent dermatology practices consolidate procurement around Nd:YAG configurations for darker-complexion patient segments. PMDA Class IV clearance pathways streamline adverse-event monitoring for software-upgradable systems. The Osaka-Kobe medical corridor anchors university hospital training ecosystems that drive multi-pulse technology adoption.
Chubu/Nagoya
Mid-tier diode platforms target underpenetrated independent practices seeking per-treatment revenue-sharing arrangements. JIS C 6802 operator certification requirements extend clinic onboarding periods in this secondary market. Nagoya's automotive industry concentration generates professional demographic demand for permanent hair reduction services.
Kyushu
Fukuoka's proximity to East Asian medical tourism corridors creates demand for multi-wavelength platforms serving international patients. Sapphire cooling component supply constraints affect system integrators serving this peripheral market. The Fukuoka-Sapporo expansion corridor presents whitespace for subscription-based equipment access models.
Hokkaido
Sapporo's seasonal tourism economy concentrates aesthetic demand in winter months, favoring flexible financing structures. Certified laser technician scarcity constrains clinic expansion timelines across northern Japan. Sapporo dermatology centers prioritize platforms with predictive maintenance algorithms to minimize regulatory downtime.
Japan Laser Hair Removal Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical materials and cooling subsystems. The vendor base concentrates around five to seven established manufacturers with PMDA clearance histories, creating tiered barriers for new entrants. Two strategic archetypes dominate: multi-wavelength platform bundlers and single-technology speed specialists. Competitive moves center on service contract bundling and certified operator training academy partnerships.
Among Israel-based platform developers, Lumenis and Alma Lasers Ltd. occupy positions as archetype anchors for multi-wavelength system integration. Cutera Inc. exemplifies the independent-practice targeting model within the US-origin vendor segment. These three manufacturers represent the core competitive set referenced in procurement discussions across Tokyo and Osaka clinic chains.
| Leading Market Players |
|---|
| Cutera Inc. |
| Cynosure |
| Lumenis |
| Venus Concept |
| Sciton |
| Lutronic |
| Candela Corporation |
| Lynton Lasers |
| Alma Lasers Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in sapphire contact cooling component fabrication is compressing margin recovery for diode laser system integrators while simultaneously hardening volume-discount tiering for Tokyo clinic chains. This utilization squeeze propagates through PMDA-mandated safety equipment procurement, where yen-denominated import costs amplify pricing volatility for non-Japanese manufacturers.
Pricing Analysis
Volume-discount tiering structures separate physician-supervised aesthetic chains from independent dermatology practices across three pricing levels differentiated by after-sales service bundling and certified operator training inclusion. Price differentiation hinges on PMDA Class IV clearance tier and multi-wavelength platform configuration, with premium tiers absorbing predictive maintenance algorithm costs. Pricing pressure intensifies in the Nd:YAG segment as subscription-based per-treatment arrangements displace outright purchase models among Nagoya and Fukuoka independents. Clinic chains demonstrate lowest price sensitivity due to capital concentration in Tokyo and Osaka, while secondary market dermatology practices exhibit acute responsiveness to financing structure flexibility.
Supply Chain Analysis
Supplier-financing extensions through 90-120 day payment terms are emerging as critical liquidity mechanisms for Osaka-based system integrators sourcing optical materials from Germany, Israel, and the United States. Raw material dependencies center on sapphire crystal substrates, GaAs semiconductor wafers, and cryogen spray propellants, with distribution running through authorized medical device distributors holding PMDA facility inspection certifications. Single-source vulnerability concentrates in Israeli platform developer supply chains, where geopolitical friction threatens component continuity for multi-wavelength diode configurations. The downstream structure favors direct manufacturer-to-clinic relationships for high-value platform sales, with regional distributors handling aftermarket service parts and consumables replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Triple-wavelength diode convergence is disrupting Japan's laser hair removal sector with PMDA's 2024 real-world evidence guidance compressing regulatory timelines for software-upgradable platforms.
For Market Incumbents: Harden service contract bundling around predictive maintenance algorithms to lock in Tokyo clinic chain loyalty against emerging subscription-based competitors. Deepen backward integration into sapphire cooling component supply through captive sourcing agreements with German optical materials specialists, insulating margin structures from yen volatility. For New Entrants and Emerging Players: Establish a beachhead in the Fukuoka-Sapporo corridor where certified laser technician scarcity has constrained incumbent expansion timelines. Target independent dermatology practices in Nagoya with per-treatment revenue-sharing arrangements for Nd:YAG platform adoption, leveraging financing structure innovation as the primary go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform developers with embedded software update capabilities and long-term service academy partnerships anchoring university hospital training ecosystems. Five-to-ten year viability favors manufacturers with PMDA clearance histories spanning multiple laser classifications. Monitor PMDA adverse-event monitoring protocol modifications as the critical inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Class IV Clearance Pathway Streamlining | Accelerated market entry for diode systems meeting real-world evidence protocols reshapes competitive timelines. |
| Triple-Wavelength Platform Integration | Convergence of 755 nm, 808 nm, and 1064 nm outputs collapses skin-type specialization economics. |
| Certified Operator Training Academy Partnerships | University hospital alliances in Osaka-Kobe corridor create defensible talent pipelines and referral networks. |
| Subscription-Based Equipment Access Models | Per-treatment financing structures unlock Nd:YAG adoption among capital-constrained independent practices. |
| Sapphire Cooling Component Backward Integration | Upstream control over optical materials supply mitigates input volatility and margin compression risks. |
Research Methodology
Initial hypotheses were tested against primary input from PMDA regulatory consultants, medical aesthetic clinic procurement directors, dermatology center operators, and biomedical equipment distributors, then refined through secondary validation against METI energy-efficiency filings, JIS C 6802 certification registries, PMDA medical device approval databases, and hospital procurement contract disclosures. Bottom-up equipment shipment tracking was triangulated with top-down clinic capacity modeling across Tokyo, Osaka, Nagoya, Fukuoka, and Sapporo metropolitan corridors.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning laser platform type, end-user facility category, service revenue model, and pulse architecture technology. CAGRs were derived from equipment replacement cycle analysis and patient visit frequency projections, incorporating PMDA clearance timeline assumptions and JIS operator certification pipeline constraints as industry-specific forecast inputs.
Stress conditions across yen exchange rate volatility, sapphire substrate supply disruptions, and PMDA adverse-event monitoring protocol stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinic consolidation rates and multicultural patient demographic expansion. Macroeconomic deviation, regulatory recalibration, or technological substitution would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Gum Lift Market