
 Germany Facial Aesthetics Market | 2026-2036
Germany Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Facial Aesthetics Market Insights
Medical spa chains is recalibrating the channel landscape for facial aesthetics delivery across Germany. Galderma leverages its injectables portfolio to anchor premium positioning in urban centers. Merz Pharma competes through sustained R&D intensity in neurotoxin formulations. Alma Lasers controls distribution for energy-based platforms targeting skin resurfacing segments.
Facial aesthetics encompasses minimally invasive and non-invasive procedures that modify skin texture, volume distribution, or muscular activity through injectable biologics, laser or radiofrequency energy delivery, and chemical exfoliation at controlled depths. Botulinum Toxin and dermal fillers concentrate margin pools due to repeat purchase cycles and practitioner certification requirements. Chemical peels and microneedling occupy expanding positions among younger age cohorts seeking lower-cost entry points. Dermatology clinics sustain the highest procedure volume, though cosmetic surgery centers and medical spas are capturing share through bundled service packaging.
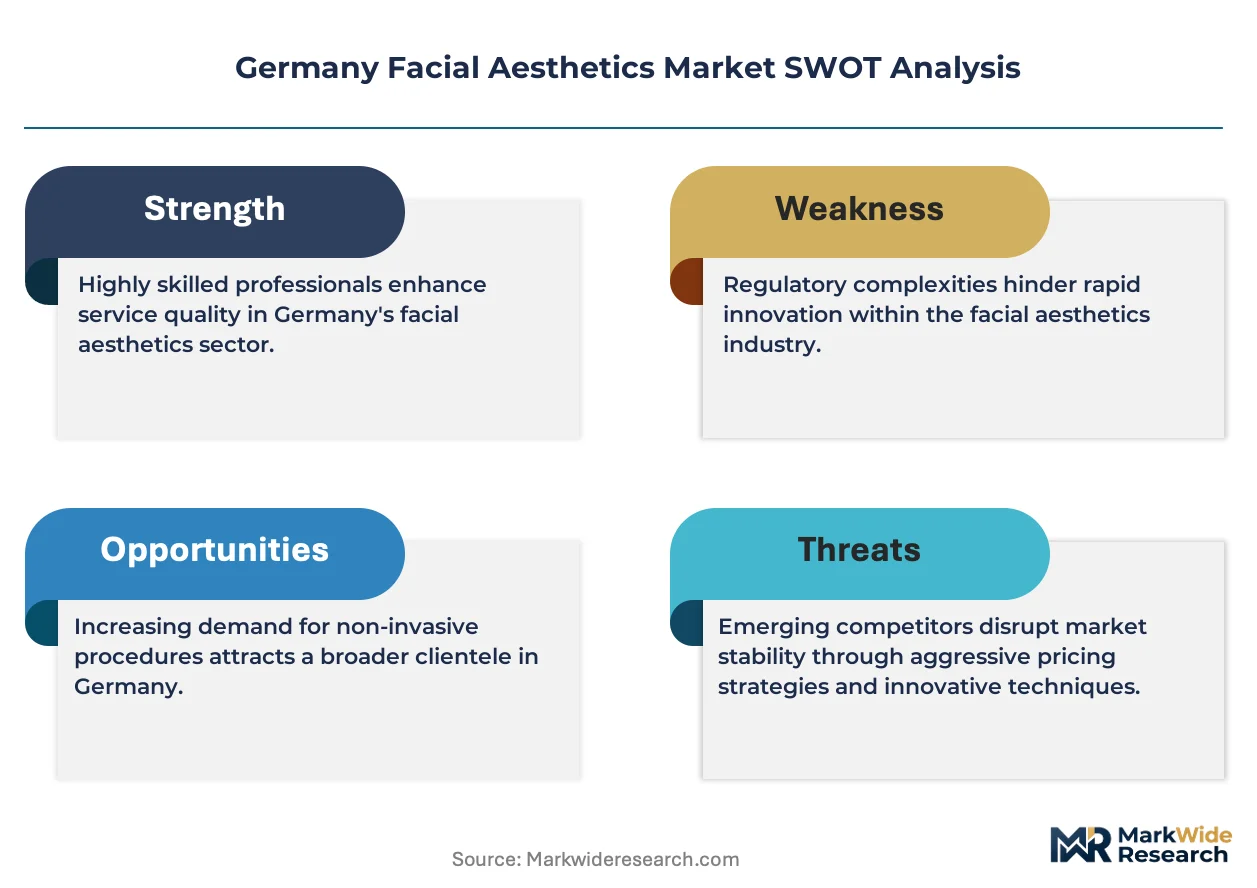
The EU Medical Device Regulation (MDR) and Germany's Federal Institute for Drugs and Medical Devices (BfArM) impose stringent clinical evidence requirements on aesthetic device manufacturers, elevating barriers for new entrants. The EU AI Act and existing GDPR provisions shape data handling for AI-assisted diagnostic and treatment planning tools emerging in facial analysis. REACH compliance governs chemical peel formulations, constraining ingredient sourcing flexibility. Stakeholders must monitor evolving BfArM guidance on combination product classifications, as blurred boundaries between drugs and devices trigger reclassification risks with significant compliance cost implications.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product launch timelines while medical spa chains in Berlin and Munich expand service menus beyond traditional dermatology clinic offerings.
Growth Catalysts
- EU MDR compliance frameworks:Stringent clinical evidence requirements under BfArM guidance elevate practitioner certification standards, creating captive demand for established device portfolios.
- Energy-based platform convergence:Radiofrequency and laser technologies are consolidating treatment protocols, reducing per-procedure time investments for Hamburg and Frankfurt clinic operators.
- Male-identifying consultation growth:Hamburg and Frankfurt now represent the fastest-growing patient demographic, expanding addressable market beyond traditional female-skewed segments.
Market Restraints
- Injectable biologics supply concentration:Botulinum toxin and hyaluronic acid filler production clusters in Switzerland and France, exposing German distributors to cross-border supply friction.
- REACH chemical sourcing constraints:Peel formulation ingredient restrictions limit German manufacturers' flexibility in developing next-generation exfoliation protocols.
- Energy device technical ceiling:Skin resurfacing platforms face diminishing returns on power output without corresponding tissue damage risk escalation.
Strategic Opportunities
- AI-assisted facial analysis tools:GDPR-compliant diagnostic platforms enable personalized treatment planning with measurable outcome documentation.
- Bavarian medical spa corridor expansion:Munich satellite clinics in Augsburg and Nuremberg remain underpenetrated relative to Berlin-Hamburg density benchmarks.
- Bundled service packaging:Multi-modality subscription models combining neurotoxin, filler, and energy-based maintenance compress patient acquisition costs.
Industry Challenges
- Practitioner certification bottlenecks:BfArM-mandated training hours for combination product administration constrain clinic staffing scalability.
- Legacy clinic management system integration:AI diagnostic platforms require substantial reconfiguration of Hamburg and Frankfurt patient record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Facial Aesthetics Market |
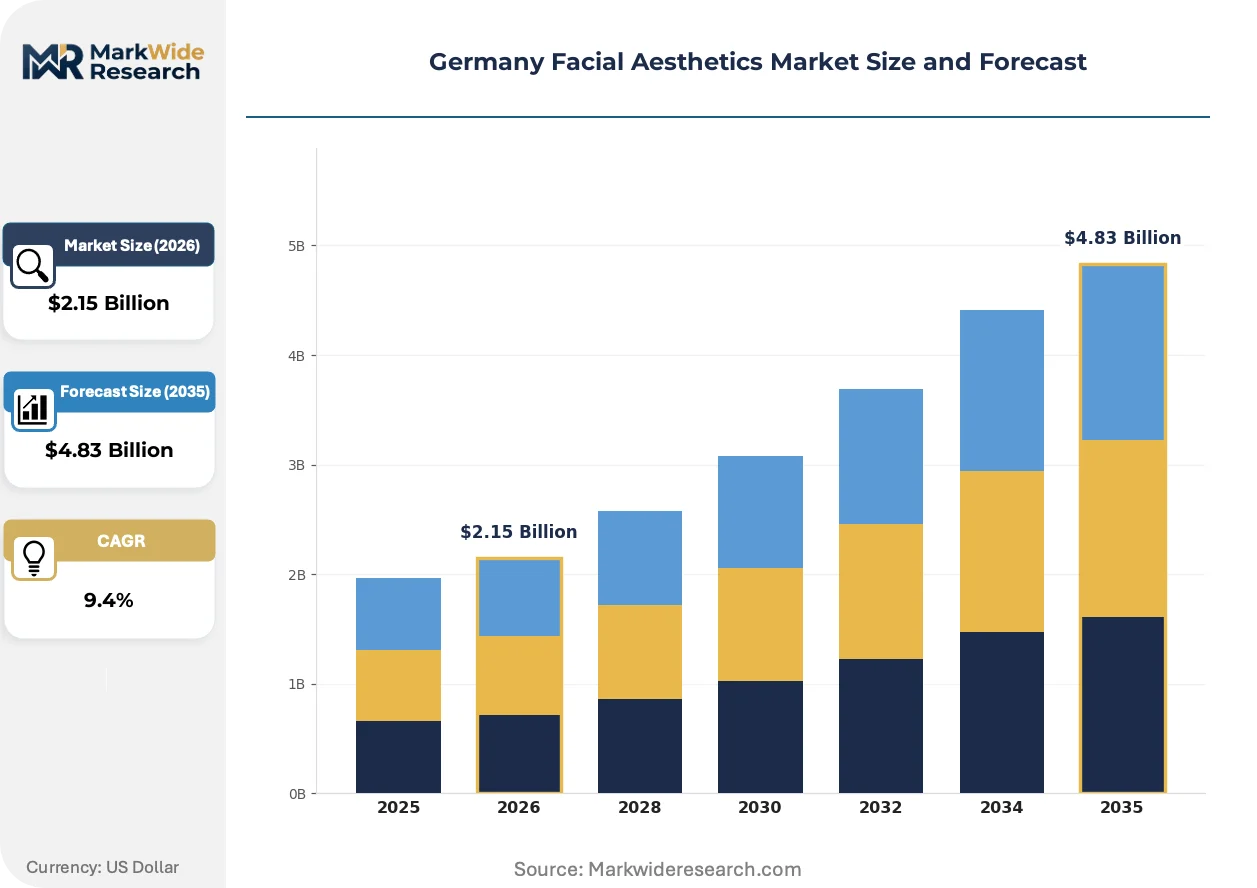
| Market Size in 2026 | $2.15 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Botulinum Toxin, Dermal Fillers, Chemical Peels, Microneedling End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Home Users Gender: Female, Male, Non-Binary, Others Age Group: 18-24, 25-34, 35-44, 45+ |
| Companies Covered | Lumenis, Cynosure, AbbVie Inc (Allergan Aesthetics), Bausch Health Companies Inc, Candela Medical, Merz Pharma, Alma Lasers, Anika Therapeutics Inc, Galderma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Facial Aesthetics Market Trends and Innovations
Automation of treatment planning and outcome prediction is compressing consultation-to-procedure cycles across German urban centers.
AI-powered facial mapping software is automating volume loss quantification and injection site prediction. Dermatology clinics in Berlin and Munich are deploying these tools to standardize filler consultation protocols. The technology is automating practitioner decision support, reducing variability in patient outcome documentation.
GDPR enforcement actions by German data protection authorities are tightening consent frameworks for biometric facial data storage. Aesthetic device manufacturers must now embed privacy-by-design architectures into diagnostic platforms. The regulatory pressure is compressing product development timelines for Hamburg and Frankfurt clinic technology vendors.
Subscription-based maintenance contracts are displacing per-procedure pricing in Berlin medical spa chains. Younger patient cohorts in Munich prefer predictable monthly outlays over lump-sum treatment investments. The behavioral shift is most visible among 25-35 age segments seeking neurotoxin prevention protocols.
Germany Facial Aesthetics Market Segmentation
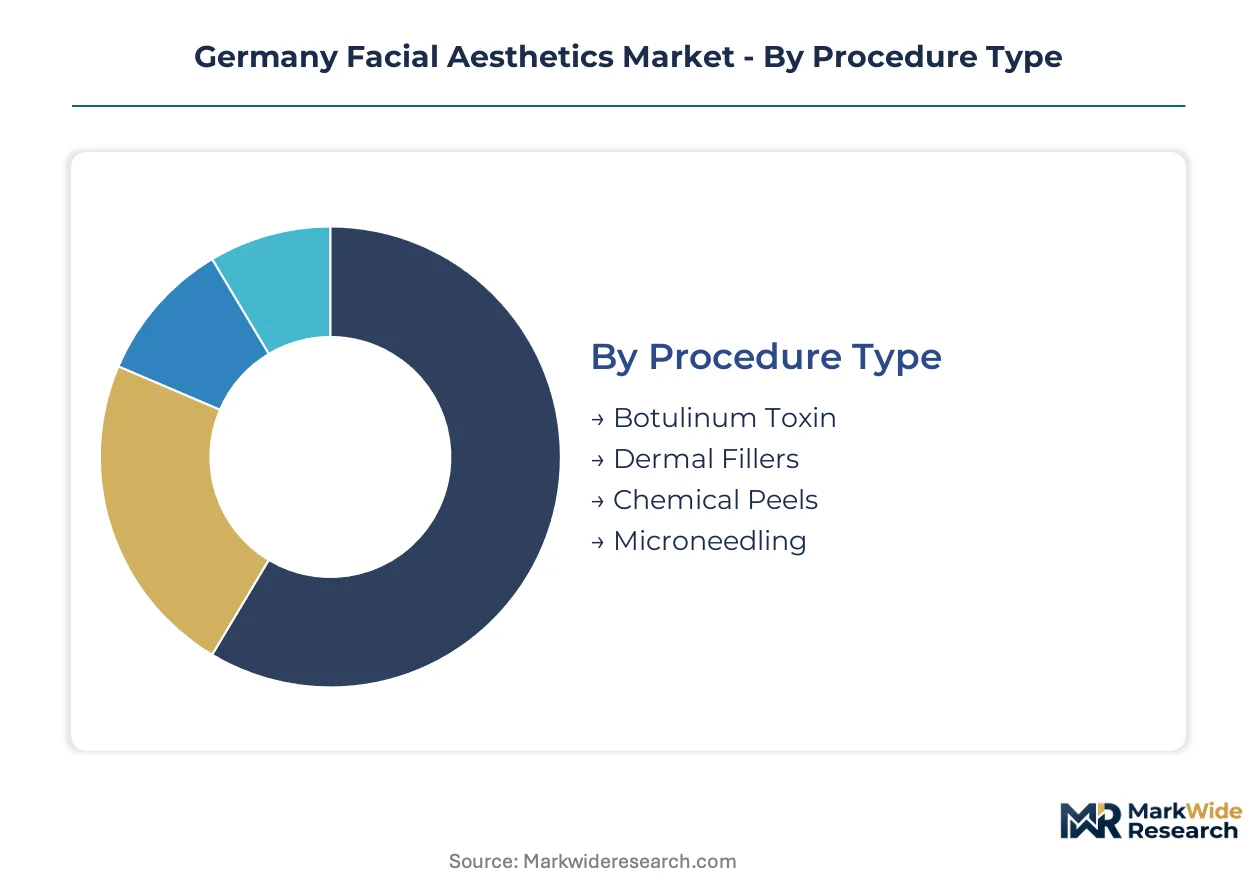
Procedure type and end user configurations determine margin capture and repeat visit economics for German facial aesthetics providers. Gender and age cohorts are fragmenting demand profiles, requiring differentiated service packaging across Berlin, Munich, and Hamburg metro clusters.
Procedure Type:
Standardization dominates injectable protocols while energy-based and chemical treatments allow practitioner customization latitude.
- Botulinum Toxin:Neurotoxin formulations temporarily inhibit muscular contraction to smooth dynamic wrinkles. Demand concentrates in Hamburg and Frankfurt medical spas where male-identifying patients now drive consultation volume expansion.
- Dermal Fillers:Hyaluronic acid and calcium hydroxylapatite compounds restore volume loss through subdermal injection. Berlin dermatology clinics capture premium pricing through BfArM-mandated practitioner certification tiers that limit supply.
- Chemical Peels:Controlled-depth acid exfoliation protocols address pigmentation and texture irregularities. REACH compliance constrains German manufacturer ingredient sourcing flexibility.
- Microneedling:Percutaneous collagen induction using automated pen devices or radiofrequency-augmented platforms. Younger Munich cohorts favor this lower-cost entry point.
Leading the category by volume: Botulinum Toxin. Expanding most quickly: Microneedling among 25-34 age segments.
End User:
Channel economics diverge sharply between high-overhead clinical settings and asset-light spa operations.
- Dermatology Clinics:Physician-supervised facilities with BfArM compliance infrastructure and highest procedure throughput. Munich and Berlin clusters sustain premium pricing through medical credential differentiation.
- Cosmetic Surgery Centers:Hospital-affiliated or standalone surgical practices bundling invasive and non-invasive services. Frankfurt operators face staffing scalability constraints from certification bottlenecks.
- Medical Spas:Hybrid clinical-aesthetic environments in Berlin and Munich expanding service menus beyond traditional dermatology offerings. Subscription pricing models are displacing per-procedure fees.
- Home Users:Consumer-grade microneedling devices and peel kits distributed through e-commerce. BfArM oversight limits device power thresholds and biologic concentration.
Dermatology Clinics generate highest absolute procedure counts. Medical Spas are gaining share fastest through bundled subscription packaging.
Gender:
Service marketing and consultation protocols are recalibrating around expanding male-identifying demand.
- Female:Traditional core demographic with established neurotoxin prevention and filler maintenance cycles. Berlin and Munich clinics retain loyalty through membership programs.
- Male:Fastest-growing consultation segment in Hamburg and Frankfurt seeking subtle volume restoration and wrinkle reduction. Medical spa chains are deploying targeted digital acquisition.
- Non-Binary:Gender-affirming facial contouring and softening procedures. Urban centers with specialized practitioner networks serve this cohort.
- Others:Patients declining binary classification, requiring documentation system flexibility under GDPR biometric data provisions.
Female patients dominate current volume. Male-identifying segments show steepest expansion trajectory.
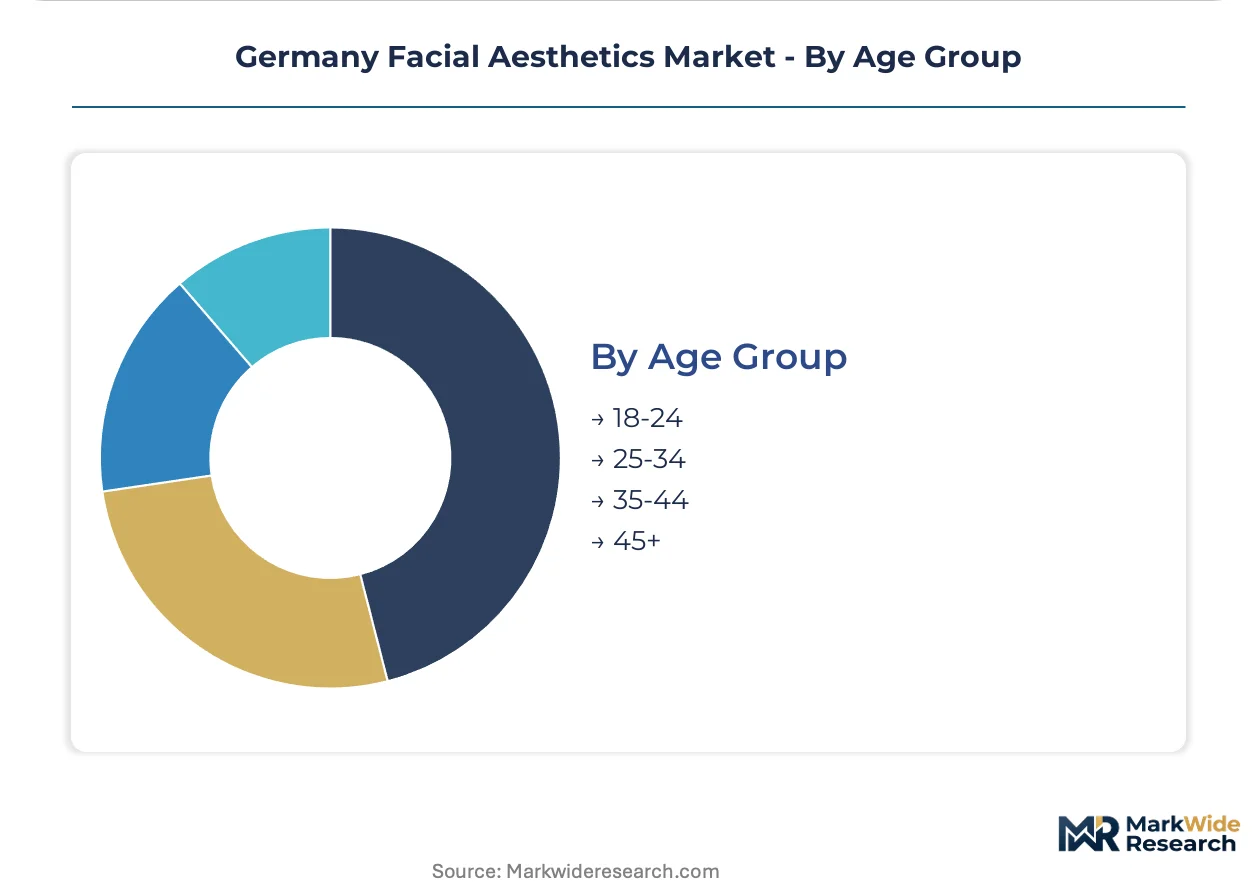
Age Group:
Treatment intensity and price sensitivity invert across the age spectrum, with prevention protocols emerging youngest.
- 18-24:Early intervention focused on skin quality maintenance and preventive neurotoxin. Munich medical spas capture this cohort through social media-native marketing.
- 25-34:Subscription-based maintenance contracts combining microneedling, light peels, and starter toxin doses. Berlin chains report highest conversion rates here.
- 35-44:Volume restoration and dynamic line correction through filler and toxin combinations. Frankfurt clinics see elevated per-patient spend.
- 45+:Comprehensive multi-modality protocols addressing advanced photodamage and structural loss. Hamburg dermatology centers sustain this base.
35-44 age bracket delivers highest per-procedure revenue. 25-34 cohort is climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's medical technology corridor concentrates Germany's highest density of aesthetic device manufacturing and clinical service delivery infrastructure.
Bavaria
Munich anchors the southern medical spa corridor with satellite clinics expanding into Augsburg and Nuremberg. BfArM-mandated practitioner certification requirements limit staffing scalability for combination product administration. Alma Lasers controls distribution for energy-based platforms targeting skin resurfacing segments from its Bavarian operational base.
North Rhine-Westphalia
Düsseldorf and Cologne clusters drive injectable biologics distribution through proximity to Benelux supply routes. REACH compliance governs chemical peel formulation ingredient sourcing flexibility across German manufacturers. The region's logistics infrastructure supports cross-border distribution of botulinum toxin and hyaluronic acid filler products from Swiss and French production centers.
Baden-Württemberg
Stuttgart's precision manufacturing ecosystem supplies components for automated microneedling and radiofrequency platforms. The EU Medical Device Regulation elevates barriers for new aesthetic device entrants through stringent clinical evidence requirements. Heidelberg and Freiburg university medical centers anchor practitioner training networks for BfArM certification programs.
Berlin-Brandenburg
Capital region medical spa chains recalibrate service menus beyond traditional dermatology clinic offerings through bundled subscription packaging. GDPR enforcement actions by Berlin data protection authorities tighten consent frameworks for biometric facial data storage in AI-assisted diagnostic platforms. Galderma leverages its injectables portfolio to anchor premium positioning across urban center locations.
Hamburg
Male-identifying patient segments in Hamburg represent the fastest-growing consultation demographic for subtle volume restoration and wrinkle reduction protocols. Merz Pharma competes through sustained R&D intensity in neurotoxin formulations from its northern German operational presence. Medical spa chains deploy targeted digital acquisition strategies to capture expanding male-skewed demand.
Germany Facial Aesthetics Market Competitive Landscape
Top-tier vendors anchor premium injectables and energy-based device portfolios, while mid-tier specialists occupy chemical peel and microneedling segments. The vendor structure concentrates around three strategic archetypes: Swiss-German pharmaceutical conglomerates with neurotoxin and filler pipelines, Israeli laser platform manufacturers with distribution control, and diversified dermatology portfolios spanning biologics and devices. Competitive moves center on M&A activity for combination product capabilities and vertical integration into practitioner training certification networks.
Among Israel-based energy platform specialists, Lumenis and Alma Lasers exemplify the device-manufacturing archetype with concentrated distribution control over skin resurfacing segments. AbbVie Inc (Allergan Aesthetics) and Galderma occupy positions within the pharmaceutical-tier vendor group, representing the injectables-focused competitive vector. Merz Pharma sits within the neurotoxin specialization tier, anchoring R&D-intensive competitive positioning against broader dermatology portfolios.
| Leading Market Players |
|---|
| Lumenis |
| Cynosure |
| AbbVie Inc (Allergan Aesthetics) |
| Bausch Health Companies Inc |
| Candela Medical |
| Merz Pharma |
| Alma Lasers |
| Anika Therapeutics Inc |
| Galderma |
| Others |
Pricing and Supply Chain Analysis
REACH chemical sourcing mandates gate qualified supply for German peel manufacturers and simultaneously restrict premium-tier pricing access for non-compliant formulations. BfArM-mandated practitioner certification tiers create parallel segmentation in injectable biologics, where certified clinic networks command pricing premiums unavailable to uncertified competitors.
Pricing Analysis
Short lead-time premiums apply to Swiss-manufactured botulinum toxin and hyaluronic acid filler shipments, while spot inventory discounts emerge for near-expiry biologic lots. Three-tier pricing structure across premium, standard, and economy levels separates BfArM-certified dermatology clinics from medical spa chains and home-use device segments. Cost compression in chemical peel formulations is intensifying because REACH-constrained ingredient sourcing limits formulation flexibility. Home users show highest price sensitivity; certified clinic networks demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and French biologics manufacturing for botulinum toxin and hyaluronic acid filler active pharmaceutical ingredients. German distributors draw from Swiss neurotoxin production clusters, French filler compound facilities, and Israeli energy-based device manufacturing centers. Cross-border regulatory friction poses structural risk for just-in-time biologics replenishment. Distribution runs through BfArM-licensed wholesale channels into certified clinic networks and direct-to-spa relationships for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR compliance costs force sub-scale device manufacturers and uncertified clinic operators toward exit. BfArM-mandated training infrastructure investments favor capitalized incumbents capable of absorbing fixed certification costs.
For Market Incumbents: Acquire practitioner training certification networks to lock in captive demand for injectable portfolios. Defensive consolidation requires backward integration into biologics distribution infrastructure to offset Swiss-French supply concentration risk. Threat substitution from AI-assisted diagnostic platforms demands counter-investment in outcome documentation software companion development. For New Entrants and Emerging Players: Begin with Bavarian satellite clinic expansion in Augsburg and Nuremberg, where Munich density benchmarks reveal underpenetrated corridors. White-space capture targets male-identifying consultation segments in Hamburg and Frankfurt through digital-native acquisition channels. Go-to-market angle centers on subscription-based maintenance contracts displacing per-procedure pricing in Berlin medical spa chains. For Investors and Strategic Acquirers: BfArM guidance expansion on combination product classifications is the leading indicator that reclassification risk will trigger distressed asset availability. Long-term viability across the projection horizon favors vertically integrated platforms spanning biologics, devices, and certification networks. Acquisition target archetype: mid-cap specialists with captive practitioner training infrastructure. Signal to watch: GDPR enforcement actions compressing diagnostic platform vendor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Network Acquisition | Locks in captive demand for Galderma and Merz Pharma injectables portfolios. |
| AI Diagnostic Platform Development | Enables GDPR-compliant outcome documentation for Berlin and Munich clinic operators. |
| Backward Integration into Biologics Distribution | Reduces cross-border friction from Swiss and French manufacturing concentration. |
| Bavarian Satellite Clinic Expansion | Captures underpenetrated Augsburg and Nuremberg corridors relative to density benchmarks. |
| Subscription Pricing Model Deployment | Aligns with 25-34 age cohort preference for predictable monthly outlays over lump-sum investments. |
Research Methodology
Multi-period observation of BfArM certification tier expansion, EU MDR implementation timelines, and medical spa chain subscription adoption anchored the trend analysis, supplemented by interviews with dermatology clinic operators, medical spa franchise directors, aesthetic device procurement managers, and biologics distribution specialists. Secondary validation drew from BfArM guidance documents, EU MDR implementation notices, REACH chemical restriction updates, and German data protection authority enforcement records. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Input-output matrices modeled relationships between practitioner certification stocks, device installation bases, and biologics consumption rates across the projection horizon. Segmentation dimensions included procedure type, end-user channel, gender cohort, and age bracket. CAGRs derived from logistic diffusion curves fitted to subscription model adoption patterns and male-identifying consultation growth trajectories. Forecast inputs incorporated BfArM training capacity constraints and GDPR compliance cost trajectories for AI-assisted diagnostic platforms.
Underlying measurement precision varies by segment; dermatology clinic procedure volumes carry tighter precision than home-use device estimates due to BfArM reporting requirements. Forecasts reflect assumptions regarding EU MDR enforcement consistency, REACH chemical restriction stability, and male-identifying demand expansion sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Cosmetic Threads Market