
 Photoelectric Medical Beauty Equipment Market | 2026-2036
Photoelectric Medical Beauty Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Photoelectric Medical Beauty Equipment Market Insights
The price-performance boundary between premium photoelectric systems and commodity alternatives is hardening. Alma Lasers leverages its multi-platform architecture to sustain margins in high-end dermatology suites. Candela Medical competes through specialized vascular and pigmentation platforms that dominate hospital-affiliated practices.
Photoelectric medical beauty equipment encompasses devices that generate controlled light, radiofrequency, or ultrasound energy for non-invasive or minimally invasive aesthetic procedures, typically operating at wavelengths from 400 nm to 10,600 nm depending on target chromophore and clinical objective. These systems serve dermatologists, plastic surgeons, and licensed aestheticians seeking reproducible tissue effects without surgical intervention. Laser devices anchor the highest-margin segment due to capital intensity and consumable attachment revenue, while LED devices extend access to lower-budget spa operators and home users. Intense pulsed light platforms occupy a mature position with established reimbursement codes in several markets, whereas fractional laser systems lead growth in skin resurfacing applications.
FDA 510(k) clearance requirements shape product development timelines and clinical validation costs for manufacturers targeting the United States. The EU Medical Device Regulation and CE marking framework impose parallel conformity obligations across European markets, while China's NMPA oversees registration of imported laser and RF devices entering its aesthetic clinic networks. Stakeholders must monitor how divergent clinical evidence standards across these jurisdictions reshape portfolio prioritization and geographic launch sequencing.
Market Dynamics
Fractional laser systems and radiofrequency platforms are compressing treatment cycles from twelve sessions to three, forcing capital planning cycles in dermatology suites to accelerate from five-year to three-year horizons.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for laser and IPL systems reduce time-to-market for manufacturers targeting United States dermatology practices.
- LED Photomodulation:Lower-cost wavelength-specific devices expand addressable market to spa operators and home-use segments previously priced out of professional equipment.
- China's Aesthetic Clinic Density:Tier-1 and Tier-2 cities host concentrated networks of medical beauty chains driving platform procurement volume.
Market Restraints
- Consumable Attachment Economics:Handpiece and tip replacement costs for fractional CO₂ and erbium systems create recurring cost burdens that strain smaller practice budgets.
- Optical Component Supply Concentration:German and Japanese suppliers dominate precision lens and fiber manufacturing, exposing OEMs to single-source fragility.
- EU MDR Clinical Evidence Burden:Enhanced post-market surveillance and clinical data requirements for Class IIa and IIb laser devices extend registration timelines and validation costs.
Strategic Opportunities
- Brazil's Underpenetrated Aesthetic Market:ANVISA registration pathways for imported photoelectric devices remain less congested than United States or European queues.
- Combination Therapy Platforms:Integrated systems merging IPL with RF or ultrasound enable single-device workflows that reduce capital footprint per treatment room.
- Subscription-Based Equipment Access:Device-as-a-service models lower entry barriers for independent aesthetic practitioners in secondary United States markets.
Industry Challenges
- Laser Safety Officer Certification:State-level licensing variations in the United States create compliance complexity for multi-site clinic operators.
- Legacy IPL System Obsolescence:First-generation intense pulsed light platforms face parts scarcity and service discontinuation, forcing premature replacement decisions.
- Interoperability with EMR Systems:Treatment parameter logging and photographic documentation integration require custom API development for major dermatology software suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoelectric Medical Beauty Equipment Market |
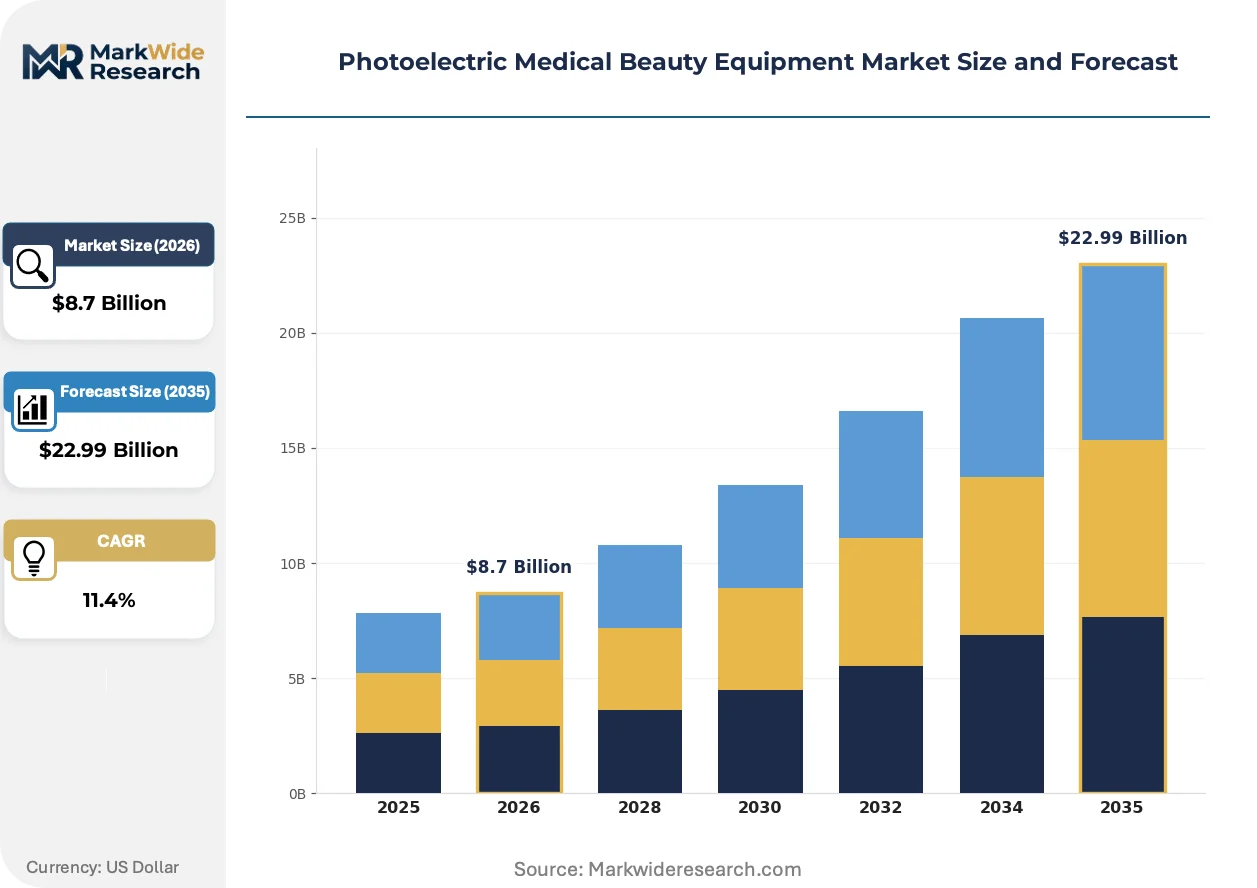
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, LED Devices, Radiofrequency Devices, Ultrasound Machines Application: Skin Rejuvenation, Hair Removal, Acne Treatment, Pigmentation Removal End User: Beauty Clinics, Dermatology Practices, Spas, Home Users Technology: Intense Pulsed Light, Fractional Laser, Non-ablative Laser, Pulsed Electromagnetic Field |
| Companies Covered | Alma Lasers, Sciton, Candela Medical, Venus Concept, Solta Medical, Lumenis, Fotona, Cutera, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoelectric Medical Beauty Equipment Market Trends and Innovations
Photoelectric medical beauty equipment is undergoing platform consolidation as multi-wavelength systems displace single-modality devices, while regulatory frameworks harden clinical evidence requirements and procurement models shift toward operational expenditure structures.
Picosecond laser technology is converging with adaptive optics for real-time beam profiling. High-volume dermatology chains in South Korea and the United States are replacing nanosecond Q-switched platforms at accelerated refresh cycles. This convergence is compressing price premiums for legacy tattoo removal and pigmentation systems while expanding addressable indications into melasma and difficult-to-treat dermal chromophores.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic clinical follow-up for high-energy laser systems. Manufacturers must maintain post-market clinical follow-up registries that track adverse events across the device lifecycle. Hospital-affiliated dermatology departments in Germany and France are prioritizing suppliers with established PMCF infrastructures, disadvantaging smaller OEMs without European regulatory affairs scale.
Buying committees in large aesthetic clinic networks now evaluate total cost of ownership over equipment lifespan rather than upfront capital expenditure. United States-based dermatology management organizations are unbundling service contracts from hardware procurement, selecting third-party field service providers for maintenance coverage. This behavioral shift is most pronounced in Texas and Florida, where rapid clinic rollouts demand flexible financing structures and rapid technician dispatch capabilities.
Photoelectric Medical Beauty Equipment Market Segmentation
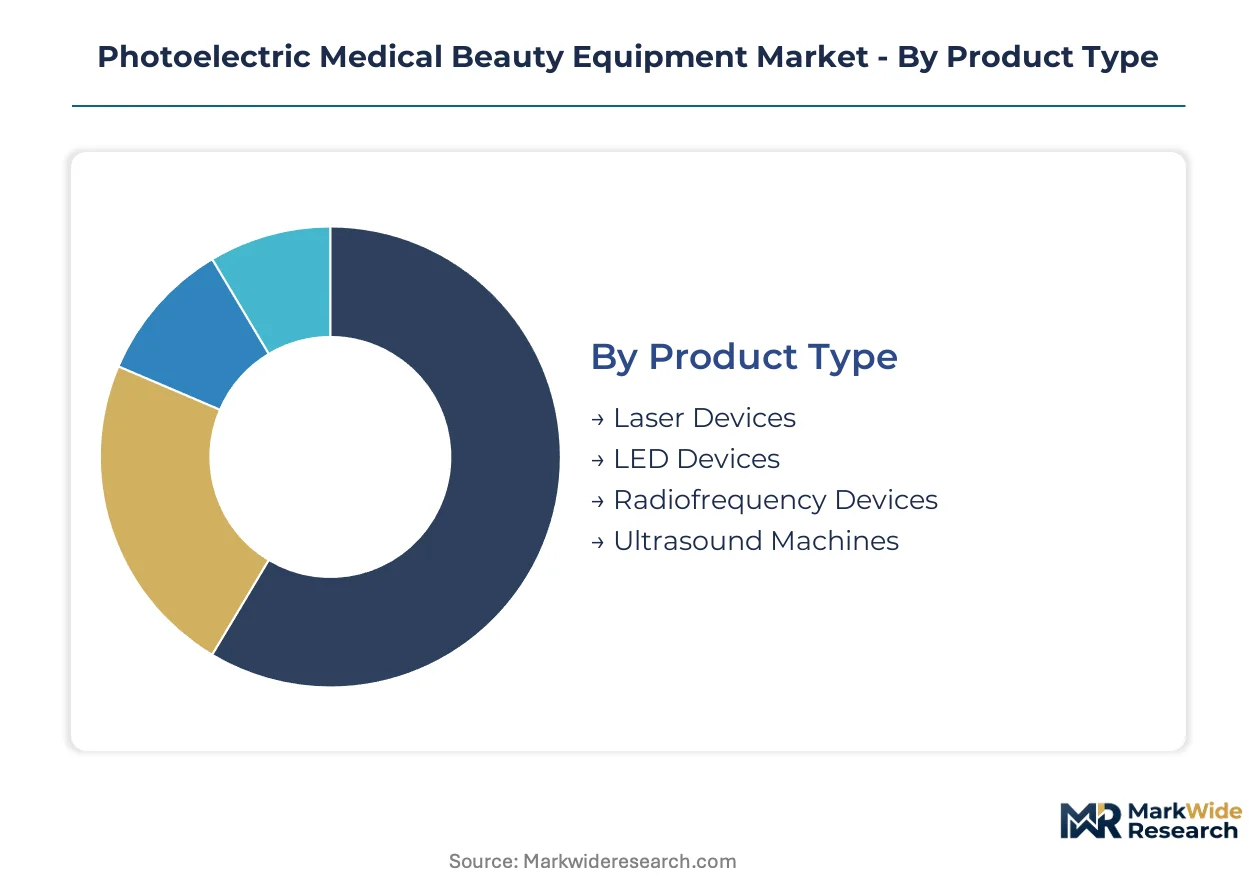
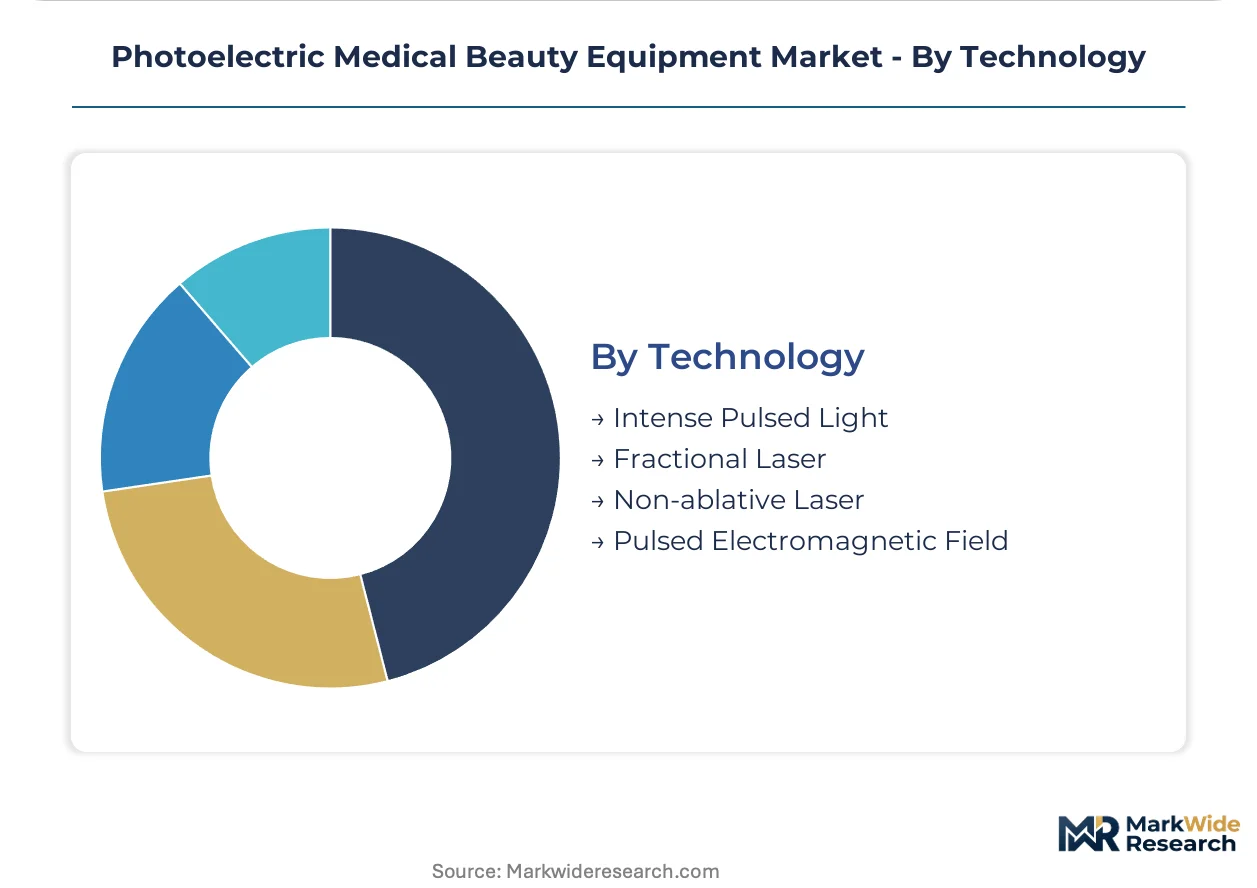
Photoelectric medical beauty equipment segments diverge sharply by capital intensity, regulatory pathway, and operator skill requirements. Buyers select platforms based on reimbursement eligibility, treatment throughput targets, and consumable revenue models rather than hardware specifications alone.
Product Type:
Capital deployment thresholds and consumable attachment economics separate buyers across product categories.
- Laser Devices:These systems generate coherent monochromatic light through stimulated emission, typically operating at 532 nm to 10,600 nm wavelengths for precise chromophore targeting. Dermatology practices in South Korea and the United States concentrate procurement here, driven by reimbursement codes for vascular lesions and high-margin consumable handpieces that sustain recurring revenue streams.
- Radiofrequency Devices:RF platforms deliver thermal energy through tissue impedance at 0.3–40 MHz frequencies, enabling non-ablative collagen remodeling without epidermal disruption. Demand clusters in China's Tier-1 aesthetic chains seeking combination therapy workflows that reduce per-treatment-room capital footprint while maintaining procedure pricing power.
- LED Devices:Lower-cost photomodulation systems utilizing 415 nm to 850 nm wavelength arrays for superficial inflammatory conditions.
- Ultrasound Machines:Microfocused ultrasound platforms generating thermal coagulation points at 4 MHz and 7 MHz depths for lifting applications.
Volume sits with Laser Devices; growth tilts toward Radiofrequency Devices.
Application:
Clinical outcome durability and treatment session frequency determine platform selection across aesthetic indications.
- Skin Rejuvenation:Fractional and non-ablative modalities targeting photodamage, rhytides, and textural irregularities through controlled thermal injury and collagen neogenesis. United States dermatology management organizations prioritize these platforms for patient retention programs, as maintenance schedules generate predictable recurring appointment volume.
- Hair Removal:Diode laser and IPL systems operating at 755 nm to 1064 nm wavelengths for permanent follicular reduction through selective photothermolysis. Demand concentrates in Saudi Arabia and the UAE, where cultural preferences and climate conditions drive year-round aesthetic service utilization.
- Acne Treatment:Blue light phototherapy and photodynamic therapy platforms addressing Cutibacterium acnes proliferation.
- Pigmentation Removal:Q-switched and picosecond laser systems targeting melanin-based lesions.
Hair Removal captures installed base volume; Skin Rejuvenation is climbing the fastest.
End User:
Regulatory licensing requirements and clinical oversight obligations fragment the buyer landscape.
- Dermatology Practices:Physician-supervised clinics with FDA 510(k) clearance requirements and malpractice insurance constraints. These buyers concentrate in Germany and France, where EU MDR post-market surveillance obligations favor established OEMs with PMCF infrastructure.
- Beauty Clinics:Medical aesthetic chains operating under national healthcare regulations with licensed practitioner requirements. China's dense network of Tier-1 and Tier-2 city chains drives platform procurement volume through standardized device fleets.
- Spas:Wellness facilities utilizing lower-energy LED and IPL systems with reduced regulatory burden.
- Home Users:Consumer-grade devices with simplified safety interlocks and reduced energy outputs.
Dermatology Practices anchor premium pricing; Beauty Clinics are expanding most quickly.
Technology:
Energy delivery mechanisms and tissue interaction physics determine clinical versatility and capital efficiency.
- Fractional Laser:Microbeam array technology creating microscopic treatment zones with intact surrounding tissue for rapid re-epithelialization. South Korean high-volume chains are accelerating refresh cycles from nanosecond to picosecond platforms, compressing legacy system resale values while expanding melasma and recalcitrant dermal pigment indications.
- Intense Pulsed Light:Broadband filtered flashlamp systems delivering 500–1200 nm wavelengths for multiple chromophore targeting. Established reimbursement codes in several markets sustain mature demand, though first-generation platforms face parts scarcity forcing premature replacement decisions.
- Non-ablative Laser:Mid-infrared and long-pulsed systems generating dermal heating without epidermal disruption.
- Pulsed Electromagnetic Field:Low-frequency energy delivery for tissue regeneration and pain modulation applications.
Intense Pulsed Light holds installed base dominance; Fractional Laser shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the densest concentration of high-volume aesthetic chains driving platform procurement, with South Korean dermatology groups accelerating refresh cycles from nanosecond to picosecond laser systems. This metropolitan cluster compresses global pricing benchmarks while expanding indications into recalcitrant dermal pigments.
United States
Dermatology management organizations in Texas and Florida unbundle service contracts from hardware procurement, selecting third-party field service providers for maintenance coverage. FDA 510(k) clearance pathways streamline market entry for laser and IPL manufacturers targeting hospital-affiliated practices. The Dallas-Fort Worth corridor hosts rapid clinic rollouts demanding flexible financing structures and rapid technician dispatch capabilities.
Germany
Hospital-affiliated dermatology departments prioritize suppliers with established post-market clinical follow-up infrastructures under EU MDR obligations. The EU Medical Device Regulation mandates systematic clinical follow-up for high-energy laser systems, disadvantaging smaller OEMs without European regulatory affairs scale. The Rhine-Ruhr metropolitan region concentrates procurement committees evaluating total cost of ownership over equipment lifespan.
China
Tier-1 and Tier-2 cities host dense networks of medical beauty chains driving platform procurement volume through standardized device fleets. NMPA registration requirements govern imported laser and RF devices entering aesthetic clinic networks. The Yangtze River Delta corridor concentrates demand for combination therapy platforms merging IPL with radiofrequency.
Brazil
ANVISA registration pathways for imported photoelectric devices remain less congested than United States or European queues, attracting manufacturers seeking faster market entry. Independent aesthetic practitioners in São Paulo and Rio de Janeiro drive demand for subscription-based equipment access models. The Southeast region's underpenetrated aesthetic market offers expansion opportunities for fractional laser and radiofrequency platforms.
United Arab Emirates
Cultural preferences and climate conditions in Dubai and Abu Dhabi drive year-round aesthetic service utilization concentrated in hair removal applications. MOHAP oversight governs medical device registration while maintaining alignment with international standards. The Dubai Healthcare City cluster imports high-margin laser systems serving Gulf Cooperation Council medical tourists seeking premium dermatology services.
Photoelectric Medical Beauty Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the capital intensity and consumable attachment revenue dimensions, with laser device manufacturers commanding superior returns through recurring handpiece replacement economics. The vendor base structures into three tiers: multi-platform architecture specialists sustaining margins in high-end dermatology suites, vascular and pigmentation platform specialists dominating hospital-affiliated practices, and LED device commoditizers extending access to lower-budget spa operators. Dominant competitive moves include geographic expansion into Brazil's underpenetrated aesthetic market and portfolio diversification toward combination therapy platforms integrating multiple energy modalities.
Within the multi-platform architecture tier, Alma Lasers represents premium-tier positioning through capital-intensive system design, while Candela Medical exemplifies specialization in vascular and pigmentation applications. Lumenis occupies a position spanning both premium laser systems and established IPL platforms with mature reimbursement codes. These three anchors demonstrate how regulatory scale—particularly EU MDR post-market surveillance infrastructure—separates sustainable competitors from constrained challengers.
| Leading Market Players |
|---|
| Alma Lasers |
| Sciton |
| Candela Medical |
| Venus Concept |
| Solta Medical |
| Lumenis |
| Fotona |
| Cutera |
| Cynosure |
| Others |
Pricing and Supply Chain Analysis
Precision optical components from German and Japanese suppliers feed through three distinct pricing tiers before reaching end-users, with lens and fiber manufacturing concentration upstream dictating margin capture downstream across dermatology suites, aesthetic chains, and spa operators.
Pricing Analysis
Outcome-based pricing anchored to treatment throughput per session dominates procurement decisions, with fractional laser platforms commanding premium positioning through consumable handpiece attachment economics. Price differentiation separates FDA 510(k)-cleared systems from CE-marked alternatives, while volume scale discounts compress margins for LED photomodulation devices. Pricing pressure stems from accelerated refresh cycles compressing equipment depreciation schedules. Independent aesthetic practitioners in secondary United States markets exhibit highest price sensitivity; hospital-affiliated dermatology departments in Germany and France demonstrate lowest sensitivity due to total cost of ownership evaluation frameworks.
Supply Chain Analysis
Specialized optical engineering talent scarcity in Stuttgart and Yokohama manufacturing corridors constrains expansion velocity for precision lens and fiber production capacity. Supply concentration rests on Germany and Japan for optical-grade sapphire and fused silica components, with China providing downstream assembly and RF generator subsystems. Raw material dependencies include rare-earth doped fibers, precision aspheric lenses, and high-voltage capacitors. Single-source vulnerability in erbium-doped fiber amplifiers creates procurement risk. Distribution runs through authorized device distributors serving hospital systems and direct sales teams penetrating high-volume aesthetic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Picosecond laser platforms are displacing nanosecond Q-switched systems across pigmentation and tattoo removal applications, compressing legacy equipment residual values while expanding treatable indications into recalcitrant dermal chromophores.
For Market Incumbents: Anchor market position through backward integration into precision optical component manufacturing, securing captive supply of German and Japanese-sourced fibers and lenses against single-source fragility. Accelerate post-market clinical follow-up infrastructure investment to satisfy EU MDR surveillance obligations, disadvantaging smaller OEMs lacking European regulatory affairs scale. Defend against subscription-based equipment access models by unbundling service contracts and partnering with third-party field service providers for rapid technician dispatch capabilities in high-growth United States corridors. For New Entrants and Emerging Players: Launch via subscription-based device-as-a-service models targeting independent aesthetic practitioners in Brazil's Southeast region, where ANVISA registration pathways remain less congested than United States or European queues. Prioritize combination therapy platforms merging IPL with radiofrequency to reduce per-treatment-room capital footprint for China's Tier-1 aesthetic chains. White-space concentration exists in LED photomodulation for home-use segments previously priced out of professional equipment markets. For Investors and Strategic Acquirers: Accelerated refresh cycles from nanosecond to picosecond platforms in South Korean high-volume chains is the leading indicator that technology transition velocity is compressing equipment lifecycles and resale values. Long-term viability over a multi-year horizon favors OEMs with established multi-platform architectures and recurring consumable revenue streams. Target acquisition profiles center on mid-tier laser device manufacturers with FDA 510(k) clearance portfolios but underdeveloped EU MDR post-market surveillance infrastructure, where regulatory investment unlocks European hospital-affiliated practice access.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Surveillance Infrastructure Buildout | Hospital-affiliated dermatology departments in Germany and France prioritize suppliers with established PMCF registries. |
| Combination Therapy Platform Development | Integrated IPL-RF-ultrasound systems reduce capital footprint per treatment room for China's aesthetic chains. |
| Subscription-Based Equipment Access Model | Device-as-a-service lowers entry barriers for independent practitioners in Brazil's underpenetrated Southeast region. |
| Precision Optical Component Backward Integration | Captive supply of German and Japanese-sourced fibers mitigates single-source vulnerability in erbium-doped amplifiers. |
| Third-Party Field Service Network Partnership | Unbundled maintenance coverage enables rapid technician dispatch for Texas and Florida clinic rollouts. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and NMPA registration databases formed the secondary backbone for device approval pathway analysis, supplemented by customs records tracking photoelectric equipment trade flows. Primary interviews with dermatology clinic purchasing committees, biomedical engineers at hospital-affiliated practices, and regulatory affairs directors at laser device manufacturers validated secondary findings. Bottom-up and top-down triangulation cross-checked installed base estimates against procurement volume data from aesthetic chain networks.
Bottom-up modeling aggregated procedure volume assumptions by application and technology type, while top-down validation anchored aggregate market size against capital expenditure disclosures from publicly traded dermatology management organizations. Segmentation dimensions spanned product type, application, end user, and technology across the projection horizon. CAGRs derived from weighted average of historical equipment refresh cycles and forward-looking regulatory pathway timelines. Industry-specific forecast inputs included picosecond platform adoption curves and LED photomodulation penetration into home-use segments.
Regulatory pathway delays, optical component supply disruptions, and accelerated technology obsolescence are the dominant revision risks that could compress or extend market expansion trajectories. Forecasts reflect assumptions about clearance timeline standardization and consumable attachment revenue sustainability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Lip Filler Market