
 Laser Scar Removal Market | 2026-2036
Laser Scar Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Scar Removal Market Insights
Software-defined treatment protocols and subscription-based laser platform upgrades are pivoting how manufacturers monetize hardware deployments. Lumenis Ltd. leverages its installed base of CO2 and fractional systems to sustain recurring revenue through proprietary software modules. Candela Medical differentiates through integrated cooling technologies that anchor premium positioning across dermatology networks. Alma Lasers Ltd. competes by bundling training and maintenance into long-term service contracts.
Laser scar removal employs concentrated light energy at specific wavelengths to ablate or remodel dermal collagen, with fractional systems delivering microbeams at 1550 nm or 2940 nm to create controlled thermal injury zones while sparing surrounding tissue. The primary commercial purpose is aesthetic improvement of hypertrophic, atrophic, and contracture scars through collagen neogenesis and epidermal resurfacing. CO2 laser and fractional laser platforms command the largest installed base, though pulsed dye laser systems lead vascular scar indications where hemoglobin-selective absorption matters. Medical spas and specialized clinics represent the fastest-growing end user channel as capital-light leasing models expand access to advanced platforms.
FDA 510(k) premarket notification requirements govern laser device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa and IIb aesthetic lasers entering European markets. ISO 13485 quality management certification has become a baseline procurement filter for hospital systems evaluating multi-specialty laser investments. Stakeholders must monitor how evolving energy-based device classification in major jurisdictions reshapes compliance costs and time-to-market for next-generation scar revision platforms.
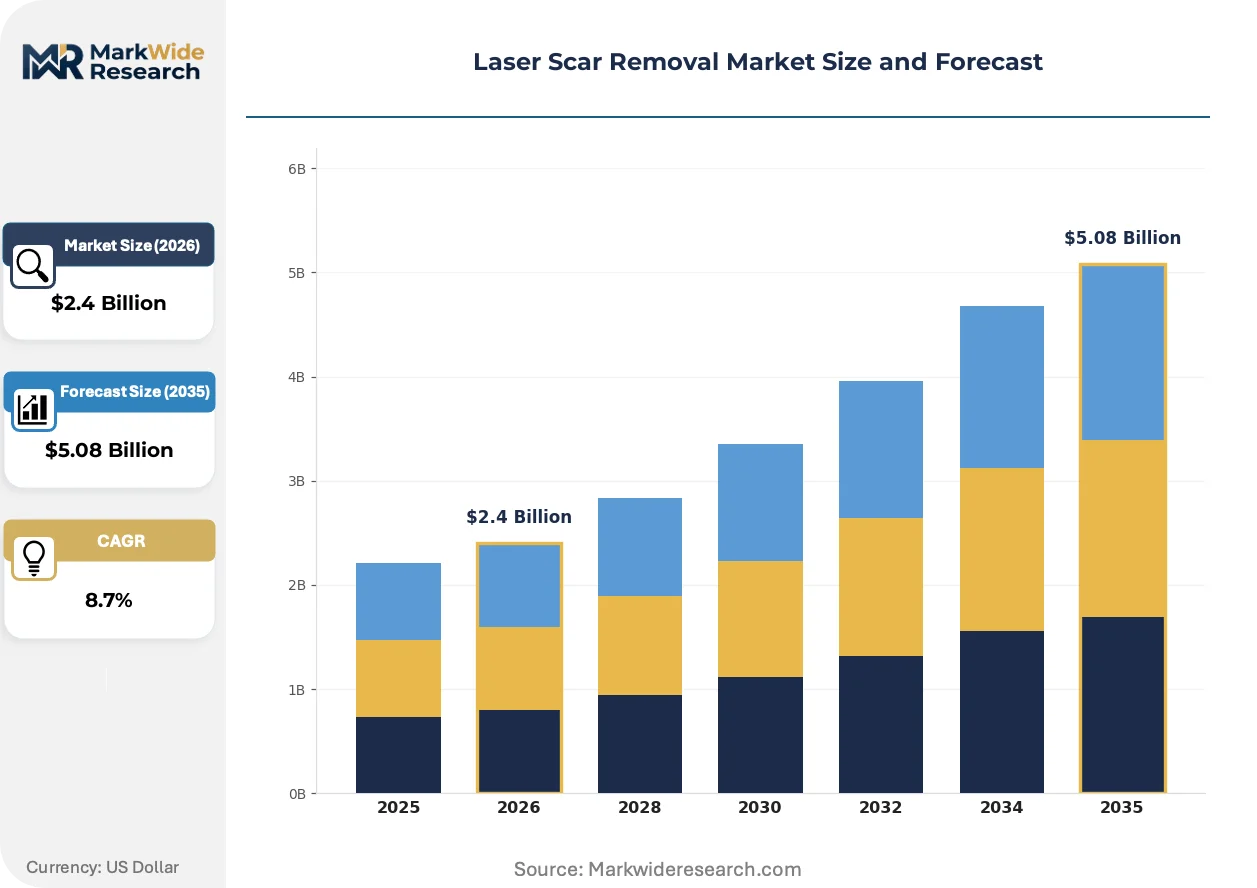
Market Dynamics
Fractional laser technology is forcing dermatology clinics and medical spas to reconfigure capital deployment strategies around wavelength modularity and software-defined treatment protocols.
Growth Catalysts
- Outpatient preference shift:Patients increasingly select ambulatory scar revision over surgical alternatives, expanding addressable procedures for CO2 and erbium platforms across United States dermatology networks.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for aesthetic laser modifications accelerates feature rollouts, enabling manufacturers to iterate fractional beam delivery algorithms without full PMA submissions.
- Collagen neogenesis protocols:Evidence-based microbeam spacing techniques at 1550 nm and 2940 nm wavelengths are standardizing treatment outcomes, reducing operator variability in hypertrophic scar management.
Market Restraints
- Capital intensity barriers:Multi-platform laser suites require $150,000-$400,000 upfront investment, constraining independent clinic adoption relative to consolidated dermatology groups.
- Er:YAG crystal supply concentration:High-purity laser rod manufacturing concentrates among specialized optical material suppliers in Germany and Japan, creating input vulnerability for 2940 nm system producers.
- EU MDR clinical evidence requirements:Class IIb aesthetic laser reclassification demands expanded biocompatibility and clinical performance documentation, extending European market entry timelines.
Strategic Opportunities
- Medical spa channel expansion:Capital-light leasing models from Alma Lasers and Candela Medical are penetrating non-physician supervised settings in Texas and Florida where supervision regulations permit.
- Combination therapy protocols:Pulsed dye laser integration with fractional resurfacing for vascularized scars creates bundled procedure revenue streams in academic dermatology centers.
- Subscription software monetization:Proprietary treatment parameter libraries and automated beam-pattern algorithms offer recurring revenue attachment to installed CO2 and fractional hardware bases.
Industry Challenges
- Laser safety officer certification gaps:State-level training requirements for Class IV laser operation vary widely, creating compliance complexity for multi-state clinic operators.
- Legacy system integration friction:Older CO2 platforms lack digital interface compatibility with modern practice management software, complicating workflow unification in acquired clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Scar Removal Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Pulsed Dye Laser, Erbium Laser, Fractional Laser Application: Acne Scars, Surgical Scars, Burn Scars, Stretch Marks End User: Clinics, Hospitals, Home Care, Medical Spas Delivery Mode: Non-Invasive, Minimally Invasive, Invasive, Others |
| Companies Covered | Lumenis Ltd., Cynosure, Inc., Alma Lasers Ltd., Candela Medical, Cutera, Inc., Fotona d.o.o., El.En. S.p.A., Merz Pharma, Solta Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Scar Removal Market Trends and Innovations
Energy-based scar revision is pivoting toward intelligent automation and hybrid wavelength platforms that compress treatment sessions while expanding treatable scar phenotypes.
Picosecond laser technology is converging with fractional delivery architectures to address post-inflammatory hyperpigmentation alongside textural scar remodeling. Medical spas in California and New York are piloting these dual-modality systems for acne scar protocols. The convergence is compressing per-procedure revenue capture while expanding total addressable patient populations beyond traditional resurfacing candidates.
EU MDR implementation is reshaping clinical evidence requirements for Class IIa and IIb aesthetic lasers entering European markets. Manufacturers must now submit expanded biocompatibility testing and post-market surveillance plans alongside technical documentation. German and French notified bodies are processing submissions most aggressively, creating regulatory arbitrage opportunities for early MDR-compliant platform launches.
Leasing structures are displacing outright purchase as the dominant acquisition model for mid-cap dermatology groups. Third-party equipment finance firms now underwrite laser platform deployments based on procedure volume commitments rather than balance sheet strength. This shift is most visible in United States Sun Belt markets where medical spa formation rates exceed national averages.
Laser Scar Removal Market Segmentation
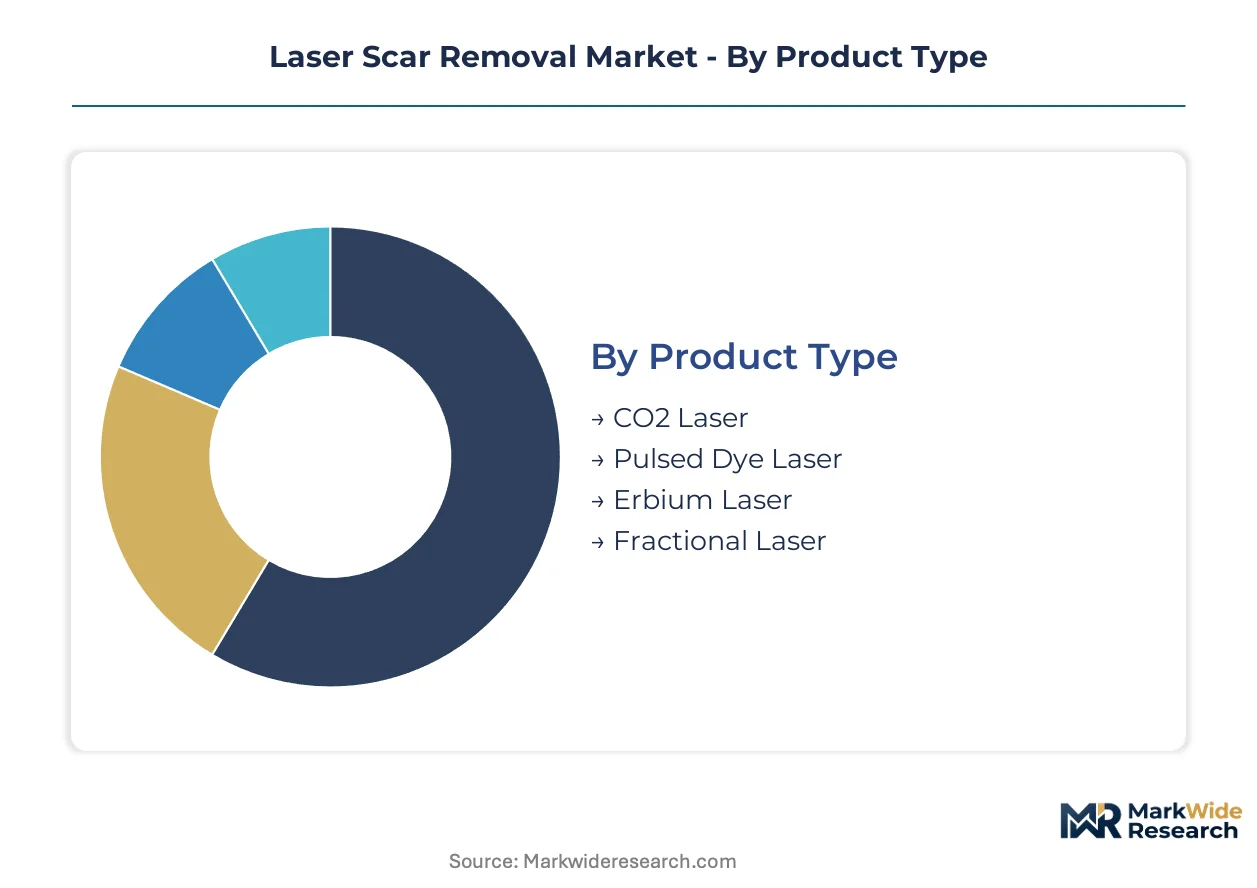
Laser scar removal equipment segments by wavelength technology, scar pathology, and care setting, each carrying distinct capital requirements and reimbursement profiles. Understanding these divisions clarifies where manufacturers concentrate R&D investment versus where service providers deploy capital.
Product Type:
Standalone laser platforms dominate high-volume dermatology networks, while modular systems integrate into multi-service aesthetic suites for operational flexibility.
- CO2 Laser:Ablative systems at 10,600 nm vaporize epidermal tissue with controlled thermal diffusion into the dermis. Demand concentrates in United States academic dermatology centers where deep resurfacing protocols for contracture scars justify capital intensity and extended recovery protocols.
- Fractional Laser:Microbeam delivery at 1550 nm or 2940 nm creates microscopic treatment zones while sparing intervening tissue, accelerating re-epithelialization. Medical spa chains in Texas and Florida favor these systems for reduced downtime and expanded treatment candidacy.
- Pulsed Dye Laser:585-595 nm wavelength selectively targets hemoglobin in vascularized scars. Pediatric burn centers and scar management clinics deploy these for erythematous hypertrophic indications.
- Erbium Laser:Er:YAG systems at 2940 nm offer more precise tissue ablation with less thermal collateral than CO2 platforms. Precision-focused dermatology practices in California and New York select these for periorbital and delicate anatomical zones.
Volume placements concentrate in CO2 and fractional platforms; the faster expansion belongs to fractional systems as outpatient settings prioritize reduced downtime protocols.
Application:
Scar etiology determines wavelength selection, treatment depth, and session count, creating procedure-specific equipment configurations across clinical settings.
- Acne Scars:Atrophic and boxcar morphologies drive demand for fractional resurfacing combined with subcision techniques. United States medical spas report highest procedure frequency for this indication among patients aged 25-40.
- Surgical Scars:Hypertrophic and keloid formations require combination protocols of pulsed dye laser for vascularity plus fractional remodeling for texture. Academic medical centers in Boston and Philadelphia publish extensively on multimodal approaches.
- Burn Scars:Contracture management demands ablative CO2 or erbium platforms with aggressive parameters. Specialized burn centers in Galveston, Texas and Cincinnati, Ohio maintain dedicated laser suites for this severe indication.
- Stretch Marks:Striae distensae respond to non-ablative fractional delivery with limited evidence base. Aesthetic clinics in Los Angeles and Miami market these treatments despite variable reimbursement.
Procedure volume clusters around acne scar revision; stretch mark treatments are gaining share fastest as non-physician supervised settings expand service menus.
End User:
Capital deployment and supervision requirements fragment the customer base across physician-led and non-physician supervised care models with diverging regulatory constraints.
- Clinics:Dermatology and plastic surgery practices represent the core installed base for multi-platform laser investments. Consolidated groups in the United States leverage purchasing power for preferred pricing on fractional and CO2 suites.
- Medical Spas:Capital-light leasing models penetrate this channel where state regulations permit non-physician operation. Florida and Texas lead formation rates for these facilities.
- Hospitals:Academic medical centers and burn units maintain specialized laser capabilities for complex scar reconstruction. These settings prioritize FDA 510(k) clearance documentation and training infrastructure.
- Home Care:Low-energy devices for consumer use occupy a peripheral market position with limited clinical efficacy data. Direct-to-consumer channels in California test this segment's viability.
Equipment placements concentrate in dermatology clinics; medical spas are expanding most quickly as supervision regulations evolve in Sun Belt states.
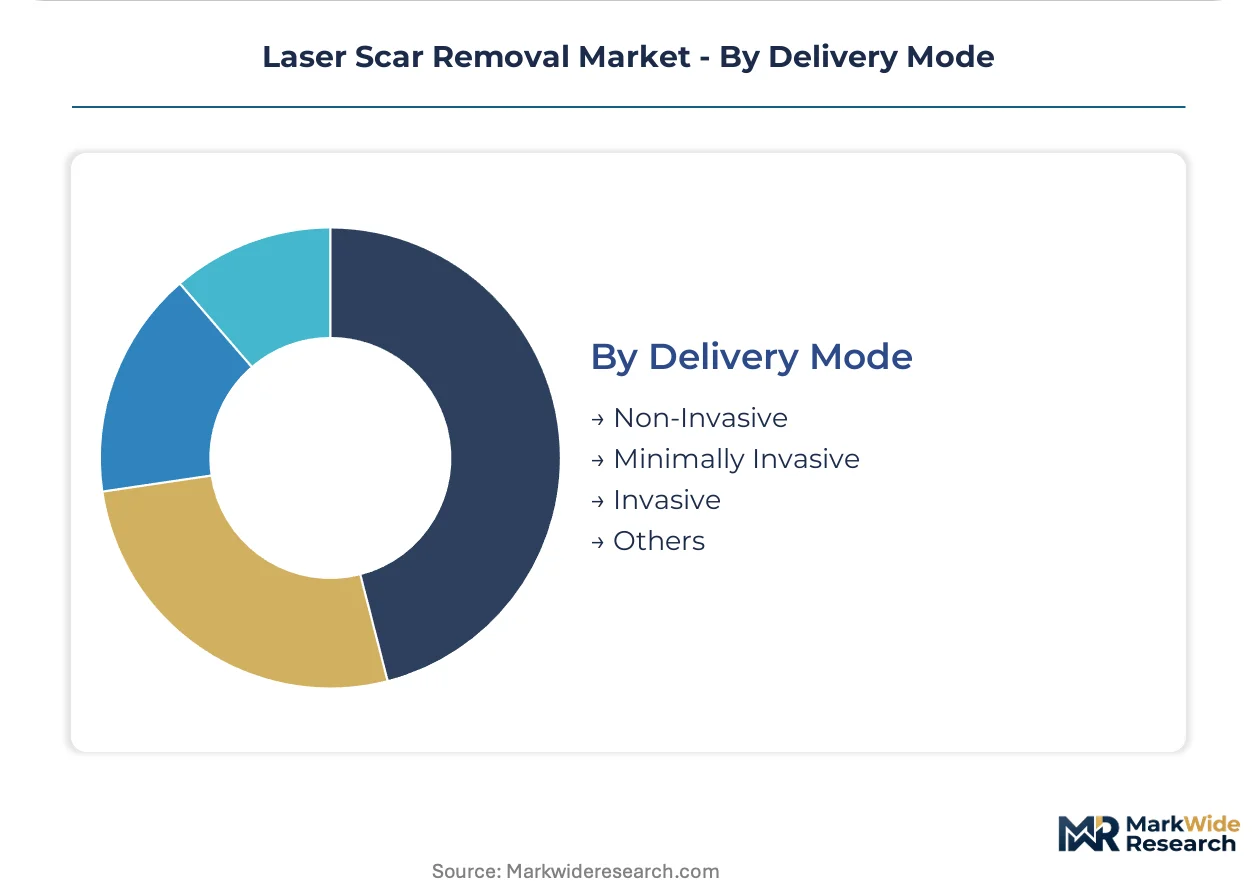
Delivery Mode:
Tissue interaction depth and recovery trajectory segment this category, with patient preference increasingly favoring modalities that minimize downtime without sacrificing efficacy.
- Non-Invasive:Surface-level energy delivery without epidermal disruption. United States medical spas emphasize these protocols for patient retention and scheduling density.
- Minimally Invasive:Fractional microbeam and controlled ablative approaches dominate current clinical practice. Dermatology networks standardize on these for risk-adjusted outcomes across operator experience levels.
- Invasive:Full-field ablative resurfacing reserved for severe scar phenotypes and specialized centers. Declining share reflects patient preference shifts and complication risk profiles.
- Others:Emerging hybrid modalities combining laser with mechanical or energy-based adjuncts. Academic centers in New York and California pilot these investigational approaches.
Procedure volume centers on minimally invasive delivery; non-invasive protocols are climbing fastest as medical spa channels prioritize zero-downtime marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American laser scar removal deployment through concentrated dermatology group expansion and medical spa formation along the Interstate 35 corridor.
United States
Medical spa chains in Texas and Florida drive fractional laser adoption through capital-light leasing structures. FDA 510(k) clearance pathways enable rapid platform iteration for manufacturers targeting outpatient settings. The Sun Belt corridor from Houston to Miami exhibits fastest equipment placement velocity among non-physician supervised channels.
Germany
Er:YAG crystal fabrication concentrates among specialized optical suppliers in Thuringia and Bavaria, creating upstream supply leverage for 2940 nm system producers. EU MDR notified bodies in Berlin and Munich process Class IIb aesthetic laser submissions with relative efficiency. The Rhine-Main manufacturing cluster around Frankfurt sustains precision optics capacity for medical laser rod production.
China
Domestic aesthetic device manufacturers in Shenzhen and Guangzhou capture mid-tier hospital procurement through price-competitive CO2 platforms. NMPA medical device registration timelines compress for Class II laser systems with predicate device pathways. The Yangtze River Delta corridor from Shanghai to Hangzhou concentrates private dermatology clinic formation driving fractional laser demand.
Japan
PMDA marketing approval requirements emphasize clinical evidence standards for energy-based scar revision devices entering Japanese markets. METI industrial policy supports domestic laser component manufacturing in Nagoya and Osaka industrial zones. Academic medical centers in Tokyo maintain specialized burn scar reconstruction capabilities with dedicated ablative laser suites.
United Kingdom
Private dermatology networks in London and Manchester consolidate purchasing for multi-platform laser investments. MHRA post-market surveillance requirements align with EU MDR transition timelines for aesthetic laser compliance. The Southeast England corridor exhibits highest medical aesthetic procedure density per capita among European markets.
Laser Scar Removal Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in laser scar removal equipment. Consolidated purchasing power among United States dermatology groups favors vendors with installed base scale and service infrastructure. Three archetypes dominate: wavelength-specialized platform developers, multi-modality aesthetic suite integrators, and component-integrated system manufacturers. Competitive moves center on software subscription attachment and third-party financing partnerships rather than hardware price competition alone.
Among Israeli platform developers, Lumenis Ltd. and Alma Lasers Ltd. occupy positions emphasizing recurring revenue through proprietary software modules and bundled service contracts. Candela Medical represents the integrated-cooling technology archetype within United States-based manufacturers. These three exemplify how geographic clustering in Tel Aviv and Boston shapes divergent approaches to dermatology network penetration.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Cynosure, Inc. |
| Alma Lasers Ltd. |
| Candela Medical |
| Cutera, Inc. |
| Fotona d.o.o. |
| El.En. S.p.A. |
| Merz Pharma |
| Solta Medical |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA 510(k)-cleared platforms and uncertified aftermarket systems manifests in both pricing stratification and supply chain qualification requirements. Premium-tier manufacturers command three-to-five-fold hardware premiums over commodity alternatives by anchoring procurement decisions on ISO 13485 quality management documentation and predicate device clinical histories.
Pricing Analysis
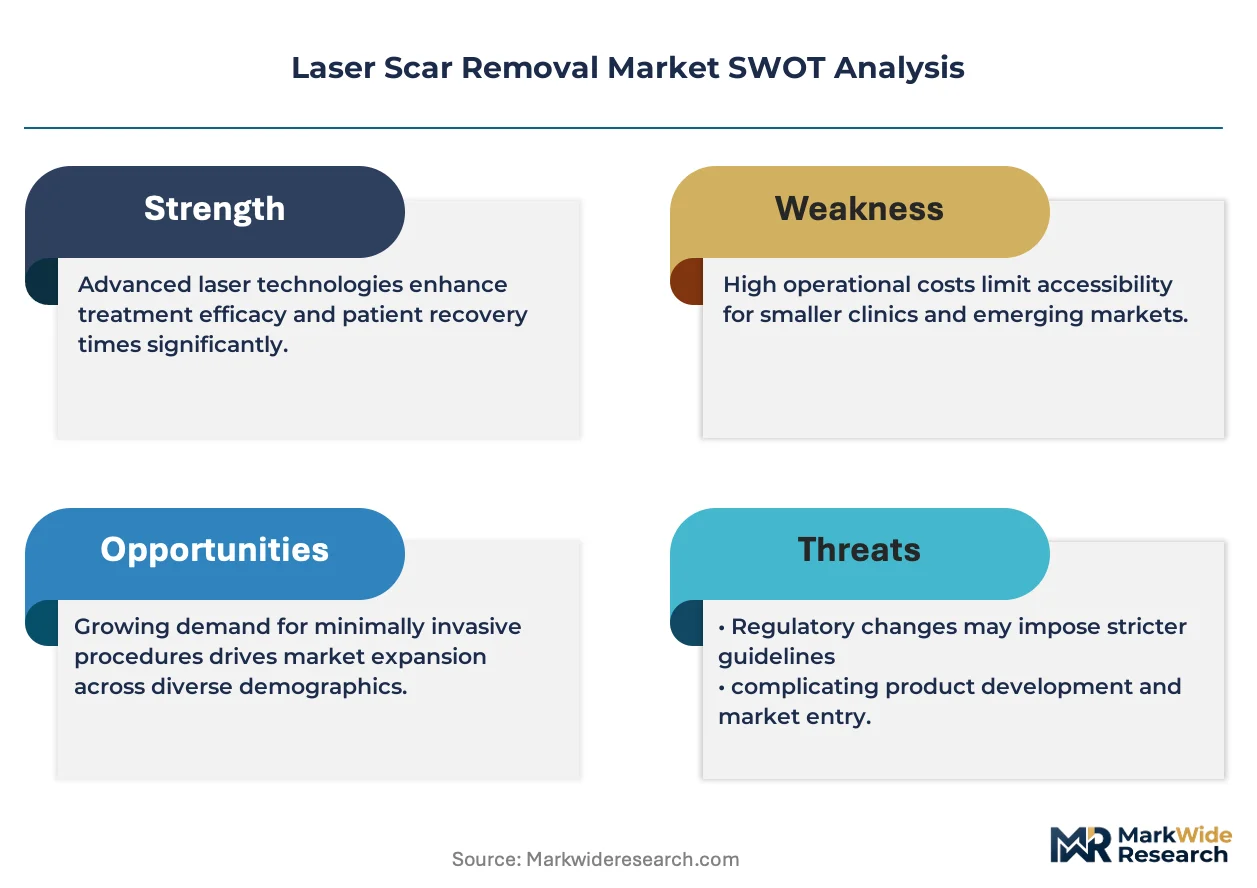
Margin tightening in mid-tier fractional laser systems reflects intensifying competition from Chinese OEMs penetrating Southeast Asian and Latin American markets. Three-tier pricing structure across premium, standard, and economy levels separates Lumenis and Candela installations bundled with proprietary software modules from stripped-down Asian platforms sold through distributor networks. Price differentiation hinges on FDA clearance tier and after-sales training infrastructure, with independent dermatology groups exhibiting highest price sensitivity and academic medical centers least sensitive due to grant-funded procurement.
Supply Chain Analysis
ISO 13485 certification gating restricts component sourcing to qualified optical material suppliers in Germany, Japan, and the United States. High-purity Er:YAG laser rods and CO2 gas discharge tubes constitute critical dependencies, with single-source vulnerability concentrated in Thuringia-based crystal growers and Nagoya precision optics houses. Tariff exposure on Japanese optical components feeds into downstream pricing. Distribution runs through authorized dealer networks serving hospital systems and direct sales teams for consolidated dermatology groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional laser technology is displacing legacy full-field ablative platforms as the dominant scar revision modality, compressing replacement cycles and reshaping capital allocation across dermatology networks.
For Market Incumbents: Cement installed base loyalty through subscription-locked software upgrades that raise switching costs for multi-platform operators facing emerging Chinese competitors with aggressive hardware pricing. Prioritize backward integration into Er:YAG crystal supply through strategic partnerships with Thuringia optical suppliers, insulating against input volatility that threatens 2940 nm system margins. For New Entrants and Emerging Players: Enter via medical spa channels in Texas and Florida where supervision regulations permit non-physician operation and capital-light leasing models lower barriers to platform adoption. Target acne scar protocols among patients aged 25-40, the fastest-expanding procedure category with limited incumbent software lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with Israeli platform developers possessing recurring revenue attachment through proprietary treatment parameter libraries, given FDA 510(k) pathway efficiency accelerates feature rollouts without full PMA submissions. Long-term viability hinges on software monetization depth rather than hardware shipment volume. Monitor EU MDR notified body processing speeds as inflection indicator for European market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates fractional beam algorithm iterations without PMA submissions. |
| Software Companion Development | Proprietary treatment libraries generate recurring revenue attachment to installed CO2 hardware bases. |
| Hospital System Partnership | Academic dermatology centers in Boston and Philadelphia anchor multimodal scar protocol validation. |
| CE Marking Pathway | EU MDR Class IIb compliance demands expanded biocompatibility documentation for European market entry. |
| Reimbursement Strategy | Outpatient scar revision coding alignment shapes purchasing committee evaluation of capital intensity. |
Research Methodology
Multi-period observation of FDA 510(k) submission volumes, dermatology clinic equipment placement announcements, and medical spa formation rates anchored the trend analysis, supplemented by interviews with biomedical engineers at academic medical centers, GPO contracts managers, and aesthetic device procurement leads at consolidated dermatology groups. Secondary validation drew from FDA 510(k) database filings, CMS Medicare procedure coding data, hospital procurement database records, and EU MDR notified body submission trackers. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment disclosures.
Input-output matrix modeling connected wavelength technology adoption curves to end-user capital deployment patterns across the projection horizon. Segmentation dimensions included laser platform type, scar pathology indication, delivery mode invasiveness, and care setting regulatory classification. CAGRs were derived from fitted adoption curves calibrated to historical replacement cycles and technology transition rates. Forecast inputs incorporated Er:YAG crystal supply constraints and state-level supervision regulation evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or abrupt changes in medical spa supervision statutes. Model outputs reflect assumptions on outpatient preference persistence and leasing model penetration rates. A model refresh is warranted upon material change in FDA device classification guidance or German optical component export licensing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market