
 Breast Reconstruction and Augmentation Market | 2026-2036
Breast Reconstruction and Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Reconstruction and Augmentation Market Analysis
Silicone gel is consolidating its position as the dominant filler material in breast implants, displacing earlier saline alternatives through superior tactile properties and reduced rippling. Establishment Labs leverages proprietary silicone technologies to differentiate its product portfolio across Latin American and European markets. Johnson & Johnson (Mentor) sustains manufacturing scale through vertically integrated production facilities in the United States and the Netherlands. Sientra specializes in exclusive silicone formulations distributed through board-certified plastic surgeon networks.
Breast reconstruction and augmentation encompasses surgical procedures and prosthetic devices designed to restore or enhance breast volume, employing silicone or saline-filled implants, tissue expanders, autologous tissue transfer, and fat grafting techniques with shell surfaces ranging from smooth to textured. The primary purpose spans oncologic reconstruction post-mastectomy, congenital anomaly correction, and aesthetic enhancement. Implants capture the dominant revenue share within product type segmentation, though fat grafting registers the fastest expansion as patients seek autologous alternatives. Reconstructive patients anchor volume demand through insurance-backed procedures, while aesthetic patients concentrate margin pools in elective cash-pay channels.
FDA oversight through premarket approval pathways and ongoing post-market surveillance studies shapes implant safety standards and manufacturer liability exposure in the United States. The EU Medical Device Regulation imposes enhanced clinical evidence requirements and unique device identification mandates that filter market access across European markets. Stakeholders must monitor evolving regulatory post-market study obligations and patient registry participation requirements as determinants of sustained commercial viability.
Market Dynamics
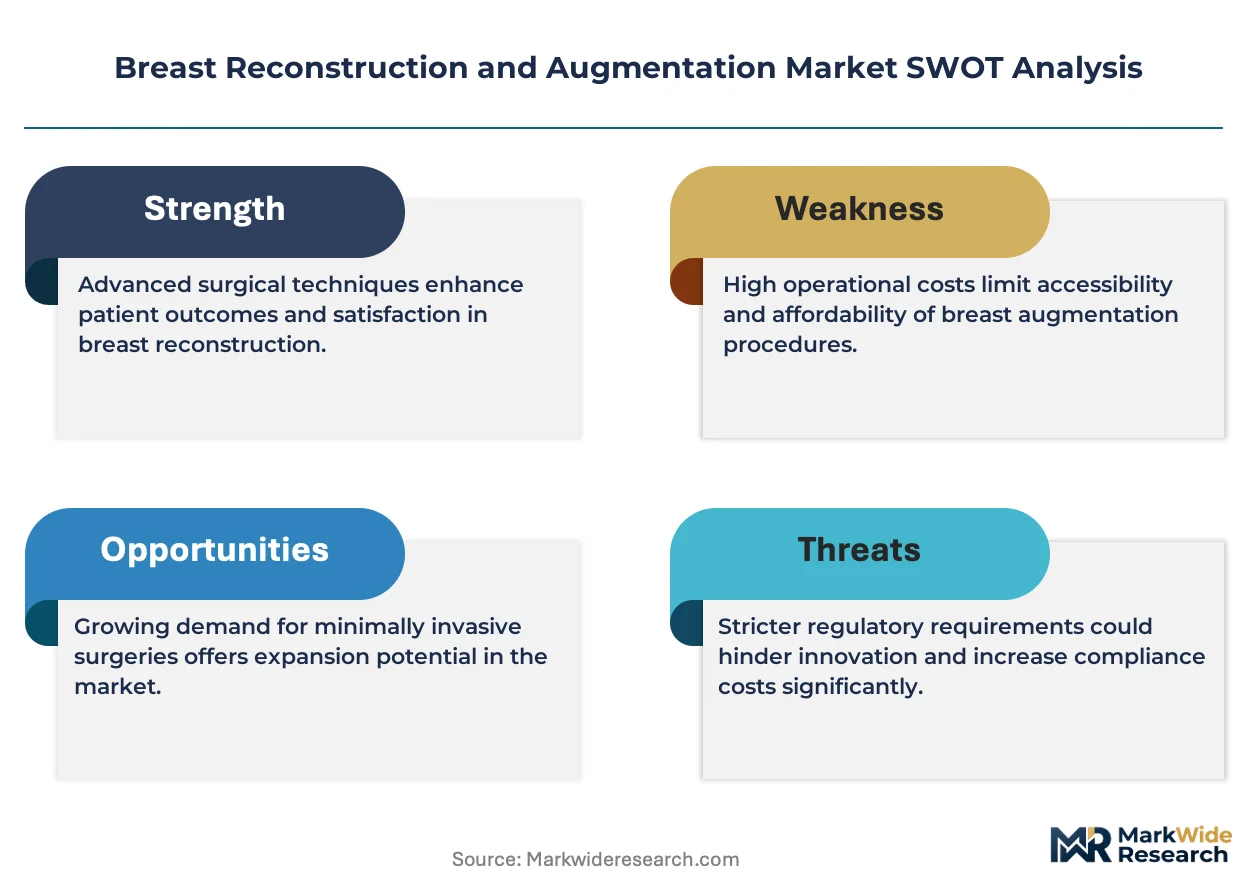
Silicone gel consolidation as the dominant filler material is restructuring competitive positioning across implant manufacturing, with tactile performance advantages compressing saline alternatives into niche applications while FDA post-market surveillance requirements extend product development timelines.
Growth Catalysts
- Aesthetic Elective Demand:Cash-pay cosmetic procedures concentrate margin pools in high-income urban clusters, with board-certified plastic surgeon networks capturing premium pricing power.
- EU MDR Implementation:Enhanced clinical evidence requirements and unique device identification mandates filter market access, advantaging manufacturers with established European regulatory infrastructure.
- Fat Grafting Techniques:Autologous tissue transfer methods register fastest expansion as patients seek implant alternatives, driving investment in liposuction-derived cell processing technologies.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty polymer production clusters in Germany and Japan, exposing manufacturers to input cost volatility and single-source dependency risks.
- FDA Premarket Approval Pathways:Extended clinical trial timelines and post-market study obligations delay revenue recognition and elevate liability exposure for new implant entrants.
- Textured Surface Limitations:Association with anaplastic large cell lymphoma has restricted textured shell adoption, constraining product differentiation options.
Strategic Opportunities
- Latin American Market Underpenetration:Brazil and Mexico present expansion vectors for manufacturers with CE-marked or FDA-approved portfolios seeking geographic diversification.
- 3D Imaging and Surgical Planning Convergence:Preoperative visualization software integration with implant selection workflows is automating patient consultation processes and reducing revision rates.
- Japan PMDA Streamlined Review:Sakigake designation pathways for innovative medical devices accelerate time-to-market for novel silicone formulations and surface technologies.
Industry Challenges
- Plastic Surgeon Certification Bottlenecks:Board eligibility requirements and fellowship training capacity constraints limit qualified implanting physician supply in key metropolitan markets.
- Patient Registry Compliance Burden:Mandatory participation in post-approval surveillance studies demands sustained data infrastructure investment and threatens smaller manufacturer viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Reconstruction and Augmentation Market |
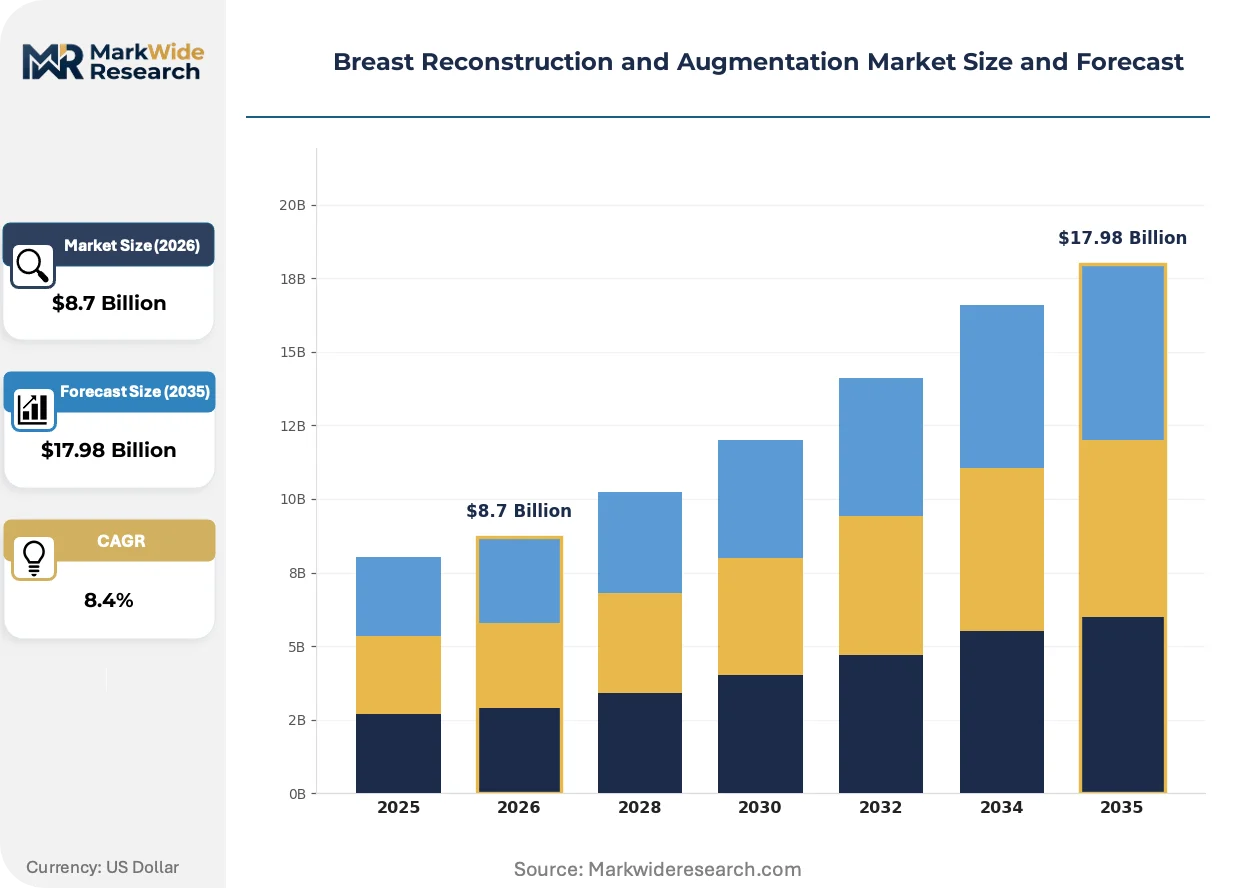
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Tissue Expanders, Flap Procedures, Autologous Tissue Patient Type: Reconstructive Patients, Aesthetic Patients, Cancer Survivors, Gender Dysphoria Patients Delivery Mode: Inpatient, Outpatient, Ambulatory Surgical Center, Hospital Technique: Submuscular, Subglandular, Hybrid, Fat Grafting |
| Companies Covered | Establishment Labs, Polytech Health & Aesthetics, Allergan (AbbVie), Sebbin, Ideal Implant, Johnson & Johnson (Mentor), GC Aesthetics, Integra LifeSciences, Sientra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Reconstruction and Augmentation Market Emerging Trajectories
Digital surgical planning tools and surface chemistry advances are compressing procedural variability while regulatory harmonization efforts reshape cross-border commercialization strategies.
Structured surface engineering is automating implant-tissue integration assessment through proprietary nano-topography mapping. Academic medical centers in the United States and South Korea are piloting these characterization protocols ahead of broader adoption. The technology is automating quality control workflows previously dependent on manual histopathological review.
EU MDR post-market clinical follow-up requirements are mandating extended implant surveillance periods and systematic literature review obligations. Manufacturers must maintain active implant registries across multiple member states to sustain CE marking. Reconstructive indication portfolios face disproportionate compliance cost impacts relative to aesthetic-only suppliers.
Direct-to-consumer digital channels are fragmenting traditional referral pathways between primary care physicians and plastic surgery practices. Social media platforms and virtual consultation tools now intermediate initial patient education and surgeon selection in North American and Western European markets. This disintermediation compresses traditional professional network gatekeeping functions.
Breast Reconstruction and Augmentation Market Segmentation
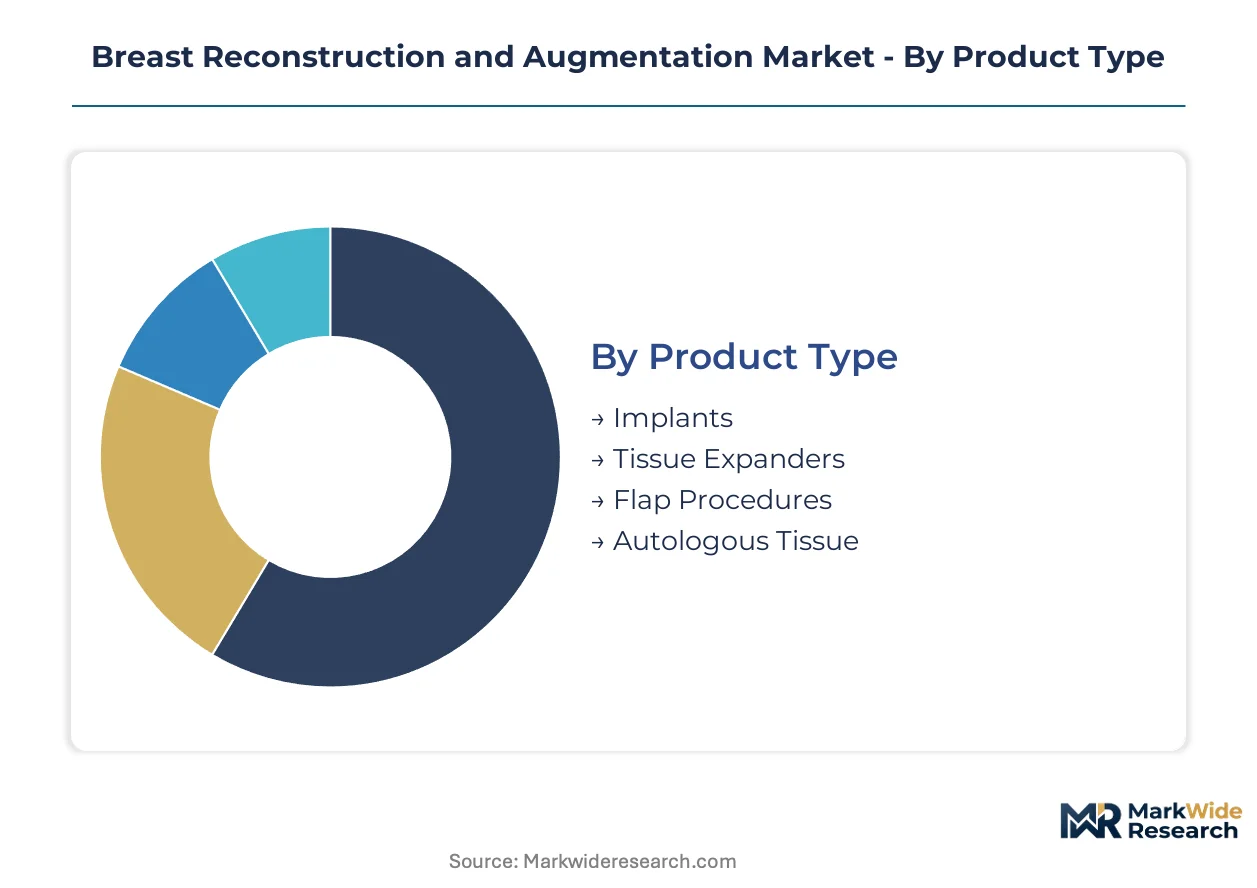
Segmentation in breast reconstruction and augmentation separates high-volume reconstructive flows from premium elective channels, with product form and care setting determining reimbursement pathways and margin structures. Understanding these splits enables manufacturers to align regulatory investment with addressable revenue pools.
Product Type:
Implants dominate unit economics through recurring replacement cycles, while autologous alternatives command premium positioning in cash-pay segments.
- Implants:Silicone gel-filled shells with textured or smooth surfaces constitute the procedural standard. Reconstructive patients in the United States sustain volume through insurance-backed mastectomy reconstruction, though FDA post-market surveillance obligations extend manufacturer liability timelines.
- Autologous Tissue:Fat grafting and tissue transfer techniques eliminate foreign body exposure. Demand concentrates in aesthetic channels across Germany and Brazil, where patients prioritize natural feel over implant durability.
- Tissue Expanders:Temporary saline devices enable staged reconstruction workflows.
- Flap Procedures:Microsurgical tissue relocation from abdomen or back.
Mature deployment sits with Implants. Newer deployment is concentrated in Autologous Tissue.
Patient Type:
Reimbursement eligibility splits the market between insurance-funded reconstruction and self-pay aesthetic enhancement.
- Reconstructive Patients:Post-mastectomy and trauma cases qualify for coverage under United States federal and state mandates. Volume anchors in academic medical centers with established oncology surgery integration.
- Aesthetic Patients:Elective cosmetic procedures operate outside reimbursement frameworks. Margin pools concentrate in coastal United States metropolitan clusters and private London clinics where surgeon reputation drives pricing power.
- Cancer Survivors:Delayed reconstruction following active treatment completion.
- Gender Dysphoria Patients:Chest masculinization and feminization procedures.
Reimbursement-dependent volume flows through Reconstructive Patients. Discretionary spending expansion is strongest among Aesthetic Patients.
Delivery Mode:
Site-of-service economics favor outpatient migration where regulatory and infrastructure requirements permit.
- Hospital:Complex reconstructive cases requiring microsurgical backup and extended monitoring. Cancer reconstruction in France and Japan remains hospital-anchored due to national health system reimbursement structures.
- Ambulatory Surgical Center:Standalone facilities capture routine implant exchange and aesthetic primary augmentation. United States certificate-of-need states restrict ASC penetration, preserving hospital volume in concentrated markets.
- Inpatient:Extended-stay cases with comorbidity management.
- Outpatient:Hospital-based same-day discharge protocols.
Complex cases remain tethered to Hospital settings. Volume migration is accelerating into Ambulatory Surgical Center environments.
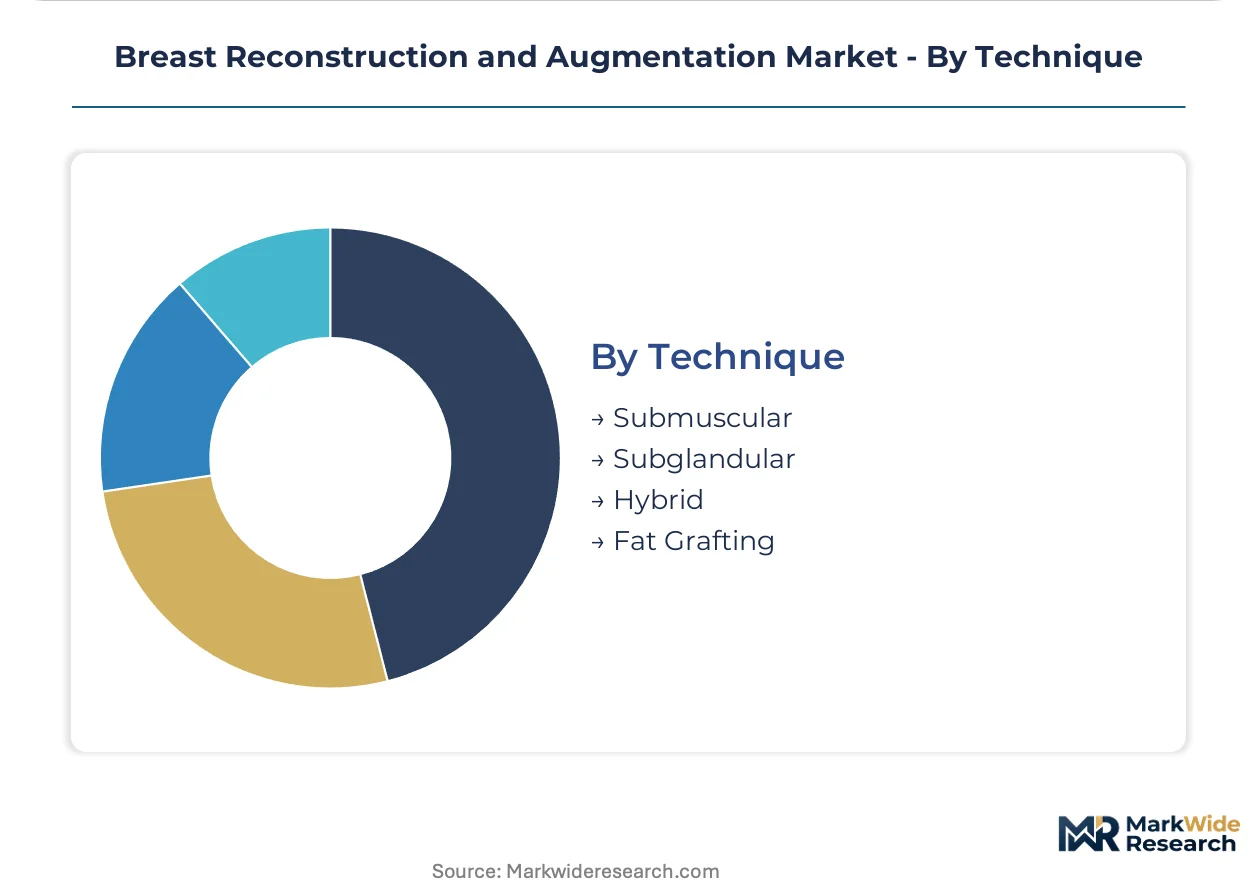
Technique:
Placement depth and tissue integration methods determine complication profiles and revision liability.
- Submuscular:Implant positioning beneath pectoralis major reduces capsular contracture rates. Reconstructive indication preference in the United States reflects long-term FDA surveillance data on device safety.
- Fat Grafting:Liposuction-derived adipose transfer avoids implant-related complications. South Korean and Brazilian clinics lead technique refinement, with Seoul academic centers publishing volumetric retention protocols.
- Subglandular:Pre-pectoral placement over muscle.
- Hybrid:Combined implant and autologous tissue approaches.
Established practice favors Submuscular placement. Technique innovation is concentrating in Fat Grafting protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for breast reconstruction and augmentation procedures concentrates in high-income markets with established plastic surgery infrastructure and favorable reimbursement frameworks. The United States absorbs the largest procedure volume globally, while Germany, Brazil, South Korea, and Japan anchor regional demand clusters with distinct regulatory and clinical characteristics.
United States
FDA premarket approval pathways and federal breast reconstruction mandates sustain manufacturer investment in post-market surveillance infrastructure. The Women's Health and Cancer Rights Act ensures insurance coverage for post-mastectomy reconstruction, anchoring volume in academic medical centers across Texas, California, and New York. Coastal metropolitan clusters concentrate elective aesthetic demand where board-certified plastic surgeon networks command premium positioning.
Germany
EU MDR implementation filters market access through enhanced clinical evidence requirements and unique device identification mandates. The BfArM maintains stringent oversight of silicone implant biocompatibility testing, with manufacturing concentration in North Rhine-Westphalia and Bavaria. Private clinics in Munich and Düsseldorf drive aesthetic procedure adoption among high-income patient segments.
Brazil
ANVISA regulatory harmonization with international standards accelerates approval timelines for CE-marked and FDA-approved device portfolios. São Paulo and Rio de Janeiro anchor Latin America's largest plastic surgery market, with cash-pay aesthetic demand exceeding reconstructive volumes. Local training institutions produce surgeon supply that outpaces regional peers.
South Korea
MFDS streamlined review pathways and medical tourism promotion position Seoul as Asia's aesthetic surgery hub. Gangnam district clinics pioneer fat grafting technique refinement and 3D imaging integration. Government initiatives targeting foreign patient inflows subsidize marketing infrastructure for accredited facilities.
Japan
PMDA Sakigake designation pathways accelerate novel silicone formulation approvals for manufacturers with established quality management systems. Tokyo and Osaka academic centers concentrate reconstructive oncology integration, while private clinics in Yokohama expand aesthetic service lines. Aging demographics and breast cancer incidence sustain reconstruction demand growth.
Breast Reconstruction and Augmentation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across reconstructive and aesthetic channels. The implant segment exhibits consolidated structure among silicone gel suppliers with vertically integrated production capabilities, while autologous tissue transfer technologies fragment across regional device vendors and surgical instrument providers. Three archetypes dominate: multinational conglomerates with diversified medical device portfolios, pure-play breast aesthetics specialists with surgeon-exclusive distribution, and regional contract manufacturers serving private-label demand. Competitive dynamics center on regulatory certification maintenance and geographic expansion through distributor partnerships rather than price-based rivalry.
Among the pure-play specialists, Establishment Labs and Sientra exemplify the surgeon-network distribution model, while Johnson & Johnson (Mentor) occupies a position spanning conglomerate scale with dedicated aesthetics focus. These three anchors demonstrate how proprietary silicone formulations and exclusive professional channel access serve as defensive positioning against contract manufacturing entrants. Each represents distinct geographic origination patterns—Costa Rica-based, US-based, and diversified multinational respectively—reflecting supply chain configuration choices in the sector.
| Leading Market Players |
|---|
| Establishment Labs |
| Polytech Health & Aesthetics |
| Allergan (AbbVie) |
| Sebbin |
| Ideal Implant |
| Johnson & Johnson (Mentor) |
| GC Aesthetics |
| Integra LifeSciences |
| Sientra |
| Others |
Supply Flow & Price Mechanics
FDA post-market surveillance mandates and EU MDR clinical evidence requirements are forcing manufacturers to absorb extended compliance costs that compress mid-tier pricing flexibility while premium silicone formulations sustain margin pools.
Pricing Analysis
Volume flows through insurance-backed reconstructive channels while margin pools concentrate in elective aesthetic segments. Three-tier pricing structure across premium silicone gel, standard saline, and economy-tier tissue expanders segments buyers by certification grade and surgeon network access. Cost compression in standard-tier implants is intensifying because of medical-grade silicone supply bottlenecks in Germany and Japan. Reconstructive patients show highest price sensitivity due to insurance reimbursement caps, whereas aesthetic patients in coastal United States metropolitan clusters demonstrate lowest sensitivity.
Supply Chain Analysis
Medical-grade silicone polymer production rests on specialty chemical manufacturers clustered in Germany, Japan, and the United States. Raw material dependencies center on platinum-cured silicone elastomers, shell-grade polydimethylsiloxane, and sterile packaging films. Single-source vulnerability in German polymer feedstock exposes manufacturers to input cost volatility and force majeure disruption. Distribution runs through board-certified plastic surgeon networks and hospital purchasing committees, with ambulatory surgical center procurement gaining share in deregulated United States states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone polymer supply constraints and extended FDA approval timelines prop pricing power for incumbent manufacturers with captive raw material access.
For Market Incumbents: Deepen backward integration into medical-grade silicone polymer production to offset German and Japanese supply concentration. Expand CE marking maintenance infrastructure ahead of EU MDR post-market clinical follow-up deadlines. Secure exclusive distribution contracts with board-certified plastic surgeon networks to lock out contract manufacturing entrants. For New Entrants and Emerging Players: Gender dysphoria patients seeking chest masculinization and feminization procedures represent an underserved buyer archetype with expanding procedural coverage. Fat grafting technique refinement in South Korean and Brazilian clinics offers white-space entry with lower regulatory capital requirements. Pursue ANVISA harmonization pathways in Brazil and Mexico to bypass FDA premarket approval bottlenecks. For Investors and Strategic Acquirers: The window for entry favors pure-play breast aesthetics specialists with established surgeon-exclusive distribution and proprietary silicone formulations. Long-term viability hinges on regulatory certification maintenance capabilities across FDA, CE marking, and PMDA jurisdictions. Watch MFDS Sakigake designation awards in South Korea as inflection indicators for novel surface technology validation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended clinical timelines favor manufacturers with established post-market surveillance infrastructure. |
| CE Marking Maintenance Investment | EU MDR compliance costs filter market access to manufacturers with European regulatory teams. |
| Hospital System Partnership | Academic medical center integration anchors reconstructive volume through oncology surgery alignment. |
| Software Companion Development | 3D imaging integration with implant selection workflows reduces revision liability and consultation friction. |
| Reimbursement Strategy | Women's Health and Cancer Rights Act coverage mandates sustain United States reconstructive demand. |
Methodological Framework
Multi-period observation of FDA premarket approval timelines, EU MDR certification transitions, and surgeon network expansion patterns anchored the trend analysis, supplemented by interviews with plastic surgery practice administrators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EUDAMED device registrations, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to cross-validate market sizing.
Segment-weighting across product type, patient category, delivery mode, and surgical technique dimensions shaped the analytical framework across the projection horizon. CAGRs were derived from regression analysis of historical procedure volumes against demographic and regulatory drivers. Industry-specific forecast inputs included breast cancer incidence trajectories, plastic surgeon fellowship graduation rates, and medical-grade silicone polymer price indices.
Revisions become necessary when FDA guidance shifts on textured surface safety, EU MDR implementation timelines extend, or major silicone feedstock disruptions materialize. Forecasts reflect assumptions about sustained reimbursement mandates and stable raw material supply. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Cosmetic Threads Market