
 Global Medical Aesthetic Devices Market | 2026-2036
Global Medical Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Aesthetic Devices Market Outlook
Med-spa franchising is reshaping how aesthetic devices reach end users in Asia-Pacific and Latin America. AbbVie Inc. leverages its Allergan Aesthetics division to control premium injectable channels across North America and Europe. Johnson & Johnson anchors its position through Ethicon's surgical-aesthetic crossover portfolio, while Alma Lasers competes aggressively on diode-laser price points in emerging markets. Merz Pharma differentiates via integrated toxin-filler combination therapies that tighten clinician loyalty.
Medical aesthetic devices encompass instruments that modify or enhance human appearance through energy delivery, substance injection, or mechanical abrasion, typically operating at wavelengths between 532 nm and 10,600 nm for laser systems or generating radio frequencies between 1 MHz and 40 MHz for tissue heating. These systems serve commercial purposes by enabling physicians and licensed practitioners to perform revenue-generating procedures without general anesthesia or overnight facility stays. Energy-based devices now capture the largest margin pools as consumable handpiece attach rates sustain recurring revenue, while hyaluronic acid fillers face accelerating biosimilar pressure that compresses premium pricing. RF technology leads procedural volumes for skin tightening, yet ultrasound technology posts the fastest expansion as micro-focused platforms penetrate Asian facial contouring markets.
The FDA governs device safety through 510(k) premarket notification and De Novo classification pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for energy-based systems sold under CE marking. Japan's PMDA maintains separate shonin approval standards that delay entry for novel cryotherapy platforms by twelve to eighteen months relative to US clearances. Stakeholders must monitor how China's NMPA streamlines innovative device review channels, as domestic manufacturers there are capturing share in electroporation and microdermabrasion segments previously dominated by Israeli and American suppliers.
Market Dynamics
Micro-focused ultrasound platforms are compressing surgical facelift volumes across East Asian dermatology networks, while consumable attach rates on RF devices now determine manufacturer profitability more than hardware margins alone.
Growth Catalysts
- MFU-V Protocol Expansion:Micro-focused ultrasound with visualization is capturing facial contouring volumes in Seoul and Tokyo clinics previously reserved for thread lifts.
- EU MDR Streamlining:The Medical Device Regulation's Article 61 amendment is accelerating CE marking timelines for Class IIa energy-based systems.
- Brazilian Med-Spa Density:Franchise networks in São Paulo and Rio de Janeiro are standardizing device procurement across 200-plus locations.
Market Restraints
- Handpiece Cost Concentration:Disposable RF applicators from single-source suppliers in Germany account for 35-45% of lifetime device ownership cost.
- 510(k) Evidence Burden:FDA's enhanced clinical data requirements for energy-based fat reduction systems extend clearance timelines by 14-22 months.
- Hyaluronic Acid Commoditization:Korean and Chinese biosimilar fillers are eroding premium pricing on established HA injectable lines.
Strategic Opportunities
- Mexico Regulatory Arbitrage:COFEPRIS's accelerated pathway for devices already cleared by FDA or CE allows 6-9 month faster market entry than Brazil's ANVISA.
- Home-Use Device Channels:IPL hair removal and microcurrent facial toners are migrating from clinic to direct-to-consumer via telemedicine prescription models.
- AI-Guided Treatment Planning:Machine vision systems that map facial anatomy for injection placement are converging with EMR workflow integration.
Industry Challenges
- Clinical Training Bottlenecks:Safe operation of multi-wavelength laser platforms requires 40-80 hours of supervised proctoring that manufacturer field teams struggle to scale.
- Interoperability Friction:Energy-based devices lack standardized data exchange protocols with practice management software, forcing manual outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Aesthetic Devices Market |
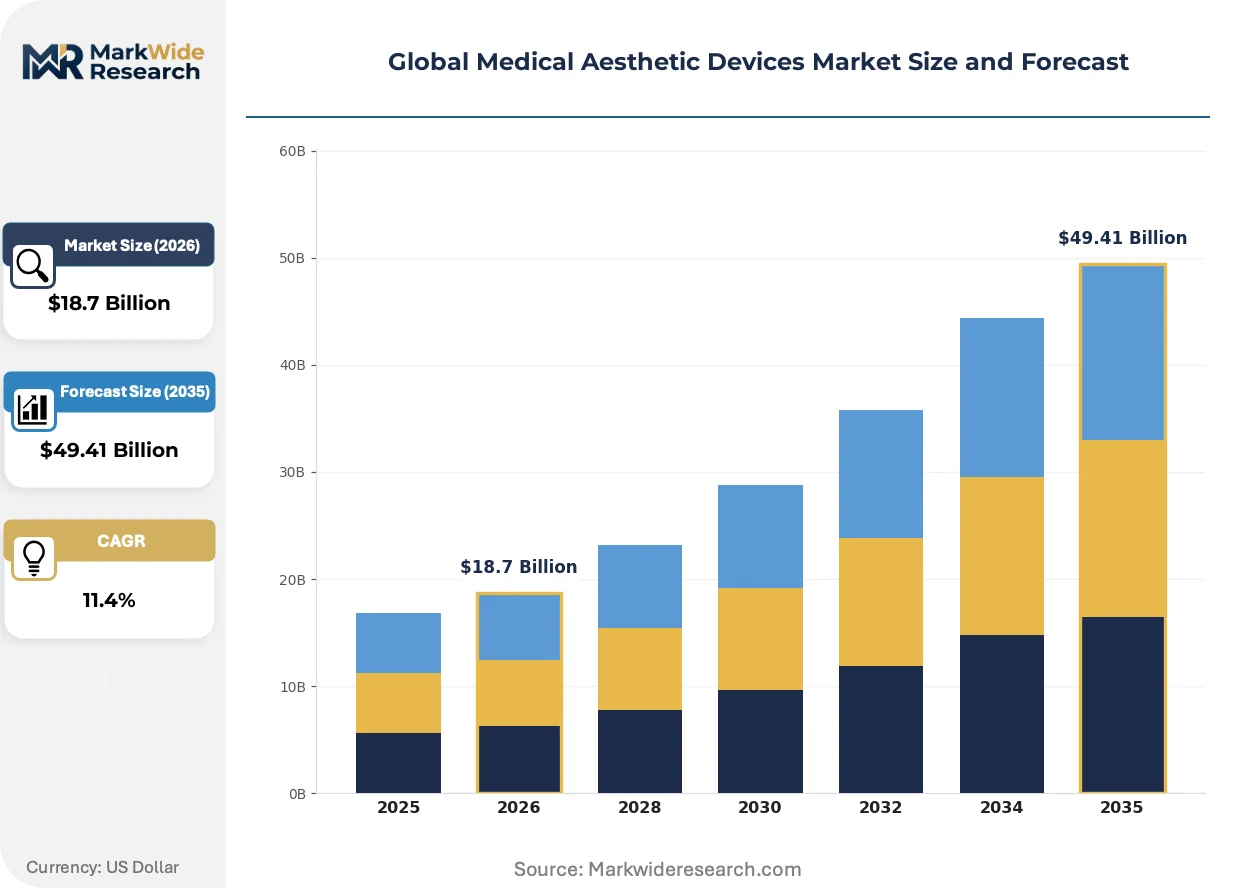
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Energy-Based Devices, Hyaluronic Acid Fillers, Microdermabrasion Devices Technology: RF Technology, Ultrasound Technology, Cryotherapy, Electroporation End User: Clinics, Hospitals, Home Care, Spa Centers Application: Skin Rejuvenation, Hair Restoration, Body Contouring, Facial Contouring |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Merz Pharma, Bausch Health Companies Inc., Alma Lasers, Cutera Inc., Cynosure LLC, Lumenis Ltd., Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Aesthetic Devices Market Strategic Shifts
Device architecture is pivoting toward modular platforms that accept multiple energy modalities through swappable handpieces, collapsing the traditional one-device-one-function procurement model.
Picosecond-domain laser technology operating at 755 nm and 1064 nm wavelengths is rendering obsolete nanosecond Q-switched systems for tattoo removal and pigmented lesion treatment. Dermatology groups in California and New South Wales are retiring older platforms ahead of normal depreciation cycles. The structural compression is eliminating secondary market resale value for legacy equipment and forcing distributors to absorb trade-in losses.
The EU Medical Device Regulation's Annex XIV clinical evaluation requirements are imposing prospective study obligations on RF and ultrasound device manufacturers seeking CE marking renewals. Companies must now generate post-market clinical follow-up data that was previously satisfied by literature reviews. German and Italian manufacturers of cryolipolysis systems are absorbing 15-20% compliance cost increases and passing portions to clinic buyers through extended service contracts.
After-sales service unbundling is separating hardware warranties from preventive maintenance and software update subscriptions. Large dermatology chains in Texas and Florida are negotiating direct technician training to reduce dependency on manufacturer field service. The disintermediation is most advanced in US multi-site practices operating 15-plus devices, where in-house biomedical engineers now handle 60% of routine calibration and handpiece replacement.
Global Medical Aesthetic Devices Market Segmentation
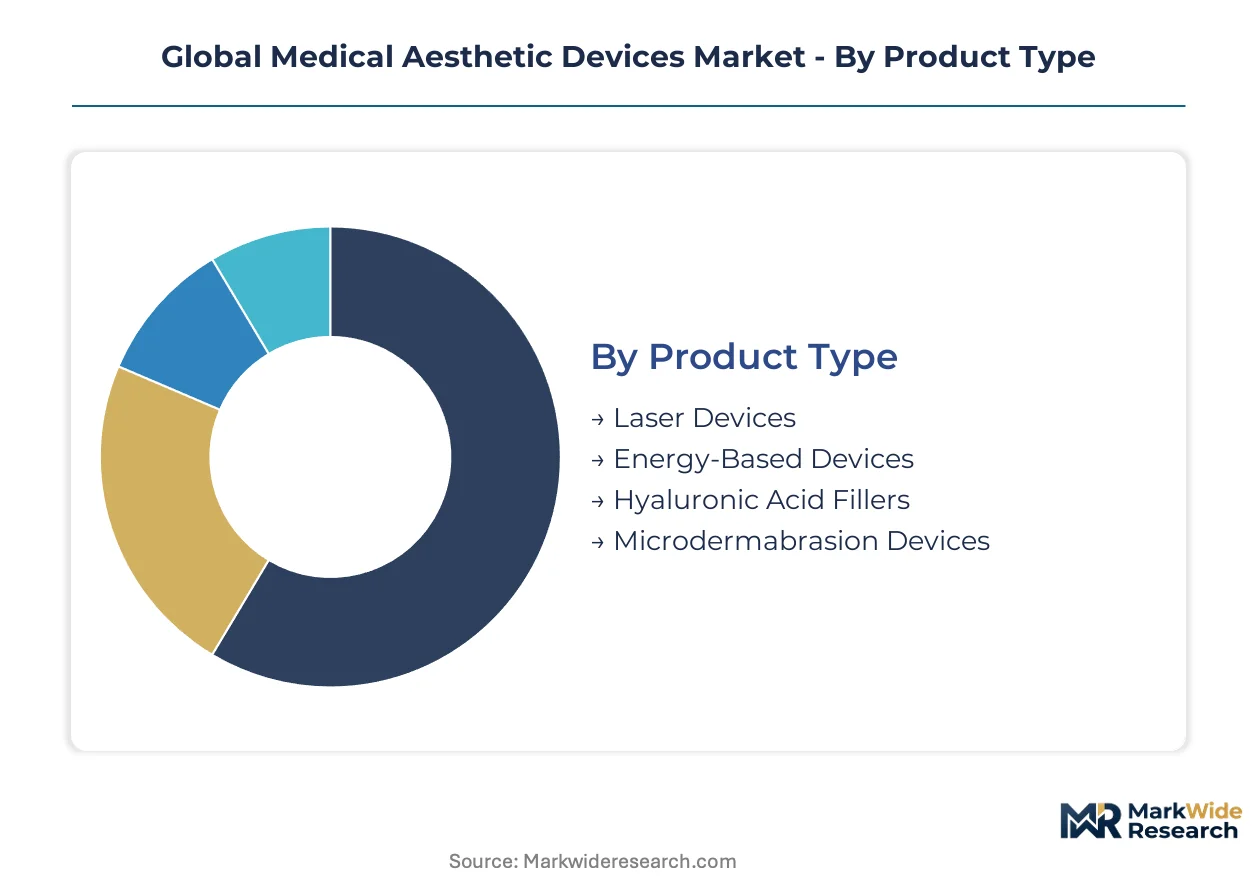
Device segmentation in medical aesthetics determines procurement patterns, service contract structures, and clinician training investments. Each category carries distinct after-sales intensity profiles that reshape manufacturer profitability and distributor relationships across global markets.
Product Type:
After-sales service intensity varies sharply across product categories, with energy-based platforms demanding continuous handpiece replacement and laser systems requiring periodic optical component calibration.
- Energy-Based Devices:RF and ultrasound platforms generate recurring revenue through disposable applicators and coupling gels. Seoul dermatology chains now standardize procurement around multi-modality systems that reduce per-procedure consumable costs.
- Laser Devices:Solid-state and diode laser systems operate at wavelengths from 532 nm to 10,600 nm for pigmentation, vascular, and resurfacing applications. California dermatology groups are retiring nanosecond platforms for picosecond-domain replacements despite incomplete depreciation cycles.
- Hyaluronic Acid Fillers:Injectable gel formulations face biosimilar pressure from Korean and Chinese manufacturers.
- Microdermabrasion Devices:Mechanical exfoliation systems carry lower service intensity than energy-based alternatives.
Energy-based devices hold the largest share; momentum sits with laser devices as picosecond technology accelerates replacement cycles.
Technology:
Technology selection drives capital allocation toward platforms with superior margin retention through proprietary consumable lock-in.
- RF Technology:Radiofrequency systems operating at 1-40 MHz dominate skin tightening procedural volumes. Brazilian med-spa networks are deploying bipolar and multipolar configurations across franchise locations to standardize treatment protocols.
- Ultrasound Technology:Micro-focused ultrasound with visualization penetrates subcutaneous tissue at precise depths for non-surgical lifting. Tokyo and Seoul clinics are displacing thread lift volumes with MFU-V protocols that require no anesthesia recovery.
- Cryotherapy:Controlled cooling platforms for fat reduction face extended FDA clearance timelines.
- Electroporation:Electrical pulse delivery systems enhance topical agent penetration.
RF technology commands the installed base; ultrasound platforms are climbing the fastest as Asian facial contouring demand accelerates.
End User:
End-user category determines purchasing authority, with clinic chains negotiating enterprise pricing unavailable to independent practices.
- Clinics:Dermatology and aesthetic medicine practices generate the majority of device utilization through high-frequency appointment scheduling. Texas and Florida multi-site operators now employ in-house biomedical engineers to reduce manufacturer dependency.
- Spa Centers:Med-spa franchises in São Paulo and Rio de Janeiro are consolidating procurement across 200-plus locations.
- Hospitals:Academic medical centers prioritize research compatibility and resident training infrastructure.
- Home Care:Direct-to-consumer IPL and microcurrent devices migrate through telemedicine prescription channels.
Clinics represent the dominant channel; home care is gaining share fastest as regulatory pathways for prescription-grade consumer devices mature.
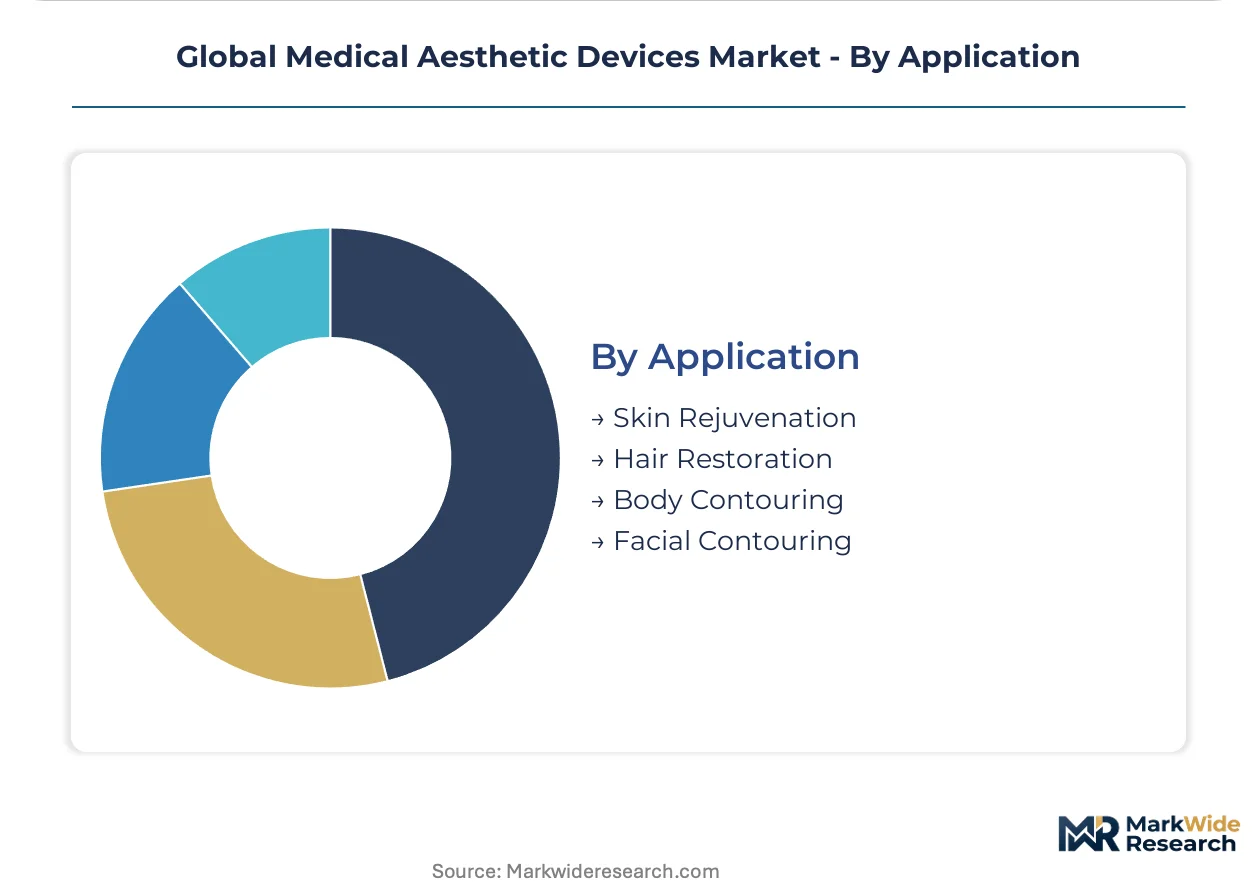
Application:
Application focus shapes device specification requirements, with body contouring platforms requiring larger treatment surface areas than facial systems.
- Body Contouring:Cryolipolysis and RF fat reduction systems target adipose tissue across abdomen, flank, and thigh regions. Brazilian med-spa corridors now drive half of new device placements in this category.
- Facial Contouring:MFU-V and injectable protocols reshape jawline and midface architecture without surgical intervention. South Korean dermatology networks are expanding device fleets specifically for non-invasive lifting.
- Skin Rejuvenation:Laser resurfacing and RF microneedling address photodamage and textural irregularities.
- Hair Restoration:Low-level laser therapy and fractional RF platforms target androgenetic alopecia.
Body contouring holds the largest share; facial contouring shows the steepest expansion trajectory as East Asian aesthetic preferences reshape global demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's tightened 510(k) pathway elevates compliance costs for energy-based device manufacturers entering the United States, while divergent approval timelines across Japan, South Korea, and Brazil create arbitrage opportunities for first-movers.
United States
Texas and Florida multi-site dermatology chains now employ in-house biomedical engineers to reduce manufacturer dependency on field service. FDA's enhanced clinical data requirements for fat reduction systems extend clearance timelines substantially. California dermatology groups in Los Angeles and San Francisco are retiring nanosecond laser platforms for picosecond-domain replacements.
South Korea
Seoul dermatology clinics are expanding device fleets as non-invasive facial contouring protocols displace traditional surgical lifts. MFDS maintains shonin approval standards that accelerate domestic device review relative to imported novel systems. The Gangnam district anchors premium aesthetic device density with standardized procurement across clinic networks.
Brazil
São Paulo and Rio de Janeiro med-spa franchise networks are consolidating procurement across 200-plus locations for body contouring applications. ANVISA's review timelines lag Mexico's COFEPRIS pathway by six to nine months for devices already cleared by FDA or CE marking. The Brazilian med-spa corridor now drives half of new device placements in Latin America.
Japan
Tokyo clinics are displacing thread lift volumes with micro-focused ultrasound protocols that require no anesthesia recovery. PMDA maintains separate approval standards that delay entry for novel cryotherapy platforms by twelve to eighteen months relative to US clearances. The Osaka-Kobe corridor concentrates device utilization through high-frequency appointment scheduling.
Germany
Disposable RF applicators from single-source German suppliers account for 35-45% of lifetime device ownership cost across European installations. EU MDR's Annex XIV clinical evaluation requirements impose prospective study obligations on manufacturers seeking CE marking renewals. Munich and Düsseldorf anchor manufacturing clusters for precision optical components serving laser system integrators.
Global Medical Aesthetic Devices Market Competitive Environment
Pharmaceutical conglomerates and specialized energy-device manufacturers split the market between injectable channels and capital equipment placement. The vendor base concentrates around three strategic archetypes: diversified healthcare conglomerates controlling premium toxin-filler portfolios, laser specialists competing on diode price points in emerging markets, and integrated platform vendors bundling multi-modality hardware with consumable lock-in. Dominant competitive moves include M&A activity to capture crossover surgical-aesthetic portfolios and geographic expansion through med-spa franchise standardization.
Within the diversified healthcare tier, AbbVie Inc. and Johnson & Johnson occupy positions anchored by aesthetic medicine divisions, while Alma Lasers exemplifies the specialized equipment archetype competing aggressively on price positioning. Merz Pharma represents the integrated therapy approach through combination toxin-filler protocols. These three entities illustrate how market participants defend margin structures—AbbVie through channel control, Johnson & Johnson through portfolio breadth, and Alma Lasers through emerging market penetration.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Merz Pharma |
| Bausch Health Companies Inc. |
| Alma Lasers |
| Cutera Inc. |
| Cynosure LLC |
| Lumenis Ltd. |
| Galderma |
| Others |
Value Chain & Pricing Dynamics
The Incheon-to-Los Angeles air freight corridor carries precision optical components and disposable RF applicators whose cost volatility ripples through manufacturer pricing power, compressing margins for standard-configured systems while amplifying premiums for devices with German-sourced calibration modules and extended service bundling.
Pricing Analysis
The customization-premium spread separates standard RF platforms from configured-to-order multi-modality systems with proprietary handpiece lock-in. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and after-sales service intensity. Cost compression in the standard tier is intensifying because Korean and Chinese biosimilar consumables are eroding proprietary attach rates. Independent dermatology practices in Brazil and Mexico show highest price sensitivity, while Texas multi-site chains with in-house biomedical engineers absorb premium pricing to reduce manufacturer dependency.
Supply Chain Analysis
Upstream feedstock for solid-state laser crystals draws from synthetic sapphire growth facilities in Russia and Ukraine, with precision optical polishing concentrated in Germany and Japan. German suppliers of disposable RF applicators and Japanese manufacturers of micro-focused ultrasound transducers anchor component sourcing. Single-source vulnerability in German RF handpiece supply creates procurement risk for European and North American device assemblers. Distribution runs through specialized medical device distributors with field service capabilities, though large clinic chains increasingly negotiate direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) and EU MDR pathways creates substantial switching costs for clinicians invested in manufacturer training ecosystems.
For Market Incumbents: Entrench position through captive supply of disposable applicators and coupling gels that lock in recurring revenue streams. Deepen backward integration into precision optical component manufacturing to insulate against German and Japanese supplier concentration. Expand in-house training infrastructure in São Paulo and Seoul to preempt third-party clinical education platforms from eroding manufacturer influence over protocol standardization.
For New Entrants and Emerging Players: Mexico's COFEPRIS regulatory arbitrage offers accelerated market entry for devices already cleared by FDA or CE marking, enabling six-to-nine month faster deployment than ANVISA-governed Brazil. Target med-spa franchise procurement consolidation across Latin America with modular platform architectures that reduce per-procedure consumable costs. Pursue telemedicine prescription channels for home-use IPL and microcurrent devices as the most penetrable direct-to-consumer pathway.
For Investors and Strategic Acquirers: Regional platform vendors with established service networks in Southeast Asia and Latin America present acquisition targets that bypass de novo regulatory approval timelines. Long-term viability hinges on consumable attach rate sustainability and AI-guided treatment planning software integration. Watch for FDA clearance acceleration for micro-focused ultrasound devices as the inflection signal indicating regulatory pathway normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex XIV compliance unlocks European clinic procurement and German distributor partnerships. |
| Hospital System Partnership | Texas and Florida multi-site dermatology chains negotiate enterprise pricing unavailable to independent practices. |
| Software Companion Development | AI-guided facial anatomy mapping converges with EMR workflow integration to tighten clinician platform loyalty. |
| Reimbursement Strategy | Telemedicine prescription models for home-use devices expand addressable market beyond traditional clinic channels. |
| Geographic Manufacturing Footprint | Mexico assembly for Latin American markets exploits COFEPRIS regulatory arbitrage against ANVISA timelines. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers at multi-site dermatology chains, GPO contracts managers, and regulatory affairs leads at energy-device manufacturers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases. Bottom-up triangulation across installed base estimates and top-down validation through trade flow analysis ensured convergence on market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, technology modality, end-user category, and application focus. CAGRs were derived from procedure volume trajectories and device replacement cycle compression observed in California and South Korean clinic networks. Forecast inputs incorporated MFU-V protocol adoption curves and biosimilar filler penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese electroporation manufacturers or AI-guided treatment planning software entrants would shift outcomes beyond modeled ranges. Cross-checking against hospital capital expenditure surveys and clinic chain procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Japan Hair Transplant Market