
 Korea Medical Aesthetics Market | 2026-2036
Korea Medical Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Korea Medical Aesthetics Market Intelligence
Hyaluronic acid formulations are recalibrating product economics as next-generation cross-linked variants displace older collagen-based injectables. Merz Pharma leverages its R&D intensity in biostimulatory agents to sustain premium positioning against commoditized fillers. Hugel anchors domestic manufacturing scale, competing on cost structure for export markets across Asia-Pacific. Galderma differentiates through integrated dermatology platforms that extend beyond injectables into energy-based devices.
Korea medical aesthetics encompasses minimally invasive and non-invasive procedures, devices, and biopharmaceutical products designed to enhance or restore physical appearance, with specifications ranging from monophasic hyaluronic acid gels at 20-24 mg/mL concentration to fractional laser systems operating at 1550 nm wavelength for dermal remodeling. The primary commercial purpose centers on delivering measurable cosmetic outcomes with reduced recovery intervals compared to surgical alternatives. Injectables occupy the largest revenue pool within product type categories, while energy-based technologies represent the fastest-growing technology segment as radiofrequency and laser platforms displace older surgical protocols. Anti-aging applications dominate procedure volumes, though body contouring generates disproportionate margin concentration due to higher per-session pricing and repeat treatment requirements.
MFDS regulates product safety and clinical evidence standards for all aesthetic devices and biologics marketed in Korea, with approval timelines directly shaping competitive entry sequencing. The Korean Ministry of Health and Welfare enforces advertising restrictions on medical procedures, constraining direct-to-consumer marketing channels for clinics and manufacturers. KISO standards govern quality management systems for aesthetic device manufacturers, creating compliance barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving MFDS guidance on combination products as device-drug hybrids blur traditional classification boundaries and reshape market access requirements.
Market Dynamics
Biostimulatory filler pipelines are compressing approval timelines through MFDS accelerated pathways, redrawing competitive entry sequencing as domestic manufacturers scale R&D investment ahead of multinational licensing deals.
Growth Catalysts
- MFDS Fast-Track Designation:The regulator's priority review pathway for novel aesthetic biologics shortens clinical evaluation windows, enabling innovators to capture first-mover positioning in emerging filler categories before patent cliffs erode incumbent portfolios.
- Energy-Based Device Convergence:Radiofrequency platforms combined with microneedling are displacing standalone laser protocols in dermatology clinics, creating bundled procedure economics that lift per-session revenue and patient retention rates.
- Gangnam Medical Tourism Cluster:Seoul's concentrated luxury retail and hospitality infrastructure channels affluent Chinese and Southeast Asian consumers toward premium anti-aging packages, anchoring foreign currency revenue streams for physician-owned chains.
Market Restraints
- Hyaluronic Acid Feedstock Concentration:Three suppliers control pharmaceutical-grade HA raw material for cross-linked formulations, exposing Korean manufacturers to price volatility and allocation constraints during upstream fermentation disruptions.
- MFDS Combination Product Uncertainty:Ambiguous classification boundaries for device-drug hybrids delay market access as sponsors navigate parallel technical consultations for products incorporating both biologic and mechanical therapeutic mechanisms.
- Non-Invasive Body Contouring Substitution:Cryolipolysis and high-intensity focused electromagnetic platforms capture patient flow that previously converted to surgical liposuction, compressing addressable volume for invasive fat-reduction procedures.
Strategic Opportunities
- Busan Secondary Hub Development:Korea's second-largest metropolitan area exhibits underpenetrated aesthetic clinic density relative to disposable income growth, offering acquisition targets for capitalized chains seeking geographic diversification beyond saturated Seoul districts.
- Telemedicine Pre-Consultation Channels:Virtual assessment platforms for procedure education and candidacy screening are emerging as patient acquisition tools that reduce physical consultation overhead while expanding reach to domestic secondary cities.
- PLA/PDLLA Biostimulator Expansion:Next-generation poly-lactic acid formulations stimulate collagen synthesis over extended release profiles, opening premium positioning above conventional HA fillers for facial volumization indications.
Industry Challenges
- Injection Specialist Certification Bottlenecks:Korean Society of Plastic and Reconstructive Surgeons credentialing timelines constrain qualified practitioner supply, limiting clinic expansion velocity despite capital availability for new location buildouts.
- Energy Device Calibration Complexity:Multi-wavelength laser platforms require specialized biomedical engineering support for maintenance and parameter optimization, elevating operational overhead relative to disposable injector-based procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Korea Medical Aesthetics Market |
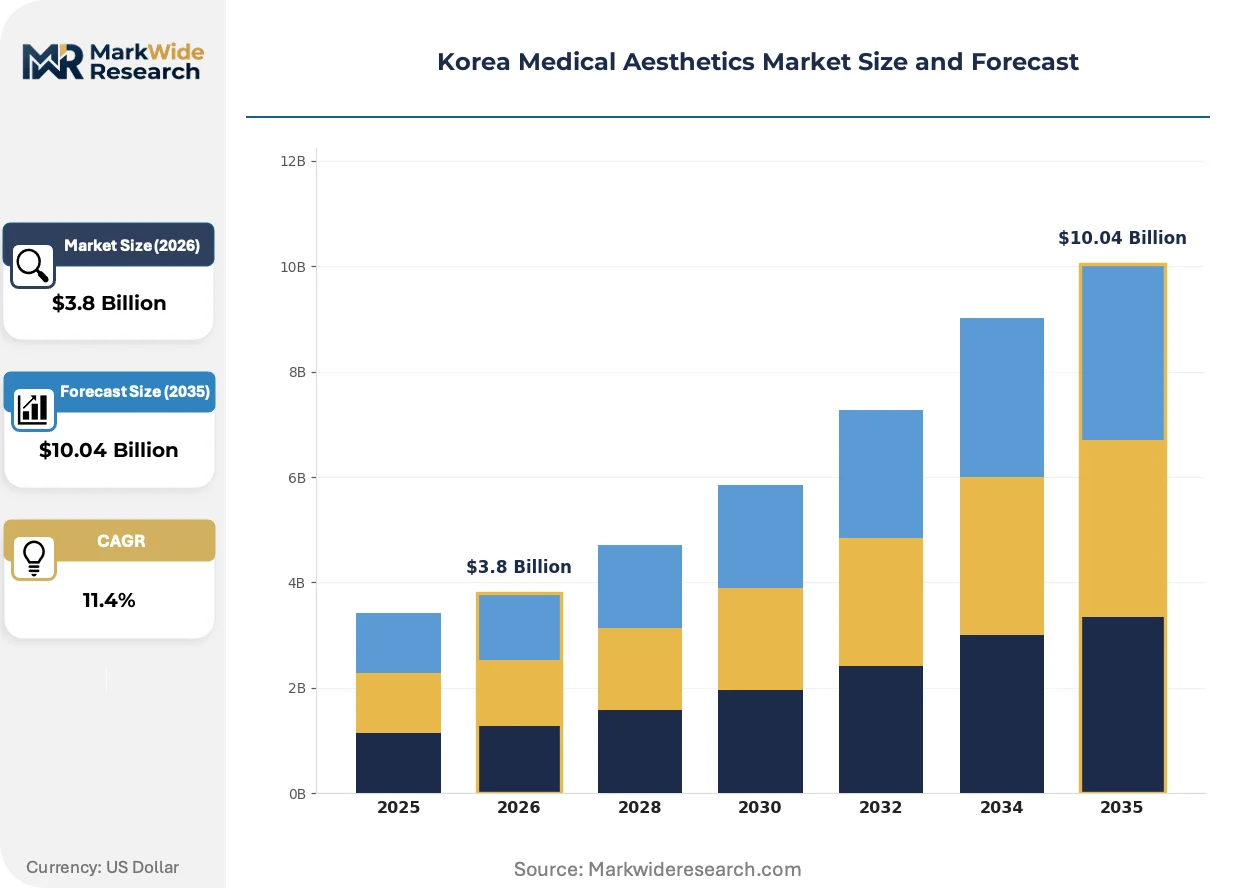
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Devices, Radiofrequency Devices, Microneedling Devices Application: Anti-Aging, Skin Rejuvenation, Hair Restoration, Body Contouring End User: Clinics, Hospitals, Home Users, Aesthetic Centers Technology: Non-Surgical, Surgical, Advanced Imaging, Energy-Based |
| Companies Covered | Merz Pharma, Johnson & Johnson, Galderma, Sinclair Pharma, Hugel, AbbVie, Lumenis, Cynosure Lutronic, Allergan Aesthetics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Korea Medical Aesthetics Market Strategic Shifts & Innovations
Digital imaging and AI-assisted treatment planning are penetrating consultation workflows, reshaping how clinics quantify outcomes and manage patient expectations prior to commitment.
High-intensity focused ultrasound systems operating at 4-7 MHz frequencies are decentralizing facial lifting procedures from surgical suites into outpatient dermatology settings. Mid-sized clinic chains in Seoul's satellite districts adopt these platforms at replacement cycles of 18-24 months. This technology is decentralizing procedure economics by eliminating anesthesia requirements and reducing facility overhead while maintaining comparable patient-reported satisfaction scores for skin laxity correction.
MFDS guidance on real-world evidence supplementation for aesthetic device approvals is tightening post-market surveillance obligations for radiofrequency and laser manufacturers. Sponsors must now submit patient registry data from Korean sites as a condition of license renewal, elevating clinical affairs infrastructure costs. Domestic energy-device producers with established investigator networks are responding faster than import-dependent distributors, compressing competitive timelines for foreign entrants.
Younger demographic cohorts in their late twenties are initiating preventive neurotoxin protocols at shorter intervals than traditional therapeutic applications, compressing the average patient age at first treatment. Social media-native channels including video-based platforms are displacing clinic-hosted informational seminars as the primary education and conversion pathway. This behavioral shift is most visible in Seoul's university districts where student-affiliated aesthetic studios report disproportionate consultation volume growth relative to established Gangnam premium providers.
Korea Medical Aesthetics Market Segmentation
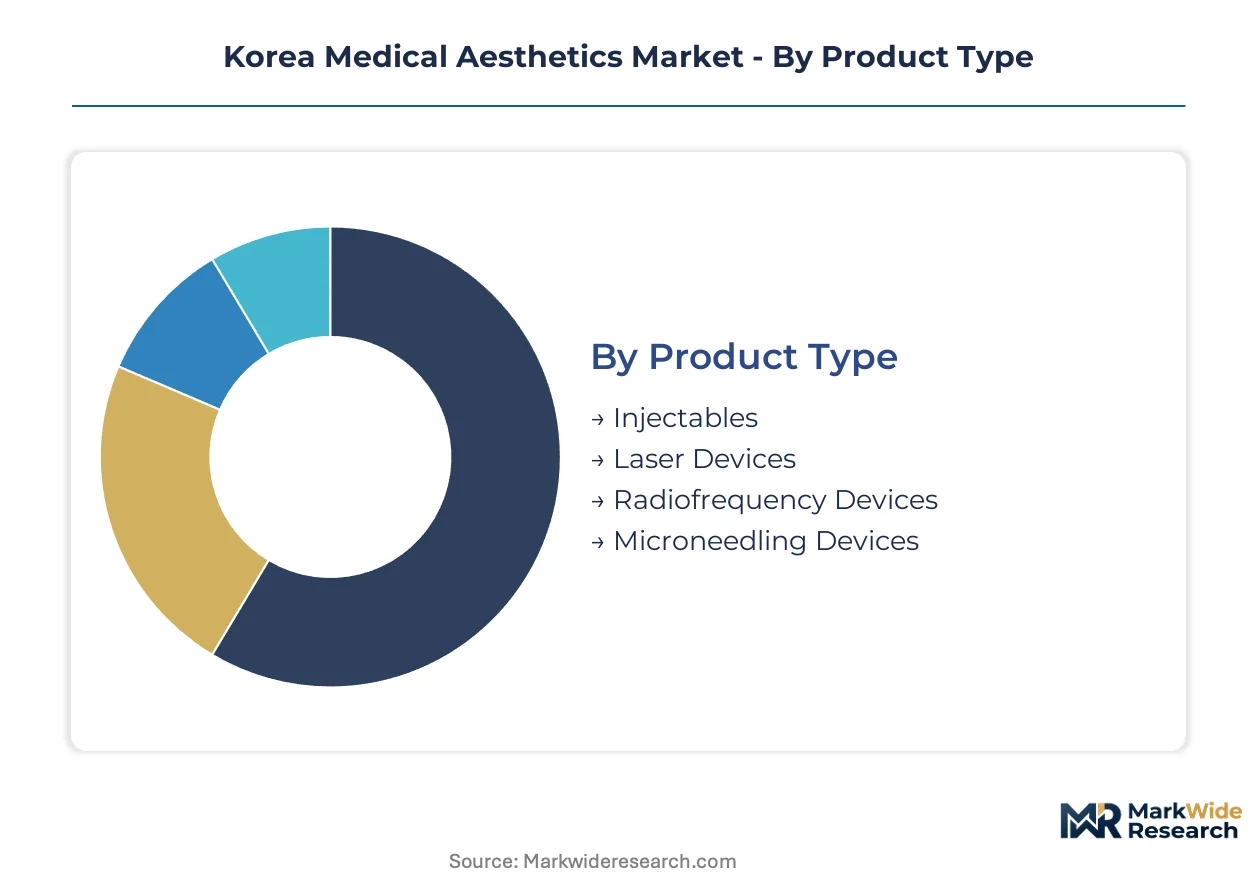
Segmentation in Korea medical aesthetics reveals distinct procurement patterns across product categories and care settings. Manufacturers align R&D investment with the technical specifications and regulatory pathways governing each segment.
Product Type:
Technical specifications differentiate competitive positioning across device and biologic categories.
- Injectables:Cross-linked hyaluronic acid gels at 20-24 mg/mL concentration dominate facial volumization procedures. Gangnam district clinics absorb premium formulations for affluent domestic consumers and medical tourists seeking immediate aesthetic outcomes.
- Laser Devices:Fractional systems operating at 1550 nm wavelength enable dermal remodeling with controlled thermal injury zones. Dermatology clinics in Seoul's satellite districts drive replacement cycles at 18-24 month intervals for these capital-intensive platforms.
- Radiofrequency Devices:Monopolar and bipolar configurations deliver controlled dermal heating for skin tightening protocols.
- Microneedling Devices:Automated pen systems and radiofrequency-integrated arrays address superficial textural concerns.
Injectables lead on scale; laser devices lead on momentum.
Application:
Procedure economics vary sharply by anatomical target and treatment frequency.
- Anti-Aging:Neurotoxin and filler protocols for facial wrinkle reduction generate repeat visit schedules at 4-6 month intervals. Physician-owned chains in Seoul concentrate capacity for this high-frequency indication.
- Skin Rejuvenation:Laser resurfacing and chemical peel combinations address photodamage and dyschromia. MFDS post-market surveillance obligations for energy-based devices elevate clinical affairs costs for manufacturers serving this segment.
- Hair Restoration:Platelet-rich plasma injections and low-level laser therapy target androgenetic alopecia.
- Body Contouring:Cryolipolysis and high-intensity focused electromagnetic platforms capture patient flow from surgical alternatives.
Anti-aging commands volume concentration; body contouring delivers margin premium.
End User:
Channel structure determines pricing power and service bundling flexibility.
- Clinics:Physician-owned dermatology and plastic surgery practices absorb the majority of injectable and energy-based device demand. Independent practices face absorption pressure from consolidating chains seeking geographic scale.
- Hospitals:Academic medical centers and general hospitals maintain surgical aesthetics capacity for complex reconstructive cases.
- Home Users:LED masks and microcurrent devices target preventive maintenance between professional treatments.
- Aesthetic Centers:Non-physician supervised facilities operate at lower price points with restricted procedural scope.
Clinics anchor revenue capture; home users expand most quickly.
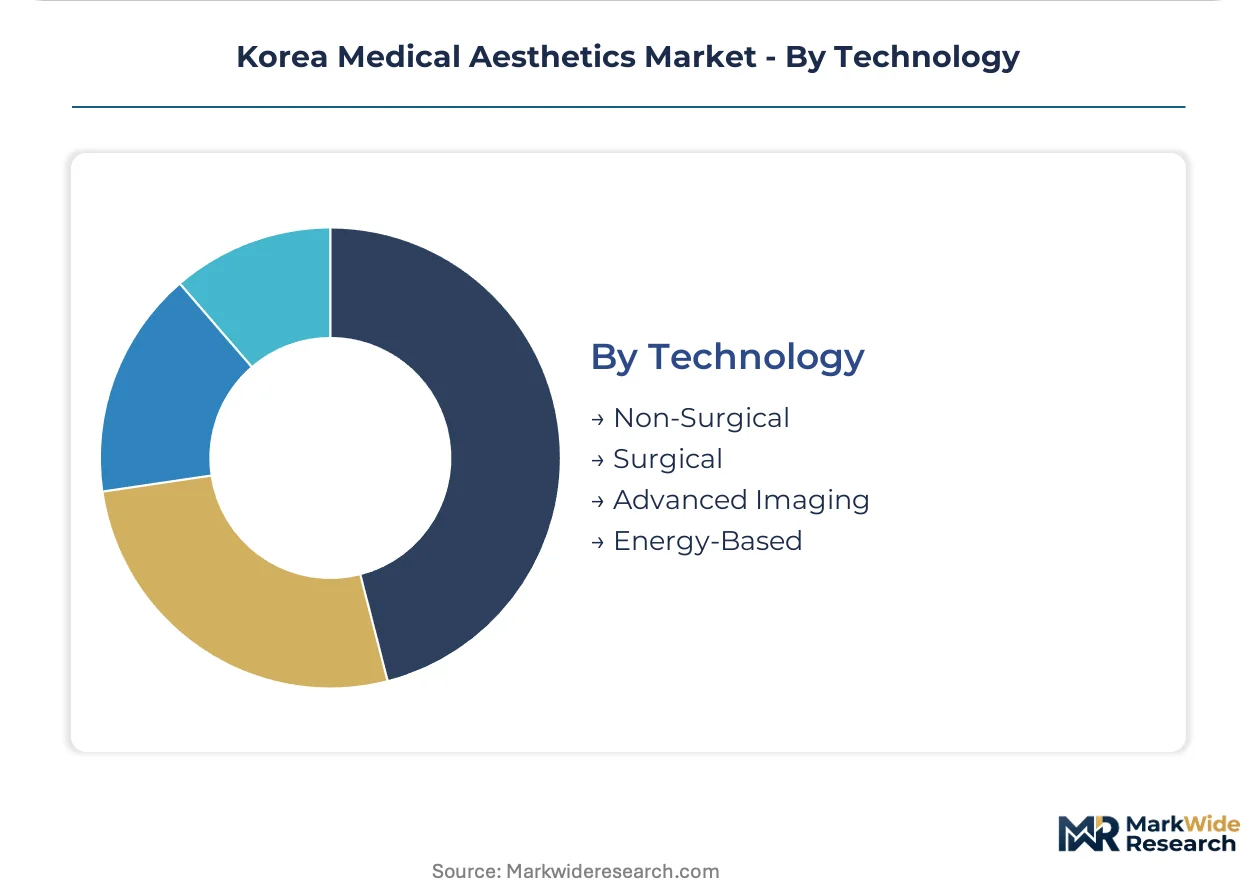
Technology:
Regulatory classification boundaries shape market access timelines and competitive entry sequencing.
- Non-Surgical:Injectable biologics and energy-based platforms deliver measurable outcomes without anesthesia requirements. MFDS accelerated pathways for novel biostimulatory fillers compress approval timelines for innovators in this category.
- Surgical:Liposuction and blepharoplasty procedures retain indication for cases beyond non-invasive device capabilities.
- Advanced Imaging:3D facial analysis systems quantify treatment outcomes and manage patient expectations pre-commitment.
- Energy-Based:Radiofrequency, laser, and ultrasound platforms displace older surgical protocols across multiple applications.
Non-surgical technologies dominate addressable volume; energy-based systems climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district concentrates Korea's medical aesthetics demand through luxury retail adjacency and medical tourism infrastructure that channels affluent Chinese and Southeast Asian consumers toward premium anti-aging packages.
Seoul Capital Area
Physician-owned chains absorb independent dermatology practices across Seoul's satellite districts, with Bundang and Songdo emerging as secondary hubs for mid-market energy-based device adoption. MFDS accelerated pathways for novel biostimulatory fillers compress approval timelines for domestic manufacturers headquartered in this region. Gangnam's concentrated hospitality infrastructure anchors foreign currency revenue streams for premium clinics serving medical tourists.
Busan-Ulsan
Korea's second-largest metropolitan area exhibits underpenetrated aesthetic clinic density relative to disposable income growth, offering acquisition targets for capitalized chains. The Korean Ministry of Health and Welfare enforces advertising restrictions that constrain direct-to-consumer marketing channels for new market entrants. Haeundae district's coastal tourism infrastructure is attracting satellite clinic locations from Seoul-based chains seeking geographic diversification.
Daegu-Gyeongbuk
Younger demographic cohorts in university districts initiate preventive neurotoxin protocols at shorter intervals than traditional therapeutic applications. KISO standards govern quality management systems for aesthetic device manufacturers with production facilities in this industrial corridor. Daegu's medical device manufacturing base supports component supply for domestic energy-based platform producers.
Daejeon-Sejong
Telemedicine pre-consultation channels for procedure education and candidacy screening are expanding reach to secondary cities from this administrative hub. The country's national pharmaceutical regulator maintains technical consultation offices in Sejong that shape classification boundaries for device-drug hybrids. Research institutes in this region collaborate with domestic manufacturers on next-generation poly-lactic acid formulation development.
Gwangju-Honam
Independent dermatology practices in this southwestern region face absorption pressure from consolidating chains with capital backing from Seoul-based investors. MFDS post-market surveillance obligations for energy-based devices elevate clinical affairs infrastructure costs for manufacturers serving this market. Honam's agricultural economy limits local disposable income concentration, restricting premium procedure penetration relative to capital region benchmarks.
Korea Medical Aesthetics Market Key Industry Players
Global majors compete with regional champions across injectable biologics and energy-based device categories, creating tiered market access dynamics where multinational R&D intensity confronts domestic manufacturing scale advantages. The vendor base stratifies across premium innovators, mid-market cost competitors, and specialized technology licensors. Three strategic archetypes dominate: biostimulatory filler specialists leveraging accelerated regulatory pathways, integrated dermatology platform operators bundling devices with consumables, and pure-play energy-device manufacturers competing on replacement cycle economics. Consolidation through physician practice acquisitions and cross-border licensing partnerships represent the dominant competitive moves reshaping market structure.
Among the named participants, Merz Pharma and Galderma exemplify the premium-tier archetype through R&D-intensive positioning in biostimulatory agents, while Hugel anchors the domestic manufacturing scale segment competing on cost structure for export markets across Asia-Pacific. These three entities represent contrasting strategic postures within Korea's medical aesthetics competitive landscape.
| Leading Market Players |
|---|
| Merz Pharma |
| Johnson & Johnson |
| Galderma |
| Sinclair Pharma |
| Hugel |
| AbbVie |
| Lumenis |
| Cynosure Lutronic |
| Allergan Aesthetics |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of pharmaceutical-grade hyaluronic acid by Korean domestic producers anchors supply security and pricing power for cross-linked filler formulations, insulating downstream injectable manufacturers from raw material allocation shocks while compressing cost structures relative to import-dependent competitors.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade HA fermentation runs through Korean manufacturer pricing schedules, with three-tier pricing structure across premium, standard, and economy levels differentiating by cross-link density and MFDS approval tier. Brand premium for biostimulatory agents resists compression while commoditized HA fillers face margin tightening due to domestic manufacturing scale expansion. Price sensitivity concentrates in mid-market dermatology chains seeking volume procurement terms, whereas Gangnam premium clinics exhibit inelastic demand for novel filler formulations.
Supply Chain Analysis
MFDS local-content requirements for medical device manufacturing reshape sourcing patterns, compelling foreign energy-device producers to establish Korean assembly operations or partner with domestic OEMs. Supply concentration centers on South Korea, China, and Japan for fractional laser componentry, with cross-linked HA polymers drawing from domestic fermentation capacity. Single-source vulnerability for 1550 nm laser diodes elevates procurement risk. Distribution runs through physician-owned clinic chains absorbing independent practices, with direct manufacturer-to-clinic relationships displacing distributor intermediaries for high-value capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Korea's medical aesthetics sector represents a late-cycle quality story as patient cohorts shift toward preventive neurotoxin protocols and premium biostimulatory fillers, demanding higher specification products with extended efficacy profiles.
For Market Incumbents: Anticipate margin compression in commoditized HA segments by accelerating backward integration into pharmaceutical-grade raw material production, while defending premium positioning through MFDS fast-track submissions for next-generation PLA/PDLLA formulations before patent cliffs erode incumbent portfolios.
For New Entrants and Emerging Players: Enter via Busan's underpenetrated clinic density relative to disposable income growth, targeting acquisition of independent dermatology practices in Haeundae's coastal tourism corridor with telemedicine-enabled pre-consultation platforms reducing patient acquisition overhead versus saturated Seoul districts.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized clinic chains because physician credentialing bottlenecks constrain qualified practitioner supply, limiting organic expansion velocity and creating scarcity value for established platforms with trained injection specialists. Long-term viability hinges on consolidation of Seoul satellite district practices with energy-device replacement cycle exposure. The signal to watch is MFDS guidance clarity on device-drug hybrid classification boundaries, which would unlock licensing value for combination product pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Fast-Track Submission | Accelerated approval compresses competitive entry timelines for novel biostimulatory fillers ahead of incumbents. |
| Physician Practice Acquisition | Consolidation of independent dermatology clinics builds geographic scale and patient retention infrastructure in secondary cities. |
| Telemedicine Pre-Consultation Platform | Virtual assessment reduces physical consultation overhead while expanding reach to domestic secondary city cohorts. |
| Domestic HA Fermentation Scale-Up | Captive raw material production insulates cost structures from pharmaceutical-grade feedstock allocation constraints. |
| Energy-Device Replacement Cycle Management | 18-24 month platform refresh schedules in satellite districts sustain recurring capital equipment revenue streams. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic operators, biomedical engineers at energy-device manufacturers, MFDS regulatory affairs specialists, and hospital purchasing committee members with secondary validation against MFDS approval databases, KISO quality management filings, Korean Ministry of Health and Welfare enforcement records, and customs trade data for aesthetic device imports. Bottom-up clinic revenue modeling and top-down manufacturer shipment data provided cross-referencing anchors.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation dimensions spanning product type, application indication, end-user channel, and technology classification. CAGRs derived from fitted growth curves incorporating MFDS approval velocity, device replacement cycle timing, and medical tourism flow patterns from Chinese and Southeast Asian source markets.
The model holds under stable MFDS regulatory frameworks and continued medical tourism infrastructure investment; deviation in combination product classification guidance or upstream HA fermentation disruptions would shift volume and pricing assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market