
 Lip Filler Market | 2026-2036
Lip Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Filler Market Analytics
Pay-per-procedure leasing of injection devices is fragmenting capital requirements for new clinic entrants. Allergan Aesthetics leverages brand equity and practitioner training networks to sustain premium positioning across developed markets. Galderma anchors its portfolio through hyaluronic acid formulations with lidocaine integration, while Merz Pharma competes via differentiated rheology profiles for precision sculpting.
Lip fillers comprise injectable gel or particulate suspensions, typically cross-linked hyaluronic acid at concentrations of 20-24 mg/mL with 0.3% lidocaine, designed for soft-tissue augmentation of the vermilion border and philtral columns. Hyaluronic acid formulations dominate current volume due to reversibility with hyaluronidase and tunable duration of nine to twelve months. Cosmetic enhancement applications command the widest addressable base, though volume restoration for age-related atrophy captures disproportionate margin pools per treatment. Biodegradable fillers lead material preferences as regulatory scrutiny intensifies around permanent implant safety profiles.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for market access. The EU AI Act and GDPR impose additional compliance layers on patient imaging databases and algorithmic treatment planning tools used in aesthetic centers. Stakeholders must monitor evolving pharmacovigilance obligations for long-acting formulations and prepare for potential reclassification of high-volume fillers as higher-risk device categories.
Market Dynamics
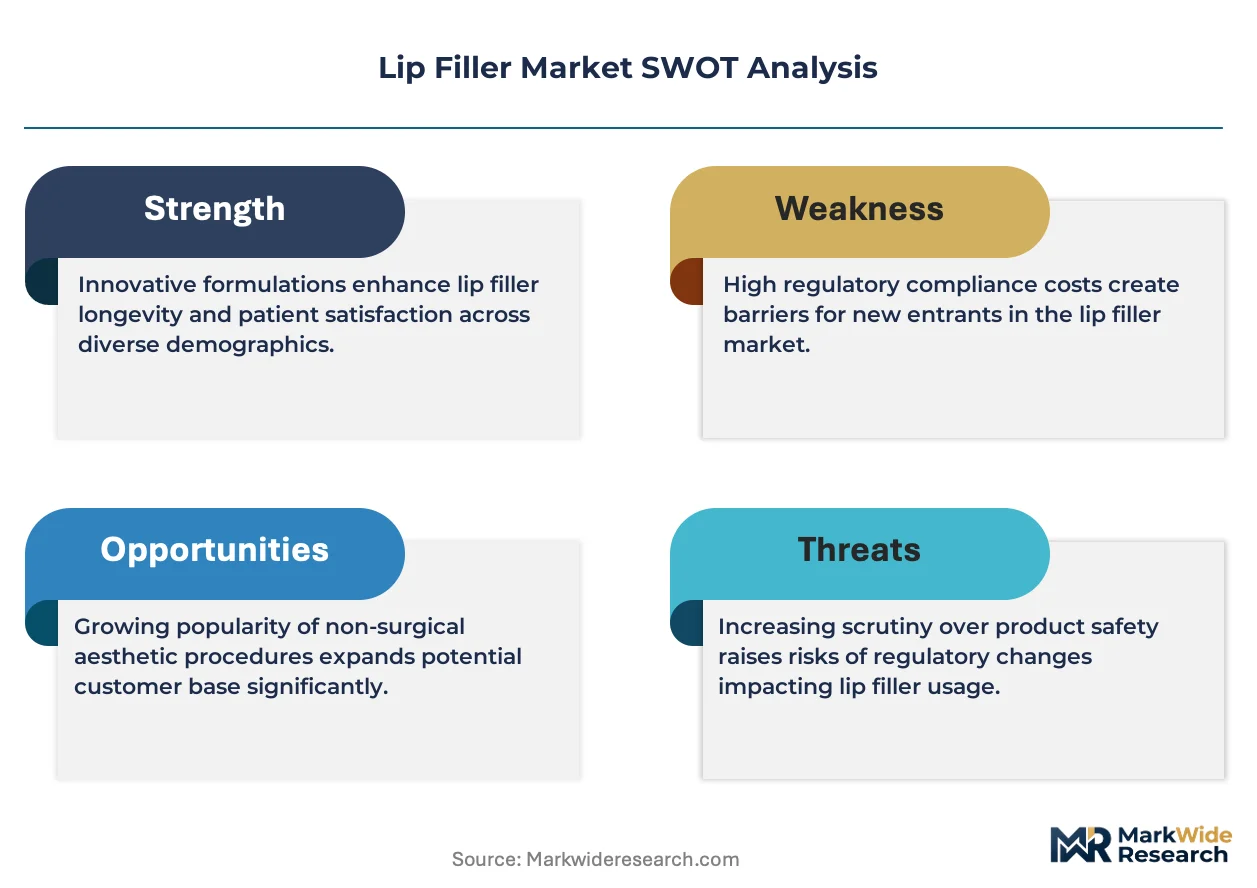
Cross-linked hyaluronic acid concentration wars are compressing formulation margins while FDA 510(k) backlog delays and EU MDR clinical evidence requirements extend product launch timelines by eighteen to thirty-six months, reshaping competitive moats around regulatory infrastructure rather than molecule novelty alone.
Growth Catalysts
- MFDS fast-track pathways:South Korea's Ministry of Food and Drug Safety accelerated approval channels for combination-device fillers, cutting time-to-market by forty percent for lidocaine-integrated formulations and positioning Seoul as a launchpad for Asian market entry.
- Combination therapy protocols:Medical aesthetic clinics are bundling lip augmentation with neurotoxin perioral treatments and laser resurfacing, lifting average transaction values and patient retention rates through integrated facial rejuvenation workflows.
- Biodegradable material preferences:Patient safety litigation against permanent implants has redirected demand toward reversibly dissolvable fillers, with hyaluronidase compatibility now a non-negotiable specification in clinic procurement criteria.
Market Restraints
- Hyaluronic acid feedstock concentration:Three fermentation suppliers control seventy percent of pharmaceutical-grade HA raw material, exposing formulation houses to price volatility and supply allocation prioritization during capacity constraints.
- CE marking clinical evidence burdens:EU Medical Device Regulation requirements for biocompatibility testing and post-market surveillance have doubled regulatory affairs headcount costs for mid-tier manufacturers seeking European market access.
- Non-surgical alternative proliferation:Topical lip plumping devices using micro-current and peptide serums are capturing price-sensitive trial users who previously constituted filler entry-level demand.
Strategic Opportunities
- Brazilian tier-two city expansion:São Paulo and Rio de Janeiro saturation contrasts with underpenetrated Belo Horizonte and Curitiba markets where disposable income growth outpaces specialist clinic availability.
- Algorithmic treatment planning convergence:3D facial imaging software paired with injection depth mapping is enabling precision dosing protocols that reduce product waste and adverse event rates.
- Men's aesthetic segment emergence:Male patient consultation rates for subtle vermilion enhancement are rising fastest in Los Angeles and London, creating demand for marketing and formulation positioning distinct from feminine beauty norms.
Industry Challenges
- Injection technique standardization gaps:No universal certification body governs cannula versus needle methodology proficiency, producing variable outcomes that damage category trust and complicate malpractice insurance underwriting.
- Hyaluronidase reversal training deficits:Vascular occlusion emergency response requires specific competency that many generalist practitioners lack, elevating liability exposure and clinic insurance premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Filler Market |
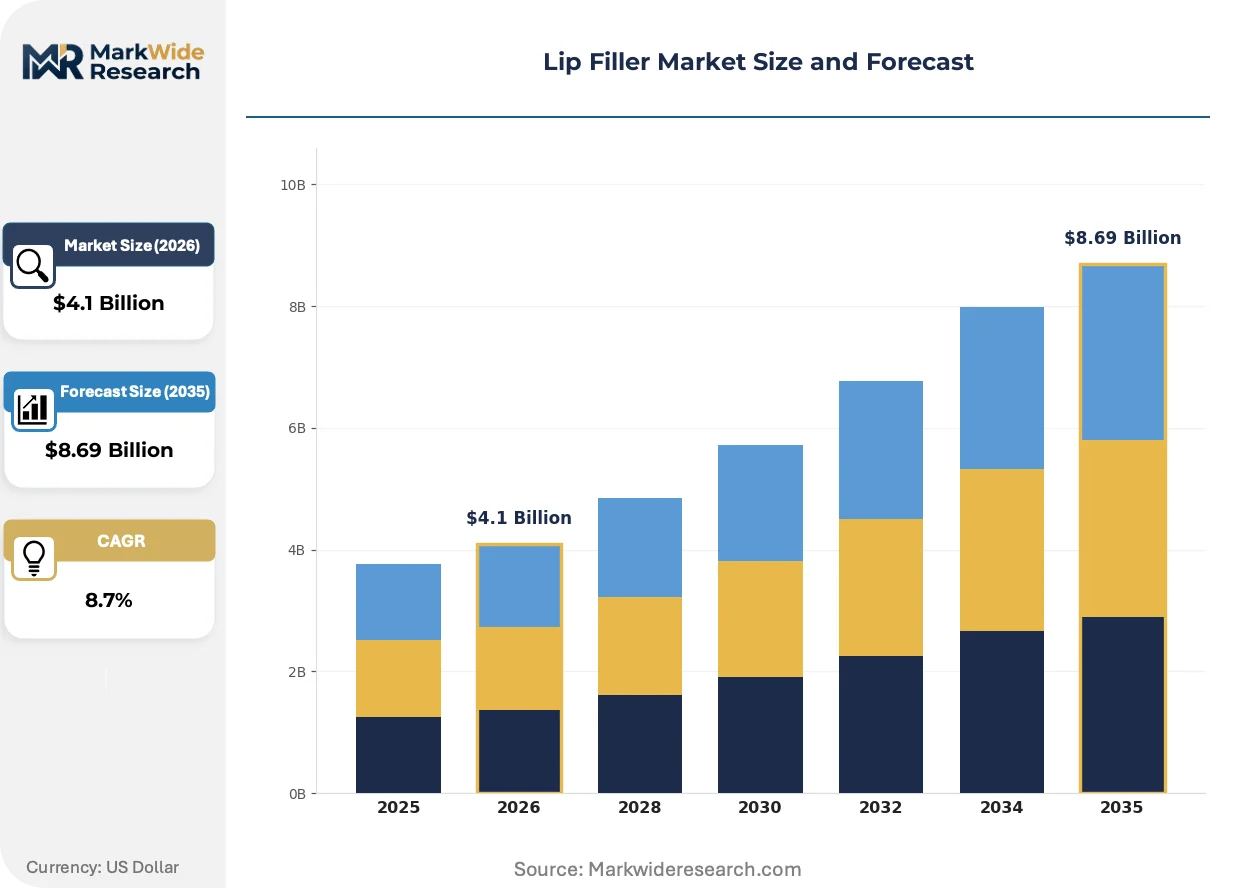
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Collagen, Calcium Hydroxyapatite, PMMA Application: Cosmetic Enhancement, Reconstructive Surgery, Lip Augmentation, Volume Restoration End User: Dermatology Clinics, Aesthetic Centers, Hospitals, Beauty Salons Material: Biodegradable Fillers, Non-biodegradable Fillers, Synthetic Fillers, Natural Fillers |
| Companies Covered | Allergan Aesthetics, Galderma, Merz Pharma, Teoxane, Revance Therapeutics, Sinclair Pharma, Zimmer Aesthetics, Revolax, Hugel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Filler Market Evolving Landscape
Product development cycles are compressing toward reversible, precision-tunable formulations while regulatory frameworks on both sides of the Atlantic harden evidence requirements for long-acting claims. Digital patient journey tools are simultaneously reshaping consultation workflows and post-procedure monitoring protocols.
Monophasic cohesive polydensified matrix technology is rendering obsolete traditional biphasic filler architectures that relied on particulate suspension rheology. High-volume aesthetic chains in the United States and United Kingdom are adopting these formulations for their reduced Tyndall effect incidence and smoother integration with native tissue. The shift is compressing demand for legacy particle-based products and rewarding manufacturers with proprietary cross-linking process patents.
EU AI Act algorithmic transparency mandates are imposing documentation burdens on clinics deploying automated facial symmetry analysis for treatment planning. Aesthetic software vendors must now maintain audit trails for recommendation logic, slowing deployment of machine learning tools in Paris and Berlin practices. The regulatory friction is diverting investment toward simpler rule-based planning systems that avoid high-risk AI classification thresholds.
Subscription membership models for maintenance dosing are displacing single-procedure pricing in metropolitan United States markets. Patients at Los Angeles and Miami clinics are locking in quarterly touch-up schedules with prepaid annual contracts, smoothing revenue predictability for practice owners. The behavioral shift is most pronounced among patients aged twenty-five to thirty-four seeking preventive rather than corrective augmentation protocols.
Lip Filler Market Segmentation
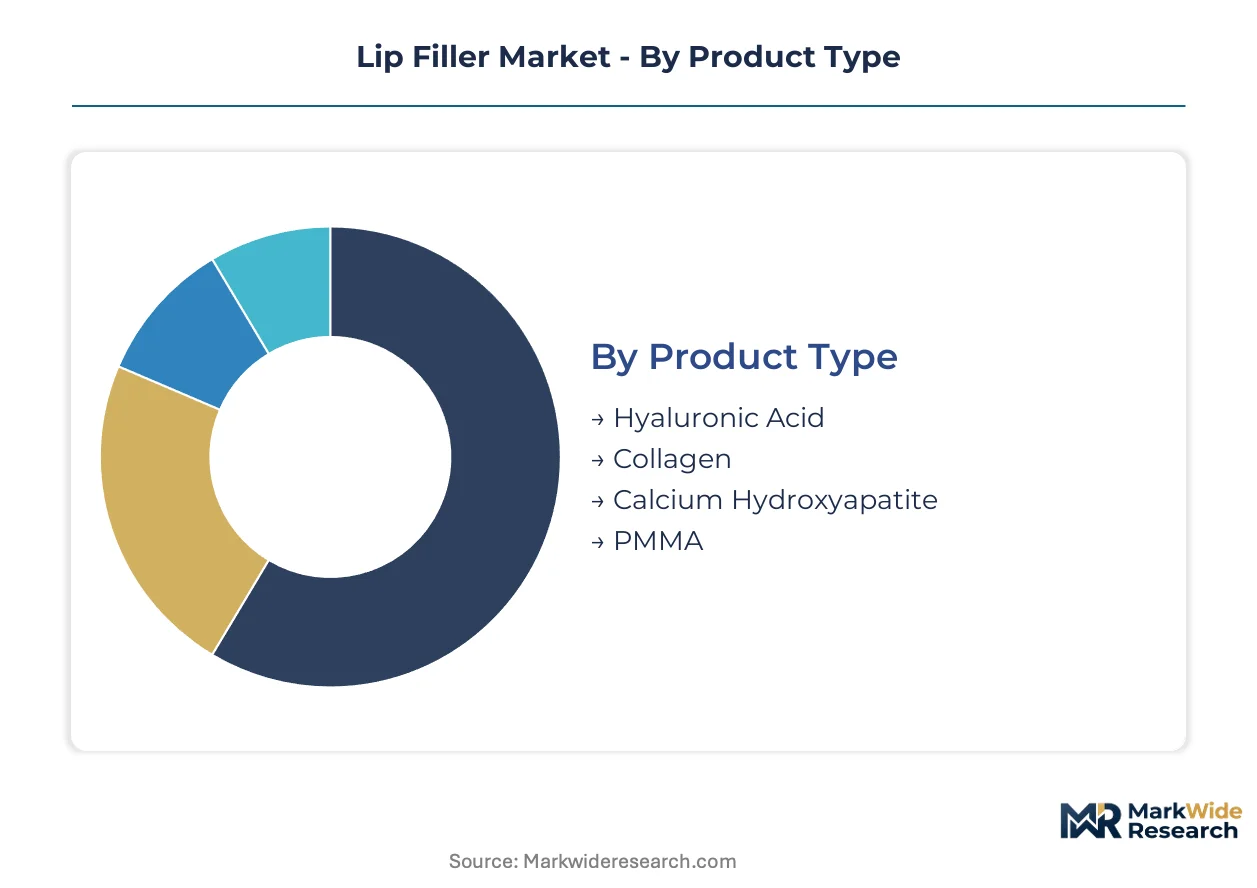
Lip filler segmentation reveals how formulation chemistry, clinical setting, and patient intent reshape procurement patterns across the value chain. Manufacturers calibrate cross-linking density and lidocaine integration differently for each application context, while regulatory pathways diverge sharply by material biodegradability.
Product Type:
Cost tier determines formulation complexity, with premium segments commanding proprietary cross-linking patents and economy tiers competing on hyaluronic acid feedstock efficiency.
- Hyaluronic Acid:Cross-linked formulations at 20-24 mg/mL concentration with 0.3% lidocaine dominate current volume due to hyaluronidase reversibility and tunable nine-to-twelve month duration. Demand concentrates in medical aesthetic clinics across the United States and South Korea where combination therapy protocols bundle lip augmentation with perioral neurotoxin treatments.
- Collagen:Bovine and human-derived matrices persist in niche reconstructive applications requiring structural scaffolding rather than volumetric expansion. Demand concentrates in hospital plastic surgery departments handling congenital defect corrections and trauma reconstruction cases.
- Calcium Hydroxyapatite:Microsphere suspensions stimulate neocollagenesis for longer-lasting correction in mature patients seeking structural rather than superficial enhancement.
- PMMA:Permanent microsphere implants retain regulatory scrutiny due to granuloma risk and irreversibility, limiting deployment to specialized reconstructive settings with informed consent protocols.
Hyaluronic Acid holds installed capacity. Calcium Hydroxyapatite is rotating up the share rankings.
Application:
Patient motivation splits between elective cosmetic pursuit and medically indicated restoration, with divergent reimbursement pathways and liability exposure shaping channel economics.
- Cosmetic Enhancement:Elective vermilion border definition and philtral column sculpting for aesthetic ideal alignment. Demand concentrates in Los Angeles, Miami, and London aesthetic centers where subscription membership models for quarterly maintenance are displacing single-procedure pricing among patients aged twenty-five to thirty-four.
- Reconstructive Surgery:Post-oncologic, trauma, or congenital defect restoration requiring structural support and functional symmetry. Demand concentrates in academic medical center plastic surgery departments where FDA 510(k) cleared devices face stringent institutional review.
- Lip Augmentation:Volume increase procedures using injectable gels or particulate suspensions for aesthetic proportion adjustment.
- Volume Restoration:Age-related atrophy correction capturing disproportionate margin pools per treatment due to higher product volumes and specialized technique requirements.
Cosmetic Enhancement captures the widest patient base. Volume Restoration delivers the steepest expansion trajectory in per-treatment value.
End User:
Facility type dictates regulatory compliance burden, with hospital settings facing Joint Commission oversight while independent clinics navigate state medical board variations.
- Dermatology Clinics:Physician-supervised settings with established dermal filler protocols and malpractice insurance frameworks. Demand concentrates in metropolitan United States markets where algorithmic treatment planning software enables precision dosing and reduced adverse event rates.
- Aesthetic Centers:Dedicated cosmetic facilities bundling lip fillers with laser resurfacing and neurotoxin workflows. Demand concentrates in São Paulo, Rio de Janeiro, and emerging tier-two Brazilian cities where disposable income growth outpaces specialist availability.
- Hospitals:Integrated health systems handling reconstructive cases with institutional procurement committees and value-analysis committees.
- Beauty Salons:Non-medical settings facing regulatory restriction in most jurisdictions, limited to topical plumping devices and peptide serums rather than injectable deployment.
Dermatology Clinics hold installed capacity. Aesthetic Centers are rotating up the share rankings.
Material:
Biodegradability determines reversibility, safety profile, and regulatory classification trajectory as pharmacovigilance obligations intensify for long-acting formulations.
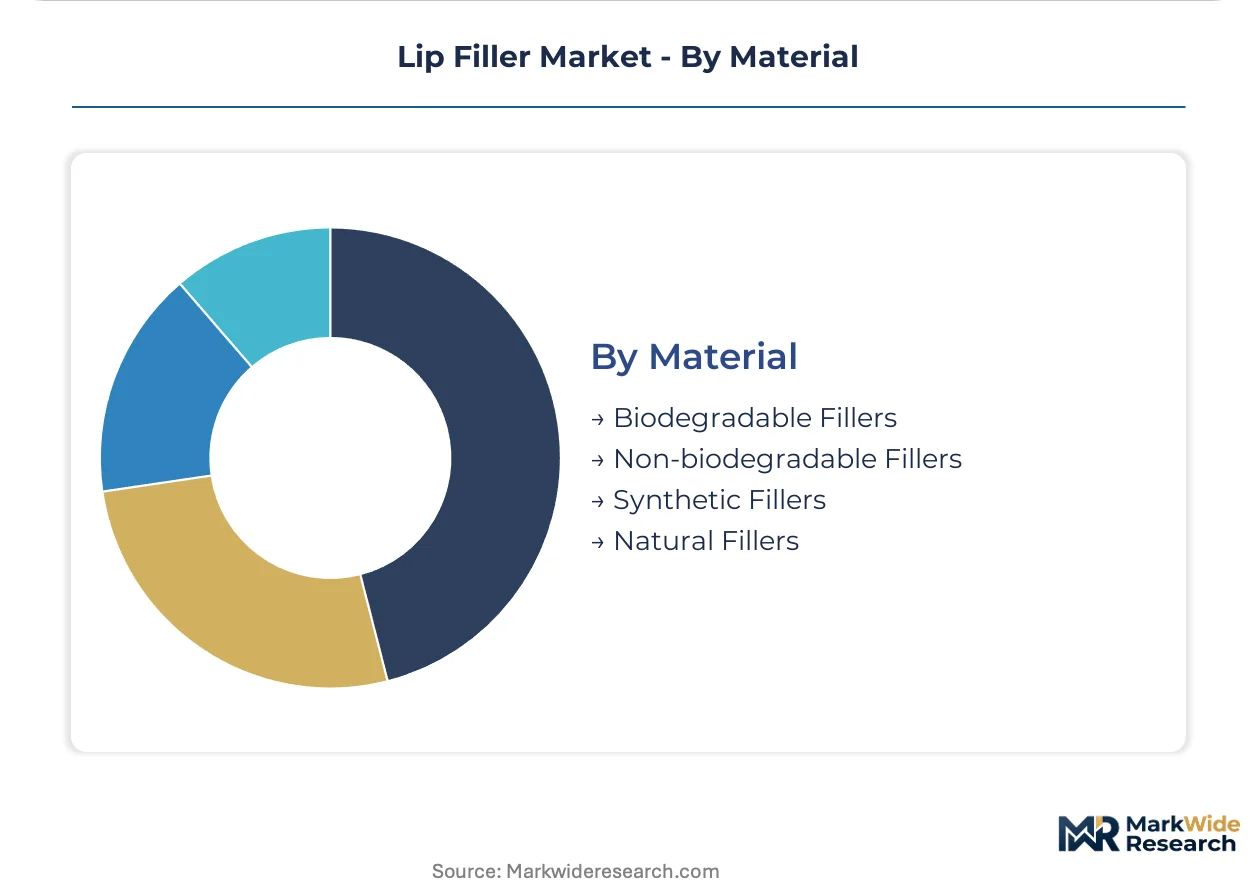
- Biodegradable Fillers:Hyaluronic acid and collagen matrices dissolve naturally or via enzymatic reversal with hyaluronidase. Demand concentrates across all major markets as patient safety litigation against permanent implants redirects procurement criteria toward dissolvable specifications.
- Non-biodegradable Fillers:PMMA and silicone implants retaining permanent presence with associated granuloma and migration risks. Demand concentrates in reconstructive niches with extensive informed consent documentation.
- Synthetic Fillers:Laboratory-engineered polymers with controlled degradation profiles and batch-to-batch consistency.
- Natural Fillers:Autologous fat transfer and processed biological matrices avoiding synthetic foreign body response.
Biodegradable Fillers hold installed capacity. Synthetic Fillers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical aesthetic clinics in the United States, South Korea, and Brazil concentrate the highest procedure volumes, with patient archetypes spanning preventive millennials in Los Angeles to reconstructive cases in São Paulo academic centers.
United States
Subscription membership models for quarterly maintenance dosing now dominate Los Angeles and Miami aesthetic centers, locking in patients aged twenty-five to thirty-four. FDA 510(k) clearance pathways shape product development timelines and clinical evidence requirements for market access. Metropolitan clusters in California and Florida drive algorithmic treatment planning adoption, with 3D facial imaging software enabling precision dosing protocols.
South Korea
MFDS fast-track pathways for combination-device fillers have cut time-to-market by forty percent for lidocaine-integrated formulations. Seoul functions as the regional launchpad for Asian market entry, with Gangnam district clinics pioneering bundled neurotoxin and laser resurfacing protocols. The Ministry of Food and Drug Safety accelerated approval channels concentrate manufacturing partnerships in the Seoul Capital Area.
Brazil
São Paulo and Rio de Janeiro saturation contrasts with underpenetrated Belo Horizonte and Curitiba markets where disposable income growth outpaces specialist clinic availability. ANVISA regulatory frameworks govern import licensing for hyaluronic acid formulations. Tier-two city expansion in Minas Gerais and Paraná states captures emerging middle-class demand for cosmetic enhancement procedures.
Germany
EU Medical Device Regulation clinical evidence requirements have doubled regulatory affairs headcount costs for mid-tier manufacturers seeking European market access. Berlin and Munich aesthetic centers deploy post-market surveillance systems for biodegradable filler tracking. The BfArM federal institute oversees pharmacovigilance obligations for long-acting formulations.
United Kingdom
London clinics lead male patient consultation rates for subtle vermilion enhancement, creating demand for marketing distinct from feminine beauty norms. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance tracks for CE-marked devices. Harley Street medical aesthetic clusters adopt monophasic cohesive polydensified matrix technology for reduced Tyndall effect incidence.
Lip Filler Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers, with premium positioning sustained through practitioner training networks and regulatory infrastructure depth. The market structures around three tiers: multinational pharmaceutical houses with aesthetic divisions, mid-tier European formulation specialists, and Asian fermentation-integrated manufacturers. Consolidation pressures favor players with captive hyaluronic acid feedstock or proprietary cross-linking patents. Strategic moves concentrate on M&A for regulatory dossier acquisition and geographic licensing partnerships for MFDS and ANVISA fast-track leverage.
Within the pharmaceutical-house tier, Allergan Aesthetics and Galderma occupy positions anchored by brand equity and lidocaine-integrated formulation portfolios. Merz Pharma exemplifies the precision-sculpting specialist archetype through differentiated rheology profiles. Among Asian manufacturers, Hugel represents fermentation-integrated supply chain control, while Teoxane sits within the Swiss-European premium formulation cluster.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Galderma |
| Merz Pharma |
| Teoxane |
| Revance Therapeutics |
| Sinclair Pharma |
| Zimmer Aesthetics |
| Revolax |
| Hugel |
| Others |
Value Network & Pricing Analysis
Air freight corridors linking Seoul Incheon to Los Angeles International carry pharmaceutical-grade hyaluronic acid at rates indexed to fuel surcharges, concentrating cost pass-through power among three fermentation suppliers while downstream clinics in Miami and São Paulo absorb differential landed costs through tiered service pricing.
Pricing Analysis
Cost-plus contracts with hyaluronic acid feedstock suppliers index to pharmaceutical-grade fermentation benchmarks, embedding raw material volatility directly into formulation costs. Pricing stratifies across premium, standard, and economy tiers where proprietary cross-linking patents command 40-60% markups over commodity HA alternatives. Cost compression in economy tiers is intensifying because South Korean and Chinese manufacturers are expanding fermentation capacity. Price-sensitive independent aesthetic clinics in Brazilian tier-two cities drive volume at standard tier, while premium-tier subscribers in Los Angeles and London lock in quarterly maintenance with minimal elasticity.
Supply Chain Analysis
Contract manufacturing for cross-linked hyaluronic acid concentrates in South Korea, China, and Switzerland where FDA-registered and CE-marked cleanroom facilities hold validated capacity. Pharmaceutical-grade HA raw material draws from fermentation bioreactors in China, Japan, and France, with cross-linking chemistry and aseptic filling completing in regional hubs. Single-source vulnerability runs through the three dominant fermentation suppliers controlling 70% of feedstock allocation. Distribution runs through cold-chain logistics partners serving medical aesthetic clinics, dermatology practices, and hospital plastic surgery departments with 2-8°C integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against topical lip plumping devices and peptide serums capturing price-sensitive trial users who previously entered through economy filler tiers.
For Market Incumbents: Harden regulatory dossier depth against EU MDR clinical evidence requirements that are doubling compliance costs for mid-tier competitors. Secure captive hyaluronic acid supply through backward integration into fermentation capacity or long-term offtake agreements with Korean and Japanese suppliers. Build algorithmic treatment planning capabilities to differentiate precision dosing protocols from commodity injection services. For New Entrants and Emerging Players: Belo Horizonte and Curitiba present immediate white-space opportunity where disposable income growth outpaces specialist clinic availability in Brazil's underpenetrated tier-two markets. Target male aesthetic segments in London and Los Angeles with formulation positioning and marketing distinct from feminine beauty norms. Enter through pay-per-procedure leasing models that fragment capital requirements and lower barrier to clinic adoption. For Investors and Strategic Acquirers: Fermentation-integrated Asian manufacturers with MFDS fast-track regulatory infrastructure and proprietary cross-linking patents represent priority acquisition archetypes. Long-term viability rests on regulatory dossier depth rather than molecule novelty alone as FDA 510(k) and EU MDR timelines extend. Watch for hyaluronidase reversal training certification mandates as inflection signal that would elevate liability exposure and consolidate demand toward established players with practitioner education networks.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Fast-Track Regulatory Pathway | Seoul-based manufacturers cut time-to-market by forty percent for lidocaine-integrated formulations. |
| Practitioner Training Network Expansion | Allergan Aesthetics and Galderma sustain premium positioning through certified injection technique programs. |
| Algorithmic Treatment Planning Software | 3D facial imaging paired with depth mapping reduces adverse event rates and product waste. |
| Subscription Membership Model Deployment | Los Angeles and Miami clinics lock in quarterly touch-up schedules with prepaid annual contracts. |
| Backward Integration into Fermentation | Hugel and Asian manufacturers secure pharmaceutical-grade HA feedstock against supply allocation volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, MFDS approval databases, EU MDR technical documentation, and trade customs data for hyaluronic acid feedstock. Primary interviews engaged regulatory affairs directors at formulation houses, procurement managers at aesthetic clinic chains, biomedical engineers at contract manufacturing organizations, and plastic surgeons at academic medical centers. Secondary validation drew from ANVISA import licensing records, hospital procurement databases, and GPO contract disclosures. Bottom-up procedure volume estimates from clinic-level data triangulate against top-down manufacturer shipment analytics.
Forecast inputs span cross-linked HA concentration tiers, application segments spanning cosmetic enhancement through volume restoration, end-user facility types from dermatology clinics to aesthetic centers, and biodegradability classifications across synthetic and natural material matrices. CAGRs derive from segmented procedure volume projections and per-treatment value trajectories over the projection horizon. Industry-specific inputs include MFDS fast-track approval velocity, EU MDR clinical evidence cost inflation, and male patient consultation rate shifts in Los Angeles and London.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fermentation suppliers or regulatory reclassification of high-volume fillers as higher-risk device categories would shift outcomes. Quarterly review of MFDS approval timelines, EU MDR notified body capacity constraints, and hyaluronidase reversal training certification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
India Hair Transplant Market