
 Chin Augmentation Market | 2026-2036
Chin Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Chin Augmentation Market Analytics
The EU Medical Device Regulation is pivoting implant manufacturers toward enhanced biocompatibility documentation and post-market surveillance. Stryker Corporation leverages its orthopedic materials science heritage to anchor premium silicone implant lines. Zimmer Biomet competes through specialized craniofacial portfolios that extend across hybrid surgical techniques. Johnson & Johnson sustains broad channel control through its Ethicon suturing and hemostasis ecosystems that support chin augmentation procedures.
Chin augmentation encompasses surgical and non-surgical procedures that modify mandibular projection or contour using implants, fillers, grafts, or autologous tissue transfer, typically employing silicone, polymethyl methacrylate, or hyaluronic acid compositions with specific durometer and pore-size specifications to ensure tissue integration and prevent capsular contracture. The primary commercial purpose centers on facial aesthetic proportion correction and post-traumatic reconstruction. Silicone implants dominate value capture due to established reimbursement pathways and surgeon familiarity, while hyaluronic acid fillers represent the fastest-expanding segment as dermatology practices absorb patients seeking reversible, minimally invasive alternatives. Surgical techniques retain margin concentration in hospital settings where facility fees compound procedure economics.
The FDA oversees implant biocompatibility through ISO 10993-1 testing frameworks, while the EU MDR mandates clinical evaluation reports and unique device identifiers for all chin implants placed in European markets. These regulatory structures elevate barriers for new material entrants and concentrate procurement authority among manufacturers with established quality management systems. Stakeholders must monitor evolving FDA guidance on nanoscale material characterization as next-generation surface-modified implants advance through pre-market channels.
Market Dynamics
EU MDR biocompatibility mandates are compressing the supplier base for silicone chin implants, forcing manufacturers to absorb elevated clinical evaluation costs or exit European markets entirely. This regulatory pivot concentrates procurement authority among orthopedic heritage firms with established quality management systems.
Growth Catalysts
- EU MDR Clinical Evaluation Requirements:Mandated post-market surveillance and unique device identifiers create compliance moats that protect incumbent manufacturers from low-cost entrants.
- Dermatology Practice Expansion:US outpatient clinics are absorbing patients seeking reversible hyaluronic acid alternatives, expanding addressable volume beyond traditional surgical centers.
- Surface-Modified Silicone Chemistry:Nanoscale texturing technologies reduce capsular contracture rates, extending implant lifecycle and justifying premium positioning in hospital procurement.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Raw material production clusters in Germany and Japan expose implant manufacturers to input cost volatility and geopolitical disruption.
- FDA Pre-Market Notification Burden:ISO 10993-1 testing frameworks require 18-24 month validation timelines for new material entrants, freezing innovation pipelines.
- Autologous Fat Transfer Substitution:Patient preference for permanent, implant-free outcomes diverts volume from synthetic chin augmentation in reconstructive applications.
Strategic Opportunities
- Underpenetrated Brazilian Aesthetic Market:ANVISA regulatory harmonization with ISO standards is opening procurement pathways for biocompatible implant portfolios.
- Hybrid Surgical Technique Convergence:Orthognathic surgeons are combining genioplasty with implant overlay, creating demand for anatomically contoured, patient-specific silicone geometries.
- Telemedicine Pre-Consultation Channels:Virtual surgical planning platforms are compressing patient acquisition costs for specialized craniofacial practices in South Korea.
Industry Challenges
- Craniofacial Fellowship Pipeline Constriction:US residency programs graduate fewer than 50 specialized surgeons annually, creating procedural bottleneck despite patient demand.
- MDR Technical Documentation Burden:Clinical evaluation report preparation consumes 12-18 months of regulatory affairs capacity, delaying product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chin Augmentation Market |
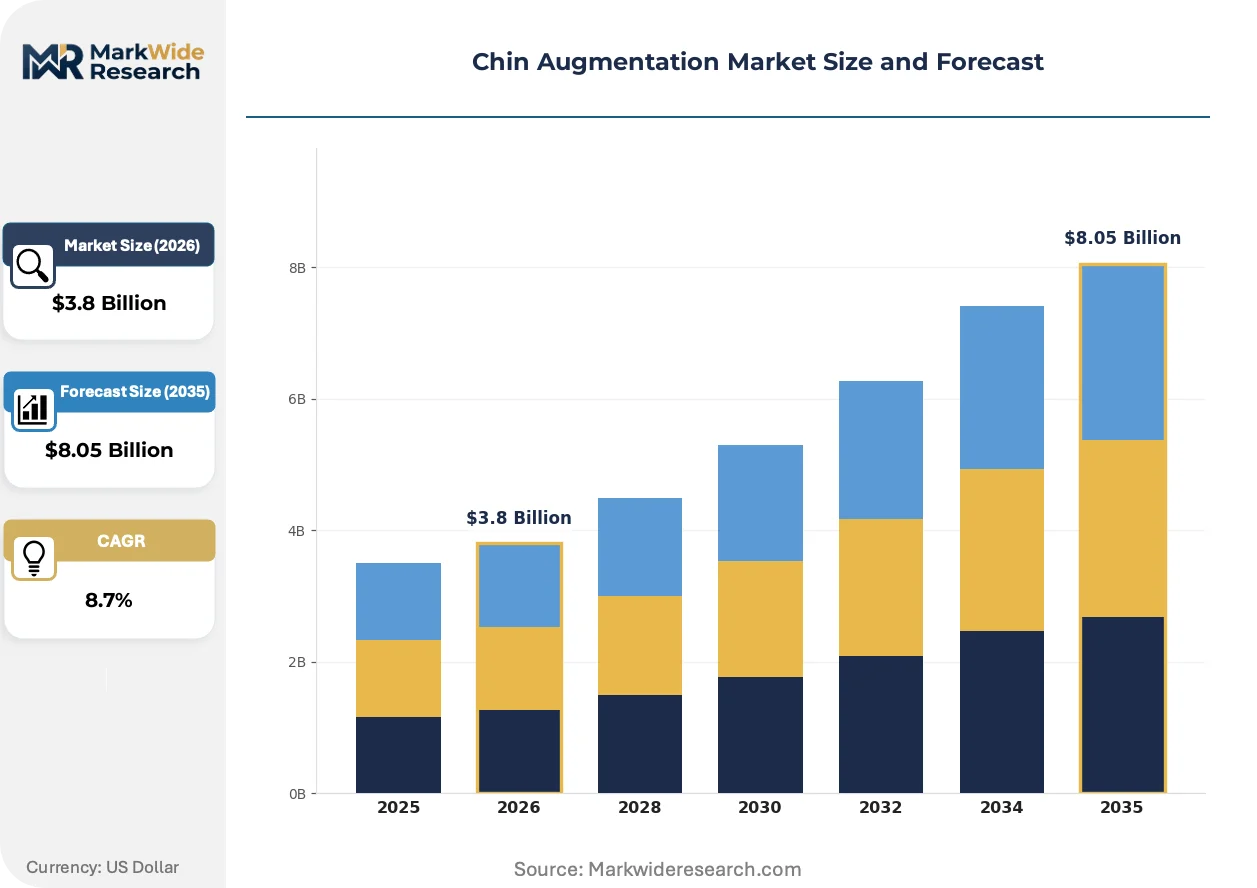
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Fillers, Injectable, Grafts Material: Silicone, Polymethyl Methacrylate, Hyaluronic Acid, Calcium Hydroxylapatite Technique: Surgical, Non-surgical, Hybrid, Autologous End User: Clinics, Hospitals, Cosmetic Surgery Centers, Dermatology Practices |
| Companies Covered | Stryker Corporation, Johnson & Johnson, Zimmer Biomet, Medartis AG, Sientra Inc., New York Plastic Surgical Group, Westlake Dermatology & Cosmetic Surgery, Cadogan Clinics, Implantech Associates Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chin Augmentation Market Evolving Landscape
Digital surgical planning tools and surface engineering advances are compressing the gap between aesthetic outcome predictability and patient-specific anatomical variation. These converging capabilities are redrawing competitive boundaries between implant manufacturers and software-enabled surgical platforms.
Patient-specific 3D-printed polymethyl methacrylate implants are modularizing the production economics of chin augmentation. Craniofacial centers in Seoul and São Paulo are adopting these workflows at accelerating pace, collapsing the traditional distinction between off-the-shelf inventory and custom fabrication. This technology is modularizing supply chain structures by enabling point-of-care manufacturing that bypasses centralized sterilization and distribution networks.
The EU MDR's enhanced post-market surveillance requirements are forcing manufacturers to rebuild adverse event reporting infrastructure. European notified bodies are rejecting legacy technical files that lack clinical performance data, compressing the effective supplier base to firms with orthopedic materials science heritage. Silicone implant portfolios with decade-long safety databases are capturing disproportionate procurement share in German and French hospital systems.
Reversible hyaluronic acid protocols are fragmenting patient acquisition patterns across US dermatology practices. Millennial and Gen Z demographics are bypassing surgical consultations entirely, initiating treatment through medspa channels that emphasize temporary, adjustable outcomes. California and Florida aesthetic clusters exhibit the most pronounced channel shift, with injectable volume growth outpacing implant placement by multiples in coastal metropolitan markets.
Chin Augmentation Market Segmentation
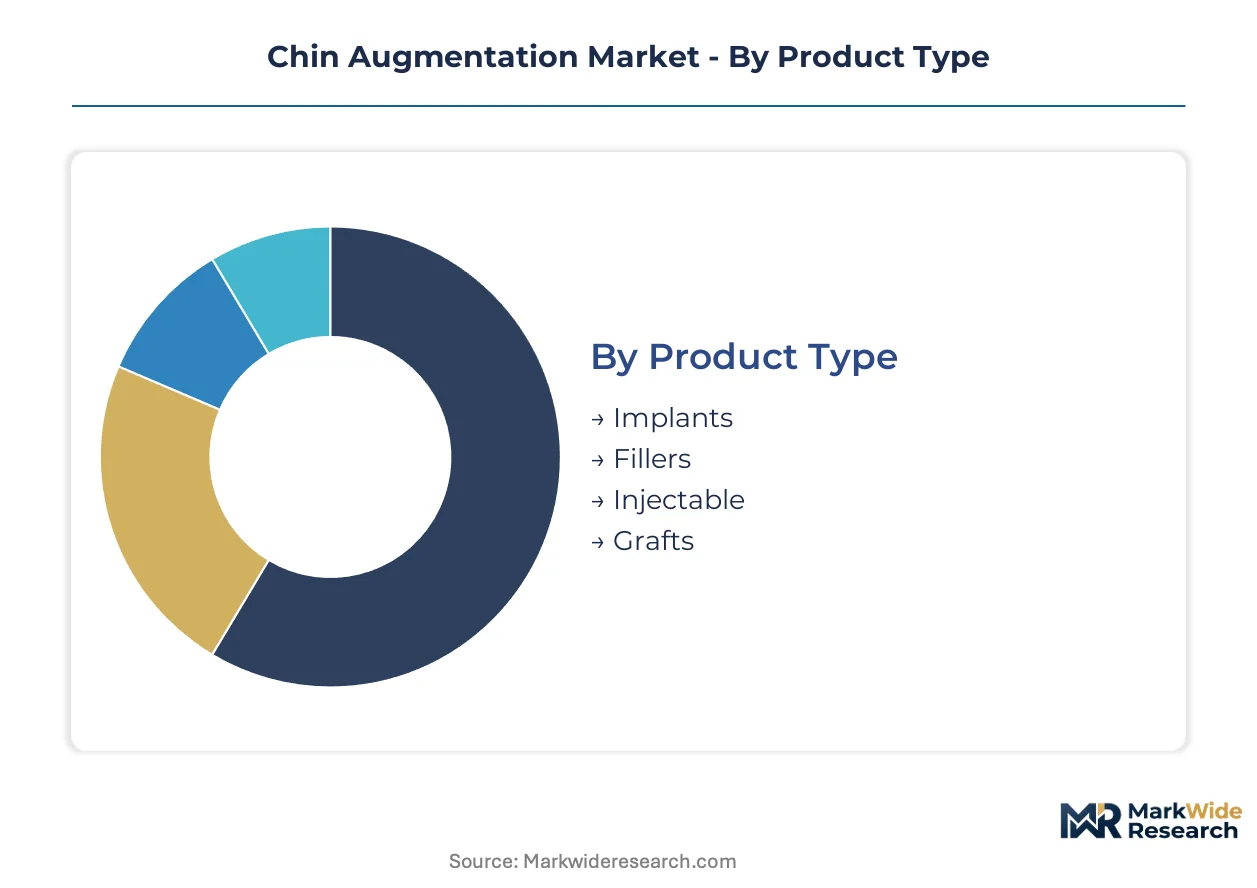
Chin augmentation procedures fragment across four distinct dimensions that determine reimbursement pathways, regulatory burden, and margin capture. Material composition and procedural setting together dictate whether manufacturers compete on surgical implant durability or dermatology practice convenience.
Product Type:
Implant manufacturing concentrates among orthopedic heritage firms with established sterilization infrastructure and biocompatibility documentation systems.
- Implants:Solid silicone or porous polyethylene constructs with specific durometer ratings and surface texturing to ensure tissue integration. Demand clusters in hospital operating rooms where facility fees compound procedure economics and surgeon preference favors permanent, reversible solutions. FDA 510(k) clearance pathways favor established implant geometries, freezing design innovation among incumbent manufacturers.
- Fillers:Cross-linked hyaluronic acid or collagen-stimulating compounds delivered via cannula or needle. Dermatology practices in California and Florida absorb the fastest volume growth as millennial patients prioritize temporary, adjustable outcomes over surgical commitment.
- Injectable:Botulinum toxin or deoxycholic acid formulations targeting submental fat reduction rather than structural projection. Medspa channels in Seoul and São Paulo drive off-label adoption for jawline contouring.
- Grafts:Autologous bone or cartilage harvested from rib, iliac crest, or calvarial sources. Reconstructive applications in craniofacial trauma centers favor grafts for post-oncologic or congenital defect correction.
Implants absorb the bulk of installed capacity; fillers are expanding most quickly.
Material:
Raw material sourcing clusters in Germany and Japan, exposing finished device manufacturers to input cost volatility and geopolitical disruption.
- Silicone:Medical-grade elastomers with Shore A durometer specifications between 20-40 and controlled pore architecture to reduce capsular contracture. German and French hospital procurement favors silicone portfolios with decade-long European safety databases under EU MDR surveillance requirements.
- Polymethyl Methacrylate:Rigid thermoplastic with radiolucent properties enabling post-operative imaging assessment. Patient-specific 3D-printed geometries are modularizing production economics at craniofacial centers in Seoul.
- Hyaluronic Acid:Cross-linked bioresorbable polymers with variable particle size for superficial versus deep plane injection. US dermatology practices favor reversible protocols that allow aesthetic adjustment without surgical revision.
- Calcium Hydroxylapatite:Mineral-based filler with collagen-stimulating properties and radiopacity for imaging verification. Limited adoption due to granuloma risk and lack of reversal agent compared to hyaluronic acid alternatives.
Silicone commands the dominant procurement share; hyaluronic acid is climbing the fastest as channel preference shifts toward dermatology.
Technique:
Procedural reimbursement structures bifurcate between facility-fee-eligible surgical suites and office-based minimally invasive settings.
- Surgical:Open or closed approaches with subperiosteal implant placement or osseous genioplasty. Hospital-based craniofacial surgeons capture premium pricing through combined orthognathic and implant overlay procedures.
- Non-surgical:Injectable filler protocols with topical anesthesia and immediate return to activity. California medspa density correlates with highest per-capita non-surgical chin augmentation volume.
- Hybrid:Combined genioplasty with implant overlay or fat grafting with filler touch-up. Orthognathic fellowship programs graduate fewer than fifty specialized surgeons annually, creating procedural bottleneck despite patient demand.
- Autologous:Fat transfer from abdominal or flank donor sites with centrifugation and reinjection. Patient preference for permanent, implant-free outcomes diverts reconstructive volume from synthetic alternatives.
Surgical techniques retain margin concentration in hospital settings; non-surgical approaches are gaining share fastest through dermatology channel expansion.
End User:
Procurement authority concentrates among health systems with centralized implant purchasing committees and established vendor credentialing.
- Clinics:Outpatient surgical facilities with limited overnight capability and focused aesthetic specialization. Brazilian aesthetic clinics are accelerating adoption following ANVISA regulatory harmonization with ISO standards.
- Hospitals:Academic medical centers and community hospitals with craniofacial surgery divisions. EU MDR technical documentation burdens compress the effective supplier base to firms with orthopedic materials science heritage.
- Cosmetic Surgery Centers:Dedicated aesthetic facilities with ambulatory surgical certification and direct-to-consumer marketing. US coastal metropolitan markets exhibit highest procedural density.
- Dermatology Practices:Office-based settings with injectable focus and telemedicine pre-consultation capabilities. Virtual surgical planning platforms are compressing patient acquisition costs in South Korean urban clusters.
Hospitals dominate implant procurement volume; dermatology practices are expanding most quickly for filler-based interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of medical-grade silicone concentrates in Germany and Japan, while procedural volume and consumption cluster in the United States, South Korea, and Brazil. This geographic split shapes procurement patterns and regulatory compliance burdens across distinct national frameworks.
United States
Dermatology practices in California and Florida absorb the fastest volume growth for hyaluronic acid fillers as millennial patients prioritize reversible outcomes. FDA ISO 10993-1 testing frameworks extend 18-24 month validation timelines for new material entrants. Greater Boston and New York Metro host the densest concentrations of craniofacial fellowship programs, yet graduate fewer than fifty specialized surgeons annually.
Germany
German hospital procurement favors silicone implant portfolios with decade-long European safety databases under EU MDR surveillance requirements. The EU MDR mandates clinical evaluation reports and unique device identifiers, compressing the effective supplier base to firms with established quality management systems. The Rhine-Ruhr and Bavarian medical technology clusters anchor continental manufacturing of medical-grade elastomers.
South Korea
Seoul Capital Area aesthetic clinics drive adoption of patient-specific 3D-printed polymethyl methacrylate implants and virtual surgical planning platforms. MFDS regulates biocompatibility through harmonized ISO standards that facilitate export-oriented production. Busan-Ulsan and Daegu-Gyeongbuk host specialized craniofacial centers combining genioplasty with implant overlay techniques.
Brazil
Brazilian aesthetic clinics in São Paulo and Rio de Janeiro accelerate adoption following ANVISA regulatory harmonization with ISO standards. Patient demand for facial aesthetic proportion correction outpaces specialized surgeon availability, creating procedural bottlenecks. Minas Gerais and Paraná exhibit emerging clinic density as medspa channels expand beyond coastal metropolitan markets.
Japan
PMDA oversight of implant biocompatibility maintains stringent post-market surveillance requirements that favor incumbent manufacturers with long-term safety data. Tokyo and Osaka medical centers retain margin concentration in hospital-based surgical techniques where facility fees compound procedure economics. Nagoya-based materials suppliers expose finished device manufacturers to input cost volatility from concentrated raw material production.
Chin Augmentation Market Competitive Landscape
The competitive structure tilts toward orthopedic heritage conglomerates with established sterilization infrastructure and biocompatibility documentation systems. Three archetypes dominate: multinational medical device conglomerates leveraging materials science heritage, specialized craniofacial portfolio builders, and dermatology-focused aesthetic clinic chains. Consolidation pressure intensifies through M&A targeting quality management system capabilities, while geographic expansion into underpenetrated Brazilian and South Korean markets accelerates.
Among orthopedic heritage conglomerates, Stryker Corporation and Zimmer Biomet exemplify the materials science-to-implant pipeline that EU MDR compliance favors. Johnson & Johnson occupies a position bridging surgical implant supply and consumable ecosystems through its Ethicon suturing and hemostasis portfolios. These three entities represent the tier that captures disproportionate procurement share in German and French hospital systems where technical documentation burdens compress vendor eligibility.
| Leading Market Players |
|---|
| Stryker Corporation |
| Johnson & Johnson |
| Zimmer Biomet |
| Medartis AG |
| Sientra Inc. |
| New York Plastic Surgical Group |
| Westlake Dermatology & Cosmetic Surgery |
| Cadogan Clinics |
| Implantech Associates Inc. |
| Others |
Value Network & Pricing Analysis
Orthopedic heritage conglomerates with private-equity-consolidated manufacturing footprints anchor pricing discipline through captive silicone supply and sterilization infrastructure. Their control over German and Japanese medical-grade elastomer sourcing creates procurement leverage that smaller implant manufacturers cannot replicate.
Pricing Analysis
Margin tightening in standard-grade silicone implants reflects EU MDR clinical evaluation cost absorption by incumbent manufacturers. Three-tier pricing structure across premium surface-modified, standard smooth-walled, and economy porous polyethylene tiers separates FDA-cleared portfolios from CE-marked equivalents from ANVISA-registered alternatives. Pricing pressure stems from hyaluronic acid filler substitution in US dermatology channels. Hospital purchasing committees exhibit lowest price sensitivity; medspa operators show highest.
Supply Chain Analysis
Reverse logistics for explanted silicone implants remain underdeveloped, with most adverse-event devices discarded rather than remanufactured. Raw material production clusters in Germany, Japan, and the United States; finished device manufacturing draws from medical-grade elastomer, porous polyethylene, and 3D-printable polymethyl methacrylate feedstocks. Single-source vulnerability concentrates in Nagoya-based silicone suppliers. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-clinic aesthetic supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craniofacial fellowship bottlenecks constrain procedural capacity below patient demand, propping implant pricing power despite filler substitution threats.
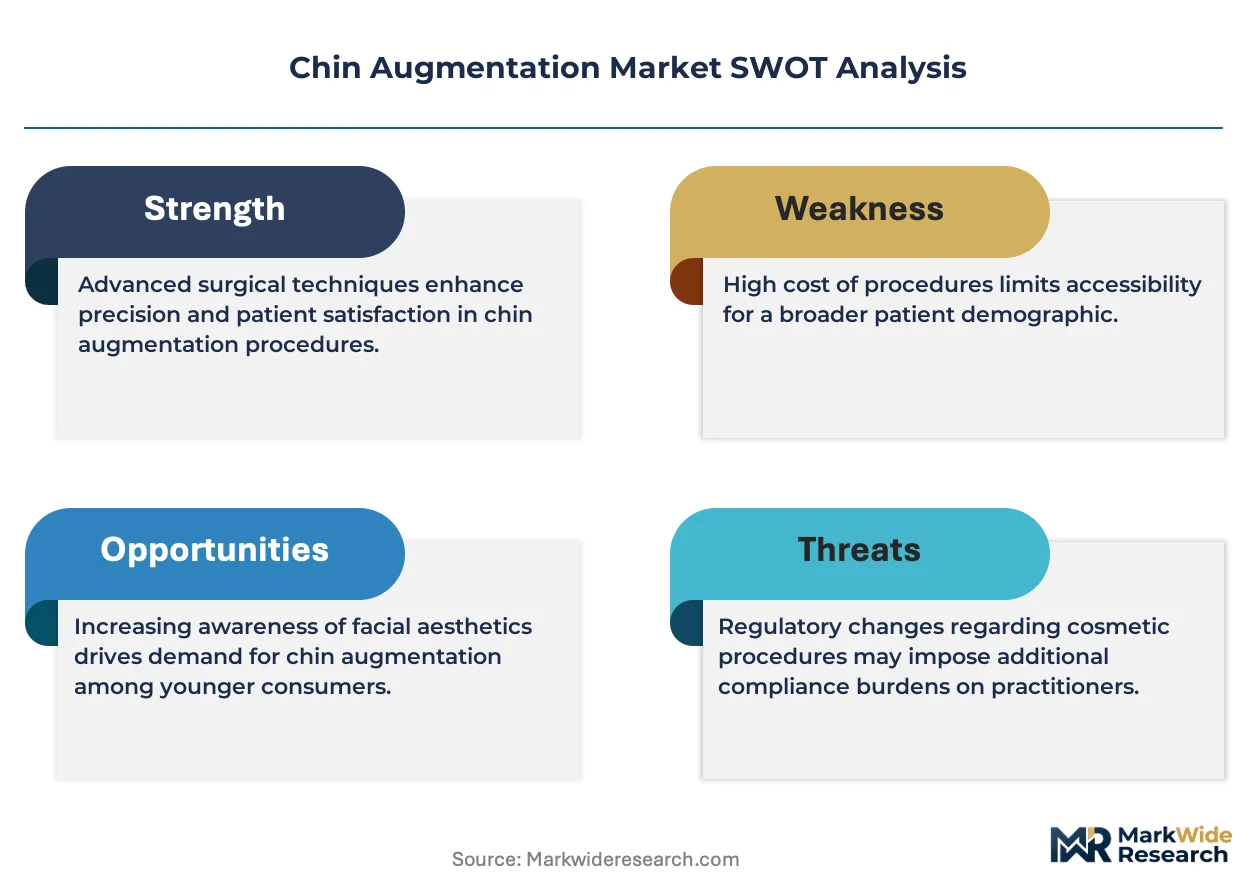
For Market Incumbents: Cement EU MDR compliance moats by accelerating clinical evaluation report preparation for next-generation surface-modified geometries. Deepen backward integration into German medical-grade silicone supply to insulate margins from raw material volatility. Channel control through Ethicon suturing ecosystems at US academic medical centers defends against hyaluronic acid diversion. For New Entrants and Emerging Players: Dermatology practice chains in São Paulo and Rio de Janeiro offer the most penetrable entry point following ANVISA harmonization with ISO standards. Patient-specific 3D-printed polymethyl methacrylate workflows bypass centralized sterilization infrastructure. Go-to-market through telemedicine-enabled pre-consultation platforms compresses patient acquisition costs below traditional surgical marketing spend. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap implant manufacturers with incomplete EU MDR technical documentation in German hospital supply networks. Long-term viability hinges on orthopedic materials science heritage and decade-long safety databases. Monitor MFDS export certification timelines for South Korean patient-specific implant producers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Report Completion | Technical documentation moats protect procurement share in German and French hospital systems. |
| Surface-Modified Silicone Chemistry Investment | Nanoscale texturing reduces capsular contracture rates and justifies premium hospital pricing. |
| Telemedicine Pre-Consultation Platform Launch | Virtual surgical planning compresses acquisition costs for Seoul and São Paulo craniofacial practices. |
| ANVISA Regulatory Harmonization Pursuit | ISO-aligned certification opens procurement pathways in underpenetrated Brazilian aesthetic clinics. |
| Patient-Specific 3D Printing Workflow Adoption | Point-of-care manufacturing bypasses centralized sterilization and collapses supply chain layers. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR technical documentation submissions, and ANVISA registration pathways anchored the trend analysis, supplemented by interviews with craniofacial surgeons, hospital purchasing committee members, biomedical engineers at German notified bodies, and GPO contracts managers. Secondary validation drew from FDA MAUDE adverse event database, EUDAMED device registration records, hospital procurement databases, and CMS outpatient procedure volume data. Bottom-up implant shipment tracking and top-down procedural volume estimates were triangulated.
Input-output matrices modeled demand across product type, material composition, procedural technique, and end-user setting dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted procedural volume projections and reimbursement rate trajectories. Industry-specific inputs included craniofacial fellowship graduation rates, EU notified body capacity constraints, and hyaluronic acid filler price erosion curves.
Caveats apply where FDA nanoscale material guidance revisions, EU MDR post-market surveillance requirement tightening, or Brazilian surgeon availability constraints could materially shift the outlook. Practitioners should monitor MFDS export certification acceleration and US dermatology practice consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Lip Augmentation Market