
 Oculoplastic Surgery Market | 2026-2036
Oculoplastic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Oculoplastic Surgery Market Intelligence
Aftermarket service revenue from laser maintenance and surgical instrument refurbishment is reconfiguring margin distribution across the oculoplastic device value chain. Integra LifeSciences Corporation leverages its regenerative tissue portfolio to anchor premium positioning in orbital reconstruction. Alcon Inc. sustains dominance in ophthalmic surgical consumables through intensive R&D allocation toward precision instrumentation. Bausch & Lomb Incorporated competes on brand strength in ocular surface preparation products used in pre-surgical protocols.
Oculoplastic surgery encompasses surgical interventions on the eyelids, orbit, lacrimal system, and adjacent facial structures, typically employing carbon dioxide or erbium lasers with pulse durations under 1 millisecond for tissue ablation and hemostasis. Its primary purpose restores visual function, corrects congenital or acquired deformities, and addresses periocular aesthetic concerns. Blepharoplasty leads procedure volume due to aging demographics and cosmetic demand, while robotics represents the fastest-growing technology segment as hospitals justify capital expenditure through improved suturing precision. Day surgery delivery mode captures expanding share as ambulatory surgical centers invest in ophthalmology-dedicated suites.
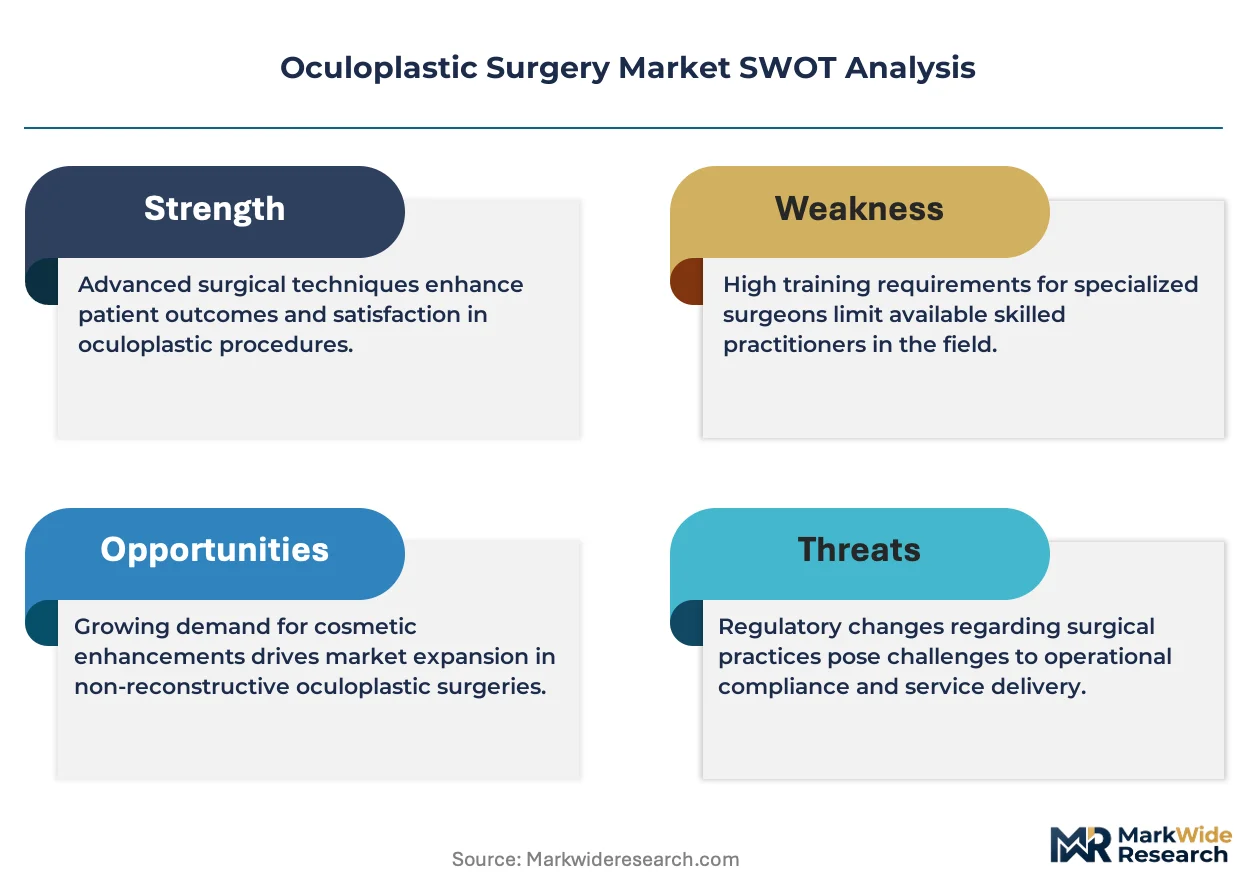
FDA 510(k) premarket notification requirements govern laser and energy-based devices, compelling manufacturers to demonstrate substantial equivalence to predicate technologies. ISO 13485 quality management standards and the EU Medical Device Regulation shape international market access and post-market surveillance obligations. The EU AI Act introduces emerging compliance dimensions for algorithmic surgical planning tools. Stakeholders must monitor regulatory divergence between FDA digital health guidance and European harmonized standards when prioritizing geographic expansion sequencing.
Market Dynamics
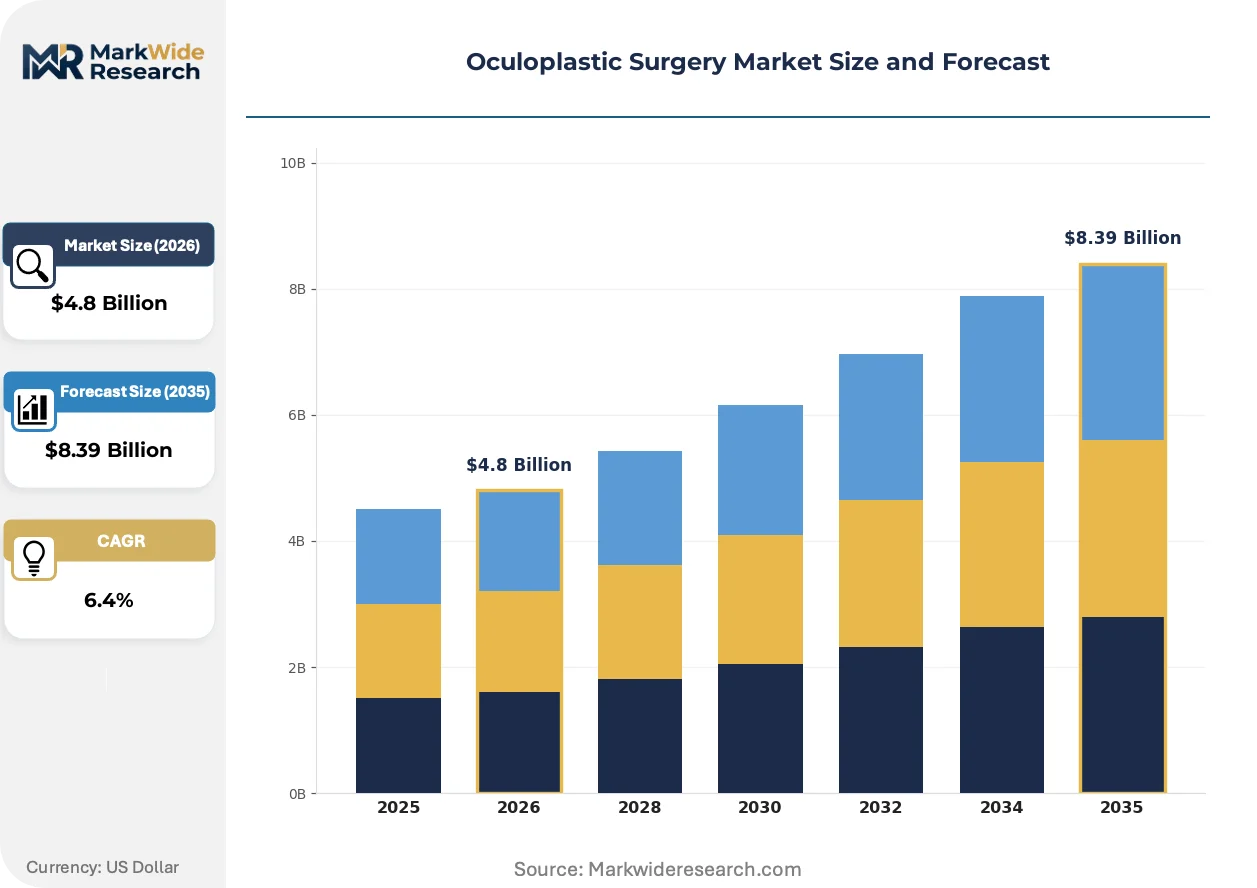
Robotic-assisted suturing platforms are compressing procedure times and forcing capital equipment refresh cycles across ambulatory surgical centers, redistributing competitive advantage toward hospitals with integrated surgical suites.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's abbreviated premarket notification pathway for laser-assisted blepharoplasty predicates accelerates device commercialization timelines for carbon dioxide and erbium laser systems.
- South Korean Medical Tourism:Seoul's Gangnam district anchors cosmetic surgery packages bundling oculoplastic procedures with recovery tourism infrastructure, drawing patients from Southeast Asia and the Middle East.
- Aging Demographics:Functional blepharoplasty demand among patients over 65 drives Medicare-reimbursed procedures addressing dermatochalasis-induced visual field obstruction.
Market Restraints
- Laser System Capital Intensity:Erbium:YAG platforms require $150,000-$400,000 initial outlay, constraining penetration in independent ophthalmology practices.
- Reimbursement Compression:CMS coding edits for cosmetic-functional procedure bundling reduce net physician compensation for combined blepharoplasty-ptosis repairs.
- Alloplastic Implant Supply Concentration:Porous polyethylene orbital implants rely on three North American manufacturers, creating vulnerability to raw material sourcing disruptions.
Strategic Opportunities
- AI-Assisted Surgical Planning:Algorithmic orbit simulation tools eligible for EU AI Act conformity assessment open premium positioning in European tertiary referral centers.
- Day Surgery Channel Expansion:Ophthalmology-dedicated ambulatory surgical centers in Texas and Florida capture migrating volume from hospital outpatient departments.
- Regenerative Tissue Integration:Acellular dermal matrix applications in eyelid reconstruction address unmet need in post-oncologic and trauma cases.
Industry Challenges
- Microsurgical Fellowship Pipeline:ACGME-accredited oculoplastic surgery fellowship positions number under 30 annually, constraining specialist supply against procedure volume growth.
- Laser Maintenance Certification:OEM-specific service technician credentials fragment aftermarket support, extending equipment downtime for multi-vendor surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oculoplastic Surgery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Blepharoplasty, Ptosis Repair, Eyelid Malposition, Orbital Decompression Delivery Mode: Inpatient, Outpatient, Day Surgery, Telehealth End User: Ophthalmology Clinics, Hospitals, Cosmetic Surgery Centers, Research Institutions Technology: Laser Surgery, Traditional Surgery, Endoscopic Surgery, Robotics |
| Companies Covered | Integra LifeSciences Corporation, Bausch & Lomb Incorporated, Carl Zeiss Meditec AG, Stryker Corporation, Alcon Inc., B. Braun Melsungen AG, Johnson & Johnson, Bolton Surgical Ltd., Lumenis Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oculoplastic Surgery Market Strategic Shifts & Innovations
Digital preoperative simulation and disposable instrument ecosystems are compressing the traditional capital-heavy surgical model toward variable-cost structures that favor high-volume operators.
Picosecond laser technology is migrating from dermatology applications into periocular resurfacing protocols. Academic medical centers in California and New York are piloting these platforms for incisional blepharoplasty adjuncts. The technology is migrating from aesthetic dermatology into functional oculoplastic suites by demonstrating reduced thermal injury profiles in Fitzpatrick skin types IV-VI.
The EU AI Act's risk-classification framework for algorithmic surgical planning tools imposes conformity assessment obligations on software-enabled orbit measurement systems. Device manufacturers must maintain technical documentation and post-market monitoring for Class IIa and IIb decision-support algorithms. European notified bodies are prioritizing ophthalmic surgical planning modules for streamlined review under harmonized standards.
Patients are bundling functional and aesthetic procedures into single operative episodes, compressing the traditional separation between medically necessary and cosmetic reimbursement categories. Ambulatory surgical centers in South Korea and Brazil are responding with packaged pricing models that obscure line-item procedure costs. This consumption-pattern shift concentrates volume in integrated practices offering simultaneous ptosis repair and cosmetic blepharoplasty.
Oculoplastic Surgery Market Segmentation
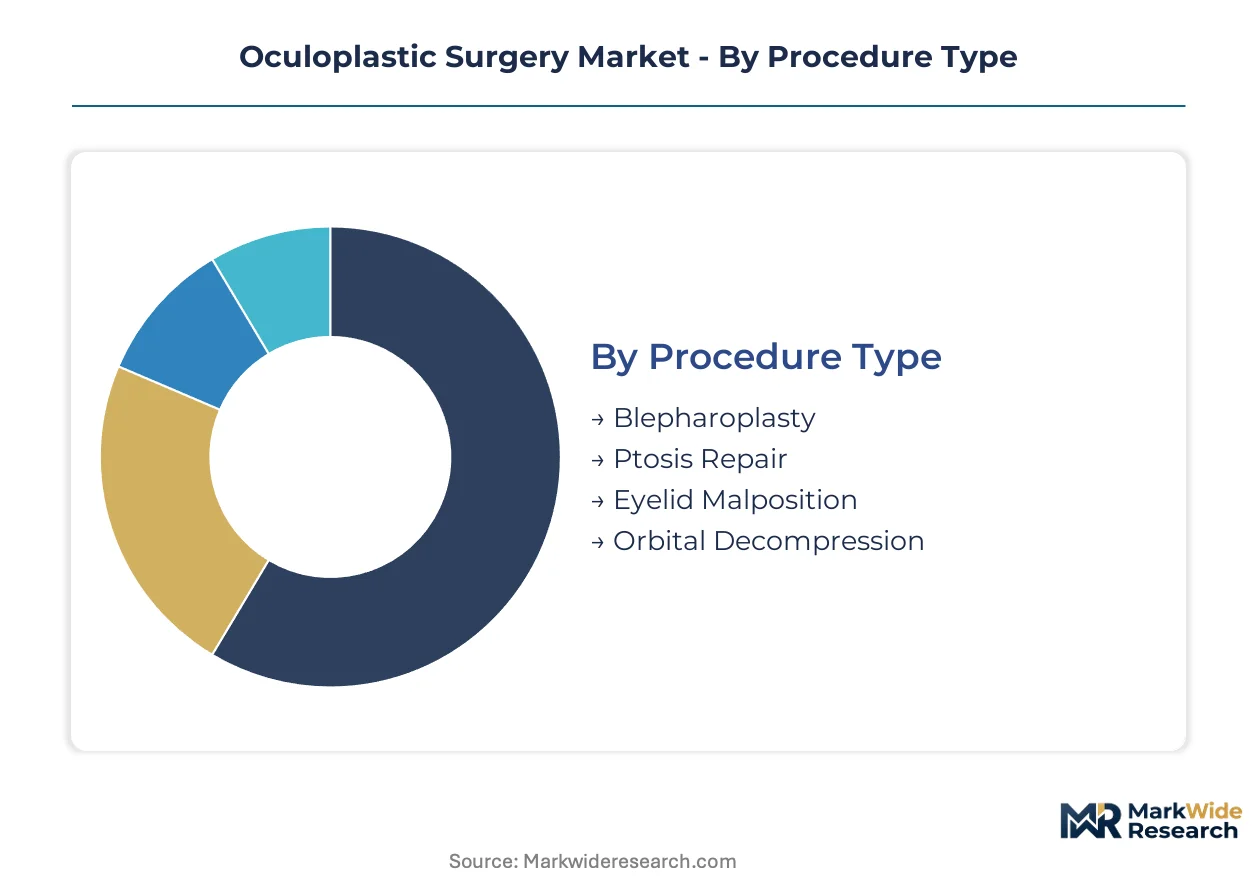
Segmentation in oculoplastic surgery reveals how reimbursement pathways, capital intensity, and patient acuity redistribute procedure economics across settings. Distinct technology and delivery-mode combinations create divergent margin profiles that shape competitive positioning.
Procedure Type:
Application focus determines reimbursement coding complexity and the balance between cosmetic self-pay and functional third-party coverage.
- Blepharoplasty:Upper and lower eyelid tissue resection addresses dermatochalasis and periocular aging. Demand concentrates in US Medicare populations for functional cases and South Korean cosmetic surgery corridors for aesthetic bundling, driven by aging demographics and medical tourism infrastructure.
- Ptosis Repair:Levator muscle resection or advancement corrects upper eyelid drooping. Academic medical centers in Germany and Japan capture complex congenital and acquired cases, constrained by ACGME-accredited fellowship scarcity limiting specialist supply.
- Eyelid Malposition:Entropion and ectropion correction restore lid margin apposition.
- Orbital Decompression:Bony wall removal relieves compressive optic neuropathy in thyroid eye disease.
Blepharoplasty commands the established base. The steepest expansion runs through orbital decompression as biologic therapy prevalence for thyroid eye disease increases surgical candidacy screening.
Delivery Mode:
Cost tier stratification separates capital-intensive inpatient infrastructure from variable-cost ambulatory models.
- Day Surgery:Dedicated ophthalmology suites in ambulatory surgical centers enable same-day discharge with reduced overhead. Texas and Florida ASCs capture migrating volume from hospital outpatient departments, propelled by CMS site-neutral payment differentials and surgeon equity participation.
- Outpatient:Hospital-based procedures without overnight stay accommodate moderate-complexity cases. South Korean cosmetic surgery clusters bundle oculoplastic procedures with recovery tourism, leveraging packaged pricing that obscures line-item costs.
- Inpatient:Overnight stay for complex orbital trauma or post-oncologic reconstruction.
- Telehealth:Preoperative screening and postoperative monitoring extend geographic reach.
Outpatient retains the largest procedure count. Day surgery is climbing the fastest as ASC capital formation accelerates in US Sun Belt markets.
End User:
Customer type determines purchasing authority—physician-owners versus institutional procurement—and service-line integration depth.
- Cosmetic Surgery Centers:Bundled aesthetic-functional procedures with transparent pricing. Seoul's Gangnam district anchors premium positioning, supported by government-certified medical tourism infrastructure and interpreter-coordinated recovery accommodations.
- Hospitals:Integrated surgical suites with robotic-assisted platforms. Tertiary referral centers in California and New York pilot picosecond laser adjuncts, justified by improved precision in Fitzpatrick skin types IV-VI.
- Ophthalmology Clinics:Independent practice settings with laser system constraints.
- Research Institutions:Academic medical centers driving technology validation.
Hospitals anchor high-complexity reconstruction. Cosmetic surgery centers are gaining share fastest as procedure bundling compresses traditional reimbursement category separation.
Technology:
Maturity and capital requirements segment innovators from incumbent platforms.
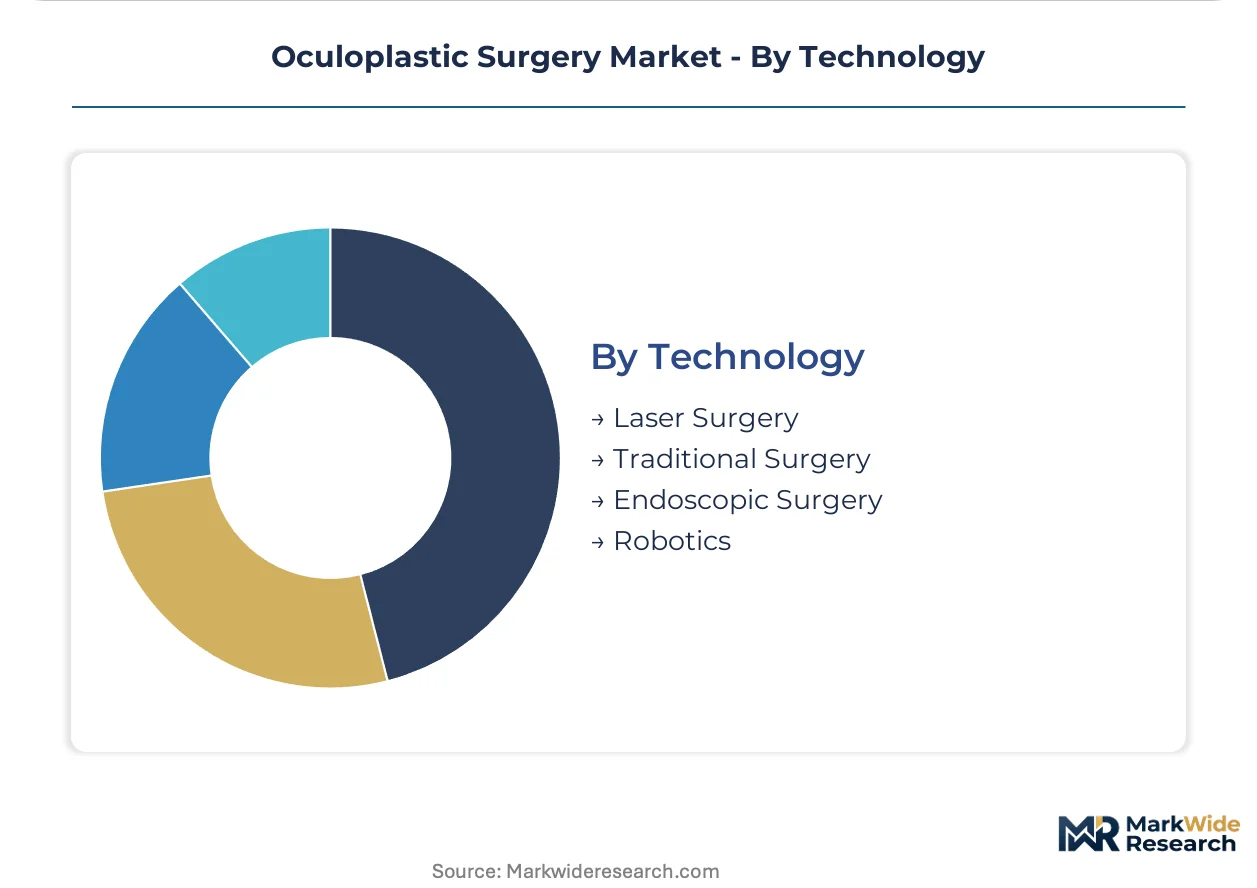
- Laser Surgery:Carbon dioxide and erbium systems with sub-millisecond pulse durations enable precise tissue ablation with hemostasis. FDA 510(k) abbreviated pathways for blepharoplasty predicates accelerate commercialization timelines for device manufacturers.
- Robotics:Suturing platforms compress operative time and improve precision. Hospitals justify capital expenditure through reduced revision rates, though Erbium:YAG platform costs of $150,000-$400,000 constrain independent practice penetration.
- Traditional Surgery:Scalpel-based techniques with established reimbursement.
- Endoscopic Surgery:Minimally invasive approaches for orbital and lacrimal procedures.
Laser surgery maintains the installed base. Robotics is expanding most quickly as integrated surgical suites amortize capital across high-volume operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes oculoplastic surgery as a medical tourism export commodity, while the United States processes it through Medicare reimbursement channels for functional cases. This demand-structure divergence shapes divergent infrastructure investments and regulatory compliance priorities across national markets.
United States
Medicare reimbursement for functional blepharoplasty drives procedure volume among patients over 65 with dermatochalasis-induced visual field obstruction. FDA 510(k) premarket notification requirements govern laser and energy-based devices, compelling manufacturers to demonstrate substantial equivalence to predicate technologies. Texas and Florida ambulatory surgical centers capture migrating volume from hospital outpatient departments, propelled by CMS site-neutral payment differentials.
Germany
Academic medical centers in Germany capture complex congenital and acquired ptosis repair cases, constrained by specialist supply scarcity. The EU Medical Device Regulation shapes international market access and post-market surveillance obligations for device manufacturers. Tertiary referral centers in Bavaria and North Rhine-Westphalia pilot advanced surgical planning technologies under harmonized European standards.
South Korea
Seoul's Gangnam district anchors cosmetic surgery packages bundling oculoplastic procedures with recovery tourism infrastructure, drawing patients from Southeast Asia and the Middle East. Government-certified medical tourism programs provide interpreter-coordinated recovery accommodations and transparent packaged pricing. MFDS regulatory pathways for laser-assisted systems support device commercialization timelines for domestic and imported platforms.
Japan
Aging demographics and aesthetic demand concentrate blepharoplasty volume in Tokyo and Osaka metropolitan corridors. PMDA approval processes for surgical devices maintain rigorous clinical evidence standards that extend time-to-market for innovators. Academic medical centers in Kanto and Kansai regions drive technology validation for precision instrumentation in Fitzpatrick skin type IV-VI populations.
Brazil
Cosmetic surgery clusters in São Paulo and Rio de Janeiro respond to patient preference for bundled functional-aesthetic procedures with packaged pricing models. ANVISA regulatory frameworks govern medical device registration and post-market surveillance for laser and energy-based surgical platforms. Ambulatory surgical centers in Southeast Brazil concentrate high-volume operators amortizing capital equipment across combined procedure episodes.
Oculoplastic Surgery Market Key Industry Players
Capability concentration sits with regenerative tissue and precision instrumentation specialists; scale advantage sits with diversified ophthalmic surgical conglomerates. The market structures around three tiers: integrated life sciences corporations with broad surgical portfolios, mid-scale device manufacturers with laser platform specialization, and regional service providers with refurbishment and maintenance capabilities. Dominant competitive moves include portfolio diversification into adjacent aesthetic-ophthalmic segments and strategic partnerships with ambulatory surgical center networks.
Among diversified surgical conglomerates, Stryker Corporation and Johnson & Johnson exemplify scale-driven positioning across capital equipment and consumable ecosystems. Carl Zeiss Meditec AG and Lumenis Ltd. occupy specialist positions in laser platform innovation, representing the precision-technology archetype that hospitals justify through improved surgical outcomes. Integra LifeSciences Corporation exemplifies the regenerative-materials tier, anchoring premium positioning in orbital reconstruction through acellular dermal matrix applications.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Bausch & Lomb Incorporated |
| Carl Zeiss Meditec AG |
| Stryker Corporation |
| Alcon Inc. |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Bolton Surgical Ltd. |
| Lumenis Ltd. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight corridors connecting South Korean device manufacturers to US ambulatory surgical centers carry laser platform components whose shipping cost volatility feeds directly into capital equipment pricing tiers and downstream procedure bundling strategies.
Pricing Analysis
Long-term service contracts dominate capital equipment procurement, with Erbium:YAG platform leases spanning 36-60 months and per-procedure consumable fees layered atop base hardware rates. Price differentiation rests on FDA 510(k) predicate lineage and ISO 13485 certification tier, with predicate-cleared systems commanding 15-25% premiums over novel predicate-seeking platforms. Cost compression in independent ophthalmology practices is intensifying because Medicare site-neutral payment differentials compress ASC reimbursement advantages. Hospital integrated delivery networks exhibit lowest price sensitivity due to capital equipment amortization across multi-specialty surgical suites, while independent single-specialty clinics face acute budget constraints.
Supply Chain Analysis
Export control regimes restricting carbon dioxide laser tube technology limit component flows from German and Japanese precision optics manufacturers to non-allied assembly facilities. Finished device assembly concentrates in the United States, Germany, and South Korea, with raw material supply drawing from rare earth processing in China, precision ceramics in Japan, and medical-grade aluminum extrusions in Germany. Single-source vulnerability pervades porous polyethylene orbital implant substrates, where three North American manufacturers control biocompatible polymer formulation. Distribution runs through GPO-negotiated hospital contracts and direct-to-ASC capital equipment sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oculoplastic surgery market is recovering from pandemic-deferred elective procedure backlogs, with cyclical momentum anchored in aging demographic-driven Medicare functional blepharoplasty volume.
For Market Incumbents: Insulate service revenue streams by capturing multi-vendor laser maintenance contracts through OEM-agnostic technician certification programs, countering third-party refurbishment entrants. Deepen backward integration into regenerative tissue matrices for orbital reconstruction, securing captive supply of acellular dermal matrices against biologics pricing volatility. For New Entrants and Emerging Players: Build out AI-assisted surgical planning modules for EU AI Act Class IIa conformity assessment, targeting European tertiary referral centers with algorithmic orbit simulation tools. The most penetrable white space sits in disposable instrument ecosystems for high-volume ASCs, with go-to-market execution through surgeon equity partnerships in Texas and Florida Sun Belt markets. For Investors and Strategic Acquirers: Mid-scale laser platform specialists with FDA 510(k) predicate libraries and established ASC channel relationships represent priority acquisition targets. Long-term viability hinges on robotics integration roadmaps and reimbursement strategy execution across site-neutral payment environments. The signal to watch is CMS coding edit frequency for cosmetic-functional procedure bundling, which would compress net physician compensation and trigger capital equipment deferral cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Abbreviated clearance pathways for laser-assisted blepharoplasty systems accelerate commercialization timelines for carbon dioxide platforms. |
| EU AI Act Conformity Pathway | Class IIa algorithmic surgical planning tools open premium positioning in European tertiary referral centers with harmonized standards. |
| ASC Network Partnership | Surgeon equity participation in Texas and Florida ophthalmology-dedicated suites captures migrating volume from hospital outpatient departments. |
| Regenerative Tissue Integration | Acellular dermal matrix applications in post-oncologic eyelid reconstruction address unmet need with premium reimbursement potential. |
| Multi-Vendor Service Certification | OEM-agnostic laser maintenance credentials fragment aftermarket support and extend equipment downtime for competitive displacement. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, CMS Medicare claims data, and EU MDR technical documentation, combining structured interviews with oculoplastic surgeons, ASC operations directors, biomedical equipment procurement managers, and laser platform service technicians. Secondary validation drew from hospital GPO contract databases, MFDS regulatory filing repositories, and medical tourism infrastructure reports. Bottom-up procedure volume estimates triangulate against top-down device shipment data across the analysis window.
Forecast inputs include aging demographic projections, Medicare reimbursement rate trajectories, and capital equipment replacement cycle assumptions. Segmentation modeling spans procedure type, delivery mode, end user, and technology maturity tiers, with CAGRs derived from regression analysis against historical procedure volume correlations. Industry-specific inputs incorporate ACGME fellowship position expansion rates and laser platform cost-per-procedure elasticity estimates.
Stress conditions across CMS site-neutral payment differential magnitude, EU AI Act enforcement timing, and South Korean medical tourism visa policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding predicate clearance pathway efficiency and ASC capital formation velocity. Material shifts in Medicare cosmetic-functional bundling policy or porous polyethylene implant supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Korea Medical Aesthetics Market