
 Inferior Vena Cava Filters Market | 2026-2036
Inferior Vena Cava Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Inferior Vena Cava Filters Market Intelligence
The development of advanced retrievable and dual-action filters with enhanced safety profiles is repositioning the market away from older, permanent filter designs. Cook Medical leverages its extensive portfolio in interventional radiology to maintain a strong presence. Boston Scientific Corporation competes on the basis of its innovative material science in nickel-titanium alloys. BD focuses on its broad distribution network to supply hospitals and ambulatory surgical centers.
An inferior vena cava (IVC) filter is a small, cage-like medical device implanted in the largest vein in the body to trap blood clots. These devices are typically constructed from non-ferromagnetic materials like nickel-titanium alloys to ensure MRI compatibility. Retrievable filters command the largest share due to their temporary nature and reduced long-term complication risks. In terms of end-users, hospitals remain the primary setting for implantation procedures, though ambulatory surgical centers are gaining traction for retrieval services.
Regulatory oversight from bodies like the US FDA, Europe's EMA, and Japan's PMDA is stringent, focusing on device retrieval rates and long-term safety data. These agencies mandate post-market surveillance studies, influencing R&D priorities toward designs with lower risks of fracture and migration. The central decision for manufacturers now revolves around balancing innovation in bioabsorbable materials against the established performance of metallic alloys.
Market Dynamics
The market's central dynamic is the clinical and commercial tension between enhancing the safety and retrievability of metallic filters and the research-intensive pursuit of fully bioabsorbable materials that eliminate the need for a second procedure entirely.
Growth Catalysts
- Advanced Filter Designs:The development of retrievable filters with features that reduce tilt, migration, and fracture is expanding their use in high-risk patient populations for pulmonary embolism prevention.
- Demographic Shifts:An aging population and rising incidence of obesity in developed nations like Germany and Japan are increasing the prevalence of deep vein thrombosis (DVT), a primary indication for IVC filter use.
- Regulatory Scrutiny:Mandates from agencies like the US FDA for post-market surveillance studies on retrieval rates are compelling manufacturers to innovate on designs that facilitate safer and more successful removal.
Market Restraints
- Device-Related Complications:Persistent risks of long-term complications, including filter fracture, embolization of fragments, and vena cava perforation, temper physician adoption and lead to litigation concerns.
- Alternative Pharmacotherapies:The increasing efficacy and safety profile of novel oral anticoagulants (NOACs) provide a strong non-invasive alternative for VTE treatment, limiting the patient pool for IVC filters.
- Cost of Retrieval Procedures:The economic and procedural burden associated with filter retrieval, including the need for specialized equipment and physician time, acts as a significant barrier for healthcare systems.
Strategic Opportunities
- Bioabsorbable Polymers:Pioneering filters made from materials like polydioxanone that degrade safely in the body offers a path to eliminate retrieval procedures and their associated long-term complication risks.
- Expansion in Underserved Geographies:Introducing IVC filter technologies into markets such as Brazil and Mexico, where healthcare infrastructure for interventional cardiology is advancing, presents a key growth vector.
- Convertible Filter Technology:Developing filters that can be converted from a permanent to a temporary state via a secondary, minimally invasive procedure could bridge the gap between current device types.
Industry Challenges
- Patient Tracking for Retrieval:Establishing effective patient follow-up systems within hospitals and ambulatory surgical centers to ensure timely retrieval of temporary filters remains a major operational hurdle.
- Intensive Clinician Training:The introduction of novel filter designs and complex retrieval techniques necessitates significant investment in training programs for interventional radiologists and vascular surgeons.
- Long-Term Biocompatibility Data:Generating sufficient long-term clinical evidence to satisfy regulators like Europe's EMA on the safety and degradation profile of new bioabsorbable materials is a protracted and costly process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inferior Vena Cava Filters Market |
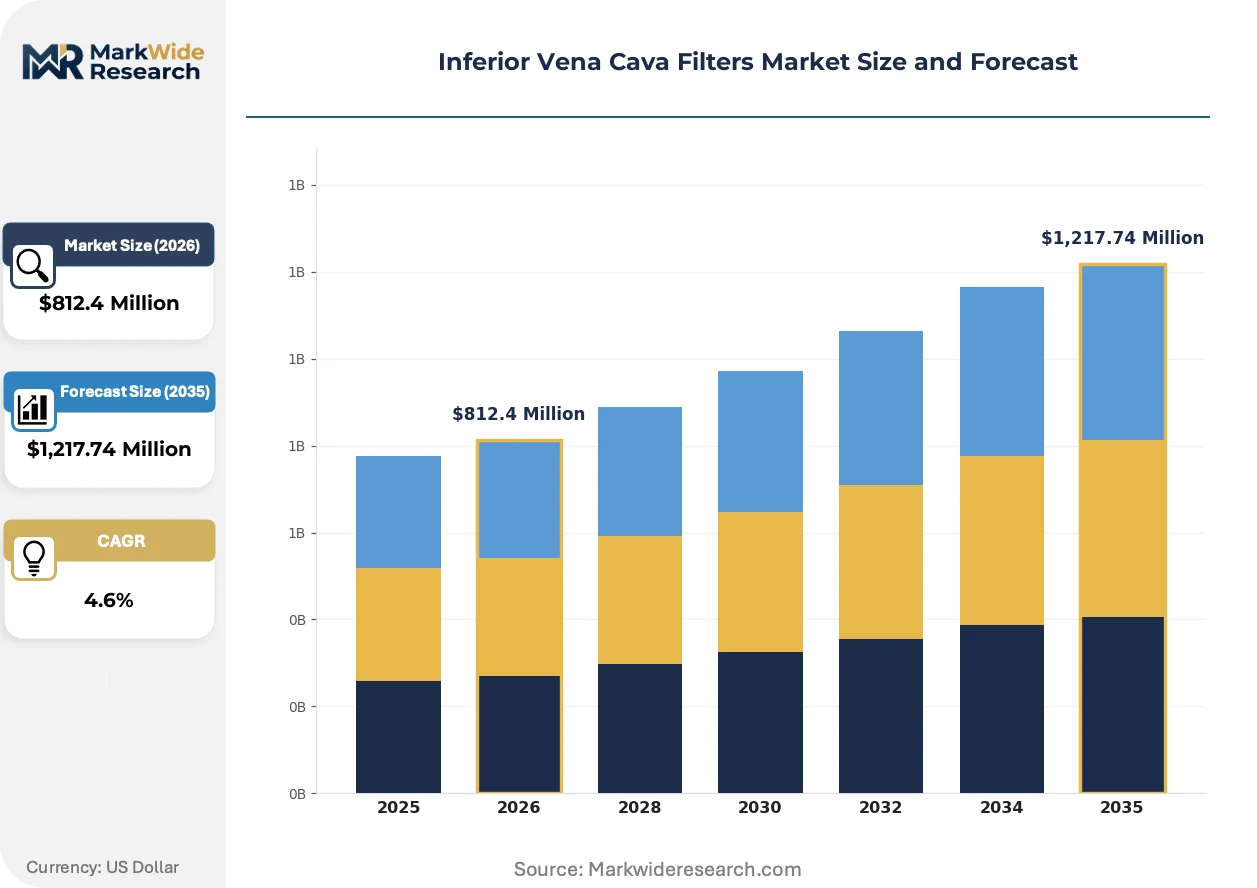
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,217.74 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retrievable Filters, Permanent Filters, Temporary Filters, Dual-action Filters End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Homecare Providers Material: Stainless Steel, Polymers, Titanium, Nickel-Titanium Alloys Delivery Mode: Transfemoral, Transjugular, Endovenous, Percutaneous |
| Companies Covered | Cook Medical, Boston Scientific Corporation, Cardinal Health, BD, Argon Medical Devices, B. Braun Melsungen, Teleflex Incorporated, Merit Medical Systems, Lifetech Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inferior Vena Cava Filters Market Strategic Shifts & Innovations
A fundamental re-evaluation of device lifespan and function defines the current innovation cycle. The market is pivoting from a focus on permanent implantation toward solutions offering temporary protection with a clear and safe exit strategy, driven by regulatory pressures and material science advances.
Smart filter technology incorporating micro-sensors or bio-markers is a significant product evolution. These devices are designed to provide real-time data on clot capture or signal the optimal window for removal. Interventional radiology departments in major academic hospitals are the primary early adopters. This technology is automating the clinical decision-making around retrieval timing, reducing dependence on inconsistent patient follow-up schedules.
Regulatory frameworks are becoming more stringent, directly influencing device design and lifecycle management. The European Union's Medical Device Regulation (MDR) requires manufacturers to provide more extensive clinical evidence of safety and performance, including higher-quality data on long-term outcomes. This impacts all devices sold in Europe, forcing companies to invest heavily in post-market clinical follow-up studies, particularly for retrievable and convertible filter categories.
A shift toward value-based healthcare is altering how these devices are purchased and managed by providers. Hospitals are increasingly moving away from simple fee-for-service implantation toward bundled payment models that include both the implantation and subsequent retrieval of the filter. This model, gaining traction in integrated health systems within the United States, incentivizes the use of filters with high retrieval success rates and encourages better patient tracking.
Inferior Vena Cava Filters Market Segmentation
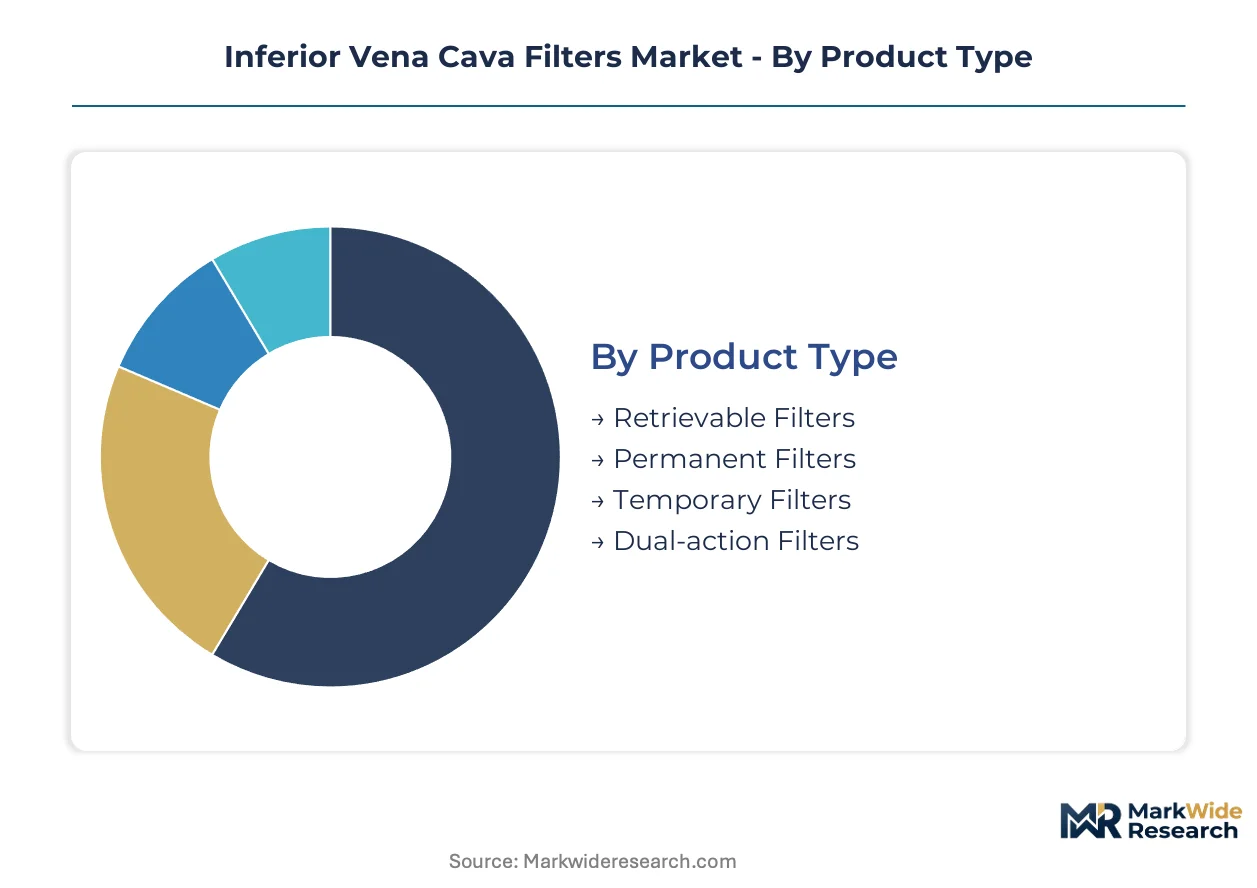
The segmentation analysis of the Inferior Vena Cava Filters Market provides a granular view of product evolution and adoption patterns. This detailed breakdown highlights the influence of material science, end-user capabilities, and procedural preferences on market dynamics. Understanding these segments is crucial for identifying areas of innovation and strategic investment.
Product Type:
The regulatory approval process for IVC filters is highly rigorous, with devices requiring extensive clinical data to satisfy bodies like the US FDA and Europe's EMA, especially concerning long-term safety and retrieval success rates.
- Retrievable Filters:These devices are designed for temporary implantation, allowing removal once the pulmonary embolism risk subsides. Their design prioritizes ease of deployment and retrieval, making them widely adopted in hospital settings due to reduced long-term complication risks.
- Permanent Filters:Intended for indefinite implantation, these filters carry higher long-term complication risks, leading to declining use.
- Temporary Filters:Similar to retrievable filters, these are designed for short-term use, requiring a subsequent removal procedure.
- Dual-action Filters:These advanced filters combine temporary and permanent design features, allowing for conversion or extended dwelling based on patient needs. Their development addresses the tension between short-term protection and long-term safety, bridging existing device types.
Retrievable Filters sit at the top of the volume ranking, with Dual-action Filters climbing the fastest.
End User:
The operational complexity and patient volume significantly differentiate demand across end-user segments, influencing device procurement and procedural training requirements.
- Hospitals:These institutions remain the primary setting for IVC filter implantation due to comprehensive infrastructure and interventional radiology suites. Hospitals require a broad range of filter types to accommodate diverse patient anatomies and manage high-risk patients.
- Specialty Clinics:These outpatient facilities perform smaller implantation volumes but contribute to follow-up care and patient tracking.
- Ambulatory Surgical Centers:These facilities are increasingly gaining traction for IVC filter retrieval procedures, driven by cost-effectiveness and patient convenience. Their focus on elective procedures allows for streamlined workflows and specialized equipment for efficient filter removal.
- Homecare Providers:Homecare services play a role in post-procedure monitoring and patient education, though not directly in implantation.
Hospitals continue to dominate implantation procedures, while Ambulatory Surgical Centers are expanding most quickly in retrieval services.
Material:
Material science underpins the performance and safety profile of IVC filters, with manufacturers investing heavily in developing biocompatible and durable alloys or bioabsorbable polymers to meet stringent regulatory standards.
- Stainless Steel:An older generation material, stainless steel filters offer good strength but are not MRI-compatible.
- Polymers:Emerging bioabsorbable polymers, such as polydioxanone, offer temporary clot protection and degrade safely within the body. Their development involves complex material engineering and extensive biocompatibility testing for predictable degradation and minimal inflammatory response.
- Titanium:Known for biocompatibility and strength, titanium is used in some permanent filter designs, offering MRI compatibility.
- Nickel-Titanium Alloys:These shape-memory alloys, often called Nitinol, are widely used for retrievable filters due to their superelasticity and MRI compatibility. They enable complex, self-expanding designs that can be precisely deployed and retrieved.
Nickel-Titanium Alloys hold a substantial market share, with advanced Polymers exhibiting the steepest expansion trajectory.
Delivery Mode:
The choice of delivery mode significantly impacts procedural invasiveness, patient comfort, and the technical skill required for successful IVC filter deployment, influencing clinical preference and adoption rates.
- Transfemoral:This common delivery route involves accessing the femoral vein in the groin, offering a straightforward approach for interventional radiologists. The larger vessel size at this site allows for easier device manipulation and deployment, making it a preferred option.
- Transjugular:Accessing the jugular vein in the neck provides an alternative delivery route, often chosen when femoral access is contraindicated or challenging. This approach can be more complex due to anatomical considerations but offers advantages in certain patient populations.
- Endovenous:This broad term refers to procedures performed within the vein using catheters, encompassing transfemoral and transjugular approaches.
- Percutaneous:This minimally invasive technique involves introducing the filter through a small skin incision, reducing recovery time and discomfort.
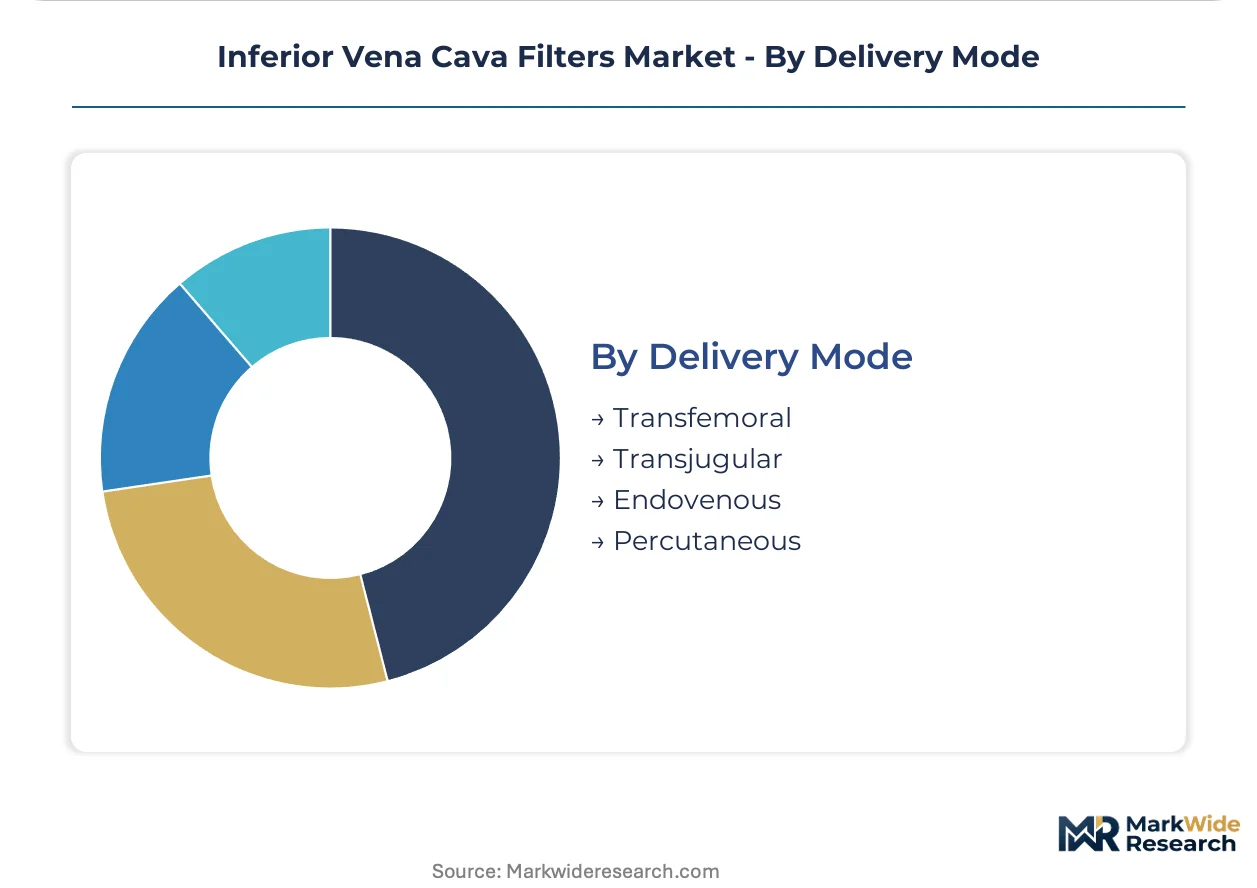
Transfemoral delivery remains the most frequently used method, while Transjugular delivery is gaining share fastest in specific clinical scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for inferior vena cava filters demonstrates distinct regional demand patterns. While the United States sees strong demand driven by an aging population and high DVT prevalence, Germany's market expansion is primarily due to advanced interventional cardiology procedures. These differing drivers highlight varying healthcare priorities and infrastructure capabilities across developed economies.
United States
The United States market for IVC filters is driven by a high prevalence of deep vein thrombosis and a robust healthcare infrastructure. The US FDA mandates stringent post-market surveillance, influencing device design towards enhanced safety and retrievability. Academic medical centers in cities like Boston pioneer novel filter deployment and retrieval techniques.
Germany
Germany exhibits significant demand for IVC filters due to its sophisticated healthcare system and an increasing elderly population requiring pulmonary embolism prevention. Europe's EMA ensures high standards for device approval and post-market follow-up under the MDR. Specialized clinics in cities like Berlin are expanding their capacity for complex filter retrieval services.
Japan
Japan's IVC filter market expansion is influenced by its rapidly aging population and a strong preference for advanced medical technologies. The PMDA ensures rigorous regulatory oversight, demanding comprehensive safety and performance data. Major hospital networks in Osaka prioritize efficient patient tracking systems to improve retrieval rates for temporary filters.
Brazil
Brazil presents a strategic opportunity for IVC filter market growth as its healthcare infrastructure for interventional cardiology continues to advance. ANVISA regulates medical devices, focusing on product quality and patient safety within the country. Major medical centers in Rio de Janeiro are expanding capabilities for specialized interventional radiology procedures.
China
China's market for IVC filters is experiencing growth, driven by a vast patient population and expanding access to modern healthcare facilities. The NMPA plays a crucial role in device approval, emphasizing clinical efficacy and safety. Interventional radiology departments in Beijing are actively adopting advanced retrievable filter technologies.
Inferior Vena Cava Filters Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers focus on niche applications and emerging technologies. The market structure for inferior vena cava filters is characterized by a mix of established medical device giants and innovative smaller players. Key strategic archetypes include diversified healthcare conglomerates leveraging broad portfolios and focused specialists pioneering bioabsorbable materials. Competitive moves across the market include strategic partnerships for technology co-development and targeted geographic expansion into underserved regions.
Within the established medical device segment, Cook Medical and Boston Scientific Corporation represent leading players with extensive product portfolios and global distribution networks. Cook Medical leverages its broad presence in interventional radiology, anchoring its position through a comprehensive range of devices. Boston Scientific Corporation occupies a strong position based on its innovative material science applications, particularly in nickel-titanium alloys. BD, a major healthcare technology company, exemplifies a player utilizing a broad distribution network to supply hospitals and ambulatory surgical centers across various regions.
| Leading Market Players |
|---|
| Cook Medical |
| Boston Scientific Corporation |
| Cardinal Health |
| BD |
| Argon Medical Devices |
| B. Braun Melsungen |
| Teleflex Incorporated |
| Merit Medical Systems |
| Lifetech Scientific |
Cost & Logistics Intelligence
The clear performance differentiation between advanced retrievable filters and older permanent designs drives distinct pricing and supply chain strategies. Premium pricing for Nitinol-based devices reflects complex manufacturing and stringent regulatory approvals.
Pricing Analysis
Capacity additions in East Asia are reshaping price floors for basic metallic IVC filters. The dominant pricing model is per-unit transactional, with prices influenced by device complexity and regulatory certification from bodies like the US FDA and Europe's EMA. Price differentiation stems from material innovation, such as bioabsorbable polymers, and comprehensive after-sales service bundles for retrieval. Pricing pressure stems from the rising efficacy of alternative pharmacotherapies; hospitals exhibit moderate price sensitivity, while ambulatory surgical centers prioritize cost-effective retrieval solutions.
Supply Chain Analysis
Rising global freight costs impact the timely delivery of specialized IVC filter components, particularly for Nitinol alloys. Geographic supply concentration for these advanced materials exists in countries like the United States, Japan, and Germany. Raw material dependencies include specialized nickel, titanium, and emerging bioabsorbable polymers like polydioxanone. Single-source vulnerability for high-purity alloys presents a structural supply chain risk; distribution runs through a direct sales force to hospitals and specialized medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Inferior Vena Cava Filters market is a late-cycle quality story, with demand shifting towards premium, retrievable, and bioabsorbable devices. This trend reflects heightened regulatory scrutiny and clinical preference for enhanced safety profiles.
For Market Incumbents:Deploy extensive R&D in bioabsorbable materials to counter the threat from long-term complication risks associated with metallic filters. Invest in clinician training programs for novel retrieval techniques to maintain market share against alternative pharmacotherapies. Leverage existing hospital relationships and broad distribution networks to defend against emerging specialized entrants. Focus on securing higher-tier regulatory approvals, such as advanced US FDA clearances, for next-generation devices.
For New Entrants and Emerging Players:Launch via strategic partnerships with ambulatory surgical centers, targeting the rapidly expanding retrieval services segment. Focus on developing convertible filter technology that bridges temporary and permanent device needs. The most penetrable segment remains underserved geographies like Brazil and Mexico, where interventional cardiology infrastructure is advancing. Emphasize innovative material science, particularly advanced polymers, as a key go-to-market angle for differentiation.
For Investors and Strategic Acquirers:Consolidation pressure builds where smaller, innovative firms develop bioabsorbable or smart filter technologies without extensive distribution. The long-term viability of the IVC filter market hinges on successful innovation in retrieval rates and reduced complications over the next decade. Acquisition targets should be specialized manufacturers with strong intellectual property in advanced materials or patient tracking solutions. Watch for increased regulatory mandates for post-market surveillance as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioabsorbable Material Development | Eliminates the need for retrieval, improving patient outcomes and reducing costs. |
| Smart Filter Technology Investment | Provides real-time data, automating clinical decision-making for optimal removal timing. |
| Global Regulatory Pathway Optimization | Accelerates market access for novel devices across diverse regulatory environments. |
| Clinician Training Program Expansion | Ensures safe and effective deployment and retrieval of advanced filters. |
| Ambulatory Surgical Center Partnerships | Expands access to cost-effective retrieval services, addressing a key restraint. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. Primary interviews included interventional radiologists, vascular surgeons, hospital procurement managers, and medical device engineers. Secondary validation drew from US FDA public databases, Europe's EMA post-market surveillance reports, and company annual filings. This approach ensured comprehensive bottom-up and top-down triangulation of market insights.
Market dimensions were modeled at the product type, end-user, material, and delivery mode level, alongside regional adoption patterns. The analytical framework integrated historical data with projected trends across the analysis window. Compound annual growth rates were derived from a detailed assessment of demand drivers and competitive dynamics. Key forecast inputs included deep vein thrombosis prevalence rates and healthcare expenditure trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory shifts or unforeseen advancements in pharmacotherapies. Projections reflect current market assumptions; potential changes in healthcare policy or material science breakthroughs could revise future forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Tissue Expanders Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Oxygen Delivery Systems Market