
 North America Insulin Syringe Market | 2026-2036
North America Insulin Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulin Syringe Market Analytics
Polypropylene is consolidating its position as the dominant barrel material across disposable insulin syringes, displacing older polystyrene formulations that carried higher brittleness risk at thin-wall geometries. Becton Dickinson leverages captive resin sourcing and in-house molding to sustain margin control across its safety syringe portfolio. Cardinal Health anchors hospital group purchasing organization contracts, while Embecta Corp. specializes in diabetes-dedicated manufacturing infrastructure spun from its legacy parent.
An insulin syringe is a calibrated disposable injection device comprising a graduated polypropylene barrel, elastomer plunger seal, and stainless steel cannula, designed to deliver precise unit-dosage of insulin subcutaneously. Manufacturing employs high-speed injection molding with cavity-pressure monitoring to maintain ±5% dose accuracy across millions of units. Safety syringes lead volume due to OSHA bloodborne pathogen compliance requirements, while prefilled syringes capture expanding margin pools as biologic insulin analogs shift toward ready-to-administer formats. Pen needles compete directly in home care settings where convenience preferences favor integrated delivery systems.
FDA 510(k) clearance pathways and OSHA's Bloodborne Pathogens Standard shape product design mandates, requiring retractable or shielded needle mechanisms for clinical settings. Health Canada and Mexico's COFEPRIS impose parallel but non-identical sterilization validation requirements that fragment regulatory submission strategies. Stakeholders must monitor pending EPA per- and polyfluoroalkyl substance restrictions on fluoropolymer lubricants used in plunger coatings, as reformulation timelines could disrupt established supply qualifications.
Market Dynamics
OSHA's Bloodborne Pathogens Standard and FDA safety-engineered device mandates are compressing legacy syringe architectures while accelerating retractable-needle and shielded-mechanism adoption across clinical procurement channels.
Growth Catalysts
- Type 1 Diabetes Prevalence:Rising autoimmune diagnoses in pediatric and young-adult populations across the United States and Canada are expanding the addressable patient base requiring multiple daily injections.
- Home Care Migration:Payer pressure and patient preference are shifting administration from hospitals to residential settings, driving unit volume in retail and mail-order pharmacy channels.
- Biologic Insulin Analog Expansion:Concentrated and ultra-long-acting formulations require precision delivery devices, creating pull for calibrated high-accuracy syringes with enhanced graduation legibility.
Market Restraints
- Polypropylene Resin Concentration:Gulf Coast petrochemical corridor disruptions expose molding operations to feedstock volatility and force majeure allocation protocols.
- Stainless Steel Cannula Supply:Precision-drawn needle tubing from specialized European and Asian metallurgical suppliers creates single-source vulnerability for North American finished-device manufacturers.
- Pen Needle Substitution:Integrated insulin pen systems capture convenience-driven patients in home care settings, eroding standalone syringe unit demand despite lower per-dose cost.
Strategic Opportunities
- Mexico Manufacturing Expansion:COFEPRIS regulatory alignment with FDA quality system requirements enables maquiladora-based production serving US distribution with reduced logistics cost.
- Prefilled Syringe Format Migration:Ready-to-administer biologic insulin presentations reduce medication error risk and capture premium positioning in specialty pharmacy channels.
- Safety Mechanism Innovation:Passive-activation shield designs that deploy without user intervention address OSHA compliance while reducing needlestick injury liability exposure.
Industry Challenges
- Fluoropolymer Lubricant Reformulation:EPA per- and polyfluoroalkyl substance restrictions threaten plunger coating chemistries, requiring multi-year supply qualification timelines.
- Injection Molding Talent Scarcity:High-speed cavity-pressure monitoring expertise concentrates among aging workforce cohorts, constraining capacity expansion at precision medical device molders.
- Dual Regulatory Validation:Health Canada sterilization requirements diverge from FDA 510(k) pathways, fragmenting submission strategies and extending time-to-market for cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulin Syringe Market |
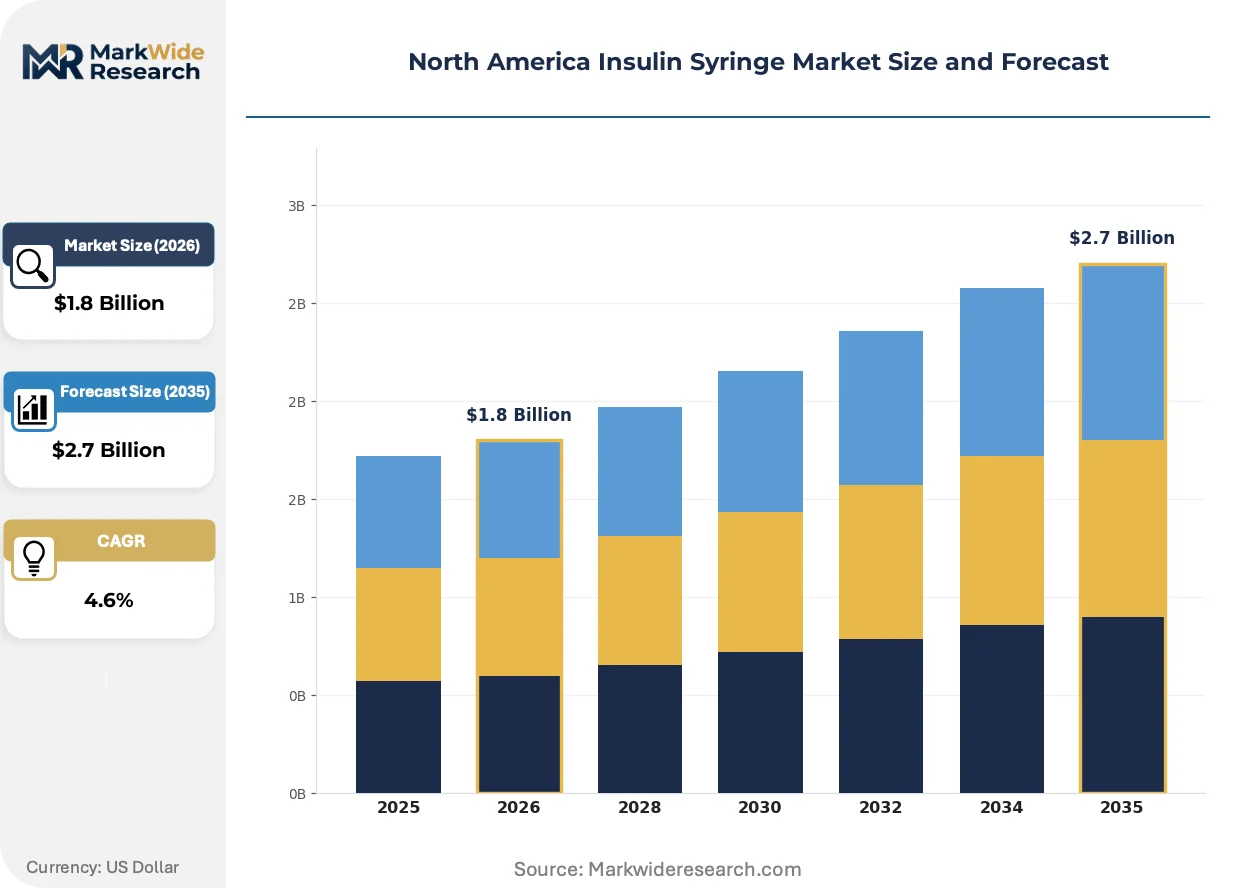
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Pen Needles, Safety Syringes, Prefilled Syringes End User: Hospitals, Home Care, Clinics, Diabetes Management Centers Material: Plastic, Glass, Stainless Steel, Biodegradable Materials Packaging Type: Bulk Packaging, Individual Packaging, Blister Packaging, Cartons |
| Companies Covered | Becton Dickinson, Cardinal Health, Ultimed Inc., Trividia Health Inc., Arkray Inc., Embecta Corp., Terumo Corporation, Nipro Corporation, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulin Syringe Market Evolving Landscape
Active needlestick prevention mechanisms, connected device integration, and patient-administered biologic formats are restructuring competitive requirements across the North American insulin delivery landscape.
Connected safety syringes with Bluetooth-enabled dose logging are integrating into remote patient monitoring platforms used by US endocrinology practices. Large health systems in Texas and California are piloting these devices for Medicaid populations with documented adherence challenges. The technology is integrating adherence data into electronic health records, enabling outcome-based reimbursement contracts with regional payers.
EPA restrictions on per- and polyfluoroalkyl substances are forcing reformulation of plunger lubricant coatings previously dependent on fluoropolymer chemistry. Device manufacturers are qualifying silicone-based alternatives through accelerated aging protocols to maintain USP Class VI biocompatibility. Canadian manufacturers face parallel PMRA environmental assessments, creating staggered compliance timelines across the integrated North American supply base.
Specialty pharmacy direct-to-patient distribution is consolidating procurement authority previously dispersed across retail chains and durable medical equipment suppliers. CVS Specialty and OptumRx are mandating specific safety-engineered configurations for their diabetes formularies, displacing hospital purchasing cooperative influence. This concentration is most visible in California and Florida, where integrated delivery networks have ceded home care device selection to pharmacy benefit managers.
North America Insulin Syringe Market Segmentation
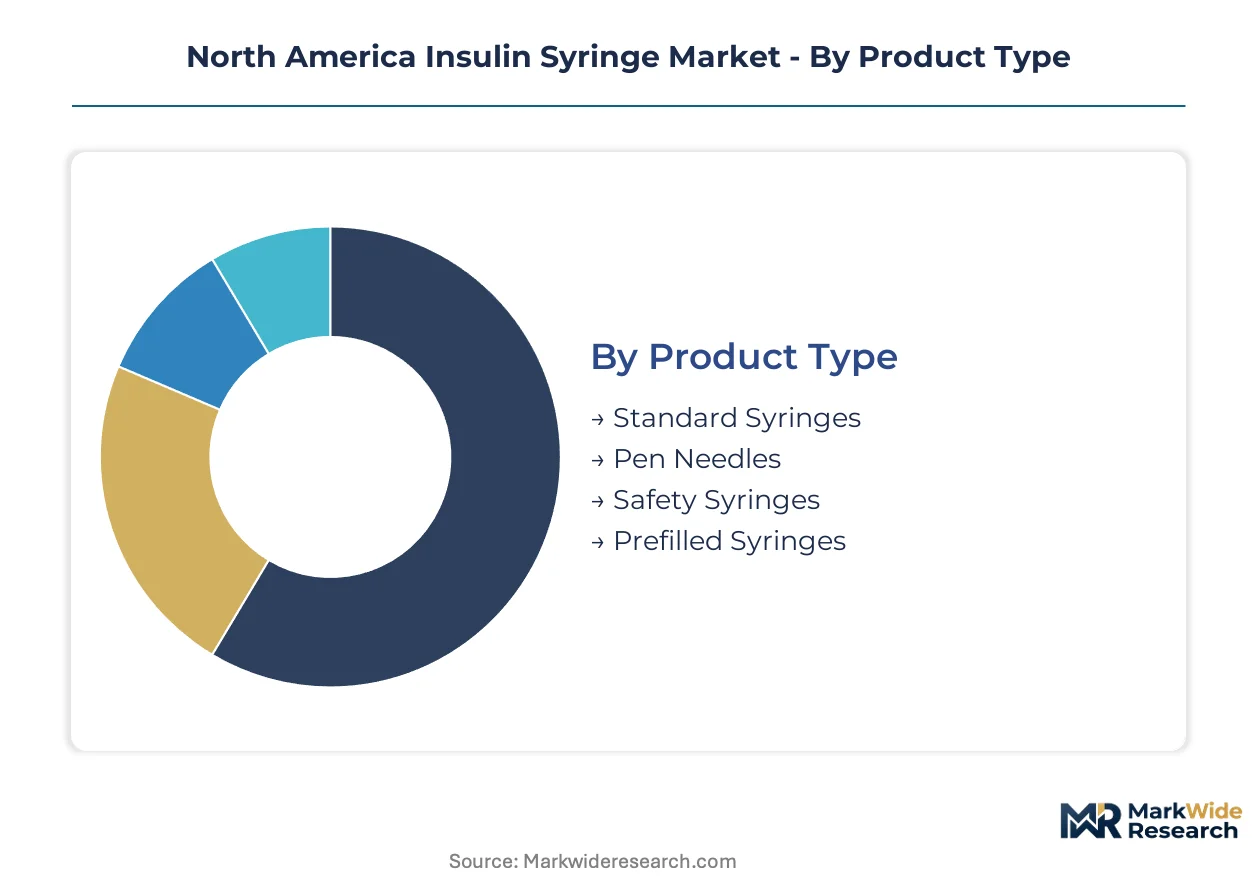
Insulin syringe segmentation reveals distinct procurement patterns between institutional buyers and retail channels. Material choices and packaging formats vary sharply across home care versus clinical settings, creating parallel demand structures within the same geography.
Product Type:
Standalone disposable devices dominate hospital procurement, while integrated delivery systems capture convenience-oriented home users.
- Safety Syringes:Retractable or shielded-needle mechanisms satisfy OSHA Bloodborne Pathogens Standard mandates across US hospital systems. Texas and California Medicaid pilots are expanding these into remote patient monitoring programs for adherence tracking.
- Prefilled Syringes:Ready-to-administer biologic insulin formats reduce medication error risk in specialty pharmacy channels. CVS Specialty and OptumRx formularies in California and Florida are mandating specific safety-engineered configurations for these presentations.
- Standard Syringes:Basic calibrated barrels with fixed needles serve cost-sensitive institutional purchasers.
- Pen Needles:Threaded attachments for reusable insulin pens capture convenience-driven patients in residential settings.
Safety syringes lead volumes today; prefilled syringes are gaining share fastest.
End User:
Procurement authority is migrating from hospital purchasing cooperatives toward pharmacy benefit managers and retail channels.
- Home Care:Patients self-administering insulin in residential settings drive unit volume through retail and mail-order pharmacy channels. Payer pressure and patient preference are accelerating this shift from facility-based care.
- Hospitals:Acute care facilities mandate safety-engineered devices under OSHA compliance, with group purchasing organization contracts consolidating supplier selection. Cardinal Health anchors these procurement networks.
- Clinics:Outpatient settings balance cost constraints with safety requirements for mixed patient populations.
- Diabetes Management Centers:Specialized endocrinology practices integrate connected dose-logging devices into remote monitoring platforms.
Home care channels are expanding most quickly; hospitals retain the largest absolute volume.
Material:
Polypropylene resin sourcing from the Gulf Coast petrochemical corridor shapes manufacturing economics and supply vulnerability.
- Plastic:Polypropylene barrels have displaced polystyrene formulations due to superior impact resistance at thin-wall geometries. Becton Dickinson leverages captive resin sourcing and in-house molding for margin control.
- Stainless Steel:Precision-drawn cannula tubing from specialized European and Asian metallurgical suppliers creates single-source vulnerability for finished-device manufacturers.
- Glass:Borosilicate barrels serve specialty applications requiring chemical inertness for specific insulin formulations.
- Biodegradable Materials:Emerging polymer alternatives face multi-year USP Class VI qualification timelines before clinical adoption.
Plastic dominates manufacturing input volumes; biodegradable materials show the steepest expansion trajectory in R&D pipelines.
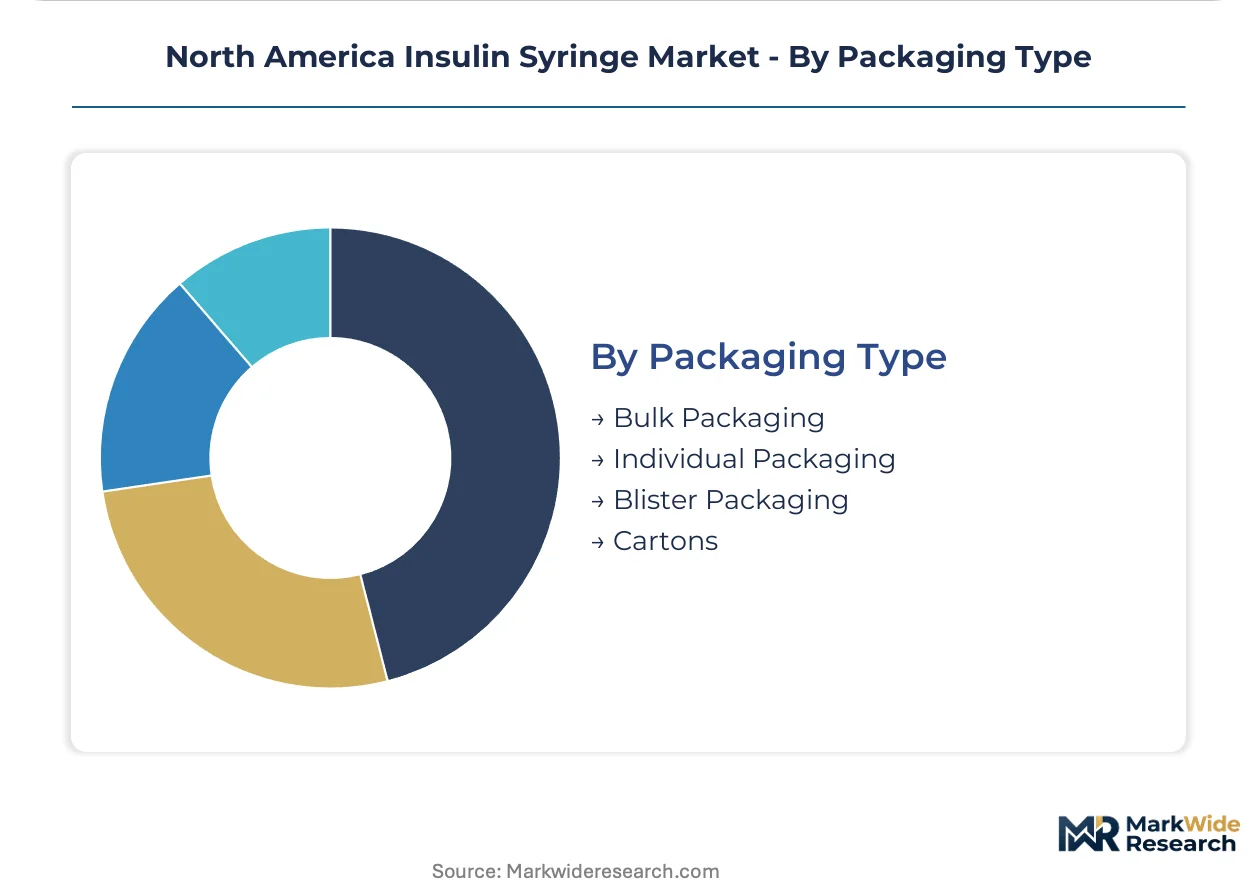
Packaging Type:
Distribution economics favor bulk formats for institutional buyers while retail channels require unit-dose presentation.
- Individual Packaging:Sterile single-unit pouches serve home care patients and travel-ready compliance requirements. Mail-order pharmacy fulfillment centers in Florida and California specify these configurations for direct-to-patient distribution.
- Bulk Packaging:Multi-hundred-unit cartons reduce per-dose logistics cost for hospital central supply operations.
- Blister Packaging:Thermoformed trays with peelable lidding balance protection with presentation for retail pharmacy shelves.
- Cartons:Secondary packaging aggregates individual units for wholesale distribution channels.
Individual packaging leads revenue per unit; bulk packaging moves the highest absolute unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American insulin syringe manufacturing, with polypropylene resin supply chains feeding molding operations across the United States, Canada, and Mexico.
United States
Texas and California Medicaid programs pilot connected dose-logging devices for adherence tracking in remote patient monitoring platforms. FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard mandates reshape procurement across hospital systems. New Jersey and Illinois host major diabetes device manufacturing clusters where specialty pharmacy distribution concentrates.
Canada
Ontario and Quebec drive institutional procurement through provincial health authority contracts for safety-engineered devices. Health Canada sterilization requirements diverge from FDA pathways, fragmenting cross-border submission strategies. Toronto and Montreal anchor distribution networks serving remote northern communities with individual packaging configurations.
Mexico
Maquiladora operations in Baja California and Chihuahua leverage COFEPRIS regulatory alignment with FDA quality systems for US-bound production. Nuevo León and Jalisco develop medical device manufacturing corridors with reduced logistics costs to American distribution centers. Mexico City Metro concentrates specialty pharmacy procurement authority for biologic insulin presentations.
North America Insulin Syringe Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory navigation capabilities. The market structure consolidates around diversified health conglomerates with captive resin sourcing and diabetes-dedicated manufacturing infrastructure. Three archetypes dominate: integrated device manufacturers with backward polymer control, group purchasing organization contract anchors, and spun-off diabetes specialists with legacy manufacturing expertise. Competitive moves center on safety mechanism innovation and prefilled syringe format migration toward ready-to-administer biologics.
Within the integrated manufacturing tier, Becton Dickinson exemplifies resin-to-device vertical control, while Cardinal Health anchors hospital procurement networks. Embecta Corp. occupies the diabetes-dedicated specialist position spun from legacy parent operations. These three represent distinct strategic postures: captive supply chain management, purchasing cooperative leverage, and focused therapeutic infrastructure.
| Leading Market Players |
|---|
| Becton Dickinson |
| Cardinal Health |
| Ultimed Inc. |
| Trividia Health Inc. |
| Arkray Inc. |
| Embecta Corp. |
| Terumo Corporation |
| Nipro Corporation |
| Smiths Medical |
| Others |
Value Network & Pricing Analysis
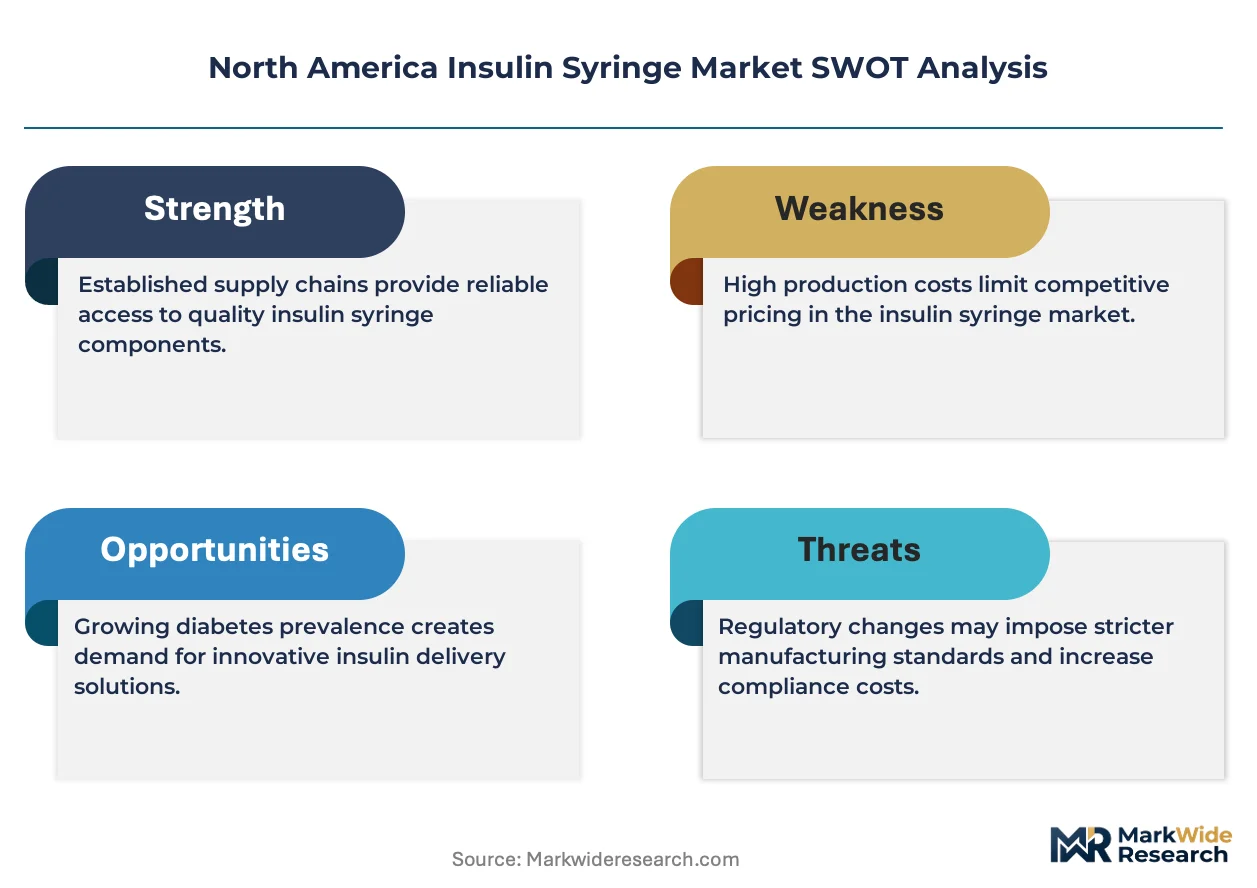
EPA per- and polyfluoroalkyl substance restrictions on fluoropolymer lubricants gate both qualified plunger-coating supply and premium-tier pricing access for safety-engineered insulin syringes, forcing manufacturers to absorb multi-year silicone-alternative qualification costs or cede high-margin hospital contracts.
Pricing Analysis
Input-cost pass-through from Gulf Coast polypropylene resin volatility shapes transactional per-unit pricing across safety syringe tiers. Pricing stratifies across premium, standard, and economy levels based on OSHA compliance certification grade and after-sales adherence support bundling. Cost compression in standard disposable segments is intensifying because pen needle substitution erodes volume leverage. Home care patients through retail channels exhibit highest price sensitivity; hospital GPO contracts anchored by Cardinal Health demonstrate lowest sensitivity due to liability-risk premiums.
Supply Chain Analysis
Freight cost differentials between Asian precision-metallurgical suppliers and North American molding operations concentrate stainless steel cannula sourcing vulnerability. Manufacturing draws from United States Gulf Coast resin corridors, Mexican maquiladora assembly zones, and European specialty steel draw benches. Single-source vulnerability in precision-drawn needle tubing from German and Japanese metallurgical houses threatens finished-device output. Distribution runs through Cardinal Health's hospital GPO networks and CVS Specialty's direct-to-patient pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Insulin Syringe Market functions as a geographic-arbitrage play where COFEPRIS-aligned Mexican manufacturing captures 15-20 point logistics cost advantages against US-based molding for FDA-cleared devices.
For Market Incumbents: Deploy captive resin sourcing as the primary lever to offset Gulf Coast petrochemical corridor disruption risk. Becton Dickinson's backward polymer control exemplifies this defense against polypropylene allocation protocols. Consolidate safety mechanism R&D spend into passive-activation shield designs that reduce needlestick liability exposure. Pen needle substitution from integrated insulin delivery systems threatens standalone syringe volume; counter with prefilled syringe format migration toward biologic insulin analogs. For New Entrants and Emerging Players: The premium-economy price-point gap in connected dose-logging devices opens white-space targeting of Medicaid adherence-tracking pilots in Texas and California. Specialty pharmacy direct-to-patient distribution channels remain underpenetrated by diabetes-dedicated manufacturers beyond Embecta's legacy infrastructure. Enter through software companion development partnerships with regional payers pursuing outcome-based reimbursement contracts. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap safety syringe specialists because hospital GPO contract consolidation favors scaled suppliers with dual FDA-Health Canada regulatory capabilities. Target manufacturers with established USP Class VI silicone lubricant qualifications ahead of EPA fluoropolymer enforcement windows. Watch COFEPRIS inspection backlog clearance rates as inflection indicator for Mexican manufacturing capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Regulatory Alignment | Enables maquiladora production serving US distribution with reduced cross-border logistics burden. |
| Silicone Lubricant Qualification | Secures USP Class VI biocompatibility ahead of EPA fluoropolymer coating restrictions. |
| Passive-Activation Shield Development | Addresses OSHA Bloodborne Pathogens Standard without user-dependent activation steps. |
| Specialty Pharmacy Partnership | Captures CVS Specialty and OptumRx formulary positioning away from hospital GPO channels. |
| Connected Dose-Logging Integration | Supports Texas and California Medicaid remote patient monitoring reimbursement pilots. |
Research Methodology
Multiple input streams — procurement director interviews at hospital GPOs, regulatory affairs discussions with FDA 510(k) consultants, and secondary validation against CMS Medicare device utilization data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged hospital biomedical engineers, diabetes management center clinicians, specialty pharmacy formulary directors, and Mexican maquiladora operations managers. Secondary sources included FDA 510(k) clearance databases, Health Canada MDALL registrations, COFEPRIS establishment listings, and hospital procurement cooperative contract disclosures.
Data-stream reconciliation across product type, end user, material composition, and packaging format dimensions produced volume and value estimates across the projection horizon. CAGRs were derived from segmented growth trajectory modeling. Forecast inputs incorporated biologic insulin analog pipeline expansion, OSHA enforcement intensity variations by state, and pen needle substitution elasticities in home care settings.
Caveats apply where EPA fluoropolymer restriction timelines, Gulf Coast petrochemical disruption frequency, or COFEPRIS inspection capacity constraints could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Microcarrier Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Casting and Splints Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market