
 Compression Stockings Market | 2026-2036
Compression Stockings Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Stockings Market Intelligence
Aftermarket service revenue from compression garment fitting and pressure-class verification is narrowing as manufacturers bundle digital measurement tools with direct-to-consumer channels. Sigvaris Group leverages proprietary sizing algorithms to sustain premium positioning across European and North American markets. Medi GmbH & Co. KG anchors its competitiveness through vertical control over elastane weaving and medical-grade dye processes. Juzo differentiates via specialized gradient-pressure engineering for lymphedema management, occupying a defensible niche in therapeutic hosiery.
Compression stockings are elastic garments engineered to apply graduated pressure—typically strongest at the ankle and decreasing toward the thigh—to enhance venous return and reduce peripheral edema, manufactured through circular knitting of nylon, spandex, or microfiber blends with calibrated stitch densities. Knee-high configurations dominate institutional procurement due to compliance advantages and lower unit economics, while thigh-high and waist-high variants command margin premiums in post-surgical and severe venous insufficiency applications. Sports recovery demand within the athlete end-user segment is accelerating fastest, driven by performance-oriented compression brands and recovery protocol integration by professional training staffs.
FDA oversight of medical device compression classifications, combined with CE marking requirements under the EU MDR, shapes product standards and market access barriers for manufacturers serving regulated channels. The EPA's textile chemical regulations and REACH substance restrictions in Europe further constrain material sourcing and dye formulation choices. Stakeholders must monitor evolving reimbursement codes from CMS and parallel health technology assessment bodies, as coverage determinations for compression therapy will dictate volume trajectories in clinical versus retail channels.
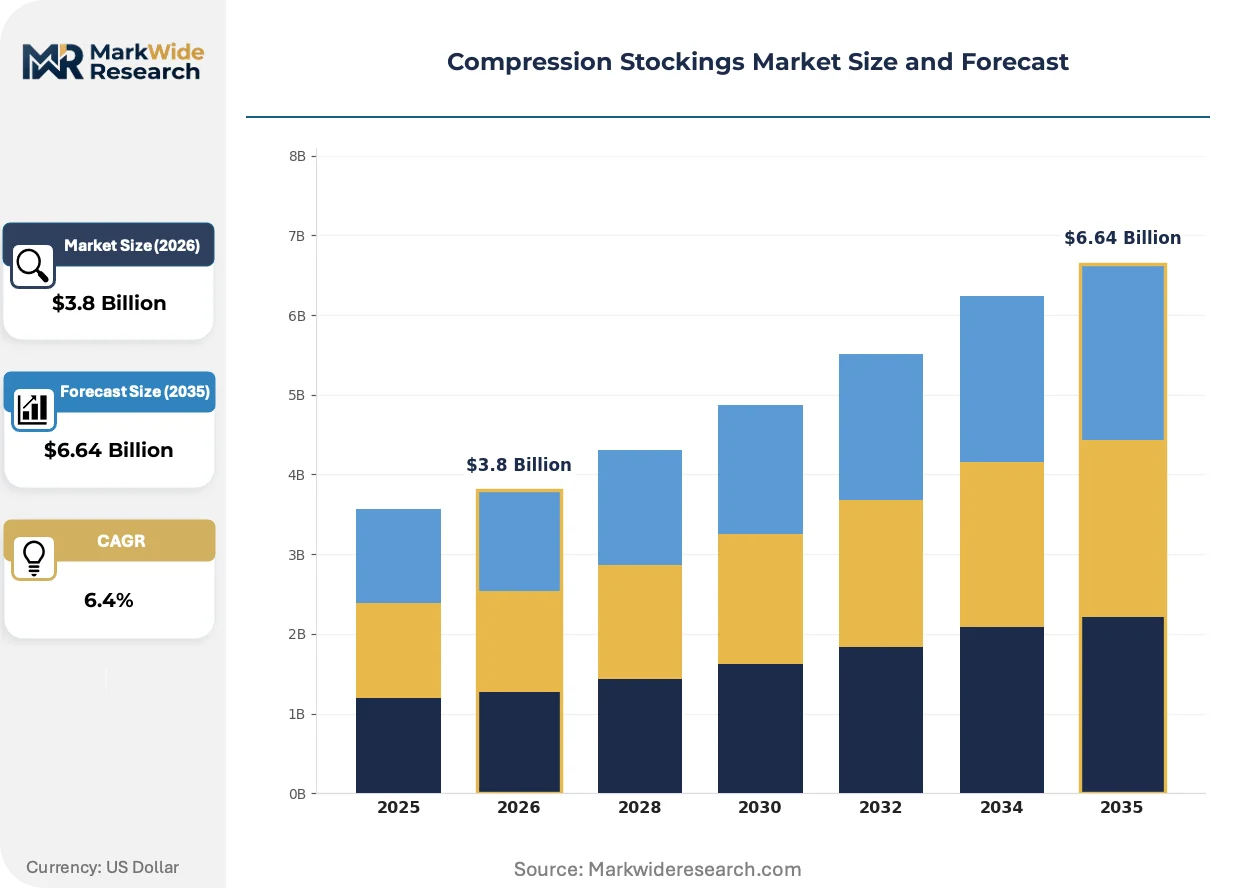
Market Dynamics
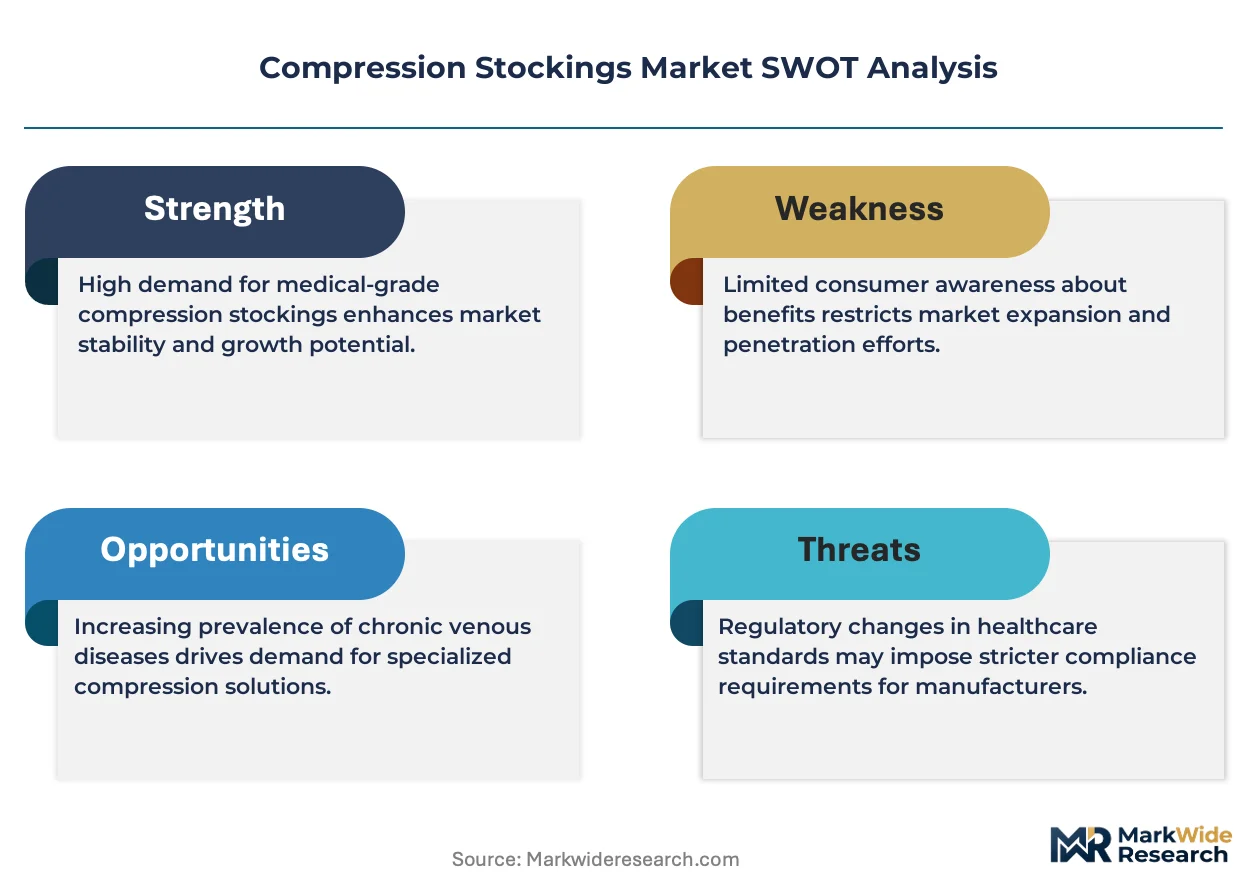
FDA's updated medical device classification for compression therapy products is compressing quality benchmarks while simultaneously fragmenting competitive positioning between premium medical-grade suppliers and direct-to-consumer entrants bundling digital fitting tools.
Growth Catalysts
- Post-surgical rehabilitation protocols:Hospital systems in the United States are mandating graduated compression garments as standard discharge protocols for orthopedic and vascular procedures, institutionalizing recurring volume.
- REACH substance restrictions:ECHA's tightening controls on textile dyes and elastane processing chemicals are accelerating substitution toward medical-grade formulations that command premium positioning.
- Diabetes prevalence trajectories:Clinical consumption of compression hosiery for diabetic foot and venous complications is hardening into chronic disease management pathways across Medicare Advantage networks.
Market Restraints
- Elastane input volatility:Spandex fiber prices fluctuate with crude oil derivatives and textile chemical feedstocks, compressing margin stability for manufacturers without captive weaving operations.
- EU MDR compliance timelines:CE marking recertification under stricter clinical evidence requirements is extending time-to-market for new gradient-pressure designs by 18-24 months.
- Substitute mechanical devices:Intermittent pneumatic compression systems are capturing severe lymphedema cases in institutional settings, capping addressable volume for static garment alternatives.
Strategic Opportunities
- India's underpenetrated clinical channel:Compression therapy awareness among diabetic and post-surgical populations remains nascent, creating first-mover advantage for localized pressure-class education and fitting infrastructure.
- Sports recovery application expansion:Professional athletic training staffs are integrating performance-oriented compression brands into recovery protocols, opening retail margin pools outside reimbursement-constrained medical channels.
- Digital measurement convergence:Smartphone-based limb circumference scanning combined with AI-driven pressure mapping is digitizing the fitting process, enabling direct-to-consumer penetration without specialized retail footprint.
Industry Challenges
- Gradient-pressure engineering talent scarcity:Specialized expertise in circular knitting calibration and medical-grade elastane blending concentrates among legacy European technical textile programs, constraining rapid capability replication.
- ISO 13485 certification bottlenecks:Medical device quality management system audits are backlogged at notified bodies, delaying market access for new entrants targeting regulated clinical procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Stockings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thigh High, Knee High, Waist High, Anti-Embolism Material: Elastic, Nylon, Cotton, Polyester Application: Post-Surgery, Varicose Vein Treatment, Sports Recovery, Daily Wear End User: Hospitals, Clinics, Homecare, Athletes |
| Companies Covered | Medtronic, Sigvaris Group, Medi GmbH & Co. KG, BSN Medical, 3M, Juzo, Bauerfeind AG, Essity, Tactile Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Stockings Market Strategic Shifts & Innovations
Digital fitting technologies and sensor-integrated garments are compressing the traditional role of specialized retail, while regulatory convergence between FDA and EU MDR frameworks is harmonizing quality expectations across Atlantic markets.
Smart compression textiles embedding pressure sensors and Bluetooth connectivity are digitizing real-time compliance monitoring for lymphedema and venous insufficiency patients. Academic medical centers in Germany and the United States are piloting these systems for remote therapeutic monitoring reimbursement pathways. The technology is digitizing the historical disconnect between prescribed pressure classes and actual garment performance during daily wear.
EU MDR's enhanced clinical evidence requirements for compression therapy products are forcing manufacturers to generate prospective patient outcome data beyond historical predicate device approvals. Notified bodies in the Netherlands and Germany are demanding pressure-distribution validation studies for thigh-high and waist-high variants. German manufacturers with established clinical research infrastructure are absorbing these costs more readily than mid-scale competitors.
Hospital procurement committees are consolidating compression garment suppliers into single-source contracts with outcome-based compliance guarantees, displacing fragmented multi-vendor purchasing. Group purchasing organizations in the United States are negotiating pressure-class verification services as bundled contract terms. This concentration is most visible in Medicare-dependent health systems across the Southeast and Midwest seeking standardized post-surgical protocols.
Compression Stockings Market Segmentation
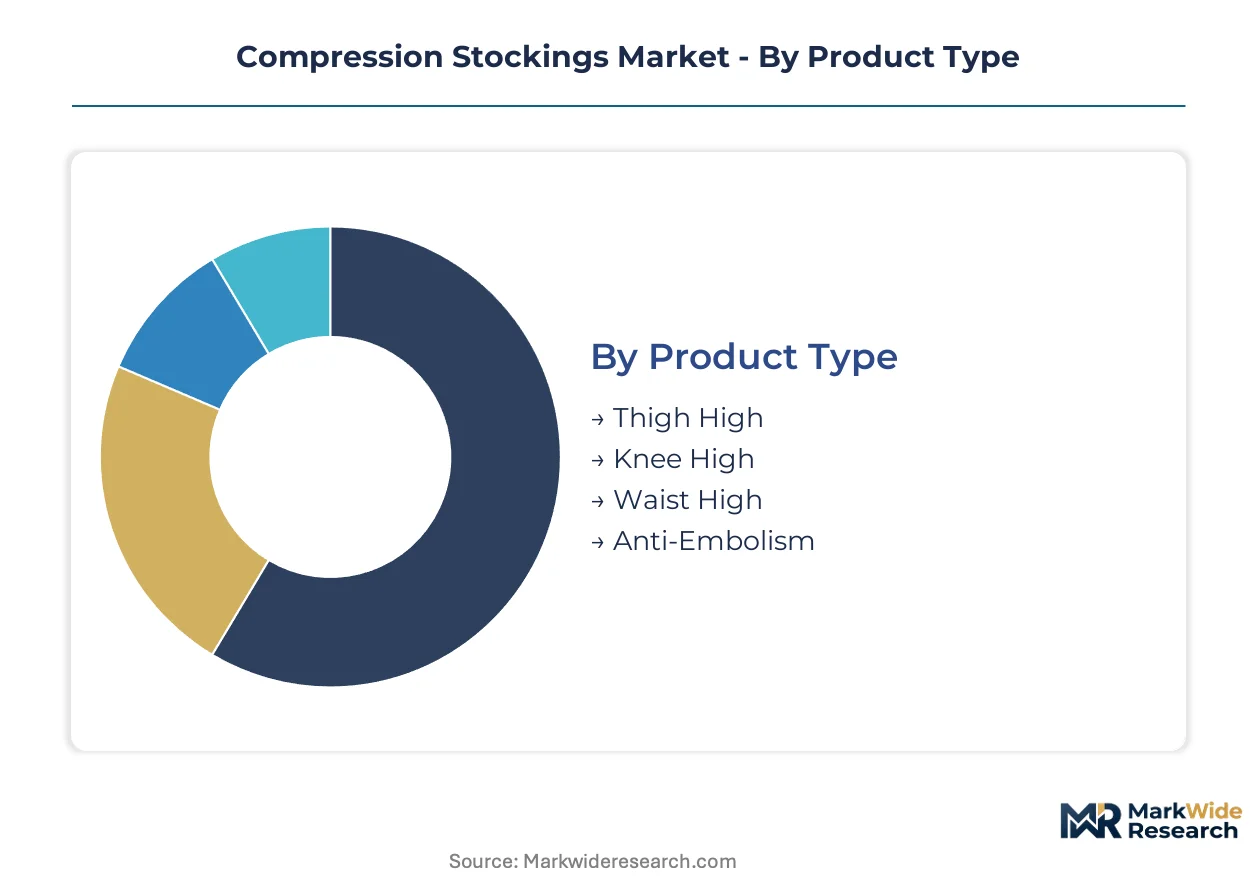
Compression stocking segmentation reveals distinct margin pools across product configurations, material grades, and channel economics. Manufacturers calibrate pressure-class engineering and distribution strategy differently for institutional procurement versus direct-to-consumer recovery applications.
Product Type:
Mature configurations dominate hospital procurement, while emerging variants target specialized therapeutic niches and athletic recovery protocols.
- Knee High:Circular-knit garments terminating below the patella deliver calibrated 15-20 mmHg ankle pressure with simplified donning protocols. United States hospital systems mandate this configuration for standard orthopedic discharge, institutionalizing high-volume recurring procurement through group purchasing organizations.
- Thigh High:Extended gradient-pressure engineering maintains compression continuity across the popliteal fossa, requiring precise silicone band integration to prevent migration. Severe venous insufficiency and post-thrombotic syndrome management in Medicare Advantage networks sustain premium positioning despite higher unit economics.
- Waist High:Pantyhose-style construction with abdominal compression panels addresses pelvic venous congestion and comprehensive lower-extremity edema.
- Anti-Embolism:Uniform compression profile optimized for immobile post-surgical patients, manufactured with lower elastane density for bedridden wear.
Knee High handles the majority of throughput; Sports Recovery applications are expanding most quickly in direct-to-consumer channels.
Material:
Cost tiers separate medical-grade formulations from commodity textile alternatives, with REACH-compliant chemistry commanding measurable price premiums.
- Elastic:Spandex-nylon blends with 20-30% elastane content enable precise gradient-pressure calibration through stitch-density variation. German technical textile manufacturers leverage captive weaving operations to stabilize input costs against crude oil derivative volatility.
- Nylon:Microfiber constructions with enhanced moisture-wicking properties dominate athletic recovery segments where extended wear comfort dictates compliance.
- Cotton:Natural fiber blends with reduced elastane integration serve dermatological-sensitive patients and tropical climate applications.
- Polyester:Cost-optimized circular knitting for price-sensitive institutional procurement in emerging markets.
Elastic formulations absorb the largest share of medical-grade production; Nylon is climbing the fastest in sports recovery positioning.
Application:
Customer type stratification separates reimbursement-constrained clinical pathways from retail-margin athletic recovery.
- Post-Surgery:Hospital discharge protocols for orthopedic and vascular procedures mandate graduated compression to prevent venous thromboembolism. United States health systems are standardizing procurement through single-source contracts with compliance verification requirements.
- Varicose Vein Treatment:Chronic venous insufficiency management through 20-30 mmHg medical-grade prescription channels.
- Sports Recovery:Performance-oriented compression brands integrate with professional athletic training protocols, bypassing reimbursement constraints entirely.
- Daily Wear:Preventive 8-15 mmHg consumer retail for occupational standing and travel applications.
Post-Surgery commands the deepest institutional volume; Sports Recovery shows the steepest expansion trajectory outside regulated channels.
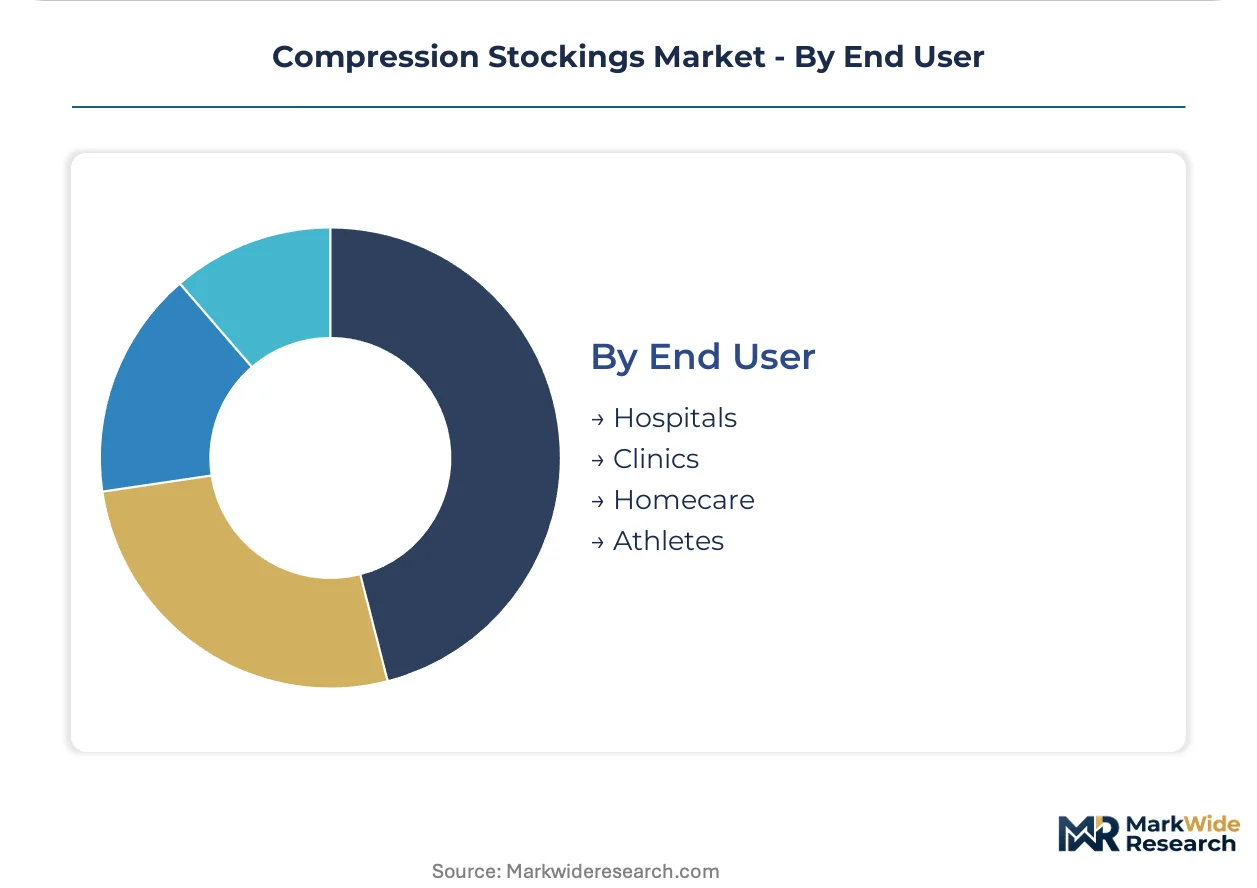
End User:
Channel concentration determines pricing power, with consolidated hospital procurement squeezing margins while fragmented homecare sustains retail premiums.
- Hospitals:Group purchasing organization consolidation in the United States Southeast and Midwest is compressing supplier margins through outcome-based compliance guarantees and pressure-class verification bundling.
- Clinics:Lymphedema therapy centers and vascular medicine practices maintain specialized fitting services for gradient-pressure customization.
- Homecare:Direct-to-consumer digital fitting tools are displacing traditional retail footprint, with smartphone limb-scanning enabling pressure-class selection without specialized infrastructure.
- Athletes:Professional training staff integration of performance compression brands creates retail margin pools independent of clinical reimbursement.
Hospitals concentrate the largest procurement volume; Athletes represent the fastest share gain in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in compression hosiery varies sharply by channel: institutional buyers in the United States squeeze margins through volume consolidation, while German clinical channels absorb premium pricing for medical-grade certification. Emerging markets trade compliance precision for accessibility.
United States
Medicare Advantage networks and hospital group purchasing organizations drive procurement concentration for post-surgical compression garments. FDA's updated medical device classification for compression therapy products tightens quality benchmarks while fragmenting competitive positioning. The Southeast and Midwest health systems standardize single-source contracts with compliance verification requirements.
Germany
Technical textile heritage and established clinical research infrastructure sustain premium positioning for graduated compression engineering. EU MDR's enhanced clinical evidence requirements and notified body audits in Germany and the Netherlands extend recertification timelines. The North Rhine-Westphalia and Bavaria industrial clusters host legacy circular-knitting expertise and medical-grade elastane blending operations.
China
Domestic manufacturing scale serves cost-optimized institutional procurement across Asia-Pacific, with NMPA medical device registration opening regulated clinical channels. GB standards for textile safety and SAMR market surveillance constrain dye formulation choices. The Yangtze River Delta and Pearl River Delta manufacturing bases supply circular-knit capacity for both export and domestic consumption.
India
Underpenetrated clinical awareness among diabetic and post-surgical populations creates first-mover opportunity for pressure-class education infrastructure. CDSCO medical device rules and BIS textile standards shape import and domestic manufacturing compliance requirements. Maharashtra and Gujarat industrial corridors develop localized elastane weaving and garment assembly for regional supply.
Japan
Aging demographics and chronic venous insufficiency prevalence sustain prescription-channel demand for precision-graded compression hosiery. PMDA medical device quality management and METI industrial standards govern market access and manufacturing practice. The Kanto and Kansai metropolitan clusters concentrate specialized lymphedema therapy centers and vascular medicine practices.
Compression Stockings Market Key Industry Players
European technical textile specialists and diversified medical device conglomerates split the market along quality-certification lines. Consolidation pressures concentrate around hospital procurement committees demanding outcome-based compliance guarantees. Three archetypes dominate: legacy circular-knitting engineers with captive elastane supply, diversified wound-care portfolios leveraging cross-selling infrastructure, and direct-to-consumer entrants bundling digital fitting tools. Competitive moves center on M&A absorption of regional distributors and backward integration into medical-grade dye formulation.
Among European-anchored specialists, Sigvaris Group and Medi GmbH & Co. KG exemplify the technical-engineering archetype through proprietary sizing infrastructure and vertical control over weaving processes. Juzo occupies a position within the therapeutic-specialist tier, with its nomenclature signaling gradient-pressure engineering orientation toward lymphedema management. These three represent distinct competitive vectors: algorithm-driven premium positioning, upstream manufacturing control, and niche therapeutic application depth.
| Leading Market Players |
|---|
| Medtronic |
| Sigvaris Group |
| Medi GmbH & Co. KG |
| BSN Medical |
| 3M |
| Juzo |
| Bauerfeind AG |
| Essity |
| Tactile Medical |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors shape landed cost differentials between German medical-grade manufacturers and Asian commodity suppliers, concentrating margin capture among vertically integrated European specialists while fragmenting price positioning across direct-to-consumer entrants.
Pricing Analysis
Aftermarket fitting service revenue is compressing as manufacturers bundle digital measurement tools with direct sales. Three-tier pricing structure across medical-grade prescription, standard clinical, and economy retail levels separates FDA-cleared devices from CE-marked alternatives and unregulated consumer variants. Cost compression in standard clinical tiers is intensifying because group purchasing organizations mandate outcome-based compliance guarantees. Hospital procurement committees exhibit highest price sensitivity; lymphedema therapy centers maintain lowest sensitivity due to gradient-pressure customization requirements.
Supply Chain Analysis
Contract manufacturing for circular-knit compression garments concentrates in German technical textile clusters, Chinese Yangtze River Delta spinning operations, and Indian Gujarat garment assembly corridors. Medical-grade elastane blending draws from petrochemical feedstocks in Belgium and South Korea, while REACH-compliant dye formulations hinge on Swiss and German specialty chemical suppliers. Single-source vulnerability runs through spandex fiber production tied to crude oil derivative volatility. Distribution runs through hospital group purchasing organizations in the United States, specialized medical retailers in Germany, and direct-to-consumer platforms in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compression stocking manufacturing represents a regulatory-entrenchment defensive moat, where FDA and EU MDR quality certifications create multi-year switching costs that protect incumbent positioning against commodity entrants.
For Market Incumbents: Insulate market position by deepening backward integration into medical-grade elastane weaving and dye formulation, securing input cost stability against petrochemical volatility. Acquire specialized lymphedema therapy distributors to lock in gradient-pressure customization channels threatened by digital fitting disruption. Prioritize ISO 13485 certification maintenance to defend hospital procurement access as notified body audits backlog extends. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated diabetic and post-surgical clinical channel, where pressure-class education infrastructure remains nascent and first-mover advantage persists. Target sports recovery applications through performance-oriented compression brands that bypass reimbursement-constrained medical pathways entirely. Deploy smartphone-based limb scanning combined with AI-driven pressure mapping to enable direct-to-consumer penetration without specialized retail footprint investment. For Investors and Strategic Acquirers: European technical textile specialists with captive circular-knitting operations and established clinical research infrastructure offer durable cash flow visibility under tightening EU MDR evidence requirements. Long-term viability rests on regulatory entrenchment deepening through enhanced clinical data generation rather than commodity cost competition. Monitor CMS reimbursement code revisions for compression therapy as the critical inflection signal dictating volume trajectories between clinical and retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastane Weaving | Medi GmbH's captive production insulates margin stability against spandex fiber price volatility. |
| Digital Fitting Platform Launch | Sigvaris Group's proprietary sizing algorithms sustain premium positioning across direct-to-consumer channels. |
| EU MDR Clinical Evidence Investment | German manufacturers absorb enhanced notified body audit costs more readily than mid-scale competitors. |
| Hospital System Partnership Consolidation | Group purchasing organization single-source contracts displace fragmented multi-vendor purchasing in United States Southeast. |
| Sports Recovery Brand Extension | Performance-oriented compression integration with professional athletic training staffs opens retail margin pools. |
Research Approach
A spread of perspectives from vascular medicine clinicians, hospital procurement managers, biomedical engineers, and group purchasing organization contract specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body audit records, CMS reimbursement code databases, and hospital procurement contract disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance dynamics across the projection horizon integrated patient population epidemiology, procedure volume trajectories, and manufacturing capacity utilization by product configuration and pressure class. Segmentation dimensions modeled encompassed garment type, material grade, application pathway, and end-user channel concentration. CAGRs were derived from regression analysis of historical procurement patterns and elasticity-adjusted adoption curves. Industry-specific inputs included diabetic prevalence trajectories, post-surgical rehabilitation protocol standardization, and REACH substance restriction implementation timelines.
Stress conditions across elastane input cost volatility, EU MDR recertification delay scenarios, and CMS reimbursement coverage determinations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and procurement consolidation momentum. Quarterly review of notified body audit queue lengths, GPO contract renewal cycles, and sports recovery brand partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
South America Syringe Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Global Syringe Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Filter Needles Market