
 Microcarrier Market | 2026-2036
Microcarrier Market Size, Share, and Industry Trends Forecast 2026-2036
Microcarrier Market Intelligence
The EU Green Deal's push for sustainable bioprocessing is broadening demand for serum-free and synthetic microcarrier substrates. Thermo Fisher Scientific leverages its bioproduction portfolio to anchor North American supply chains for vaccine-grade microcarriers. Sartorius AG competes through integrated bioreactor-microcarrier workflows that reduce process development timelines. Merck KGaA specializes in chemically defined surfaces that meet evolving regulatory expectations for traceability.
Microcarriers are small, typically 100-300 micrometer beads engineered from polystyrene, dextran, or collagen derivatives that provide attachment surfaces for anchorage-dependent cells in suspension culture. Their primary purpose is enabling scalable production of viral vectors, stem cells, and recombinant proteins in stirred-tank or wave-mixed bioreactors. Synthetic polymer microcarriers now lead the type segment due to lot-to-lot consistency and defined surface chemistries that simplify regulatory filings. Cell therapy applications represent the fastest-expanding application category as allogeneic programs require cost-effective scale-up of adherent stem cell populations.
The FDA's cell and gene therapy guidance and EMA's ATMP framework jointly shape product qualification requirements for clinical-grade microcarriers, pushing manufacturers toward animal-origin-free certifications. ISO 10993 biocompatibility standards and USP <1046> cell culture reagent guidelines further constrain supplier selection for commercial programs. Stakeholders must monitor evolving pharmacopeial standards for raw materials used in advanced therapy manufacturing as regulatory stringency tightens ahead of pipeline maturation.
Market Dynamics
Cell therapy commercialization timelines are compressing validation requirements for microcarrier-based manufacturing, forcing suppliers to pre-qualify substrates for GMP environments before clinical programs reach Phase III.
Growth Catalysts
- FDA Cell and Gene Therapy Guidance:Accelerated validation requirements for microcarrier-based processes are pulling investment into scalable adherent cell platforms for commercial manufacturing.
- Allogeneic Cell Therapy Pipelines:Cost-effective scale-up of adherent stem cell populations is driving demand for synthetic polymer microcarriers with defined surface chemistries.
- EU Green Deal Bioprocessing Mandates:Sustainability requirements are broadening procurement criteria toward serum-free and animal-origin-free microcarrier substrates.
Market Restraints
- Collagen Raw Material Volatility:Bovine and porcine collagen supply chains face pricing instability and traceability constraints that increase input cost unpredictability for biodegradable microcarrier production.
- Single-Source Concentration Risk:Critical surface modification chemistries for cell attachment depend on a narrow supplier base concentrated in Germany and Switzerland, creating vulnerability to regional disruptions.
- USP Pharmacopeial Lag:Absence of dedicated monographs for cell culture-grade microcarriers forces manufacturers to negotiate case-by-case qualification with national pharmacopeias, extending regulatory timelines.
Strategic Opportunities
- India Contract Manufacturing Expansion:CDSCO's streamlined ATMP approval pathways and PLI scheme incentives for biologics production are attracting microcarrier suppliers to establish local substrate finishing capabilities.
- Perfusion Bioreactor Convergence:Integration of microcarrier suspension culture with continuous perfusion systems is opening process intensification opportunities for viral vector manufacturing.
- Japan Regenerative Medicine Commercialization:PMDA's Sakigake designation system and conditional early approval framework are accelerating demand for clinical-grade microcarriers in iPSC-derived therapy programs.
Industry Challenges
- Cell Banking Standardization:Inconsistent master cell bank characterization across microcarrier batches creates lot-to-lot variability that complicates BLA submissions for adherent cell products.
- Downstream Harvest Integration:Separation of cells from dissolvable microcarriers requires customized centrifugation or filtration trains that extend process development timelines and increase capital requirements for GMP suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcarrier Market |
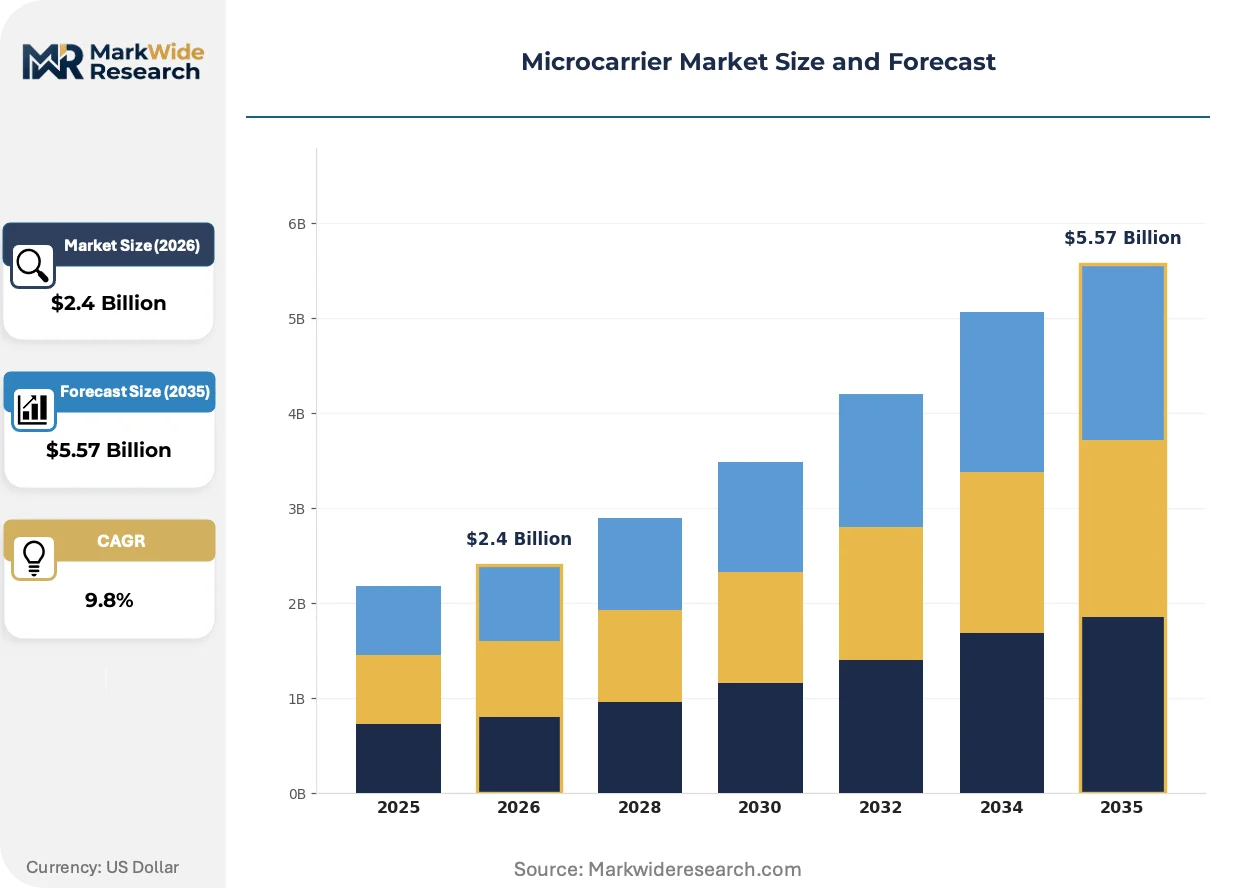
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solid, Gelatin, Synthetic Polymer, Natural Polymer, Cross-linked, Porous Application: Vaccine Production, Cell Therapy, Monoclonal Antibody Production, Tissue Engineering, Biopharmaceutical Manufacturing End User: Biotechnology Companies, Contract Research Organizations, Pharmaceutical Manufacturers, Academic Research Institutions Technology: Spinner Flask, Stirred Tank Bioreactor, Fixed Bed, Wave Bioreactor, Hollow Fiber |
| Companies Covered | Sartorius AG, Eppendorf SE, Thermo Fisher Scientific Inc., Asahi Kasei Corporation, Bio-Rad Laboratories, Inc., Merck KGaA, Corning Incorporated, HiMedia Laboratories Pvt. Ltd., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcarrier Market Strategic Shifts & Innovations
Synthetic surface engineering and modular bioreactor architectures are reconfiguring how anchorage-dependent cell populations achieve commercial scale, shifting competitive advantage toward substrate suppliers with integrated process development capabilities.
Electrospun nanofiber microcarriers are decentralizing the dominance of traditional beaded substrates by offering three-dimensional scaffold architectures that enhance cell attachment density and reduce shear stress in stirred-tank environments. Gene therapy CDMOs are adopting these materials for AAV production campaigns requiring high cell densities. The technology is decentralizing equipment requirements by enabling equivalent yields in smaller vessel footprints, compressing facility capital intensity for emerging biotech sponsors.
EMA's ATMP framework revision is tightening traceability requirements for raw materials used in advanced therapy manufacturing, mandating documented supply chain oversight back to polymer synthesis. Microcarrier suppliers must now maintain dual sourcing for surface coating reagents and submit drug master files for substrate components. European cell therapy developers are responding by consolidating supplier relationships with vendors holding ISO 13485 medical device quality certifications alongside ISO 10993 biocompatibility data.
Biopharmaceutical procurement teams are compressing vendor qualification cycles by demanding pre-validated microcarrier configurations with existing drug master file references. Large-cap gene therapy developers are bypassing traditional distributor channels to negotiate direct supply agreements with substrate manufacturers, securing lot reservation priority for commercial campaigns. This pattern is most visible in the United States, where FDA breakthrough therapy designations are accelerating manufacturing readiness timelines and forcing earlier commitment to qualified raw material suppliers.
Microcarrier Market Segmentation
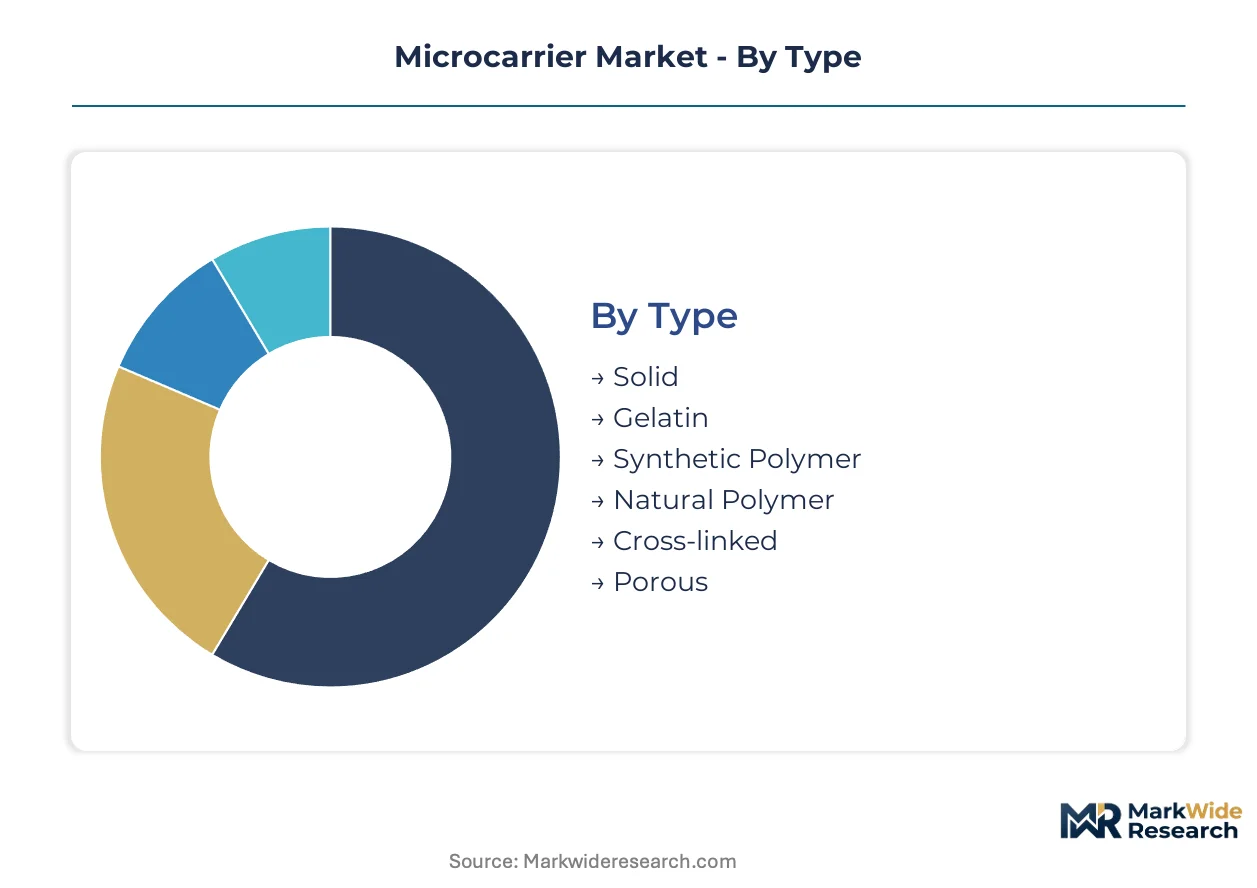
Microcarrier segmentation determines process scalability and regulatory pathway complexity for anchorage-dependent cell culture. Substrate composition, application purpose, and bioreactor technology integration each constrain supplier selection and manufacturing economics differently.
Type:
Solid microcarriers function as standalone attachment surfaces requiring harvest separation, while dissolvable and porous variants embed into continuous processing workflows.
- Solid:Polystyrene-based beads with defined surface chemistries deliver lot-to-lot consistency for vaccine-grade viral vector production. Demand concentrates in United States gene therapy CDMOs where FDA breakthrough therapy designations compress manufacturing readiness timelines.
- Synthetic Polymer:Chemically defined substrates eliminate animal-origin variability, simplifying EMA ATMP traceability requirements. European cell therapy developers prioritize these for allogeneic stem cell expansion programs facing EU Green Deal sustainability mandates.
- Gelatin:Temperature-sensitive dissolution enables gentle cell harvest without enzymatic treatment.
- Natural Polymer:Collagen and dextran derivatives offer biodegradable alternatives for tissue engineering scaffolds.
- Cross-linked:Enhanced mechanical stability supports high-shear stirred-tank environments.
- Porous:Internal surface architecture increases cell attachment density per unit volume.
Synthetic Polymer leads volumes today; Porous variants are gaining share fastest.
Application:
Commercial manufacturing applications command premium pricing against research-scale uses, with cell therapy programs requiring the most intensive substrate qualification.
- Cell Therapy:Allogeneic programs demand cost-effective scale-up of adherent stem cell populations in suspension culture. Japan's PMDA Sakigake framework accelerates demand for clinical-grade substrates in iPSC-derived therapy manufacturing.
- Vaccine Production:Viral vector manufacturing for preventive and therapeutic vaccines requires high-density cell attachment in stirred-tank bioreactors. United States biopharmaceutical investment anchors North American demand for serum-free microcarrier supply chains.
- Monoclonal Antibody Production:Hybridoma and recombinant cell line expansion leverages microcarriers for perfusion-based intensification.
- Tissue Engineering:Biodegradable scaffolds support three-dimensional organoid and construct development.
- Biopharmaceutical Manufacturing:Broad category encompassing recombinant protein and gene therapy vector production.
Vaccine Production anchors current revenue; Cell Therapy climbs the fastest.
End User:
Procurement sophistication varies sharply—pharmaceutical manufacturers negotiate direct supply agreements while academic institutions purchase through distributors.
- Pharmaceutical Manufacturers:Large-cap developers bypass distributor channels to secure lot reservation priority for commercial campaigns, demanding pre-validated configurations with existing drug master file references.
- Biotechnology Companies:Emerging sponsors prioritize facility capital efficiency, driving adoption of electrospun nanofiber microcarriers that enable equivalent yields in smaller vessel footprints.
- Contract Research Organizations:Process development services require flexible substrate portfolios spanning multiple cell types.
- Academic Research Institutions:Exploratory programs tolerate higher lot-to-lot variability for cost-sensitive early-stage studies.
Pharmaceutical Manufacturers dominate procurement value; Biotechnology Companies expand most quickly.
Technology:
Bioreactor architecture determines shear stress tolerance, mass transfer efficiency, and integration complexity for microcarrier suspension systems.
- Stirred Tank Bioreactor:Dominant platform for commercial-scale manufacturing with established scale-up protocols and extensive supplier ecosystems. India CDSCO's streamlined ATMP pathways attract substrate suppliers to establish local finishing capabilities for this equipment class.
- Wave Bioreactor:Rocking-motion agitation reduces shear stress on sensitive cell types during expansion. Gene therapy CDMOs adopt these systems for AAV production campaigns requiring high cell densities with minimal mechanical damage.
- Spinner Flask:Bench-scale screening tool for early process development and cell line qualification.
- Fixed Bed:Immobilized microcarrier configurations enable continuous perfusion with reduced downstream separation burden.
- Hollow Fiber:Compartmentalized cell retention supports high-density culture with integrated metabolite exchange.
Stirred Tank Bioreactor holds installed base dominance; Wave Bioreactor shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microcarrier technology originated in North American academic laboratories during the 1960s before commercial scale-up migrated to United States biopharmaceutical corridors. The industry's geographic footprint now spans three continents with distinct regulatory drivers shaping substrate procurement patterns.
United States
Gene therapy CDMOs in Massachusetts and Maryland drive demand for pre-validated synthetic polymer substrates with drug master file references. FDA breakthrough therapy designations compress manufacturing readiness timelines, forcing sponsors to lock raw material suppliers before Phase II completion. The Greater Boston cluster anchors North American supply chain security negotiations for commercial-scale microcarrier campaigns.
Germany
EMA ATMP traceability mandates push Baden-Württemberg cell therapy developers toward chemically defined, animal-origin-free microcarrier specifications. The country's national pharmaceutical regulator enforces documented supply chain oversight back to polymer synthesis for advanced therapy substrates. Frankfurt-Rhine-Main logistics hubs coordinate surface coating reagent distribution across European GMP manufacturing networks.
Japan
PMDA's Sakigake designation system accelerates iPSC-derived therapy programs requiring clinical-grade microcarriers for adherent stem cell expansion. The country's national pharmaceutical regulator maintains conditional early approval frameworks that compress substrate qualification cycles. Kansai manufacturing corridors around Osaka concentrate perfusion bioreactor integration expertise for viral vector production.
India
CDSCO's streamlined ATMP approval pathways attract microcarrier suppliers to establish local substrate finishing capabilities for contract manufacturing expansion. The country's production-linked incentive scheme for biologics production reduces import dependency for vaccine-grade cell culture materials. Hyderabad and Bangalore biotech clusters anchor South Asian demand for serum-free microcarrier supply chains.
Switzerland
Swissmedic's stringent raw material oversight reinforces Basel-region demand for ISO 13485-certified substrate suppliers with dual-sourcing capabilities. The country's medical device quality framework exceeds baseline ISO 10993 requirements for cell therapy manufacturing inputs. Zurich-Schaffhausen industrial corridors concentrate surface modification chemistry expertise for high-attachment-density microcarrier architectures.
Microcarrier Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the microcarrier supply base, with integrated bioproduction conglomerates facing specialized substrate developers. The market structure tilts toward consolidation at the premium tier while mid-scale suppliers fragment across regional distributor networks. Three archetypes dominate: diversified life science conglomerates with bioproduction portfolios, specialized cell culture substrate developers with surface chemistry expertise, and equipment-integrated solution providers bundling bioreactor-microcarrier workflows. Competitive intensity centers on GMP pre-qualification speed and drug master file depth rather than manufacturing scale alone.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc., Merck KGaA, and Danaher Corporation exemplify the integrated bioproduction archetype. These entities anchor North American and European supply chains through captive distribution networks and pre-validated substrate configurations. Sartorius AG occupies a distinct position as an equipment-integrated specialist, representing the workflow convergence archetype that compresses process development timelines through bioreactor-microcarrier bundling. Asian market presence concentrates in diversified chemical conglomerates and regional laboratory supply specialists, with Asahi Kasei Corporation exemplifying the materials science-to-biopharma pivot archetype common among Japanese industrial groups.
| Leading Market Players |
|---|
| Sartorius AG |
| Eppendorf SE |
| Thermo Fisher Scientific Inc. |
| Asahi Kasei Corporation |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Corning Incorporated |
| HiMedia Laboratories Pvt. Ltd. |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up substrate specialists anchor pricing discipline through concentrated ownership of surface modification chemistries, while their captive distribution networks in Germany and Switzerland extract premiums from cell therapy developers facing compressed FDA validation timelines. This ownership pattern concentrates supply bargaining power upstream, forcing downstream biopharmaceutical manufacturers into multi-year offtake commitments to secure lot reservation priority for commercial campaigns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated substrates with drug master file references from research-grade alternatives. Price differentiation hinges on ISO 13485 certification tier and animal-origin-free documentation depth. Cost compression in the standard tier is intensifying because European EMA traceability mandates are forcing qualification investment that smaller CDMOs cannot absorb. Academic research institutions exhibit highest price sensitivity, while large-cap gene therapy developers demonstrate lowest sensitivity due to breakthrough therapy designation timelines.
Supply Chain Analysis
Regional distribution centers in Frankfurt-Rhine-Main and Basel coordinate hub-and-spoke patterns for surface coating reagents across European GMP networks. Manufacturing concentrates in Germany, Switzerland, and the United States, with raw material dependencies on bovine collagen supply chains and polystyrene polymer feedstocks. Single-source vulnerability in German-Swiss surface modification chemistry creates exposure to regional logistics disruptions. Distribution runs through direct supply agreements for pharmaceutical manufacturers and specialty distributors for academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States premium pricing for FDA-validated substrates and India's emerging cost base under CDSCO's PLI scheme for biologics production.
For Market Incumbents: Lock in raw material sourcing through backward integration into polystyrene polymer synthesis or long-term offtake agreements with bovine collagen processors. Cell banking standardization inconsistencies across microcarrier batches threaten BLA submission success rates, making ISO 13485 certification investment the critical defensive lever against emerging synthetic polymer competitors. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Indian CDMOs exploiting PLI scheme incentives and CDSCO's streamlined ATMP pathways. Electrospun nanofiber microcarriers for AAV production represent the most penetrable white space, enabling facility capital efficiency that attracts emerging biotech sponsors seeking smaller vessel footprints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale surface chemistry specialists lacking drug master file portfolios but holding ISO 10993 biocompatibility data. Long-term viability over the next decade rests on regulatory tailwinds from cell therapy commercialization rather than commodity substrate volumes. Watch for FDA breakthrough therapy designation announcements as the signal indicating imminent manufacturing readiness spending inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Submission | FDA drug master file references accelerate GMP validation timelines for commercial cell therapy campaigns. |
| Backward Integration into Polymer Synthesis | Captive polystyrene production insulates margins from petrochemical feedstock volatility and EMA traceability requirements. |
| Perfusion Bioreactor Partnership | Integration with Sartorius AG continuous processing workflows captures viral vector manufacturing intensification demand. |
| India Local Finishing Capability | CDSCO PLI scheme incentives reduce import dependency for South Asian vaccine-grade substrate supply chains. |
| ISO 13485 Certification Investment | Medical device quality certification exceeds baseline ISO 10993 requirements for European ATMP procurement consolidation. |
Research Approach
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each region combining interviews with cell therapy manufacturing executives, regulatory affairs leads at substrate suppliers, GMP facility procurement managers, and bioprocess development scientists. Secondary validation draws from FDA guidance documents, EMA ATMP framework revisions, CDSCO PLI scheme notifications, PMDA Sakigake designations, and USP pharmacopeial draft standards. Bottom-up segment sizing triangulates against top-down industry expenditure estimates.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across the projection horizon. Segmentation dimensions modeled include substrate type, application purpose, end-user procurement sophistication, and bioreactor technology integration. CAGRs derive from regression analysis against cell therapy pipeline maturation indicators and viral vector manufacturing capacity announcements. Forecast inputs incorporate FDA breakthrough therapy designation velocity and EMA traceability mandate implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of prolonged USP pharmacopeial lag or sudden bovine collagen supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Asia Pacific Industrial Gloves Market