
 North America Insulin Market | 2026-2036
North America Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulin Market Insights
Aftermarket service revenue from insulin pump maintenance and continuous glucose monitoring integration is reshaping margin pools across the North America insulin landscape. Novo Nordisk leverages its manufacturing scale to dominate long-acting analog supply chains. Eli Lilly and Company anchors its position through vertical control over active pharmaceutical ingredient production. Sanofi competes aggressively in the biosimilar segment with differentiated pricing strategies.
Insulin encompasses peptide hormone formulations synthesized through recombinant DNA technology in Escherichia coli or Saccharomyces cerevisiae expression systems, with purity standards exceeding 99% and specified potency measured in international units per milligram. The molecule regulates glucose metabolism by facilitating cellular uptake, making it essential for patients with absolute or relative insulin deficiency. Long-acting insulin formulations command the largest revenue share due to once-daily dosing convenience and superior adherence profiles, while biosimilar insulin represents the fastest-expanding product category as patent cliffs open substitution pathways across retail pharmacy channels. Insulin pump delivery mode adoption accelerates fastest among Type 1 diabetes patients seeking automated dosing algorithms, though insulin pens retain volume leadership across home care and clinic settings.
FDA oversight through the Center for Drug Evaluation and Research governs insulin approval pathways, while the Inflation Reduction Act's Medicare price caps directly constrain list-price escalation and reshape commercial contracting dynamics. Health Canada's Pharmaceutical Drugs Directorate maintains parallel bioequivalence standards that influence cross-border manufacturing decisions and regulatory submission strategies. Stakeholders must monitor CMS reimbursement rulemaking and state-level insulin copay caps as these mechanisms determine patient access thresholds and manufacturer net revenue realization.
Market Dynamics
Medicare price caps under the Inflation Reduction Act are compressing manufacturer net revenue realization while accelerating biosimilar substitution across retail pharmacy channels. This regulatory pressure is reshaping contracting dynamics between insulin suppliers and pharmacy benefit managers.
Growth Catalysts
- FDA biosimilar approval pathways:Streamlined review timelines under the Biologics Price Competition and Innovation Act accelerate competitive entry. Substitution pathways open across state-level pharmacy regulations.
- Home care settings:Patients shift from clinical administration to self-managed therapy. Insulin pens and continuous glucose monitoring integration support this migration.
- Type 1 diabetes automated dosing:Insulin pump algorithms reduce hypoglycemic events. Adoption concentrates among pediatric and young adult populations seeking glycemic control.
Market Restraints
- Active pharmaceutical ingredient concentration:Three manufacturers control recombinant DNA fermentation capacity for insulin bulk. Supply disruptions propagate quickly through formulation networks.
- Reimbursement rate compression:CMS Medicare price caps constrain list-price escalation. Commercial contracting leverage diminishes as reference pricing spreads.
- Cold chain distribution costs:Temperature-controlled logistics from manufacturing through last-mile delivery add 12-18% to landed product cost. Rural pharmacy access suffers.
Strategic Opportunities
- Continuous glucose monitoring convergence:Sensor-augmented pump systems create closed-loop artificial pancreas functionality. Algorithm licensing generates recurring software revenue.
- State-level insulin copay caps:Colorado, Illinois, and Minnesota mandate patient out-of-pocket limits. Manufacturers gain volume access through preferred formulary placement.
- Long-acting biosimilar white space:Patent cliffs for glargine and degludec analogs open substitution pathways. Retail pharmacy channels seek interchangeable alternatives.
Industry Challenges
- Bioequivalence demonstration complexity:Immunogenicity testing for biosimilar insulin requires extensive clinical trials. FDA analytical similarity standards extend development timelines.
- Legacy pump system integration:Proprietary communication protocols between devices block seamless sensor-pump interoperability. Open-source standard adoption lags.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulin Market |
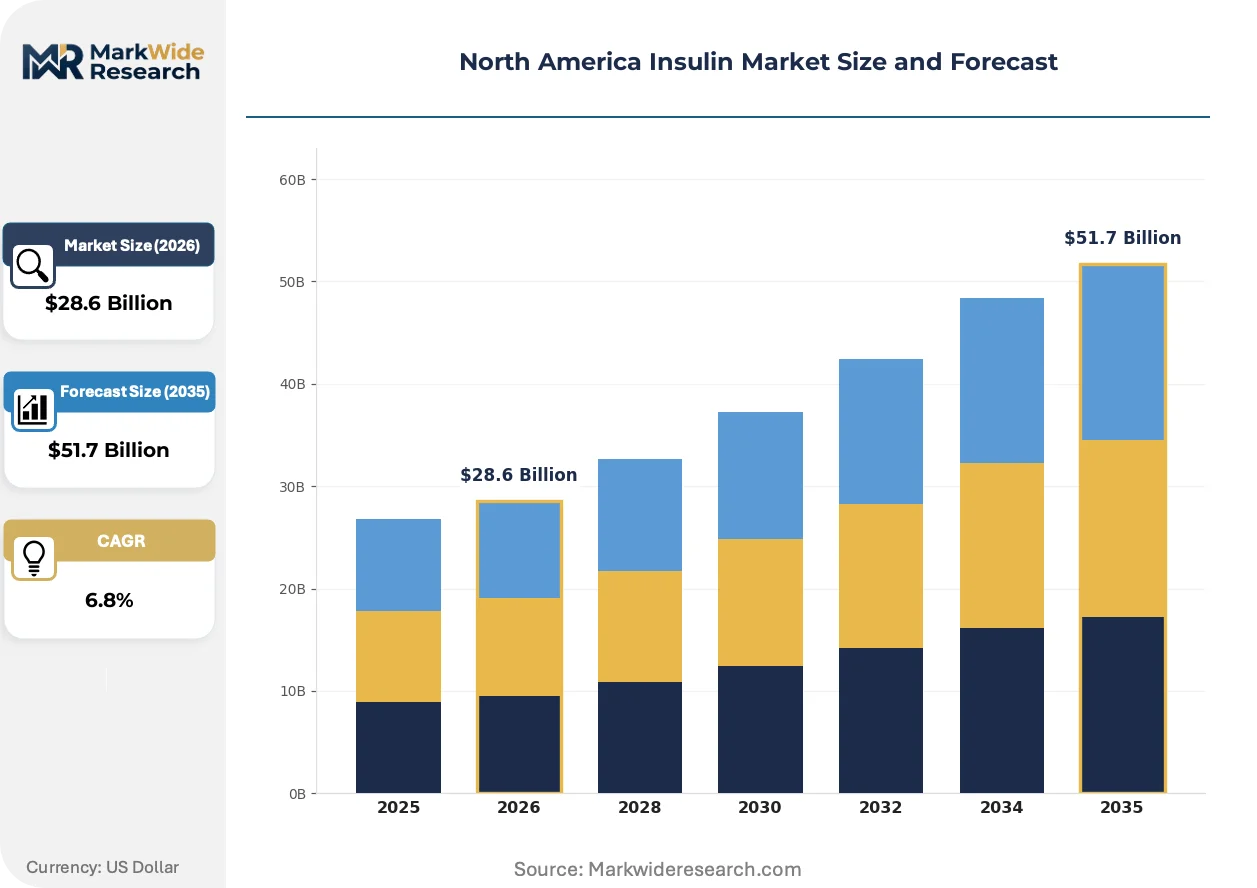
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Pre-Mixed Insulin, Biosimilar Insulin Delivery Mode: Insulin Syringe, Insulin Pen, Insulin Pump, Inhalable Insulin End User: Hospitals, Clinics, Home Care, Retail Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetes Complications |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, Merck & Co., Inc., Biocon Limited, Pfizer Inc, Becton Dickinson and Company, MannKind Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulin Market Trends and Innovations
Automated insulin delivery systems are converging with real-time glucose sensing to reduce therapeutic burden. Three distinct vectors are reshaping product development and competitive positioning across the North American landscape.
Smart insulin pen technology is migrating from simple dose logging to dose decision support. Endocrinology practices deploy Bluetooth-enabled pens that transmit injection data to electronic health records. This connectivity layer enables remote patient monitoring and reduces clinic visit frequency for dose titration.
The Inflation Reduction Act's Medicare price caps directly constrain manufacturer list-price escalation. Commercial contracting dynamics reshape as pharmacy benefit managers reference Medicare reimbursement benchmarks. Long-acting analog suppliers face margin compression most acutely in the United States market.
Patient self-administration preferences are compressing clinical injection visits. Home care channels displace hospital outpatient settings for insulin initiation and training. This shift concentrates demand in retail pharmacy and mail-order distribution across the United States and Canada.
North America Insulin Market Segmentation
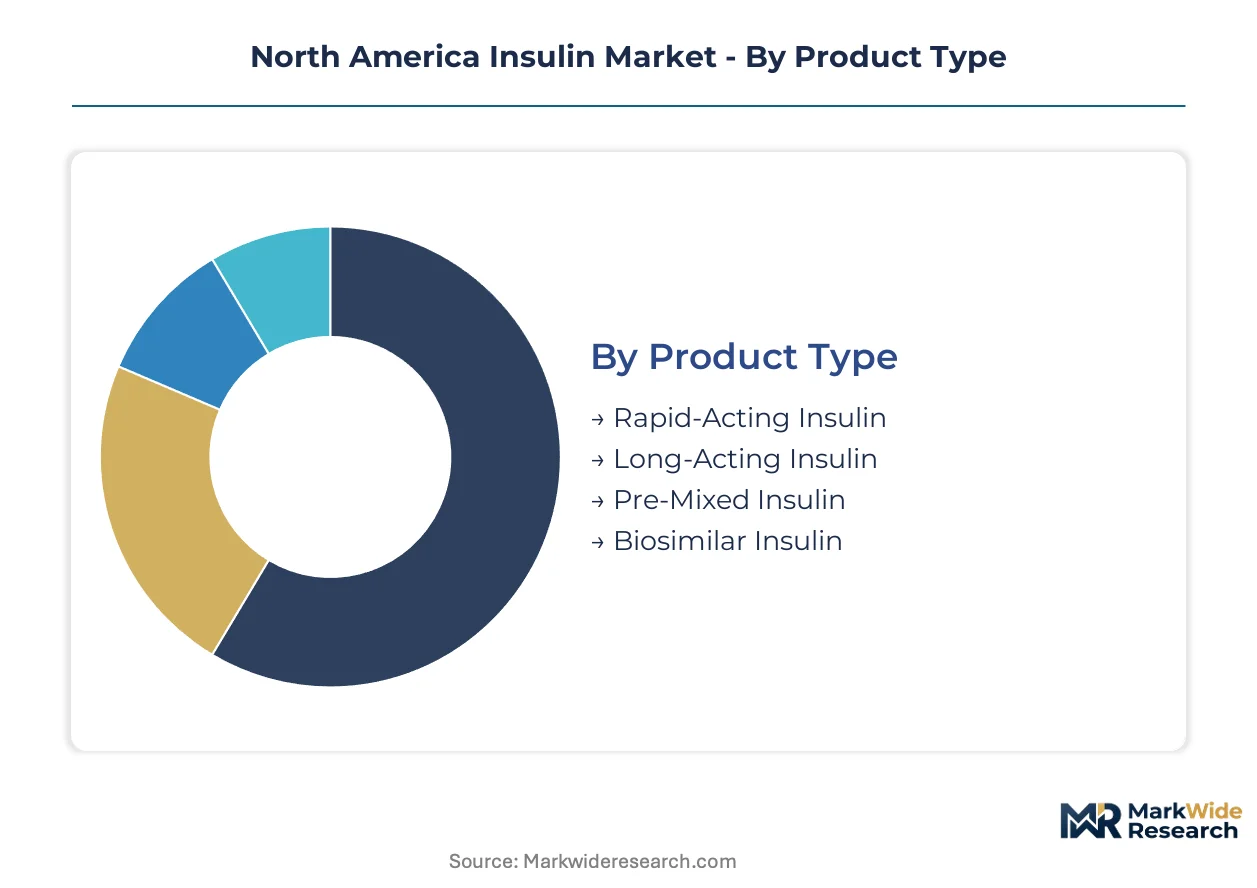
Insulin market segmentation reveals distinct velocity profiles across therapeutic and delivery categories. Cycle times vary dramatically—pump hardware refreshes every 4-6 years while analog formulations command decade-long patient loyalty.
Product Type:
Long-acting analogs turn over slowest due to therapeutic inertia, while biosimilars accelerate fastest as substitution pathways mature.
- Long-Acting Insulin:Recombinant glargine and degludec formulations provide basal coverage with 24-42 hour pharmacokinetic profiles. United States Medicare Part D claims show concentration here, though Inflation Reduction Act price caps compress net realization per prescription.
- Biosimilar Insulin:Interchangeable follow-on biologics manufactured through comparable E. coli or yeast expression systems achieve analytical similarity to reference products. Retail pharmacy substitution laws in multiple United States states drive volume migration fastest in this category.
- Rapid-Acting Insulin:Lispro, aspart, and glulisine analogs target postprandial glucose spikes with 15-minute onset profiles. Hospital inpatient protocols and pump algorithms anchor demand.
- Pre-Mixed Insulin:Fixed-ratio combinations of intermediate and rapid-acting components simplify regimens for patients with limited self-monitoring capacity. Concentrates in Medicare populations seeking dosing convenience.
Long-acting insulin dominates installed base. Biosimilar insulin is where expansion concentrates.
Delivery Mode:
Capital intensity separates segments—pump systems require manufacturing scale and software integration, while pen devices compete on unit economics.
- Insulin Pen:Disposable and reusable cartridge systems integrate dose dialing with fine-gauge needles. Home care settings across the United States and Canada concentrate demand here, supported by pharmacy benefit manager formulary preference.
- Insulin Pump:Tethered and patch pump configurations deliver subcutaneous infusion with algorithmic dose modulation. Pediatric Type 1 diabetes populations in United States academic medical centers anchor adoption.
- Insulin Syringe:Vial-and-syringe administration persists in cost-sensitive segments and institutional settings. Medicaid programs and safety-net clinics maintain volume.
- Inhalable Insulin:Pulmonary delivery of Technosphere insulin powder offers prandial coverage without injection. United States FDA risk evaluation and mitigation strategies constrain prescribing to select endocrinology practices.
Insulin pen systems capture highest prescription volume. Insulin pump adoption is climbing the fastest among technology-enabled patients.
End User:
Reimbursement mechanics determine segment profitability—facility fees versus pharmacy margins create divergent economics.
- Home Care:Self-administered therapy supported by continuous glucose monitoring integration and telehealth titration protocols. United States commercial insurance and Medicare Advantage plans increasingly mandate this channel for maintenance therapy.
- Retail Pharmacies:Community and mail-order dispensing capture 90-day supply fulfillment and prior authorization management. Pharmacy benefit manager vertical integration concentrates volume here.
- Hospitals:Inpatient glycemic management protocols use intravenous insulin for critical care and subcutaneous analogs for step-down units. United States CMS quality metrics drive standardization.
- Clinics:Outpatient endocrinology and primary care sites handle insulin initiation and dose optimization. Federally qualified health centers serve underinsured populations.
Home care dominates installed base. Retail pharmacy is where expansion concentrates.
Therapy Area:
Disease severity and progression rate create distinct insulin dependence profiles across patient populations.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement from diagnosis. Pediatric and young adult populations in United States and Canada academic centers drive pump and automated delivery adoption.
- Type 2 Diabetes:Progressive beta-cell failure generates insulin requirement in 30-40% of patients over disease course. United States Medicare and commercial formularies concentrate volume for long-acting analogs.
- Gestational Diabetes:Insulin resistance during pregnancy requires tight glycemic control when diet modification fails. Maternal-fetal medicine practices in United States hospital systems anchor prescribing.
- Diabetes Complications:Perioperative management, hyperosmolar states, and diabetic ketoacidosis require intensive insulin protocols. Hospital emergency departments and intensive care units concentrate acute use.
Type 2 diabetes dominates installed base. Type 1 diabetes is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insulin consumption patterns diverge sharply across North American jurisdictions, with the United States exhibiting pharmacy-centric dispensing dominance while Canada maintains tighter provincial formulary integration and Mexico's private sector drives branded analog demand.
United States
Medicare Part D enrollment and commercial insurance integration concentrate demand for long-acting analogs and pump systems. The Inflation Reduction Act's price caps directly constrain manufacturer net revenue realization while accelerating biosimilar substitution pathways. Boston's academic medical centers anchor pediatric Type 1 diabetes automated delivery adoption.
Canada
Provincial drug benefit programs and Health Canada's interchangeability standards shape biosimilar penetration rates. The Patented Medicine Prices Review Board's pricing guidelines moderate list-price escalation relative to US benchmarks. Ontario's Greater Toronto Area concentrates endocrinology specialist capacity and pump training infrastructure.
Mexico
Private insurance expansion and out-of-pocket purchasing sustain branded insulin analog demand despite public sector human insulin provision. COFEPRIS regulatory pathways for biocomparable products lag FDA timelines by 18-24 months. Mexico City's private hospital networks anchor premium delivery system adoption.
North America Insulin Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where manufacturing scale and vertical integration separate leaders from followers. The North America insulin landscape consolidates around three dominant recombinant DNA fermentation networks controlling active pharmaceutical ingredient supply. Strategic archetypes include integrated biopharmaceutical conglomerates, biosimilar-focused specialists, and device-pump hybrid players. Competitive moves center on backward integration into fermentation capacity and algorithm licensing for automated delivery systems.
Among integrated biopharmaceutical conglomerates, Novo Nordisk and Eli Lilly and Company exemplify the scale-driven tier, occupying positions defined by captive supply chains and decades-long therapeutic category presence. Sanofi represents the biosimilar-specialist vector within this consolidated structure.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| Merck & Co., Inc. |
| Biocon Limited |
| Pfizer Inc |
| Becton Dickinson and Company |
| MannKind Corporation |
| Medtronic |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on recombinant DNA fermentation capacity in Denmark, the United States, and France determines both pricing tier spreads and supply chain shape across the North America insulin landscape. The Inflation Reduction Act's Medicare price caps compress net realization for long-acting analogs while cold chain logistics costs widen geographic price differentials between urban and rural pharmacy access points.
Pricing Analysis
Long-term offtake agreements between insulin manufacturers and pharmacy benefit managers anchor pricing structures, with rebate-driven contracting dominating over spot-market transactions. Price differentiation rests on interchangeability designation under FDA standards and vertical integration into active pharmaceutical ingredient production. Cost compression in the biosimilar tier is intensifying because state-level substitution laws accelerate volume migration. Medicaid programs and safety-net clinics exhibit highest price sensitivity, while pediatric Type 1 diabetes populations in academic medical centers show lowest sensitivity due to algorithm-driven pump system preferences.
Supply Chain Analysis
Export-control regimes governing recombinant DNA technology and biologics manufacturing equipment limit capacity expansion outside established fermentation networks in Denmark, the United States, and India. Raw material dependencies center on E. coli and Saccharomyces cerevisiae expression system cell banks, chromatography resins, and pharmaceutical-grade water systems. Single-source vulnerability concentrates in three manufacturers controlling insulin bulk supply. Distribution runs through temperature-controlled logistics networks from manufacturing sites to retail pharmacy and mail-order channels, with last-mile cold chain integrity adding substantial landed cost in rural geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as patient self-administration preferences and automated dosing algorithm adoption create distinct subsegments requiring specialized capabilities. The shift from clinical to home-based therapy opens niches for connectivity-enabled delivery systems and remote monitoring platforms.
For Market Incumbents: Entrench manufacturing scale advantage through captive fermentation capacity expansion and algorithm licensing for closed-loop artificial pancreas systems. Biosimilar substitution pressure from Sanofi and emerging biocomparable specialists threatens margin pools in long-acting analogs. Backward integration into continuous glucose monitoring sensor production secures interoperability control and recurring software revenue streams.
For New Entrants and Emerging Players: Pursue long-acting biosimilar white space as patent cliffs for glargine and degludec analogs open retail pharmacy substitution pathways. The most penetrable segment sits in state-level copay cap markets like Colorado, Illinois, and Minnesota where volume access hinges on interchangeable designation. A go-to-market angle anchored in 340B program participation and federally qualified health center partnerships captures underinsured population demand.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors device-pump hybrid specialists with FDA-cleared algorithms and established pharmacy benefit manager formulary placement. Long-term viability over the next decade hinges on convergence with continuous glucose monitoring and telehealth titration protocols. Acquisition targets should demonstrate proprietary communication protocols or open-source standard adoption enabling sensor-pump interoperability. The signal to watch is CMS reimbursement rulemaking on automated insulin delivery systems as an inflection indicator for algorithm licensing revenue potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA interchangeability designation accelerates biosimilar substitution across state pharmacy channels. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Denmark and the United States secures active pharmaceutical ingredient supply dominance. |
| Software Companion Development | Algorithm licensing for automated dosing generates recurring revenue beyond hardware sales cycles. |
| Hospital System Partnership | Academic medical center alliances anchor pediatric Type 1 diabetes pump adoption and training infrastructure. |
| Reimbursement Strategy | Medicare Part D and commercial formulary placement determines patient access thresholds and net price realization. |
Research Methodology
Desk research of FDA approval databases, CMS Medicare claims data, and formulary submission records preceded structured interviews with regulatory affairs directors at insulin manufacturers, pharmacy benefit manager formulary leads, hospital procurement managers, and endocrinology practice administrators. Secondary validation drew from Health Canada interchangeability standards, state-level pharmacy substitution statutes, and clinical trial registries. Bottom-up prescription volume modeling and top-down revenue reconciliation triangulated market size estimates.
Assumptions held fixed include current FDA biosimilar review timelines and existing Medicare price cap mechanics, while variables included biosimilar interchangeability adoption rates and automated insulin delivery algorithm penetration. The analytical framework segmented by product type, delivery mode, end user, and therapy area across the analysis window. CAGRs derived from patient population growth, dosing intensity trends, and price trajectory modeling. Forecast inputs incorporated Inflation Reduction Act implementation pace and continuous glucose monitoring convergence adoption curves.
Macroeconomic conditions sit as an overlay; deviation in commercial insurance coverage rates, Medicaid expansion policy, or biologics manufacturing input costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and reimbursement mechanism durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
France Diabetes Devices Market