
 Steam Sterilizer Bag Market | 2026-2036
Steam Sterilizer Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Sterilizer Bag Market Insights
The capital-intensity divergence between integrated film producers and converted-only suppliers is unwinding competitive stability in the steam sterilizer bag landscape. 3M Company leverages captive polymer science to sustain margin control across Tyvek-laminated portfolios. Amcor Plc anchors its position through backward integration into medical-grade polyethylene extrusion, while Getinge AB differentiates by bundling sterilizer bags with autoclave service contracts.
Steam sterilizer bags are heat-sealable, breathable pouches engineered from medical-grade polymers or spunbonded olefin laminates, designed to maintain sterility after autoclave cycles at 121–134°C while permitting steam penetration and subsequent dry-out. Their primary purpose is to package surgical instruments, dental tools, and laboratory equipment for terminal sterilization, ensuring aseptic presentation at point of use. Pouch bags lead unit volume due to pre-formed convenience in high-throughput hospital central sterile supply departments, while roll bags capture growing share among cost-conscious clinics that cut-to-length for variable instrument sizes. Tyvek material commands premium positioning because its porous structure balances microbial barrier performance with steam permeability, whereas polyethylene dominates in price-sensitive disposable applications.
FDA 510(k) requirements and ISO 11607 standards govern sterile barrier system validation in the United States, compelling manufacturers to invest in accelerated aging and seal-strength documentation. The EU Medical Device Regulation (MDR) and CE marking protocols in Europe impose equivalent technical file burdens, with notified bodies scrutinizing biocompatibility and sterilization compatibility claims more intensively than under the prior MDD framework. Stakeholders must monitor evolving EPA and state-level single-use plastic restrictions, as material substitution mandates could disrupt established polyethylene supply chains without equivalent performance alternatives certified for steam sterilization cycles.
Market Dynamics
The FDA's updated guidance on reusable medical device packaging is compressing validation timelines while elevating documentation burdens, forcing suppliers to restructure quality assurance workflows and accelerate sterilization compatibility testing cycles.
Growth Catalysts
- EU MDR Compliance Deadlines:Germany's centralized sterilization services are upgrading to premium Tyvek-laminated bags to meet intensified biocompatibility scrutiny from notified bodies under the Medical Device Regulation framework.
- Dental Outpatient Expansion:Tightened sterilization protocols in dental clinics across the United States are converting single-use wrapping to validated steam sterilizer pouches for instrument terminal processing.
- Autoclave Temperature Standardization:The shift toward 134°C vacuum-assisted cycles is driving material substitution toward high-density polyethylene laminates that withstand accelerated thermal stress without seal degradation.
Market Restraints
- Medical-Grade Polyethylene Concentration:Backward-integrated film producers in the United States and Germany control resin formulation specifications, limiting converted-only suppliers' margin flexibility during feedstock volatility.
- ISO 11607 Validation Burden:Accelerated aging studies and seal-strength documentation requirements extend product launch timelines by 12-18 months for new bag geometries.
- Single-Use Plastic Substitution Risk:EPA and state-level restrictions on polyethylene disposal threaten established supply chains where compostable alternatives lack steam sterilization certification.
Strategic Opportunities
- Indian Dental Clinic Modernization:CDSCO alignment with ISO 13485 standards in urban clusters creates first-mover positioning for pre-validated pouch formats in a historically unregulated sterilization supply market.
- Service Contract Bundling:Autoclave manufacturers are integrating consumables procurement into equipment leasing agreements, opening captive channel access for bag suppliers with preventive maintenance capabilities.
- Biodegradable Polymer Convergence:PLA-PHA blends with steam permeability engineering represent white-space material science where compostability and 121°C autoclave compatibility intersect.
Industry Challenges
- Polymer Science Talent Scarcity:Medical-grade extrusion engineers with steam barrier and biocompatibility expertise command premium compensation, constraining mid-tier suppliers' R&D scaling.
- 510(k) Resubmission Complexity:FDA requests for additional seal-strength data on modified adhesive formulations reset review clocks, disrupting launch synchronization with autoclave OEM refresh cycles.
- Legacy ERP Integration:Hospital central sterile supply departments require EDI connectivity for automated reordering, forcing bag suppliers to retrofit small-batch operations with enterprise software infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Sterilizer Bag Market |
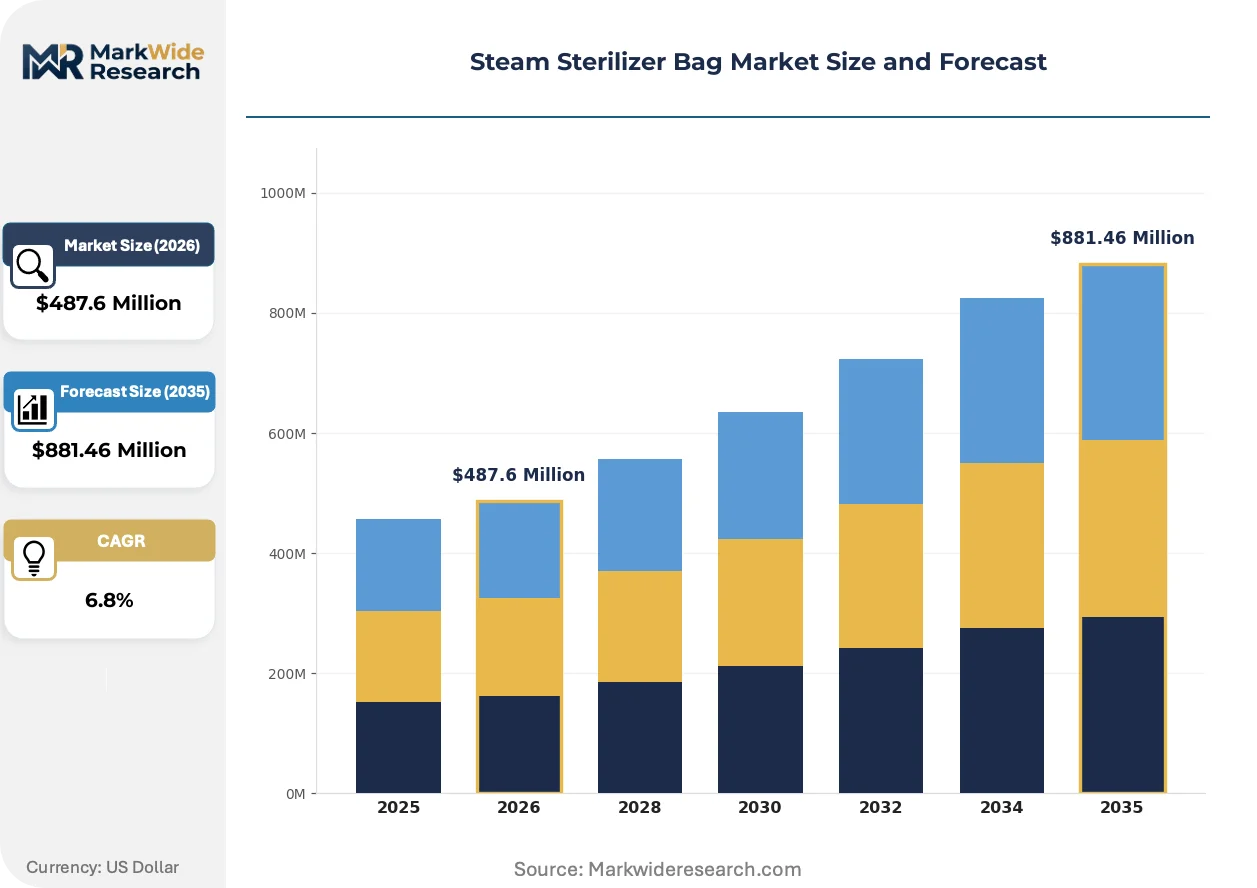
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Pouch Bags, Roll Bags, Custom Bags Material: Polyethylene, Polypropylene, Tyvek, Nylon End User: Hospitals, Clinics, Laboratories, Dental Offices Certification: ISO, CE, FDA, GMP |
| Companies Covered | 3M Company, Steris Corporation, BD (Becton Dickinson), Amcor Plc, DuPont, Getinge AB, Solventum Corporation, Sotera Health, West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Sterilizer Bag Market Trends and Innovations
Material science advances and regulatory compression are reconfiguring competitive advantage around validation speed rather than commodity scale, with differentiation migrating toward integrated sterilization workflow design.
Tyvek-spunbonded olefin laminates with proprietary heat-seal coatings are fragmenting the premium segment as dental service organizations consolidate purchasing around pre-validated, color-change indicator-integrated pouch formats. Large multi-site clinic chains in Texas and Florida are mandating these specifications in master service agreements, compressing price negotiation leverage for standard polyethylene alternatives.
REACH substance restriction proposals targeting perfluorinated compounds in packaging materials are forcing European manufacturers to reformulate barrier coatings ahead of 2026 sunset dates. The ECHA consultation process has accelerated substitution R&D timelines, with German sterilization service providers now requiring supplier declarations on fluorine content for all new bag qualifications.
Hospital procurement departments are consolidating sterilization consumables into multi-year enterprise agreements that bundle bags, indicators, and chemical integrators under single-source accountability. This behavior concentrates contract value with suppliers offering validated sterile barrier system portfolios rather than discrete commodity pouches, most visibly in California and New York health system alliances.
Steam Sterilizer Bag Market Segmentation
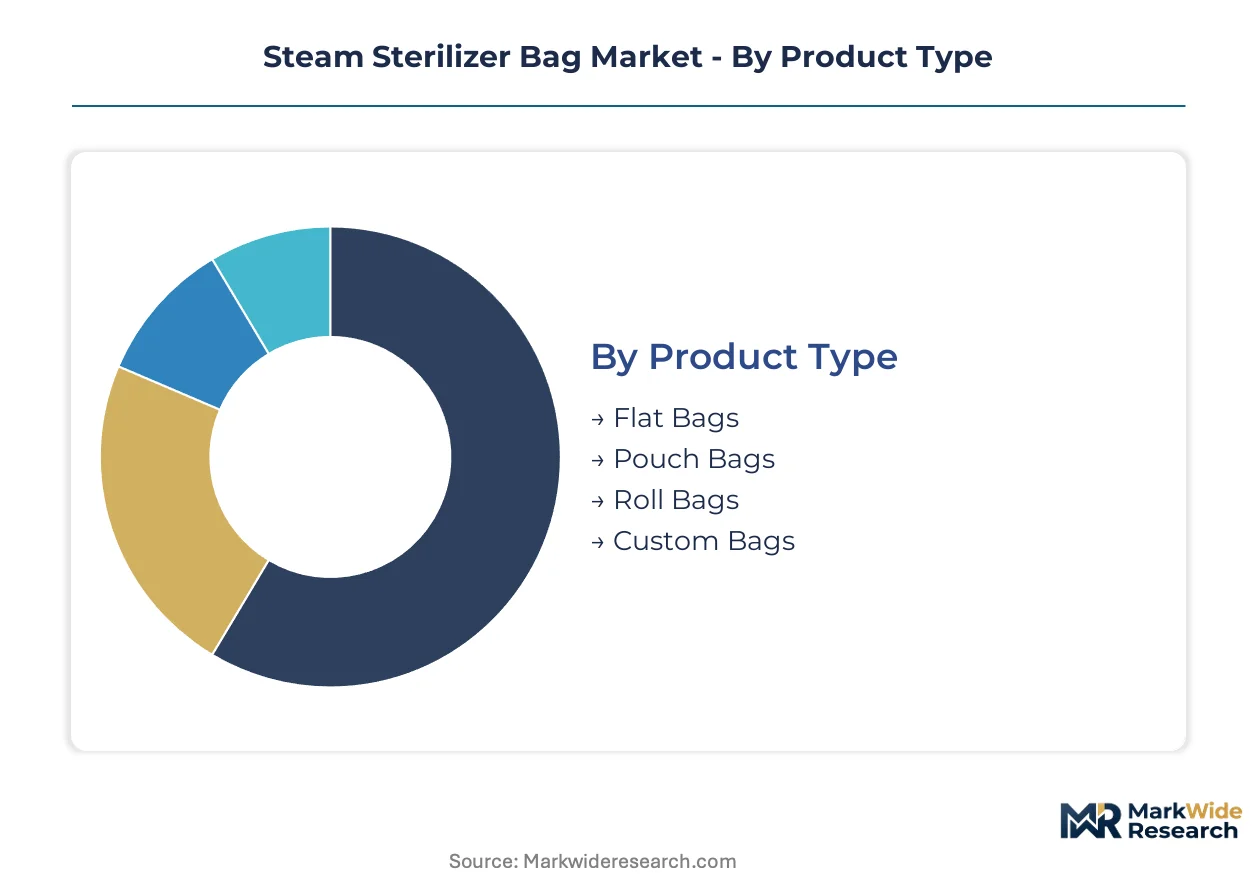
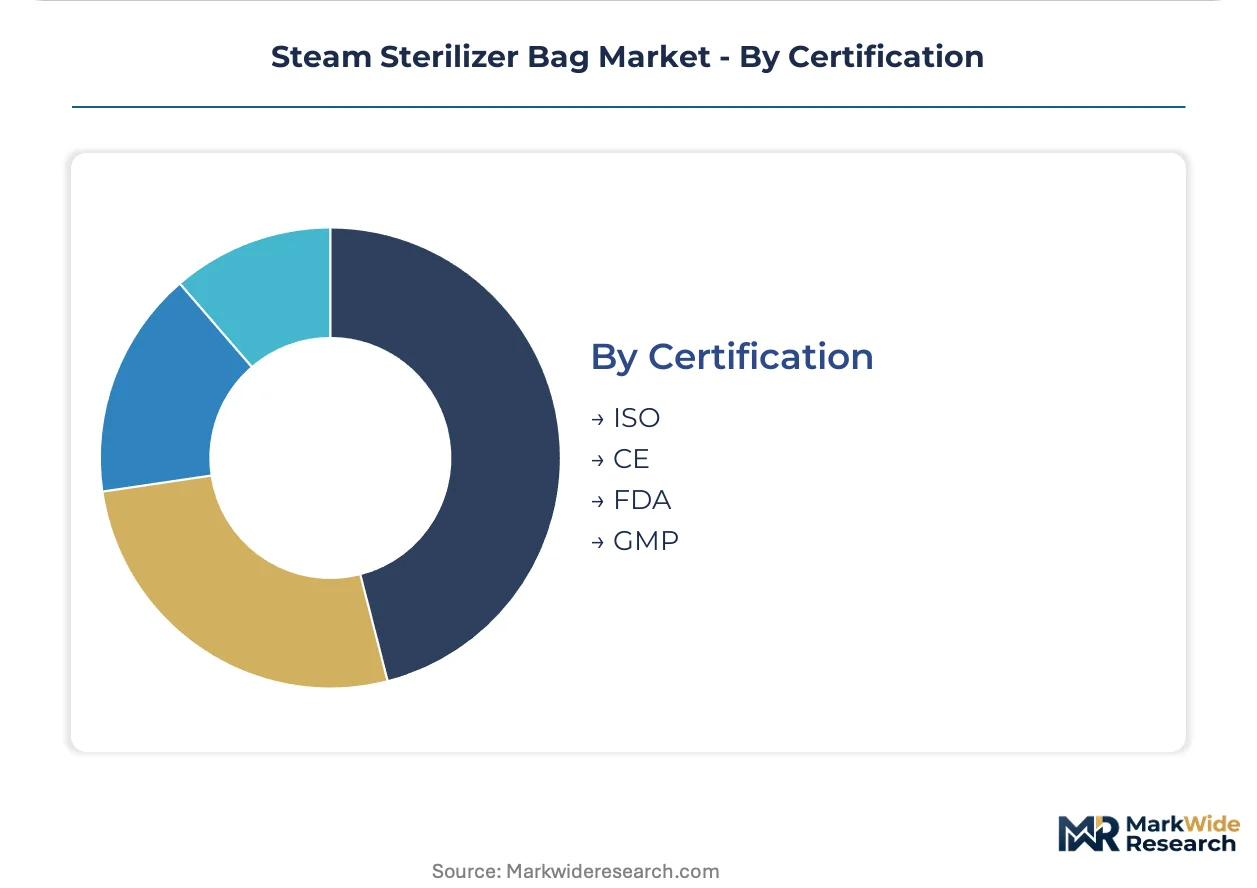
Steam sterilizer bag procurement channels diverge sharply by product format and end-use scale, with hospital central sterile supply departments favoring pre-formed pouches while independent clinics source roll formats through dental distributors. Material certification tiers further partition the channel map, as ISO-validated portfolios penetrate integrated delivery networks and FDA-cleared alternatives dominate outpatient surgery centers.
Product Type:
Channel mix varies by sterilization throughput and labor economics, with high-volume health systems consolidating around formats that minimize handling time.
- Pouch Bags:Pre-formed, heat-sealed envelopes with integrated chemical indicators streamline terminal sterilization workflows in hospital central sterile supply departments. Demand concentrates in Germany's centralized sterilization services, where Tyvek-laminated pouches command premium positioning under intensified MDR biocompatibility scrutiny.
- Roll Bags:Continuous sheeting cut to instrument-specific lengths reduces material waste for variable-sized loads. Dental clinics in Texas and Florida are converting to roll formats as service organization purchasing consolidates around cost-per-cycle metrics.
- Flat Bags:Two-dimensional sheets requiring manual folding and sealing serve low-throughput veterinary and research applications.
- Custom Bags:Dimension-specific fabrication for robotic surgical instrument sets and orthopedic implant trays.
Pouch bags dominate installed base. Roll bags are where expansion concentrates.
Material:
Cost tier alignment separates premium barrier performance from commodity disposability, with resin formulation control determining supplier margin sustainability.
- Tyvek:Spunbonded high-density polyethylene olefin provides porous microbial barrier integrity with steam permeability. Germany's notified bodies under MDR framework are driving premium adoption through intensified biocompatibility documentation requirements for terminal sterilization applications.
- Polyethylene:Medical-grade low and high-density variants dominate price-sensitive disposable volumes. EPA and state-level single-use plastic restrictions threaten established supply chains where compostable alternatives lack steam sterilization certification.
- Polypropylene:Higher thermal tolerance supports 134°C vacuum-assisted autoclave cycles without seal degradation.
- Nylon:Superior puncture resistance for sharp instrument containment in orthopedic and ophthalmic surgical sets.
Polyethylene dominates installed base. Tyvek is climbing the fastest.
End User:
Customer type determines validation burden and contract structure, with enterprise procurement favoring integrated sterile barrier system portfolios.
- Hospitals:Central sterile supply departments require EDI-enabled reordering systems and multi-year enterprise agreements bundling bags with chemical integrators. California and New York health system alliances are consolidating sterilization consumables under single-source accountability frameworks.
- Dental Offices:Outpatient sterilization protocol tightening is converting single-use wrapping to validated steam sterilizer pouches. CDSCO alignment with ISO 13485 standards in Indian urban clusters creates first-mover positioning for pre-validated formats.
- Clinics:Ambulatory surgery centers balance throughput efficiency against limited storage footprint.
- Laboratories:Research and diagnostic facilities prioritize batch traceability and lot-controlled release documentation.
Hospitals dominate installed base. Dental offices are gaining share fastest.
Certification:
Geography determines which validation frameworks gate market access, with regulatory divergence fragmenting product qualification pathways.
- ISO:ISO 11607 sterile barrier system standards govern global baseline validation, with accelerated aging studies and seal-strength documentation extending launch timelines. CDSCO alignment in India and MFDS recognition in South Korea enable cross-border portfolio leverage.
- FDA:510(k) requirements for reusable medical device packaging compress validation timelines while elevating documentation burdens. FDA requests for additional seal-strength data on modified adhesive formulations reset review clocks, disrupting launch synchronization.
- CE:EU MDR technical file scrutiny exceeds prior MDD framework intensity for biocompatibility claims.
- GMP:Pharmaceutical manufacturing sterilization protocols impose batch release documentation beyond medical device baselines.
ISO dominates installed base. FDA is where qualification investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in steam sterilizer bags favor net-producing regions with integrated polymer supply chains. Germany and the United States maintain structural surpluses in medical-grade film extrusion, while India and Brazil absorb premium pouch volumes through distributor networks serving fragmented clinic bases.
United States
FDA 510(k) validation requirements for reusable medical device packaging compress product launch timelines while elevating documentation burdens. EPA state-level single-use plastic restrictions in California and New York threaten polyethylene supply chains where compostable alternatives lack steam sterilization certification. Texas and Florida dental service organizations consolidate purchasing around pre-validated Tyvek-laminated pouch formats.
Germany
Centralized sterilization services in Bavaria and North Rhine-Westphalia upgrade to premium Tyvek-laminated bags under intensified EU MDR biocompatibility scrutiny from notified bodies. REACH substance restriction proposals targeting perfluorinated compounds force barrier coating reformulation ahead of 2026 sunset dates. The ECHA consultation process accelerates substitution R&D timelines across medical packaging clusters.
India
CDSCO alignment with ISO 13485 standards in Maharashtra and Karnataka urban clusters creates first-mover positioning for pre-validated pouch formats. Dental clinic modernization in Delhi-NCR converts historically unregulated sterilization supply markets to validated steam sterilizer systems. Import dependency for medical-grade polyethylene concentrates procurement leverage with German and US film producers.
China
NMPA medical device packaging regulations tighten sterile barrier system documentation requirements for domestic manufacturers. Yangtze River Delta polymer science clusters develop high-density polyethylene laminates for 134°C vacuum-assisted autoclave cycles. Export-oriented producers in Guangdong face EU MDR technical file scrutiny exceeding prior MDD framework intensity.
Brazil
ANVISA medical device regulations align with ISO 11607 standards, extending validation timelines for imported sterilization consumables. São Paulo state dental clinic chains adopt roll bag formats to reduce material waste under cost-per-cycle procurement metrics. Import tariffs on medical-grade films protect domestic converted-only suppliers lacking backward resin integration.
Steam Sterilizer Bag Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates possessing captive polymer science capabilities. Three to five integrated multinationals control premium Tyvek-laminated portfolios through proprietary heat-seal coating formulations. Mid-tier converted-only suppliers compete on price-sensitive polyethylene volumes with limited margin flexibility during resin volatility. Dominant competitive moves include backward integration into medical-grade film extrusion and bundling consumables procurement into autoclave equipment leasing agreements.
Among US-based healthcare conglomerates, 3M Company and Solventum Corporation exemplify the integrated archetype with polymer science depth. Swedish industrial group Getinge AB occupies a position representing the equipment-bundling vector. Swiss sterilization specialist Steris Corporation and Australian-American packaging multinational Amcor Plc anchor the diversified multinational tier. DuPont retains material science positioning through spunbonded olefin technology heritage.
| Leading Market Players |
|---|
| 3M Company |
| Steris Corporation |
| BD (Becton Dickinson) |
| Amcor Plc |
| DuPont |
| Getinge AB |
| Solventum Corporation |
| Sotera Health |
| West Pharmaceutical Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Multi-year enterprise agreements bundling sterilization consumables with equipment service contracts lock in supply access and price visibility for hospital central sterile supply departments, insulating integrated suppliers from resin volatility while compressing margin flexibility for converted-only competitors.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium Tyvek-laminated, standard polyethylene, and economy roll formats. Price differentiation separates FDA-cleared portfolios with accelerated aging documentation from commodity ISO-baseline alternatives. Cost compression in polyethylene tiers is intensifying because EPA state-level single-use plastic restrictions threaten established supply chains. Dental clinics in Texas and Florida exhibit highest price sensitivity, while German centralized sterilization services demonstrate lowest sensitivity due to MDR compliance mandates.
Supply Chain Analysis
Strategic stockpiling of medical-grade polyethylene resin dominates converted-only supplier inventory strategy, whereas backward-integrated producers maintain just-in-time extrusion-to-conversion workflows. Supply concentrates in the United States, Germany, and China for medical-grade film extrusion. Raw material dependencies rest on high-density polyethylene resin, spunbonded olefin substrates, and proprietary heat-seal adhesive formulations. Single-source vulnerability concentrates in DuPont's Tyvek substrate technology. Distribution runs through autoclave OEM service contracts, dental distributor networks, and hospital GPO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as dental clinic modernization across India and Brazil creates niches for pre-validated pouch formats, while hospital procurement consolidation in California and New York favors integrated sterile barrier system portfolios over commodity suppliers.
For Market Incumbents: Shield premium positioning by deepening backward integration into medical-grade polyethylene extrusion to offset resin volatility. Accelerate biocompatibility documentation ahead of EU MDR intensified scrutiny from German notified bodies. Channel control through autoclave service contract bundling represents the critical defensive lever against mid-tier price competition. For New Entrants and Emerging Players: Differentiate on biodegradable polymer convergence where PLA-PHA blends achieve steam permeability engineering compatible with 121°C autoclave cycles. Target Indian dental clinic modernization in Maharashtra and Karnataka urban clusters as the most penetrable geography. CDSCO alignment with ISO 13485 standards enables first-mover positioning through pre-validated pouch format introduction. For Investors and Strategic Acquirers: Converted-only suppliers with established dental distributor relationships and pending FDA 510(k) submissions represent compelling acquisition targets. Long-term viability centers on validation speed rather than commodity scale, with material substitution R&D capabilities determining competitive endurance. Watch for EPA state-level polyethylene restriction enforcement as the inflection indicator compelling portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin formulation control insulates margin stability against medical-grade polyethylene feedstock volatility. |
| FDA 510(k) Submission Acceleration | Compressed validation timelines align sterilization compatibility testing with autoclave OEM refresh cycles. |
| Autoclave Service Contract Bundling | Preventive maintenance capabilities open captive channel access for consumables procurement integration. |
| Biodegradable Polymer R&D Investment | PLA-PHA blend engineering addresses compostability mandates where alternatives lack steam sterilization certification. |
| CDSCO Regulatory Alignment | ISO 13485 certification enables first-mover positioning in Indian dental clinic modernization markets. |
Research Methodology
A spread of perspectives from sterilization service directors, dental clinic procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, ISO 11607 technical documentation, EPA regulatory dockets, and hospital procurement database extracts. Bottom-up demand modeling from end-use segments triangulated against top-down polymer resin consumption trends.
Segmentation dimensions modeled include product format, material certification tier, end-use scale, and geographic regulatory cluster across the projection horizon. CAGRs were derived from sterilization cycle volume trajectories and premium material substitution elasticities. Industry-specific forecast inputs incorporated autoclave temperature standardization shifts toward 134°C vacuum-assisted cycles and REACH substance restriction timelines targeting perfluorinated compounds.
The analysis sits within stated boundaries; outcomes outside sustained MDR enforcement intensity, stable medical-grade resin supply, and continued dental outpatient expansion would require recalibration. Forecasts reflect documented assumptions regarding sterilization protocol tightening and centralized service adoption patterns. Revision becomes warranted when EPA state-level polyethylene restriction enforcement crosses thresholds triggering material substitution at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Global Syringe Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Respiratory Masks Market