
 Industrial Flooring Market | 2026-2036
Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Flooring Market Analysis
Distributor networks for specification-grade resin flooring is narrowing as manufacturers consolidate direct-to-contractor relationships. Sika AG leverages its integrated adhesive and flooring portfolio to control project specification from substrate to finish layer. BASF SE anchors its position through captive supply of polyurethane raw materials into commercial and industrial installations. RPM International Inc. competes across multiple brand architectures spanning epoxy coatings to polished concrete systems.
Industrial flooring comprises load-bearing surface systems engineered from cementitious, thermoset resin, or thermoplastic compositions, typically specified to withstand mechanical abrasion, chemical exposure, and static loads exceeding 500 psi in operational environments. These installations serve primarily to protect structural substrates, ensure worker safety through slip resistance, and maintain hygienic or electrostatic discharge conditions in regulated production spaces. Epoxy formulations dominate specification activity in heavy manufacturing and warehousing end uses where chemical resistance and seamless hygiene matter, while polyurethane systems gain share in pharmaceutical cleanrooms requiring thermal cycling durability and flexible crack bridging. Concrete polishing occupies a mature, cost-driven position across retail and light industrial applications where aesthetic finish and dustproofing suffice without chemical containment demands.
EPA VOC regulations constrain solvent-based coating formulations across US industrial flooring projects, pushing waterborne and high-solids epoxy alternatives into specification pipelines. REACH and the EU Green Deal restrict isocyanate and heavy-metal additive content in European resin flooring systems, compelling reformulation investments from suppliers serving EMA-inspected pharmaceutical facilities. OSHA slip-resistance standards and FDA food safety surface requirements further segment product qualification thresholds by end-use jurisdiction. Stakeholders must monitor regulatory divergence between North American and European emission frameworks when allocating R&D and certification budgets across regional product portfolios.
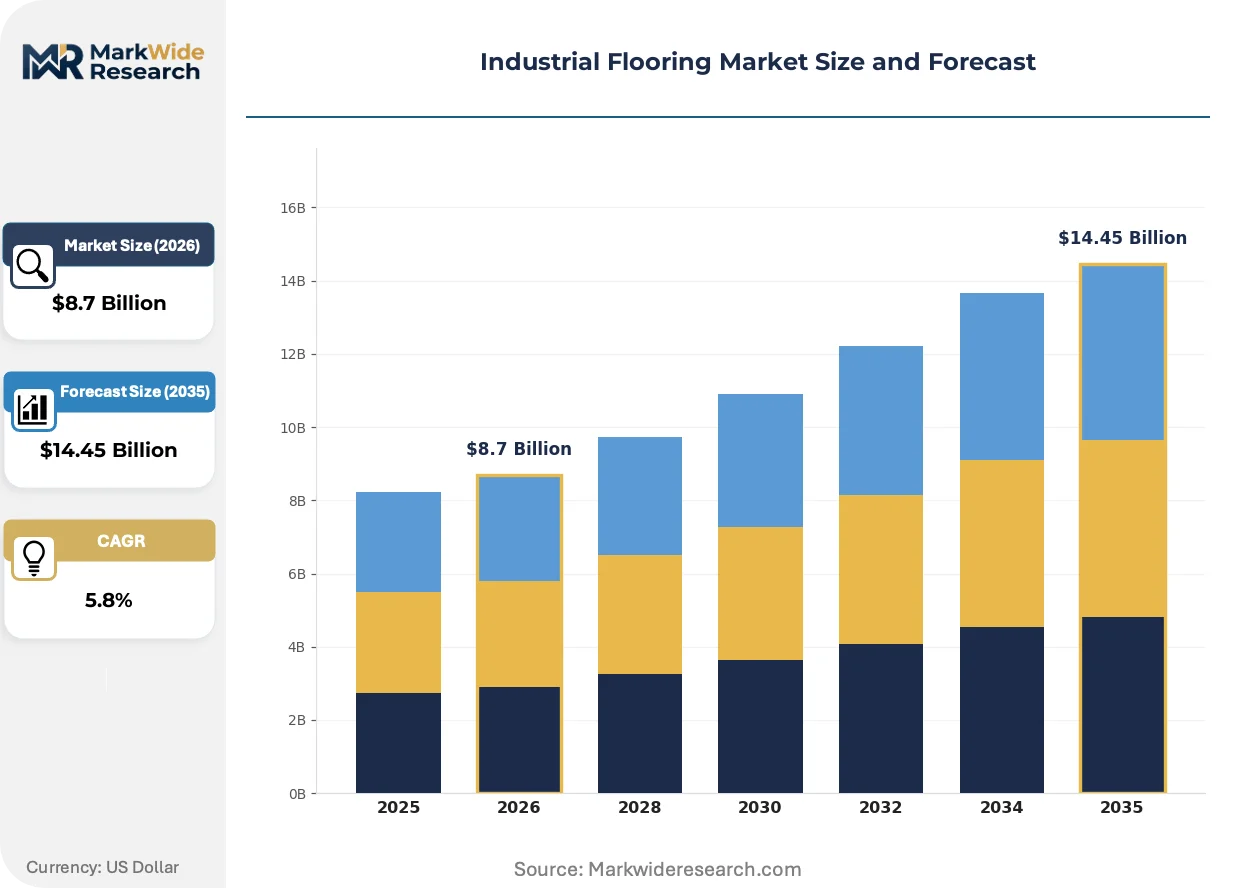
Market Dynamics
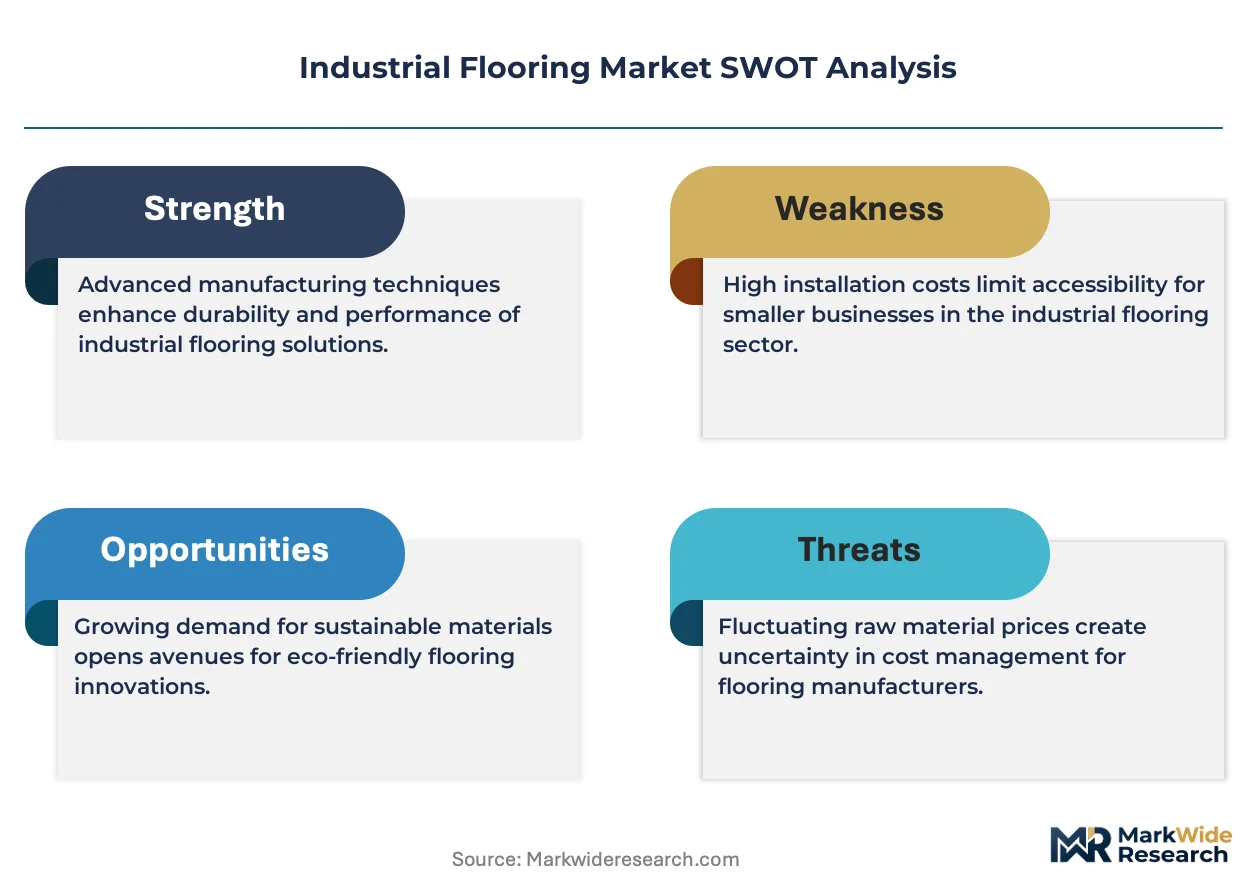
Resin flooring manufacturers face intensifying pressure from REACH and EPA VOC compliance costs that compress formulation margins while forcing rapid substitution of legacy chemistries. The structural imperative to reformulate solvent-based systems is redrawing competitive boundaries between integrated chemical suppliers and specialty coating producers.
Growth Catalysts
- EMA pharmaceutical inspections:Cleanroom flooring specifications across European Union member states now mandate antimicrobial and electrostatic discharge properties, expanding specification-grade resin system demand.
- Automotive manufacturing clusters:German chemical and vehicle production facilities require heavy-load epoxy installations with thermal cycling resistance, anchoring regional specification activity.
- Waterborne epoxy technology:Low-VOC formulation advances enable compliance with evolving EPA emission thresholds across US industrial construction projects.
Market Restraints
- Isocyanate input cost volatility:Polyurethane raw material prices fluctuate with petrochemical feedstock availability, constraining margin predictability for system suppliers.
- Specialized applicator concentration:Certified installation contractors cluster in developed manufacturing regions, limiting project execution capacity in emerging industrial zones.
- Cementitious overlay substitution:Polished concrete systems capture light industrial and retail applications where chemical resistance requirements remain minimal.
Strategic Opportunities
- Biobased resin feedstocks:EU Green Deal procurement incentives favor flooring systems incorporating renewable carbon content in public infrastructure projects.
- Modular cleanroom construction:Prefabricated pharmaceutical production facilities require rapid-install flooring with validated antimicrobial performance.
- Digital specification platforms:Architect and contractor procurement through building information modeling integrations reduces traditional distributor intermediation.
Industry Challenges
- Certified applicator pipeline:Skilled trades capable of moisture-tolerant substrate preparation and self-leveling resin installation remain scarce relative to project demand.
- Multi-jurisdiction compliance:Flooring systems qualified under FDA food contact surfaces require separate validation for EMA-inspected pharmaceutical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Flooring Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Epoxy, Polyurethane, Vinyl End User: Manufacturing, Warehousing, Retail, Pharmaceuticals Technology: Self-Leveling, Coating, Sheet Flooring, Tiles Installation Method: Polished, Seamed, Interlocking, Stitched |
| Companies Covered | RPM International Inc., BASF SE, Sika AG, JOTUN, Akzo Nobel N.V., PPG Industries Inc., MBCC Group, Fosroc Inc., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Flooring Market Emerging Trajectories
Formulation chemistry and installation methodology are converging to address thermal cycling durability, emission compliance, and accelerated project timelines. Three developments are restructuring how industrial flooring is specified, procured, and deployed.
Polyurea spray-applied membrane technology is hybridizing with conventional epoxy build coats to create rapid-cure systems that withstand thermal shock in food processing environments. Pharmaceutical manufacturers with continuous production schedules adopt these hybrid systems to minimize operational downtime during facility renovation. The technology is hybridizing project timelines by compressing installation windows from days to hours, displacing traditional multi-coat epoxy sequences in time-sensitive retrofit applications.
REACH authorization requirements for isocyanate-containing products are forcing reformulation of polyurethane flooring systems across European manufacturing facilities. ECHA regulatory evaluations now extend to catalyst and additive chemistries previously exempt from substance restriction protocols. German automotive and chemical producers face the most acute compliance pressure, accelerating supplier qualification of aliphatic and waterborne polyurethane alternatives.
Facility managers now bundle flooring specification with long-term performance warranties and predictive maintenance monitoring. Traditional material-supply contracts lose ground to integrated service agreements covering substrate assessment, installation, and lifecycle resurfacing. This contracting evolution is most visible in US food and beverage processing plants where FDA surface sanitation requirements demand documented flooring integrity across extended operational periods.
Industrial Flooring Market Segmentation
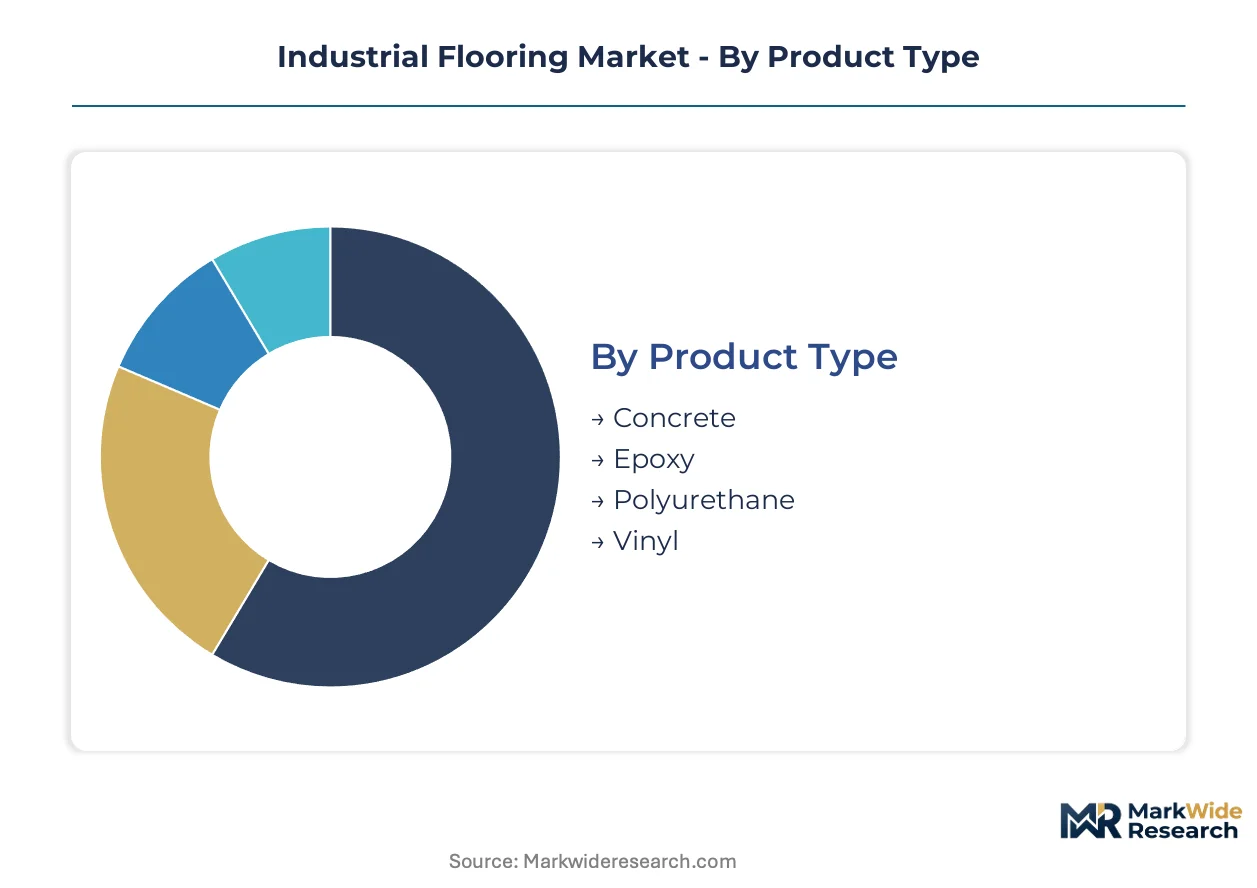
Industrial flooring procurement varies sharply by performance specification and regulatory environment. Segmentation reveals how resin chemistry, installation methodology, and end-use compliance requirements dictate supplier positioning and margin structure across project types.
Product Type:
After-sales intensity runs highest in resin-based systems requiring periodic recoating and substrate repair, while cementitious alternatives demand minimal ongoing service engagement.
- Epoxy:Thermoset resin systems formulated from bisphenol-A or bisphenol-F precursors deliver seamless, chemical-resistant surfaces. German automotive assembly plants and US food processing facilities specify heavy-build epoxy for thermal cycling durability and FDA sanitation compliance.
- Polyurethane:Aliphatic and aromatic isocyanate-based formulations provide flexible crack bridging and impact absorption. EMA-inspected pharmaceutical cleanrooms across France and Switzerland drive specification-grade demand for antimicrobial polyurethane with electrostatic discharge properties.
- Concrete:Cementitious substrates with densifier and stain-guard treatments occupy cost-driven warehouse and retail applications.
- Vinyl:Thermoplastic sheet and tile systems serve light industrial zones with rapid installation requirements and moderate chemical exposure.
By volume, concrete leads. By growth pace, polyurethane is ahead.
End User:
Application intensity segments by operational criticality — continuous production environments demand validated flooring integrity with documented maintenance protocols.
- Manufacturing:Heavy machinery operations and chemical processing require load-bearing surfaces exceeding 500 psi compressive strength. REACH-compliant epoxy installations anchor specification activity across German chemical production clusters.
- Pharmaceuticals:Cleanroom-grade resin systems with ISO 14644-1 particle control and antimicrobial additives face rigorous EMA inspection protocols.
- Warehousing:Polished concrete and thin-film epoxy coatings dominate high-bay storage facilities with forklift traffic and dustproofing requirements.
- Retail:Aesthetic-driven polished concrete and vinyl sheet flooring prioritize visual finish over chemical containment in consumer-facing spaces.
Manufacturing commands the largest project scale. Pharmaceuticals shows the steepest expansion trajectory.
Technology:
Margin structure correlates with application complexity — self-leveling systems require certified substrate preparation and moisture mitigation, capturing premium pricing over commodity coating alternatives.
- Self-Leveling:Fluid-applied resin systems achieving 1/8-inch thickness with automated trowel or rake distribution. US food and beverage plants specify rapid-cure self-leveling epoxy to minimize FDA-regulated production downtime.
- Coating:Thin-film roll-applied or spray-applied resin layers serve protective and decorative functions in light industrial environments.
- Sheet Flooring:Factory-manufactured vinyl or rubber membranes with heat-welded seams for moisture barrier applications.
- Tiles:Modular interlocking or adhesive-set units enabling rapid replacement of damaged sections in high-traffic zones.
Coating technology holds the broadest install base. Self-leveling is gaining share fastest.
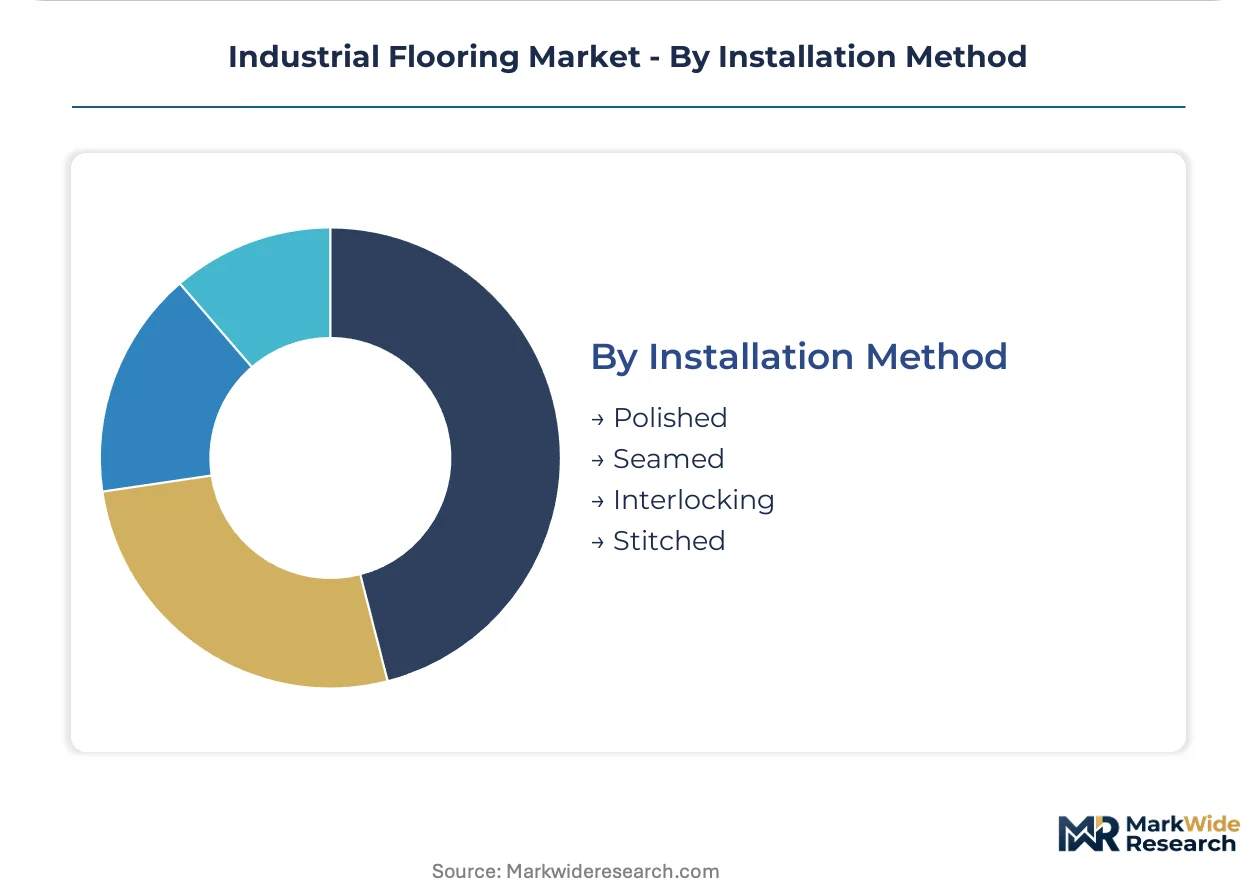
Installation Method:
Supply concentration clusters around certified applicator networks capable of moisture-tolerant substrate preparation and precision finishing.
- Polished:Mechanical grinding and densification of existing concrete slabs to achieve specified gloss levels and surface hardness. Retail and warehouse developers across the US specify polished concrete for LEED contribution and low maintenance burden.
- Seamed:Heat-welded or chemically bonded joints in sheet vinyl and rubber systems creating continuous moisture barriers.
- Interlocking:Floating floor systems with mechanical connection profiles enabling rapid deployment and future relocation.
- Stitched:Specialized welding techniques for heavy-duty PVC or polyurethane sheet in wet processing environments.
Polished methods dominate by project count. Seamed installations command the highest specification grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites the Netherlands' role in European resin flooring distribution, while the Rhine-Main-Danube canal network connects German manufacturing clusters to raw material supply corridors across Central Europe.
United States
Automotive battery gigafactories in Michigan and Tennessee drive heavy-load epoxy specifications for thermal cycling resistance. EPA VOC emission thresholds constrain solvent-based coating formulations across industrial construction projects. The Houston Ship Channel petrochemical complex anchors Gulf Coast demand for chemical-resistant polyurethane systems in refinery maintenance.
Germany
EMA-inspected pharmaceutical facilities in Baden-Württemberg mandate antimicrobial flooring with electrostatic discharge validation. REACH authorization protocols restrict isocyanate content in polyurethane formulations serving automotive assembly plants. The BASF Ludwigshafen chemical cluster concentrates specification-grade resin system procurement for adjacent manufacturing operations.
China
Semiconductor fabrication facilities in the Yangtze River Delta specify cleanroom-grade flooring with ISO 14644-1 particle control. NMPA pharmaceutical manufacturing guidelines drive antimicrobial system adoption in biologics production zones. The Shanghai Pudong airport logistics hub concentrates warehousing epoxy installations for cold-chain pharmaceutical distribution.
India
CDSCO-regulated active pharmaceutical ingredient plants in Gujarat and Maharashtra require electrostatic discharge flooring for hazardous powder handling. BIS construction material standards increasingly reference slip-resistance performance in industrial surface specifications. The Mumbai-Pune manufacturing corridor concentrates automotive and chemical processing installations driving epoxy demand.
Switzerland
Swissmedic-inspected biologics facilities in Basel mandate validated flooring integrity with documented maintenance protocols for continuous production environments. The country's dual-track regulatory alignment with both EU REACH and independent pharmaceutical standards creates specialized compliance demand. The Novartis-Roche manufacturing cluster anchors specification-grade antimicrobial polyurethane procurement.
Industrial Flooring Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material supply. The industrial flooring market structures around integrated chemical conglomerates with captive resin production, specialty coating houses with formulation expertise, and construction chemical distributors with certified applicator networks. Three archetypes dominate: vertically integrated material suppliers controlling formulation-to-finish value chains; regional specialists with moisture-tolerant substrate preparation capabilities; and diversified coating conglomerates spanning industrial, protective, and decorative segments. Competitive moves concentrate on direct-to-contractor specification relationships and rapid-cure technology licensing.
Among European-integrated chemical suppliers, BASF SE and Sika AG exemplify platform control through upstream resin production and downstream specification influence. RPM International Inc. occupies a position spanning multiple brand architectures. These three anchors represent distinct strategic postures: captive raw material supply, integrated adhesive-flooring portfolios, and multi-brand market coverage.
| Leading Market Players |
|---|
| RPM International Inc. |
| BASF SE |
| Sika AG |
| JOTUN |
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| MBCC Group |
| Fosroc Inc. |
| The Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
Isocyanate feedstock volatility from European petrochemical complexes determines both the spread between specification-grade polyurethane and commodity epoxy tiers and the geographic clustering of certified applicator networks. REACH authorization timelines for aromatic isocyanates compress formulation margins while forcing rapid qualification of aliphatic alternatives, redrawing supplier cost structures across German automotive and pharmaceutical installations.
Pricing Analysis
Three-tier pricing structure across specification-grade, commercial-grade, and economy-grade resin systems dominates procurement contracts. Price differentiation hinges on EMA certification level for pharmaceutical cleanroom validation and volume scale for warehousing rollouts. Cost compression in specification-grade polyurethane is intensifying because REACH-driven reformulation expenses transfer downstream. Warehouse developers exhibit the highest price sensitivity; EMA-inspected biologics facilities show minimal elasticity due to validated performance requirements.
Supply Chain Analysis
Upstream bisphenol-A and isocyanate production concentrates in Germany, Belgium, and the Netherlands, anchoring raw material availability for European resin flooring formulation. Formulation chemistry draws from petrochemical feedstocks, epoxy curing agents, and antimicrobial additive packages. Single-source vulnerability runs through certified applicator pipelines capable of moisture-tolerant substrate preparation. Distribution runs through manufacturer-direct specification relationships with EPC contractors and facility managers, bypassing traditional distributor intermediation in pharmaceutical and food processing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installation capacity scarcity constrains market expansion more than raw material availability, with qualified applicator pipelines lagging project demand across pharmaceutical and battery manufacturing clusters. This capability gap rewards early investment in workforce development and rapid-cure technology licensing.
For Market Incumbents: Pre-empt polished concrete substitution in light industrial verticals by bundling predictive maintenance monitoring with specification-grade epoxy installations. Cementitious overlay systems threaten margin compression in warehousing and retail applications where chemical resistance requirements remain minimal. Defend position through captive supply of polyurethane raw materials and direct-to-contractor digital specification platforms that reduce distributor intermediation. For New Entrants and Emerging Players: Build out certified applicator networks in India's Mumbai-Pune manufacturing corridor and China's Yangtze River Delta semiconductor fabrication zones, where CDSCO and NMPA pharmaceutical guidelines drive antimicrobial flooring demand but local installation capacity remains underdeveloped. Target modular cleanroom construction projects requiring rapid-install flooring with validated electrostatic discharge properties. Penetrate through technology licensing partnerships with regional construction chemical distributors possessing existing contractor relationships. For Investors and Strategic Acquirers: EU Green Deal biobased procurement mandates reshape the acquisition landscape toward formulation houses with renewable carbon content capabilities and REACH-compliant aliphatic polyurethane portfolios. Long-term viability centers on suppliers capable of serving both EMA-inspected pharmaceutical environments and automotive manufacturing clusters with unified certification investments. Monitor ECHA regulatory evaluations extending to catalyst and additive chemistries as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | BASF SE's captive raw material production anchors margin control for polyurethane system suppliers serving REACH-regulated European facilities. |
| Digital Specification Platform Deployment | Sika AG's building information modeling integrations reduce distributor intermediation and lock project specification from substrate to finish layer. |
| Certified Applicator Network Expansion | Regional specialists with moisture-tolerant substrate preparation capabilities capture premium pricing in pharmaceutical cleanroom installations. |
| Rapid-Cure Technology Licensing | Polyurea spray-applied membrane hybrid systems compress installation windows from days to hours in FDA-regulated food processing renovations. |
| Biobased Resin Feedstock Transition | EU Green Deal procurement incentives favor flooring systems incorporating renewable carbon content in public infrastructure projects. |
Methodological Framework
The analysis maps epoxy, polyurethane, concrete densifier, and vinyl sheet sub-sectors, each validated through plant engineers, EPC contractors, facility managers, and resin formulation specialists. Primary interviews with certified applicators and pharmaceutical cleanroom specification consultants combined with secondary validation from ECHA substance restriction databases, EPA VOC emission filings, and customs trade data. Bottom-up project pipeline assessment and top-down chemical consumption triangulation anchored volume estimates across the analysis window.
Assumptions held fixed include REACH authorization timelines for isocyanate-containing products and EPA VOC threshold evolution, while variables included pharmaceutical manufacturing capacity expansion rates and automotive battery gigafactory construction cadence. Segmentation modeling spanned resin chemistry, installation methodology, end-use regulatory environment, and regional production cluster. CAGRs were derived from weighted average of project pipeline visibility and raw material consumption trends, with thermal cycling durability requirements and antimicrobial additive adoption as industry-specific demand drivers.
Stress conditions across isocyanate price volatility, certified applicator availability, and EMA inspection protocol stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and substitution elasticity between resin systems and cementitious alternatives. Cross-checking against EPC contractor backlog disclosures and pharmaceutical facility construction permits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Thinset Mortar Market