
 Window Film Market | 2026-2036
Window Film Market Size, Share, and Industry Trends Forecast 2026-2036
Window Film Market Analysis
California's Title 24 building energy code is restructuring demand specifications across the North American window film supply chain. Eastman Chemical Company leverages its captive polyester production to sustain margin control across metallized and ceramic film lines. Johnson Window Films anchors its position through specialized automotive OEM channels, while 3M Company differentiates via patent density in multi-layer optical film technology.
Window film comprises thin polymer laminates, typically polyethylene terephthalate between 0.5 and 2 mils thick, engineered with UV absorbers, metal oxides, or nano-ceramic dispersions to modulate solar transmission, thermal radiation, and visible light throughput for glazing systems. Solar control film dominates value capture due to premium pricing on spectrally selective ceramic grades, while safety film occupies a mature, specification-driven segment tied to blast-mitigation and hurricane-impact building codes. Nanotechnology film represents the fastest-expanding technology category as manufacturers displace dyed and metallized alternatives with infrared-blocking nano-ceramic layers that avoid signal interference.
The US EPA Energy Star program and the EU Green Deal's building renovation targets collectively shape product certification requirements and retrofit incentive eligibility across major demand centers. China's GB standards for building energy efficiency, administered by the Ministry of Housing and Urban-Rural Development, enforce solar heat gain coefficient limits that filter market access for imported film suppliers. Stakeholders must monitor divergence between regional test protocols—ASHRAE versus ISO solar metrics—as this friction determines which product portfolios qualify for public procurement and utility rebate programs.
Market Dynamics
The window film market is restructuring around ceramic nano-particle technology, which is displacing metallized films in automotive and architectural applications due to superior infrared rejection without electromagnetic interference.
Growth Catalysts
- California Title 24 energy code:Mandatory solar heat gain coefficient thresholds for commercial glazing retrofits are pulling specification-grade ceramic films into new construction and renovation projects across the state.
- Automotive OEM thermal management:Electric vehicle manufacturers are integrating heat-rejection films into factory glass to reduce HVAC load and extend battery range in high-temperature climates.
- China megacity construction:Guangzhou, Shenzhen, and Chengdu tower developments are driving bulk procurement of high-performance films for commercial facade retrofits under GB building efficiency standards.
Market Restraints
- Polyester feedstock concentration:Captive production of PET substrate by integrated chemical majors limits margin leverage for independent film converters and coating specialists.
- Regional test protocol divergence:ASHRAE solar metrics in North America versus ISO standards in Europe create product qualification friction and duplicate certification costs for multi-market suppliers.
- DIY installation quality variance:Consumer-applied films in residential channels generate warranty claims and reputation risk that constrains brand premium capture.
Strategic Opportunities
- Smart glass convergence:Electrochromic and thermochromic glazing systems create attach opportunities for switchable film layers in premium commercial towers.
- India building stock retrofit:BIS energy efficiency standards for existing commercial structures open specification pathways for solar control films in Mumbai and Delhi NCR thermal retrofits.
- Utility rebate program expansion:EPA Energy Star certification alignment positions film suppliers for demand-side management incentives in US municipal procurement.
Industry Challenges
- Nano-dispersion manufacturing scale-up:Uniform ceramic particle distribution across wide-web coating lines requires capital-intensive process engineering that strains mid-tier producers.
- Multi-certification timeline compression:Simultaneous pursuit of blast-mitigation, hurricane-impact, and energy performance ratings stretches technical validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Film Market |
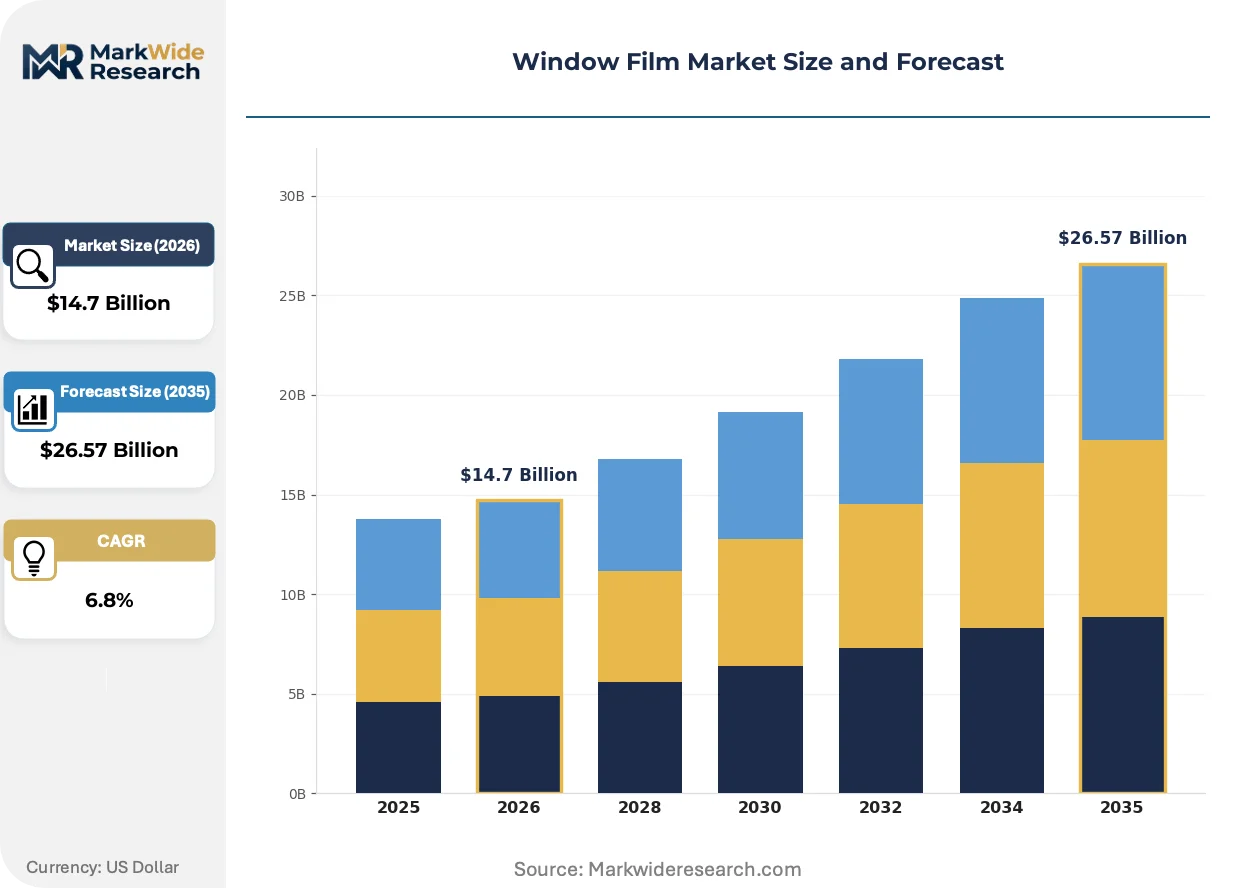
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Control Film, Safety Film, Decorative Film, Insulating Film Application: Automotive, Residential, Commercial, Government Technology: Dyed Film, Metallized Film, Ceramic Film, Nanotechnology Film End User: Manufacturers, Distributors, Installers, Retailers |
| Companies Covered | Johnson Window Films, Madico, 3M Company, LINTEC Corporation, Saint-Gobain Performance Plastics Corporation, Eastman Chemical Company, LLumar, Solar Gard, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Film Market Emerging Trajectories
Ceramic nano-technology is rewriting competitive advantage in window films, while regulatory energy codes and shifting procurement models reshape how value flows through the supply chain.
Sputtered nano-ceramic dispersions are rewriting the performance hierarchy in solar control films. These infrared-blocking layers reject thermal radiation without the signal interference that plagues metallized alternatives. Automotive OEM glass suppliers and commercial tower specifiers are accelerating adoption of ceramic grades for 5G transparency and GPS reliability. The technology is rewriting margin structures by collapsing the premium that dyed and metallized films once commanded in mid-market segments.
REACH chemical registration requirements in Europe are tightening the approved substance list for UV stabilizers and adhesives used in film laminates. Manufacturers must reformulate product lines to maintain CE marking eligibility for architectural applications. The safety film segment faces the steepest compliance burden, as blast-mitigation certifications depend on adhesive performance windows that new chemistries must revalidate.
Direct procurement from coating specialists is compressing traditional distribution layers in the commercial retrofit channel. Facility managers and glazing contractors are establishing supply relationships that bypass regional distributors for large-volume tower projects. This pattern is most visible in China's tier-one cities, where state-owned developers centralize specification decisions and negotiate master service agreements with film manufacturers.
Window Film Market Segmentation
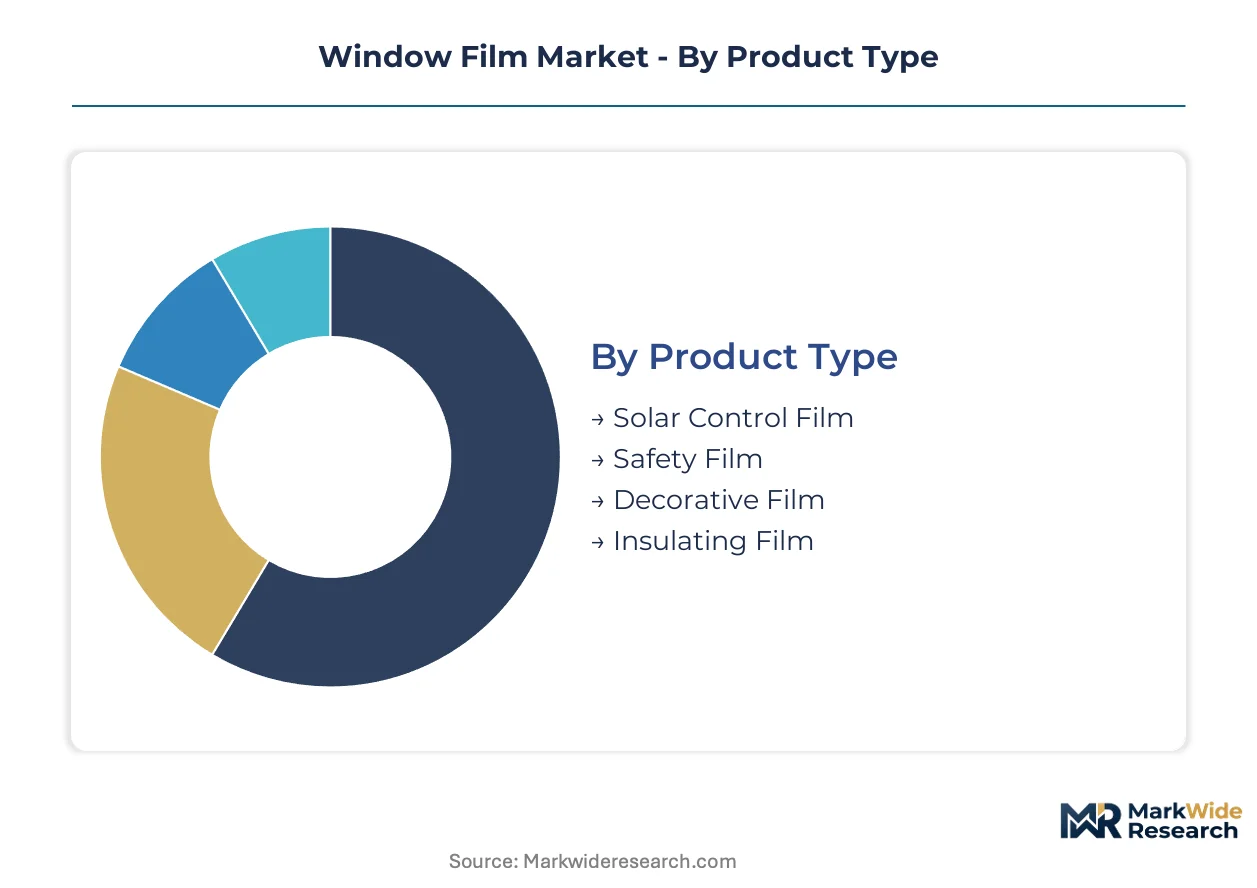
Window film segmentation reveals how procurement patterns split between specification-driven architectural retrofits and volume automotive OEM contracts. Technology tiers separate signal-transparent ceramic solutions from legacy metallized alternatives, while end-user channel structure determines margin capture for coating specialists versus integrated chemical producers.
Product Type:
Buyers in this category differentiate by performance certification requirements and installation scale rather than unit economics alone.
- Solar Control Film:Engineered with spectrally selective coatings—ceramic nano-particles or sputtered metal oxides—to modulate solar heat gain coefficients for glazing systems. Demand concentrates in California commercial retrofits where Title 24 mandates pull specification-grade ceramic grades into new construction and renovation projects across the state.
- Safety Film:Multi-layer PET laminates with high-tack adhesives engineered for blast-mitigation and hurricane-impact resistance per ASTM and Miami-Dade protocols. Procurement clusters in Florida and Gulf Coast states where building codes mandate shatter retention for commercial and government glazing.
- Decorative Film:Frosted, patterned, or colored PET layers for privacy and branding applications in interior commercial spaces.
- Insulating Film:Low-emissivity coatings that reduce winter heat loss in cold-climate residential and commercial installations.
Solar control film leads volumes today; nanotechnology-infused ceramic grades are gaining share fastest.
Application:
Channel economics vary sharply between factory-integrated automotive glass and field-applied architectural retrofit work.
- Automotive:Heat-rejection films specified by EV manufacturers for factory glass integration to reduce HVAC load and extend battery range in high-temperature climates. Procurement concentrates with Guangzhou, Shenzhen, and Chengdu-based OEM glass suppliers serving domestic Chinese EV production.
- Commercial:Specification-grade solar control and safety films for tower facade retrofits under municipal energy efficiency codes. Demand clusters in China megacity construction where state-owned developers centralize procurement decisions.
- Residential:Consumer and contractor-applied films for single-family glazing, constrained by DIY installation quality variance and warranty claim exposure.
- Government:Blast-mitigation and energy performance specifications for federal and municipal building security upgrades.
Commercial application leads volumes today; automotive OEM integration is climbing the fastest.
Technology:
Performance tier and electromagnetic transparency separate winning formulations from legacy alternatives facing displacement.
- Ceramic Film:Nano-particle dispersions of metal oxides—indium tin oxide, antimony tin oxide—in PET substrates blocking infrared without signal interference. Adoption accelerates among automotive OEM glass suppliers and 5G-transparent commercial tower specifications.
- Nanotechnology Film:Advanced ceramic layering with precise particle distribution control for maximum heat rejection at visible light transmission targets. Manufacturing scale-up challenges strain mid-tier producers lacking wide-web coating line investment.
- Metallized Film:Vacuum-sputtered aluminum or silver layers facing displacement due to GPS and cellular signal degradation in connected vehicles.
- Dyed Film:Absorptive colorant layers in PET, lowest-cost option with inferior durability and heat rejection versus ceramic alternatives.
Ceramic film leads volumes today; nanotechnology refinement is expanding most quickly.
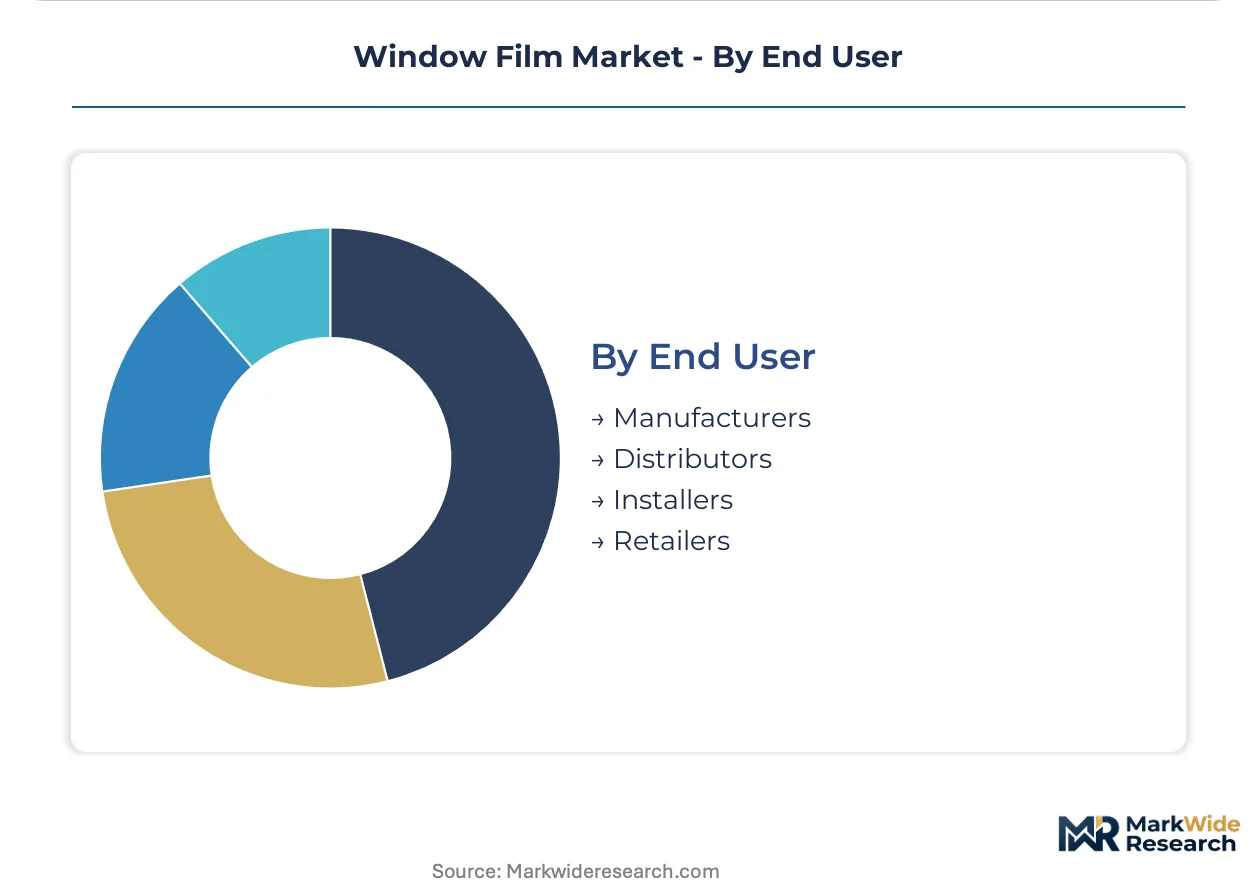
End User:
Channel position determines margin capture and technical validation burden across the value chain.
- Manufacturers:Integrated chemical majors and independent coating specialists producing master rolls for downstream conversion, differentiated by captive PET substrate supply versus toll-coating arrangements.
- Distributors:Regional and national inventory holders facing compression as direct procurement from coating specialists bypasses traditional layers in commercial retrofit channels.
- Installers:Certified applicators for automotive, architectural, and safety film segments, carrying warranty execution risk and brand reputation exposure.
- Retailers:Big-box and specialty channels for DIY residential film, constrained by installation quality variance and customer support costs.
Manufacturers lead volumes today; direct-installer relationships are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Window film manufacturing originated in the United States during the 1960s petroleum boom, when polyester substrate production and vacuum metallization techniques first converged for automotive and architectural applications.
United States
California's Title 24 building energy code mandates solar heat gain coefficient thresholds for commercial glazing retrofits, pulling specification-grade ceramic films into new construction projects. The EPA Energy Star program shapes product certification requirements and retrofit incentive eligibility across municipal procurement. Demand concentrates in Los Angeles and San Francisco commercial tower developments where facility managers negotiate direct supply relationships with coating specialists.
China
Guangzhou, Shenzhen, and Chengdu megacity construction drives bulk procurement of high-performance films for commercial facade retrofits. The Ministry of Housing and Urban-Rural Development enforces GB standards for building energy efficiency that filter market access for imported suppliers. State-owned developers in these tier-one cities centralize specification decisions and negotiate master service agreements directly with film manufacturers.
Germany
The EU Green Deal's building renovation targets shape product certification requirements and retrofit incentive eligibility across commercial retrofit channels. REACH chemical registration requirements tighten the approved substance list for UV stabilizers and adhesives used in film laminates. Industrial demand clusters in the Rhine-Ruhr metropolitan region where facility managers pursue energy performance upgrades for existing commercial stock.
Japan
METI efficiency standards for commercial buildings drive specification pathways for solar control films in Tokyo and Osaka thermal retrofits. JIS standards govern product performance testing and quality benchmarks for architectural applications. Automotive OEM glass suppliers in the Nagoya industrial corridor integrate heat-rejection films for domestic electric vehicle production.
India
BIS energy efficiency standards for existing commercial structures open specification pathways for solar control films in Mumbai and Delhi NCR thermal retrofits. The Bureau of Indian Standards administers certification protocols that determine eligibility for government building procurement. Construction activity concentrates in Maharashtra and Karnataka where commercial tower developments drive specification-grade film volumes.
Window Film Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the window film value chain. Integrated chemical majors with captive polyester substrate production sustain margin control against independent coating specialists dependent on toll-coating arrangements. Three archetypes dominate: upstream resin and substrate integrators, specialized coating and conversion houses, and automotive OEM channel specialists. Competitive moves center on ceramic nano-particle manufacturing scale-up and direct procurement relationships that bypass traditional distribution layers.
Among integrated chemical producers, Eastman Chemical Company and Saint-Gobain Performance Plastics Corporation exemplify the upstream archetype through in-house substrate supply. Johnson Window Films occupies a position within the specialized coating tier. These three anchors illustrate how supply chain position—captive resin production versus toll-coating dependence—determines margin capture and channel access across metallized, ceramic, and spectrally selective film grades.
| Leading Market Players |
|---|
| Johnson Window Films |
| Madico |
| 3M Company |
| LINTEC Corporation |
| Saint-Gobain Performance Plastics Corporation |
| Eastman Chemical Company |
| LLumar |
| Solar Gard |
| Avery Dennison Corporation |
| Others |
Supply Flow & Price Mechanics
Coating chemist concentrations in the Rhine-Ruhr metropolitan region and the Nagoya industrial corridor create labor-cost differentials that widen pricing spreads between premium ceramic grades and commodity metallized alternatives. European REACH compliance burdens and Japanese JIS certification overhead feed into tiered pricing structures that separate specification-grade from standard-performance films.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction economics in window films. Price differentiation rests on ceramic nano-particle certification grade and volume scale, with OEM automotive contracts commanding premiums over aftermarket DIY channels. Cost compression in metallized tiers is intensifying because EV manufacturers are abandoning signal-interfering formulations. Residential DIY buyers exhibit highest price sensitivity, while state-owned developers in Chinese megacities prioritize performance certification over unit cost.
Supply Chain Analysis
Skilled coating technicians cluster disproportionately in Germany, Japan, and the United States, constraining manufacturing scale-up for ceramic nano-dispersion lines. PET substrate production draws from Eastman Chemical Company's captive Tennessee operations and Saint-Gobain's European resin networks, with sputtering equipment and nano-particle feedstocks as critical dependencies. Single-source vulnerability in wide-web coating machinery strains mid-tier producers lacking capital for process engineering. Distribution runs through direct procurement relationships that bypass regional inventory holders for large-volume commercial tower projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Window film manufacturing arbitrages regulatory compliance costs between California's Title 24 enforcement and China's GB standard administration, with ceramic-grade production marginally cheaper under Asian certification timelines. Divergent test protocols between ASHRAE and ISO metrics create pricing inefficiencies that alert players can exploit.
For Market Incumbents: Deepen captive PET substrate control to defend margin position against independent coating specialists dependent on toll-coating arrangements. Expand ceramic nano-particle capacity in Tennessee and South Carolina production corridors to preempt supply constraints as EV OEMs accelerate heat-rejection film integration. Prioritize simultaneous ASHRAE and ISO certification investment to reduce multi-market qualification friction. For New Entrants and Emerging Players: Capture specification-grade solar control demand in India's Mumbai and Delhi NCR thermal retrofit corridors where BIS energy efficiency standards are newly enforced and incumbent presence remains thin. Target automotive aftermarket channels in Southeast Asian EV assembly hubs before factory-integrated ceramic films displace field-applied alternatives. Lead with 5G-transparent ceramic formulations as the go-to-market wedge against legacy metallized distributors. For Investors and Strategic Acquirers: Integrated chemical majors with backward resin control are the most active acquirer in this space, consolidating independent coating specialists to secure ceramic nano-dispersion capabilities. The five-to-ten year viability window favors targets with existing EPA Energy Star alignment and direct procurement relationships with state-owned Chinese developers. Watch for divergence between California Title 24 amendment timelines and federal IRA retrofit incentive continuity as the inflection signal for North American demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Nano-Particle Capacity Expansion | Eastman Chemical's Tennessee coating lines address EV OEM thermal management specifications for Guangzhou and Shenzhen assembly plants. |
| Dual Certification Investment | Simultaneous ASHRAE and ISO validation reduces duplicate testing costs for suppliers serving California and EU Green Deal retrofit programs. |
| Direct Procurement Channel Development | Master service agreements with Chinese state-owned developers compress distributor margins and capture specification-grade volume. |
| REACH-Compliant Adhesive Reformulation | CE marking retention for European architectural safety films depends on revalidated blast-mitigation adhesive performance windows. |
| Utility Rebate Program Alignment | EPA Energy Star certification positions coating specialists for municipal procurement and demand-side management incentives. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with coating plant managers, automotive OEM glass procurement leads, commercial facility managers, and distribution channel partners. Secondary validation draws from EPA Energy Star certification databases, Chinese Ministry of Housing GB standard filings, SEC 10-K disclosures by integrated chemical producers, and EU ECHA REACH registration records. Bottom-up volume builds from country-level construction permits and EV production forecasts, cross-checked against top-down chemical industry capacity assessments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include technology tier, application channel, and regional regulatory cluster, with ceramic nano-particle manufacturing yield curves and polyester substrate cost trajectories as industry-specific inputs. CAGRs derive from iterative reconciliation between supply-side capacity expansion schedules and demand-side code enforcement timelines.
Regulatory amendment delays, feedstock price volatility, and certification protocol divergence are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about Title 24 enforcement continuity, GB standard administration stability, and REACH substance list evolution. Material deviation in any trigger warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Watertight Doors Market