
 Red Brick Market | 2026-2036
Red Brick Market Size, Share, and Industry Trends Forecast 2026-2036
Red Brick Market Intelligence
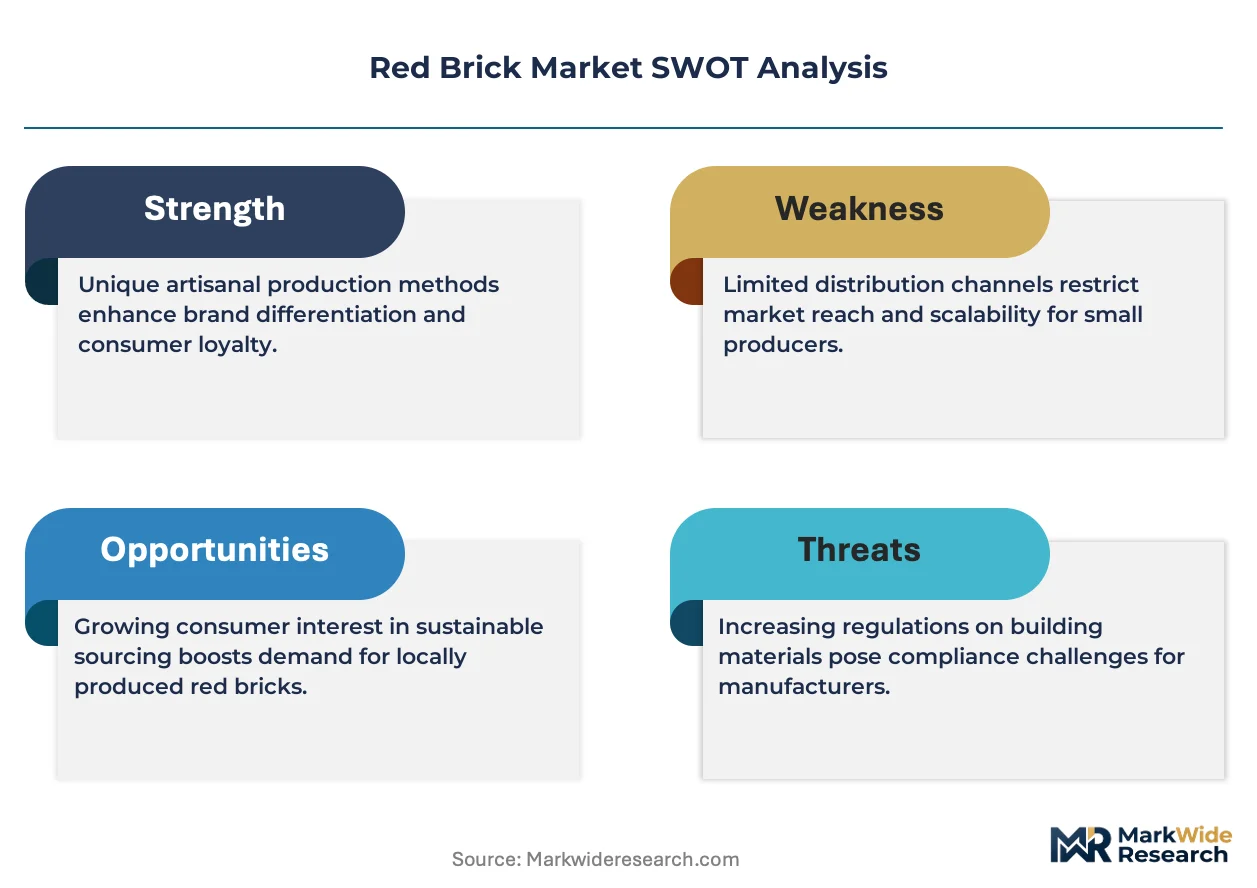
The performance distinction between architectural-grade and standard structural red bricks is hardening, driven by new building energy codes and specific aesthetic preferences in urban renewal projects. Wienerberger AG leverages its extensive portfolio to serve both premium and volume segments across key European markets. Brickworks Limited sustains its dominance in the Australian market with a focus on high-end residential and commercial facades. In North America, General Shale competes on brand reputation and specialized textures for custom homebuilders and designers.
Red brick is a ceramic building material produced from clay, shale, or other earthen materials, formed into rectangular blocks and fired in a kiln at high temperatures. Its primary function is providing structural support, durable facade cladding, and essential thermal mass in building envelopes. While traditional clay brick commands the largest market share, fly ash brick is gaining traction in regions with stringent environmental regulations on waste utilization. Residential construction represents the largest application by volume, though heritage restoration projects offer higher-margin opportunities for specialized, custom-matched products.
The European Union's CE marking mandates specific performance and safety standards for all bricks used in structural applications. Regulations from the US EPA on kiln emissions and quality specifications from India's BIS directly impact manufacturing costs and regional market access. Producers must therefore navigate the strategic trade-off between investing in lower-emission firing technologies and maintaining the material's core value proposition of long-term, maintenance-free durability.
Market Dynamics
The central dynamic in the red brick market is the conflict between its inherent durability and thermal mass properties and new building energy codes demanding higher performance insulation. This pressure forces innovation in a material traditionally valued for its consistency, pushing producers toward either enhanced performance or pure aesthetic applications.
Growth Catalysts
- Urban Renewal Projects:Demand for aesthetically specific and historically accurate bricks in urban redevelopment and gentrification zones creates high-margin opportunities for specialized producers.
- Public Housing Initiatives:Large-scale government-funded housing programs, particularly in India, specify brick for its low lifecycle cost and resilience in diverse climate conditions, driving significant volume.
- EU Green Deal:European regulations emphasizing building energy efficiency and lifecycle emissions favor materials with long service lives and good thermal mass, sustaining brick's relevance in new construction and renovation.
Market Restraints
- Energy Intensive Production:The kiln-firing process is heavily reliant on natural gas, making brick manufacturing vulnerable to energy price volatility and carbon taxation schemes, which directly impacts production costs.
- Substitution from Precast Concrete:In large-scale commercial and industrial construction, precast concrete panels offer faster installation times and design flexibility, presenting a significant substitution threat.
- Weight and Logistics Costs:As a heavy, high-volume material, red brick incurs substantial transportation costs, limiting the economic radius from a production plant and creating regionalized market structures.
Strategic Opportunities
- Insulated Brick Systems:Developing bricks with integrated insulation cavities or marketing composite wall systems that combine brick with high-performance insulation panels opens new specification pathways in energy-efficient construction.
- Waste Material Valorization:Incorporating industrial byproducts like fly ash or construction demolition waste into brick composition can lower raw material costs and appeal to green building certification programs.
- Digital Specification Tools:Offering digital libraries of brick textures, colors, and bond patterns for use in Building Information Modeling (BIM) software can embed a manufacturer's products early in the architectural design process.
Industry Challenges
- Modernization Capex:Upgrading traditional kilns to meet stricter emissions standards, such as those from the US EPA, requires significant capital investment that can be prohibitive for smaller, family-owned producers.
- Skilled Labor Scarcity:A declining number of trained masons in many developed economies presents a bottleneck, as poor installation can compromise the performance and aesthetic of even premium brick products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Brick Market |
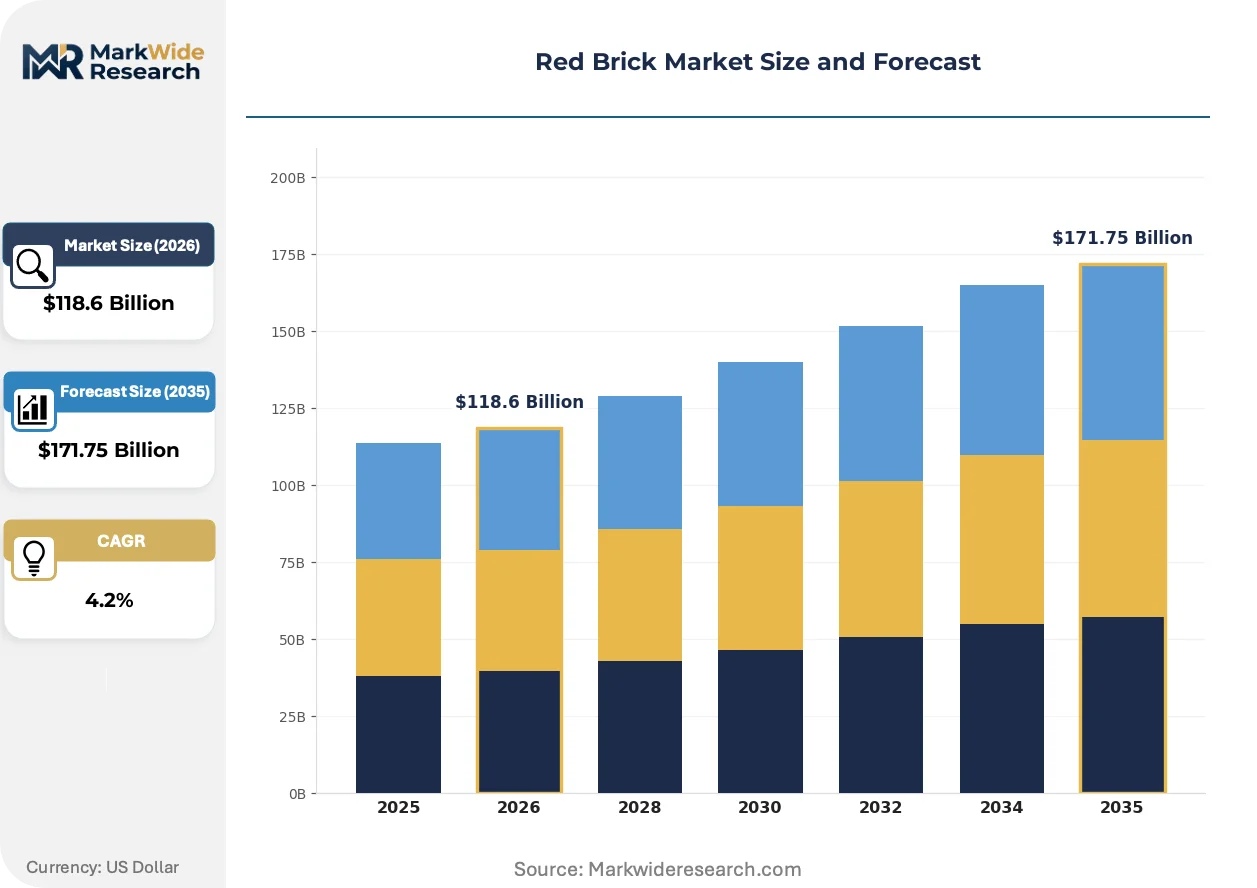
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $171.75 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Brick, Fly Ash Brick, Concrete Brick, Calcium Silicate Brick, Eco Brick Application: Residential Construction, Commercial Buildings, Landscaping, Boundary Walls, Heritage Restoration Manufacturing Process: Extrusion, Molding, Pressing, Firing, Dry Pressing End User: Construction Contractors, Real Estate Developers, Masonry Specialists, Infrastructure Firms, Renovation Companies |
| Companies Covered | Wienerberger AG, General Shale, Belden Brick, Brickworks Limited, Forterra Inc., Redland Brick, Boral Limited, El-Khayyat Group, PGH Bricks & Pavers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Brick Market Strategic Shifts & Innovations
Innovation in the red brick industry is driven by the need to align a traditional material with modern performance demands. This involves advancements in material composition, regulatory compliance strategies, and a fundamental shift in how architects specify and procure facade materials for complex projects.
Thin brick veneer systems are a key product evolution, offering the aesthetic of full-bed brick without the structural weight. These systems are rapidly being adopted by developers for retrofitting existing buildings and for new multi-story wood or steel-framed construction. This lightweight cladding technology is converging with modular construction methods, allowing for the creation of large, prefabricated facade panels in a factory setting for faster on-site assembly.
Regulatory frameworks like India's Bureau of Indian Standards (BIS) specifications for clay building bricks are formalizing quality requirements across the market. These standards impose minimums for compressive strength and maximums for water absorption, directly influencing manufacturing process control. This affects the vast number of unorganized, small-scale producers in the region, forcing investment in better clay preparation and firing technology to remain compliant.
Aesthetic customization is altering specification patterns away from commodity orders. Architects are increasingly demanding unique colors, non-standard sizes, and specialized textures to create signature building facades, particularly in the high-end residential and commercial sectors. This displaces bulk procurement through general distributors with a more collaborative, design-led selection process directly involving manufacturers. This shift is most visible in North American and European metropolitan centers undergoing architectural revitalization.
Red Brick Market Segmentation
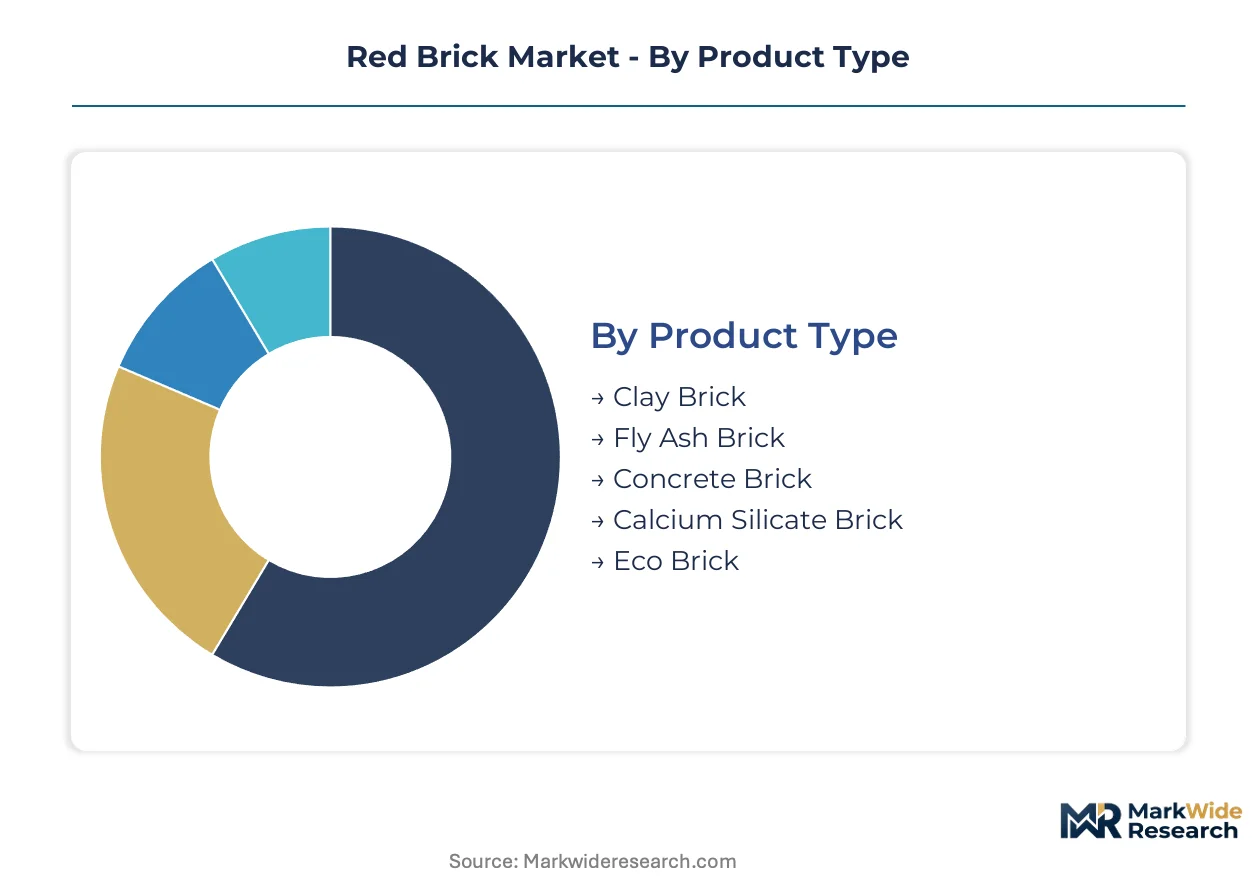
Understanding the red brick market through distinct segments reveals how material properties, application demands, and manufacturing processes influence procurement and strategic positioning. This granular view highlights where innovation and investment are most critical for producers.
Product Type:
Material properties and performance drive product type selection for red bricks, aligning with specific structural and aesthetic requirements across diverse projects.
- Clay Brick:This traditional ceramic building material is produced from natural clay and shale, fired at high temperatures to achieve strength and durability. Residential construction in India and Europe drives significant volume due to its long service life and thermal mass properties.
- Fly Ash Brick:Composed primarily of industrial waste fly ash, this brick type offers environmental benefits through waste valorization and often boasts consistent dimensions. Regions with stringent environmental regulations, such as parts of India, are seeing increased demand for sustainable building materials.
- Concrete Brick:Manufactured from cement, aggregates, and water, concrete bricks offer versatility in shape and color, often without a firing process.
- Calcium Silicate Brick:These bricks are made from lime, sand, and water, then autoclaved under high pressure steam to achieve high compressive strength.
- Eco Brick:Incorporating recycled materials or alternative binders, eco bricks focus on reducing environmental impact and embodied carbon.
Volume sits with Clay Brick; growth tilts toward Fly Ash Brick.
Application:
The intended use case for red bricks dictates specific material and aesthetic requirements, influencing product development and market focus for manufacturers.
- Residential Construction:This segment represents the primary application for red bricks, providing structural support, facade cladding, and thermal mass for single-family and multi-unit dwellings. Global housing initiatives, particularly in India, rely on brick for its low lifecycle cost and resilience.
- Heritage Restoration:This high-margin niche demands custom-matched products in terms of color, texture, and size to maintain historical accuracy and aesthetic integrity. Urban renewal projects in European metropolitan centers frequently specify specialized bricks for these sensitive applications.
- Commercial Buildings:Red bricks are utilized for facade cladding, interior features, and structural elements in offices, retail spaces, and institutional structures.
- Landscaping:This application includes pavers, garden walls, and decorative elements, where durability and aesthetic appeal in outdoor environments are key.
- Boundary Walls:Bricks provide security, privacy, and property demarcation, valued for their robustness and minimal maintenance.
The largest volume demand stems from Residential Construction, while Heritage Restoration presents the steepest expansion trajectory.
Manufacturing Process:
The production methodology profoundly impacts brick properties, cost, and environmental footprint, driving continuous investment in technology and operational efficiency.
- Extrusion:This highly automated process pushes prepared clay through a die to create uniform, dense bricks, suitable for high-volume production of standard structural units. Efficiency gains in extrusion lines directly reduce per-unit manufacturing costs.
- Firing:This critical step involves heating green bricks in kilns at high temperatures to achieve their final ceramic properties, hardness, and durability. Compliance with emissions standards from regulators like the US EPA necessitates significant capital investment in advanced kiln technologies.
- Molding:Traditional molding techniques, including hand-forming, produce bricks with unique textures and irregular shapes, often favored for specialized aesthetic projects.
- Pressing:This method uses high pressure to form bricks from semi-dry clay, resulting in precise dimensions and high density, often used for engineering bricks.
- Dry Pressing:A process for low-moisture clay mixes, dry pressing minimizes shrinkage and is suitable for certain raw material compositions.
Process optimization efforts primarily focus on Firing, with evolving technologies influencing Extrusion.
End User:
Procurement channels and specification requirements vary significantly across different red brick purchasers, influencing sales strategies and product offerings.
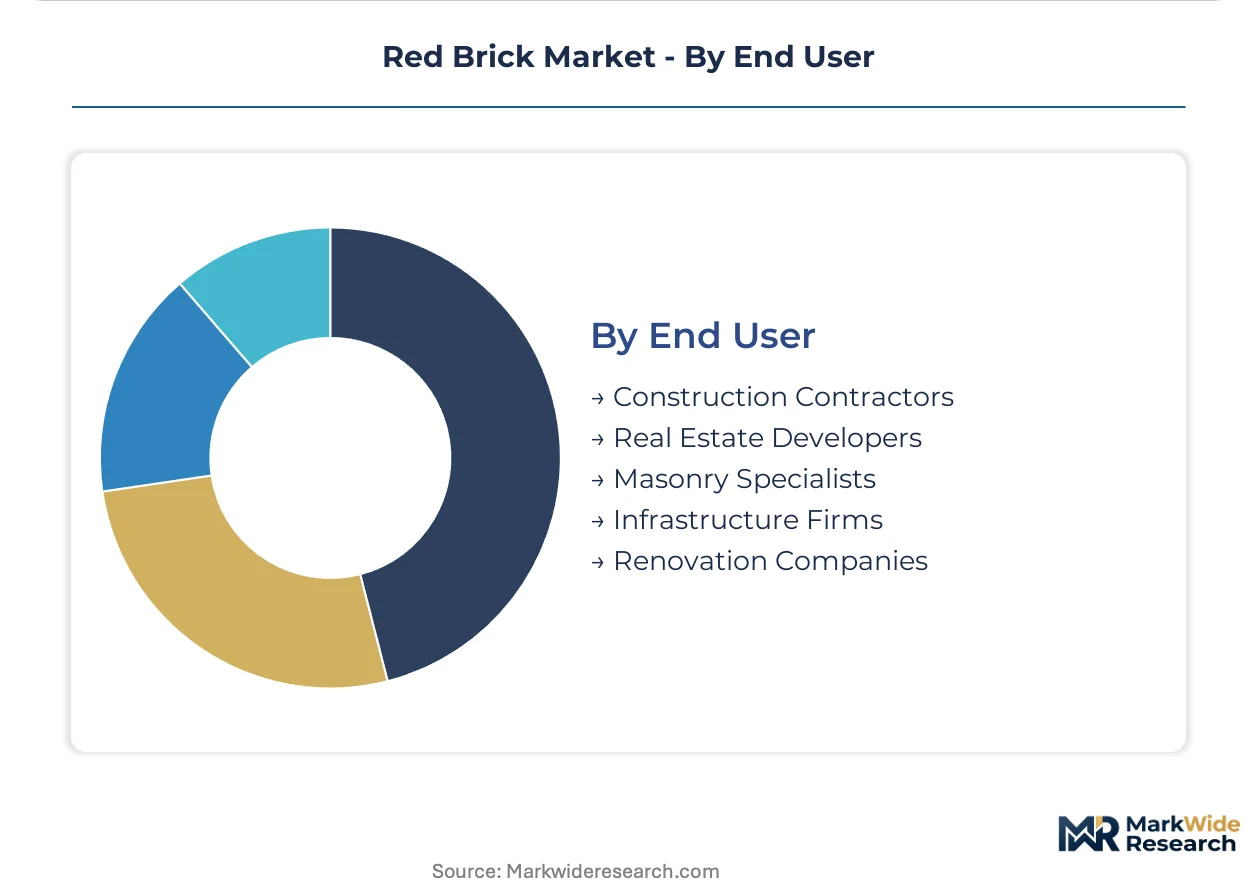
- Construction Contractors:These entities are direct purchasers for project execution, requiring reliable supply, competitive pricing, and adherence to project timelines for structural and facade applications. Their volume orders form the backbone of market demand.
- Real Estate Developers:As key specifiers for large-scale projects, developers influence material selection based on aesthetic vision, cost-effectiveness, and long-term property value. New housing developments and commercial complexes represent significant opportunities.
- Masonry Specialists:These skilled professionals are crucial for quality installation, often influencing product choice based on workability and aesthetic outcomes.
- Infrastructure Firms:Involved in large public works, these firms require bricks that meet specific technical specifications for durability and structural integrity.
- Renovation Companies:Focused on upgrading existing structures, these companies often seek custom-matched or specialized bricks for seamless integration.
Major purchasing power rests with Construction Contractors, while specialized demand is driven by Renovation Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's extensive urban development projects and infrastructure initiatives heavily influence the red brick market. These large-scale construction efforts demand significant volumes of durable building materials. This concentrated activity drives both traditional brick production and innovative material adoption across the region.
India
India's public housing initiatives create substantial demand for red bricks, valuing their low lifecycle cost. The Bureau of Indian Standards (BIS) mandates quality specifications for clay building bricks, influencing manufacturing processes. Construction in Delhi and Bangalore sees high volume procurement for both residential and commercial projects.
Germany
Germany's stringent energy codes and aesthetic preferences drive demand for high-performance red bricks. The EU Green Deal promotes materials with long service lives and good thermal mass, benefiting brick manufacturers. Producers in North Rhine-Westphalia focus on advanced firing technologies to meet emissions standards.
United States
United States custom homebuilders and designers seek specialized textures and brand reputation in red brick products. Environmental Protection Agency (EPA) regulations on kiln emissions impact production costs for brick manufacturers. The Southeast region, particularly in Texas and Florida, experiences consistent residential construction activity.
Australia
Australia's high-end residential and commercial facade sectors sustain strong demand for premium red bricks. Building codes emphasize durability and aesthetic quality for long-term structural integrity. Companies in New South Wales invest in product innovation for specialized architectural applications.
United Kingdom
United Kingdom urban renewal projects require historically accurate and aesthetically specific bricks. The country's building regulations prioritize energy efficiency and material longevity in new construction. London and other metropolitan centers drive demand for custom-matched products in heritage restoration.
Red Brick Market Key Industry Players
Premium-margin players sit above commodity-margin players across product differentiation and market reach. The red brick market exhibits a tiered structure, with specialized producers catering to high-value niches and large-scale manufacturers serving volume segments. Strategic archetypes include global diversified material suppliers, regional specialists, and niche aesthetic providers. Companies engage in portfolio diversification and geographic expansion to solidify their market positions.
Within the global diversified material suppliers archetype, Wienerberger AG exemplifies a broad portfolio across key European markets, serving both premium and volume segments. Australian-based Brickworks Limited anchors the high-end residential and commercial facade segments in its home region, maintaining market dominance with a focus on quality. General Shale, with its strong brand reputation and specialized textures, represents a key player for custom homebuilders and designers in North America. These firms collectively demonstrate how leading entities navigate varied regional demands, aesthetic preferences, and regulatory landscapes through strategic product offerings.
| Leading Market Players |
|---|
| Wienerberger AG |
| General Shale |
| Belden Brick |
| Brickworks Limited |
| Forterra Inc. |
| Redland Brick |
| Boral Limited |
| El-Khayyat Group |
| PGH Bricks & Pavers |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material sourcing anchors both the red brick market's supply position and its pricing power, particularly for large manufacturers controlling clay and shale deposits.
Pricing Analysis
Project-based pricing, tied to the specific aesthetic and performance outcomes required for building envelopes, drives premium red brick sales. Quality grade and brand reputation differentiate pricing, with specialized textures commanding higher margins in urban renewal projects. Pricing softness stems from commodity brick segments, where competition from precast concrete and regional oversupply creates downward pressure. Construction contractors exhibit the highest price sensitivity for standard structural bricks, while heritage restoration projects are least sensitive due to unique specification demands.
Supply Chain Analysis
Logistics and freight costs significantly influence red brick supply chains, limiting economic radii from production plants and fostering regionalized market structures. Supply concentration draws from India, China, and parts of Europe for raw clay and shale. Key raw material dependencies include specific clay types and natural gas for kiln firing. Commodity price volatility for natural gas presents a structural supply chain risk for producers. Downstream distribution runs primarily through regional building material distributors and direct sales to large construction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players pursuing upstream control over raw materials and downstream engagement with architectural specification tools to secure value.
For Market Incumbents: Deepen proprietary clay and shale reserves through strategic land acquisitions, securing long-term raw material supply against future environmental restrictions. Invest in advanced kiln technologies to reduce energy consumption and meet stricter emissions standards from regulators like the US EPA, mitigating carbon taxation threats. Control distribution channels more directly, especially for specialized products, to counter substitution from precast concrete. Expand digital specification libraries for Building Information Modeling (BIM) software, embedding products early in the design process.
For New Entrants and Emerging Players: Architectural design firms represent a critical channel partner for new entrants. Focus on niche product differentiation, such as eco-bricks incorporating waste materials, targeting green building certification programs. The most penetrable segment is specialized facade cladding for multi-story residential construction, offering aesthetic flexibility. A go-to-market angle involves direct collaboration with architects and developers on custom-matched products for specific urban renewal projects, bypassing traditional bulk distributors.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated mid-cap specialists with strong regional market shares and proprietary raw material access. Long-term viability (5-10 years) favors companies investing in both sustainability and aesthetic customization capabilities. An acquisition target archetype involves firms with established brands in high-margin segments like heritage restoration or insulated brick systems. The signal to watch is the consistent adoption rate of insulated brick systems in new construction across European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Clay & Shale Reserves | Secures long-term raw material supply and buffers against input price volatility for brick manufacturers. |
| Invest in Low-Emission Kilns | Ensures compliance with US EPA and EU Green Deal regulations, reducing operational costs and carbon footprint. |
| Develop Insulated Brick Systems | Addresses new building energy codes and expands market opportunities in energy-efficient construction. |
| Expand Digital Specification Tools | Embeds manufacturer products early in architectural design workflows, influencing material selection. |
| Target Heritage Restoration Niche | Captures high-margin opportunities for specialized, custom-matched products in urban revitalization projects. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and primary interviews underwrites the qualitative findings and quantitative projections. This analysis combines insights from plant managers, procurement leads at construction contractors, architectural designers, and sustainability officers. Secondary data sources include the Bureau of Indian Standards (BIS) specifications, US EPA emissions data, and EU Green Deal policy documents, triangulated with company annual reports.
The comparable-period framing anchored the forecast window to historical market performance and technological adoption rates across the analysis window. Segmentation dimensions modeled included product type, application, manufacturing process, and end user, alongside regional regulatory impacts. Compound annual growth rates were derived through a regression analysis of historical data and projected market drivers. Industry-specific forecast inputs included projected residential construction starts and energy price forecasts.
Caveats apply where shifts in global energy prices or unexpected regulatory changes could materially shift the outlook for red brick production costs. Forecasts reflect assumptions documented regarding construction activity and material preferences. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Tower Bolt Market