
 North America Hydrogen Compressor Market | 2026-2036
North America Hydrogen Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrogen Compressor Market Analytics
The US Inflation Reduction Act hydrogen production tax credits is shifting capital allocation toward domestic compressor manufacturing and electrolyzer integration. Atlas Copco Group leverages its oil-free compression technology leadership to anchor European-origin supply into North American hydrogen hubs. Ingersoll Rand Inc sustains a broad aftermarket service network that dominates maintenance contracts across existing refinery hydrogen circuits. Ariel Corporation specializes in high-pressure reciprocating frames purpose-built for the pressure demands of tube trailer and station dispensing applications.
A hydrogen compressor is a mechanical device that raises hydrogen gas pressure from atmospheric or process levels to storage, transport, or dispensing pressures, typically spanning 350 to 700 bar for mobility applications and 20 to 100 bar for industrial pipeline feed. These machines employ specialized sealing systems, non-lubricated cylinders, and corrosion-resistant metallurgies to prevent hydrogen embrittlement and ensure purity compliance for fuel cell applications. Diaphragm compressors command premium positioning in high-purity fuel cell supply chains where oil contamination risks are unacceptable. Positive displacement technology occupies the bulk of installed capacity across hydrogen production and oil refinery settings where flow rates and pressure ratios favor reciprocating or screw architectures.
The US Department of Energy hydrogen and fuel cell program coordinates with EPA emissions frameworks and DOT pipeline safety standards to define compressor performance benchmarks and station certification protocols. Canada's Natural Resources Canada and the Canadian Standards Association administer parallel hydrogen equipment codes that shape cross-border equipment qualification requirements. Stakeholders must monitor how evolving OSHA process safety management interpretations apply to high-pressure hydrogen compression facilities as deployment scales beyond pilot installations.
Market Dynamics
US Inflation Reduction Act hydrogen production tax credits are redirecting capital flows toward domestic electrolyzer-compressor integration, compressing procurement timelines and reshaping supplier qualification criteria across the value chain.
Growth Catalysts
- Refueling Infrastructure Deployment:California's transport hub corridor and the US Gulf Coast industrial cluster are driving concentrated demand for high-pressure dispensing systems. Station buildout mandates in Texas and the northeastern corridor accelerate compressor procurement cycles.
- Domestic Manufacturing Incentives:IRA tax credits are shifting fabrication capacity toward US-based electrolyzer and compressor production. Equipment localization reduces lead times and import dependency for critical hydrogen infrastructure.
- Fuel Cell Mobility Expansion:Heavy-duty trucking fleets and municipal bus operators are adopting 700-bar tube trailer supply chains. This pressure tier demands specialized reciprocating and diaphragm compressor architectures.
Market Restraints
- Specialized Metallurgy Costs:Hydrogen embrittlement-resistant alloys and non-lubricated cylinder coatings command premium input pricing. Material scarcity constrains production scaling for high-purity fuel cell-grade compressors.
- European Supply Concentration:Oil-free compression technology leadership remains concentrated among European-origin suppliers. Transatlantic logistics and qualification timelines extend project delivery schedules.
- DOT Pipeline Safety Standards:Evolving high-pressure hydrogen transport regulations create certification friction for new equipment entrants. Compliance timelines delay station commissioning and revenue recognition.
Strategic Opportunities
- Canadian Hydrogen Corridor Development:Natural Resources Canada funding streams and CSA equipment codes are stimulating cross-border hub development. Alberta's industrial hydrogen production and Ontario's transport corridors represent underpenetrated deployment zones.
- Aftermarket Service Unbundling:Refinery hydrogen circuit operators are separating maintenance contracts from original equipment procurement. Independent service providers can capture recurring revenue streams previously locked to OEM relationships.
- Electrolyzer-Compressor Integration:Green hydrogen production facilities are specifying packaged compression systems upstream of storage. Technology convergence between alkaline/PEM electrolysis and high-pressure compression reduces balance-of-plant complexity.
Industry Challenges
- High-Pressure Systems Engineering Talent:Specialized expertise in 350-700 bar sealing systems and hydrogen-compatible metallurgy remains scarce. Workforce development lags deployment timelines across California, Texas, and Gulf Coast hubs.
- OSHA Process Safety Management Interpretation:Evolving regulatory guidance on high-pressure hydrogen facility classification creates compliance uncertainty. Operators face recertification risk as deployment scales beyond pilot installations.
- Legacy Refinery Integration:Existing 20-100 bar industrial hydrogen circuits require pressure upgrade or parallel infrastructure for fuel cell supply. Retrofit complexity extends project timelines and capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrogen Compressor Market |
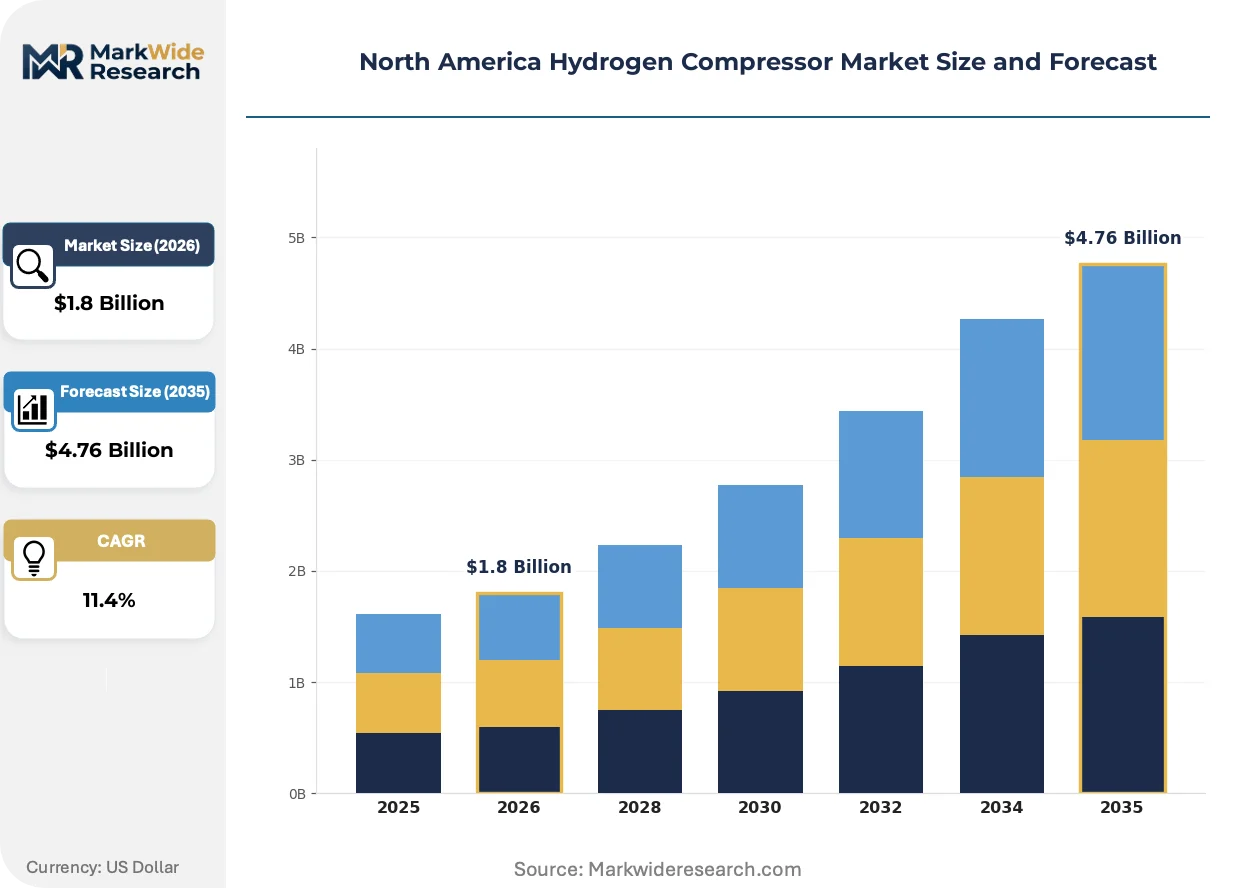
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Compressors, Reciprocating Compressors, Rotary Compressors, Screw Compressors End User: Fuel Cell Manufacturers, Chemical Plants, Oil Refineries, Industrial Gas Companies Application: Hydrogen Refueling Stations, Hydrogen Production, Power Generation, Storage Solutions Technology: Centrifugal Technology, Positive Displacement Technology, Electrochemical Technology, Cryogenic Technology |
| Companies Covered | Atlas Copco Group, Haug Kompressoren AG, Ingersoll Rand Inc, Hydro-Pac Inc, Corken Inc, Ariel Corporation, Sundyne Corp, Howden Group Ltd, Burckhardt Compression AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrogen Compressor Market Evolving Landscape
Intelligent compression systems and predictive maintenance architectures are displacing conventional mechanical-only designs, while regulatory pressure on hydrogen purity and safety accelerates equipment specification changes across North American deployment zones.
AI-driven condition monitoring is automating fault detection in high-pressure reciprocating compressor frames. Fleet operators in California's heavy-duty trucking corridors are deploying sensor-integrated units to minimize unplanned downtime. This capability is automating maintenance scheduling and compressing total cost of ownership calculations for station investors.
EPA emissions frameworks are tightening hydrogen purity requirements for fuel cell applications. The agency's coordination with DOT pipeline safety standards is elevating certification thresholds for compressor sealing integrity. California Air Resources Board implementation timelines are forcing equipment suppliers to accelerate oil-free technology validation.
Buying committees at municipal transit authorities are consolidating procurement decisions at state and regional levels. Previously fragmented station operator purchases are centralizing through California hydrogen hub consortia and Texas clean hydrogen alliance structures. This concentration is visible most acutely in competitive bidding for 700-bar dispensing infrastructure across the I-5 and I-10 corridors.
North America Hydrogen Compressor Market Segmentation
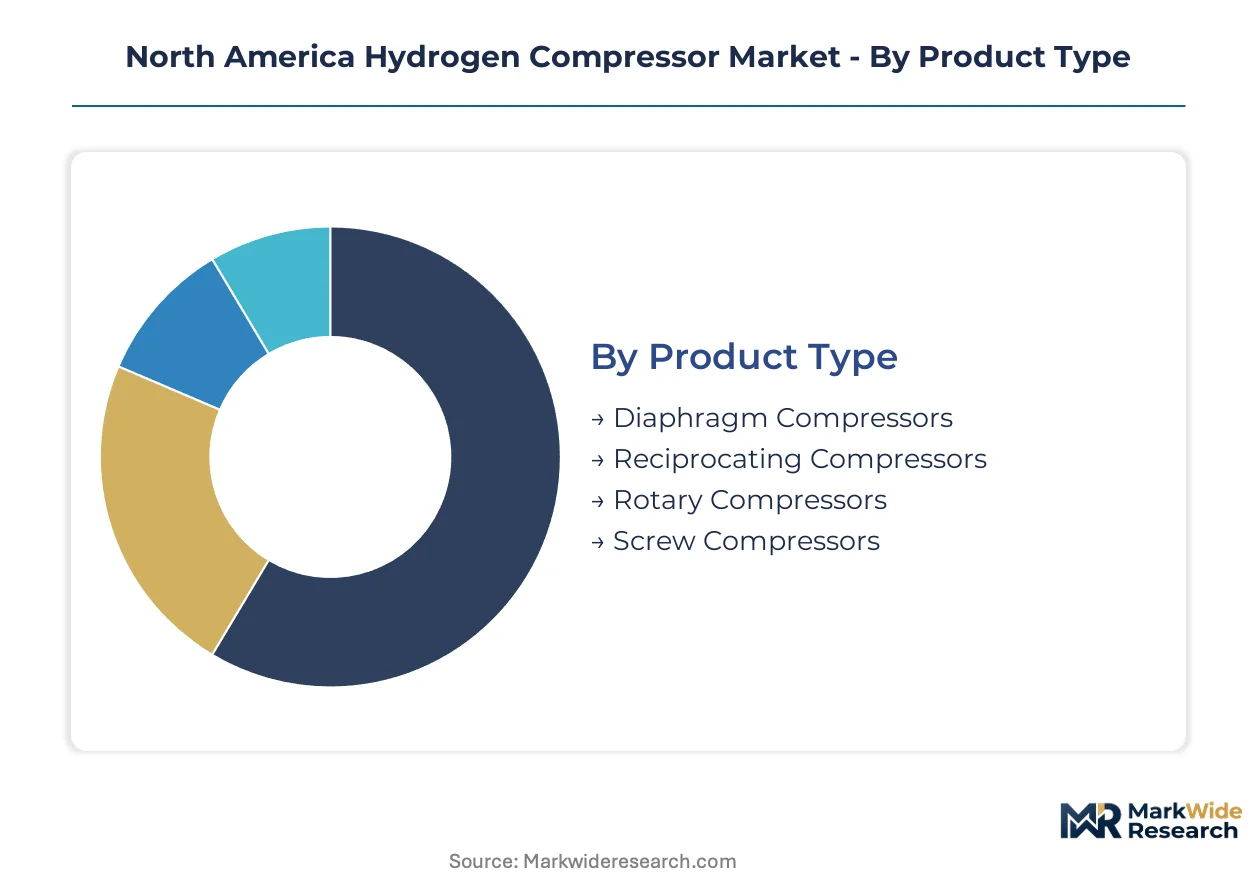
Compressor architecture and deployment context determine equipment specification, metallurgy requirements, and aftermarket service intensity across North American hydrogen infrastructure. Segmentation reveals how pressure tier, purity grade, and integration complexity fragment procurement patterns between industrial hydrogen circuits and fuel cell supply chains.
Product Type:
Equipment replacement cycles and pressure upgrade trajectories vary dramatically by compression mechanism, with oil-free architectures commanding premium positioning in transport applications.
- Reciprocating Compressors:High-pressure frames with non-lubricated cylinders and hydrogen-resistant alloys dominate 350-700 bar dispensing applications. Demand concentrates in California's heavy-duty trucking corridors and Texas hydrogen hub deployments where station throughput requirements favor positive displacement reliability.
- Diaphragm Compressors:Metal diaphragm isolation ensures absolute oil-free delivery for PEM fuel cell supply chains. California Air Resources Board purity mandates and EPA emissions frameworks are elevating specification priority for this architecture in municipal bus and fleet refueling infrastructure.
- Screw Compressors:Oil-injected rotary designs serve 20-100 bar industrial hydrogen circuits with lower purity tolerance.
- Rotary Compressors:Vane and lobe configurations handle intermediate pressure boosting in production facility balance-of-plant.
Reciprocating compressors sit at the top of the volume ranking, with diaphragm compressors climbing the fastest.
End User:
Customer procurement sophistication and lifecycle cost calculation methods diverge sharply between process industry incumbents and emerging mobility infrastructure operators.
- Oil Refineries:Established 20-100 bar hydrogen circuits for hydrocracking and desulfurization require pressure upgrades or parallel high-purity systems. US Gulf Coast cluster operators are retrofitting legacy infrastructure to serve emerging fuel cell demand while maintaining refinery process supply.
- Fuel Cell Manufacturers:PEM and SOFC stack producers specify compressor-integrated test stands and production line gas handling. California's transport hub corridor and Ontario's emerging fuel cell manufacturing base are driving demand for ultra-high-purity compression systems.
- Industrial Gas Companies:Merchant hydrogen suppliers manage distributed production and tube trailer logistics across multiple pressure tiers.
- Chemical Plants:Ammonia and methanol producers consume hydrogen at pipeline pressure with tolerance for lubricated compression.
Oil refineries anchor current installed base value, though fuel cell manufacturers are expanding most quickly.
Application:
Deployment setting dictates pressure specification, duty cycle, and regulatory compliance burden across the hydrogen value chain.
- Hydrogen Refueling Stations:700-bar dispensing systems for heavy-duty trucking and passenger vehicles demand specialized high-pressure architectures. California's I-5 corridor and Texas clean hydrogen alliance are concentrating procurement for 350-700 bar cascade storage and direct dispensing configurations.
- Hydrogen Production:Electrolyzer-integrated compression packages upstream of storage are standardizing across green hydrogen facilities. US Inflation Reduction Act tax credits are compressing procurement timelines for alkaline and PEM production sites in Texas and the US Gulf Coast.
- Storage Solutions:Geological and vessel storage injection requires intermediate pressure boosting with variable flow turndown.
- Power Generation:Turbine fuel supply and fuel cell power plants utilize lower-pressure pipeline feed compression.
Hydrogen production applications hold the largest current deployment volume, with refueling stations gaining share fastest.
Technology:
Fundamental compression physics and energy efficiency tradeoffs segment supplier capability and equipment qualification pathways.
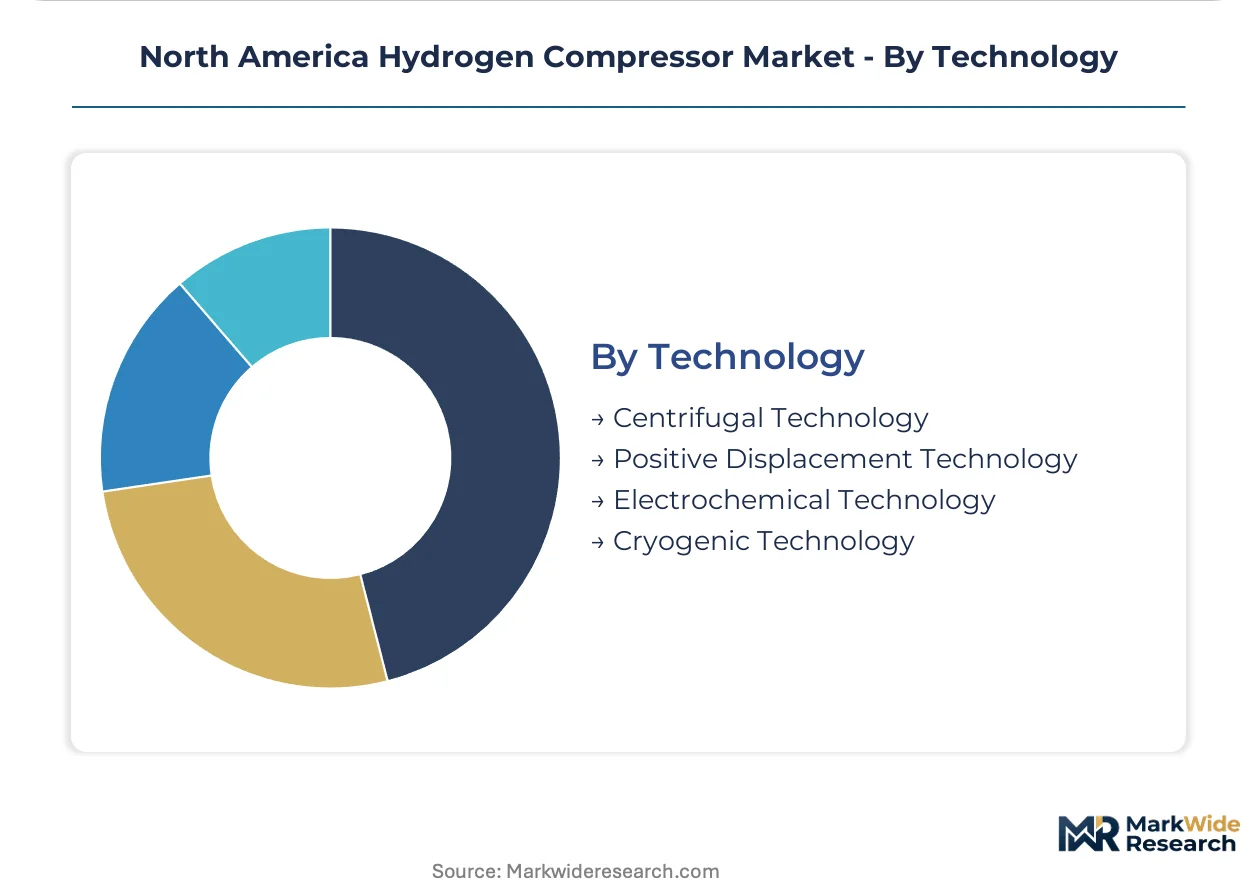
- Positive Displacement Technology:Reciprocating, screw, and vane mechanisms capture the majority of installed capacity across North American hydrogen infrastructure. The technology's pressure ratio flexibility suits both 20-100 bar industrial circuits and 350-700 bar mobility applications with appropriate metallurgical specification.
- Centrifugal Technology:Dynamic compression achieves highest flow rates at lower pressure ratios for pipeline transmission and large-scale production facilities. US Gulf Coast industrial clusters and Alberta hydrogen export corridors are evaluating centrifugal stages for 50-100 bar pipeline injection.
- Cryogenic Technology:Liquid hydrogen pumping achieves density advantages for long-distance transport and aerospace applications.
- Electrochemical Technology:Emerging solid-state compression approaches eliminate mechanical moving parts in research-phase deployments.
Positive displacement technology dominates current deployment, while centrifugal technology is expanding most quickly into pipeline-scale applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American hydrogen compressor industry traces its operational lineage to the US Gulf Coast petrochemical corridor, where refinery hydrogen circuits established the foundational demand for high-pressure compression equipment during the mid-20th century.
United States
California's heavy-duty trucking corridors and Texas clean hydrogen hubs are driving concentrated procurement for 700-bar dispensing systems. The US Inflation Reduction Act production tax credits are compressing procurement timelines for electrolyzer-integrated compression packages. Station buildout mandates across the I-5 and I-10 corridors are accelerating deployment of high-pressure reciprocating and diaphragm architectures.
Canada
Alberta's industrial hydrogen production facilities and Ontario's emerging transport corridors represent underpenetrated deployment zones for compression infrastructure. Natural Resources Canada funding streams and Canadian Standards Association equipment codes are stimulating cross-border hub development with US markets. British Columbia's hydrogen export initiatives and Quebec's electrolyzer manufacturing base are creating demand for intermediate-pressure boosting systems.
Mexico
Northern border states are positioning industrial clusters to serve cross-border hydrogen logistics between US Gulf Coast production and Mexican manufacturing demand. The country's national energy regulator is developing hydrogen pipeline safety standards aligned with US DOT frameworks. Monterrey's industrial corridor and Baja California's manufacturing zones are evaluating compression infrastructure for fuel cell forklift and port equipment applications.
North America Hydrogen Compressor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American hydrogen compressor landscape. The market structure consolidates around European-origin technology leaders with established oil-free compression expertise and domestic specialists with deep aftermarket service networks. Three strategic archetypes dominate: integrated industrial conglomerates with multi-technology portfolios, pure-play hydrogen compression specialists, and regional fabricators serving refinery retrofit markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves as IRA-driven demand compresses equipment delivery timelines.
Among European-origin technology providers, Atlas Copco Group and Burckhardt Compression AG occupy positions exemplifying oil-free compression leadership for fuel cell-grade hydrogen supply chains. Domestic specialists including Ariel Corporation and Hydro-Pac Inc represent the high-pressure reciprocating archetype purpose-built for tube trailer and station dispensing applications. Ingersoll Rand Inc anchors the integrated industrial tier with extensive aftermarket service infrastructure across existing refinery hydrogen circuits.
| Leading Market Players |
|---|
| Atlas Copco Group |
| Haug Kompressoren AG |
| Ingersoll Rand Inc |
| Hydro-Pac Inc |
| Corken Inc |
| Ariel Corporation |
| Sundyne Corp |
| Howden Group Ltd |
| Burckhardt Compression AG |
| Others |
Value Network & Pricing Analysis
Hydrogen embrittlement-resistant alloy costs cascade through three distinct equipment tiers, with nickel-based superalloy pricing from US and German specialty mills determining the floor for 700-bar fuel cell-grade compressor systems. California Air Resources Board certification requirements and EPA purity mandates amplify this input cost structure, compressing margins for standard-grade industrial units while premium diaphragm architectures capture value from municipal transit authorities and heavy-duty fleet operators.
Pricing Analysis
Project-based equipment procurement with modular add-on structures dominates the North American landscape, separating oil-free certified systems from lubricated industrial units from economy-grade retrofit packages. Price differentiation rests on CARB certification tier and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because IRA-driven demand is pulling European-origin supply into constrained domestic fabrication capacity. Municipal transit authorities exhibit highest price sensitivity due to grant-dependent capital cycles, while US Gulf Coast refinery operators prioritize lifecycle reliability over upfront equipment cost.
Supply Chain Analysis
Refurbishment flows for high-pressure reciprocating frames create secondary supply channels, with Ariel Corporation and domestic service networks remanufacturing cylinder packs and valve assemblies for cost-conscious station operators. Manufacturing concentration in Germany, Switzerland, and the United States shapes equipment availability, with specialized sealing technology drawing from Japanese precision component suppliers and Italian forging houses. Single-source vulnerability in oil-free diaphragm technology creates procurement risk for California hub deployments. Distribution runs through OEM-direct project sales for large installations and regional distributor networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fuel cell-grade specifications displace legacy refinery-grade equipment across California and Texas deployment corridors. The shift toward 700-bar dispensing infrastructure elevates certification-hardened suppliers over commodity fabricators.
For Market Incumbents: Cement aftermarket service lock-in through predictive maintenance platform deployment across California's I-5 corridor refueling networks. European-origin technology leaders face margin pressure from domestic fabrication incentives; backward integration into US-based alloy machining capacity defends position against tariff exposure and logistics friction.
For New Entrants and Emerging Players: AI-driven condition monitoring systems offer technology-first entry into fragmented municipal bus procurement committees previously captive to incumbent OEM relationships. Underpenetrated Canadian hydrogen corridors and Texas industrial cluster retrofits represent the most penetrable white-space targets. Go-to-market execution should anchor on electrolyzer-integrated compression package partnerships with green hydrogen developers.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized high-pressure engineering talent scarcity constrains scaling beyond pilot installations. Long-term viability favors vertically integrated specialists with captive metallurgy expertise and certified service infrastructure. The signal to watch is CARB certification timeline acceleration for oil-free architectures, which would compress qualification windows and favor incumbent technology holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Compressor Integration | Packaged green hydrogen production systems reduce balance-of-plant complexity for IRA-funded Texas projects. |
| Predictive Maintenance Platform Deployment | AI-driven condition monitoring minimizes unplanned downtime for California heavy-duty trucking station operators. |
| Domestic Alloy Machining Capacity Addition | US-based fabrication reduces lead times and import dependency for critical hydrogen infrastructure components. |
| CARB Certification Fast-Track Investment | Accelerated oil-free technology validation captures municipal transit authority procurement centralization. |
| Canadian Corridor Partnership Structure | Cross-border hub development with Alberta production and Ontario transport networks diversifies geographic exposure. |
Research Methodology
Bottom-up refueling station and production facility modeling reconciled against top-down compressor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with station engineering directors, electrolyzer project developers, refinery maintenance managers, and aftermarket service heads were validated against secondary sources including EIA hydrogen infrastructure databases, DOT pipeline safety filings, CARB equipment certification records, and SEC disclosures from listed industrial conglomerates. Triangulation between demand-side deployment timelines and supply-side capacity expansion plans ensures cross-verified volume estimates.
Input-output matrices map hydrogen flow requirements by pressure tier, purity specification, and duty cycle across the projection horizon. Segmentation dimensions modeled include compressor architecture, end-use industry, application setting, and technology type, with regional regulatory framework as an additional cross-cutting variable. CAGRs were derived from equipment replacement cycle analysis and green hydrogen production facility commissioning schedules. Key forecast inputs include IRA tax credit allocation trajectories and CARB implementation timeline assumptions.
The model holds under sustained IRA incentive continuity and CARB mandate enforcement; deviation in federal policy support or OSHA process safety management reclassification would shift deployment velocity and equipment specification priorities. Practitioners should monitor DOT pipeline safety standard evolution and European supply chain disruption indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Compressor Oil Market
Compressors
North America Air Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Compressor Wheel Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Tandem Piston Compressors Market
Compressors
Centrifugal Compressors Market
Compressors
Gas Compressors Market
Compressors
Axial Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market