
 Positive-Displacement Hydrogen Compressor Market | 2026-2036
Positive-Displacement Hydrogen Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Positive-Displacement Hydrogen Compressor Market Insights
Single-source procurement for high-pressure hydrogen compression systems is shifting toward dual-source and multi-source arrangements among station developers and industrial gas distributors. Burckhardt Compression AG leverages its Swiss engineering heritage to sustain premium positioning in diaphragm compressor systems for ultra-high-purity hydrogen. Ariel Corporation anchors North American demand with its reciprocating compressor expertise serving refueling and chemical processing installations. NEUMAN & ESSER competes through integrated package solutions that combine compression, cooling, and control systems for large-scale hydrogen hubs.
Positive-displacement hydrogen compressors are mechanical devices that reduce gas volume through reciprocating pistons, rotary lobes, intermeshing screws, or oscillating diaphragms to achieve discharge pressures from 350 bar to over 900 bar for tube trailer and pipeline injection service. These systems operate with minimal hydrogen contamination compared to dynamic compressors, preserving fuel cell-grade purity specifications below 0.01 ppm total contaminants. Diaphragm technology leads the premium segment due to hermetic sealing and zero leakage characteristics demanded by automotive refueling protocols. Reciprocating systems occupy the volume-intensive industrial and chemical processing application tier where capex efficiency outweighs absolute purity requirements. Screw compressor configurations are gaining traction in medium-scale integrated systems where continuous duty cycles and compact footprints serve distributed hydrogen production sites.
The EU Green Deal and F-Gas Regulation are tightening allowable leakage rates for hydrogen handling equipment, directly influencing compressor seal design and maintenance interval specifications. Japan's METI hydrogen roadmap and South Korea's KGS certification framework mandate third-party validation of compressor safety systems for refueling station deployment. Germany's DVGW technical rules and the US EPA hydrogen production tax credit guidelines are creating divergent compliance pathways that equipment manufacturers must navigate simultaneously. Stakeholders should monitor how national hydrogen bank funding mechanisms and production credit structures reshape procurement timing for compressor fleet investments.
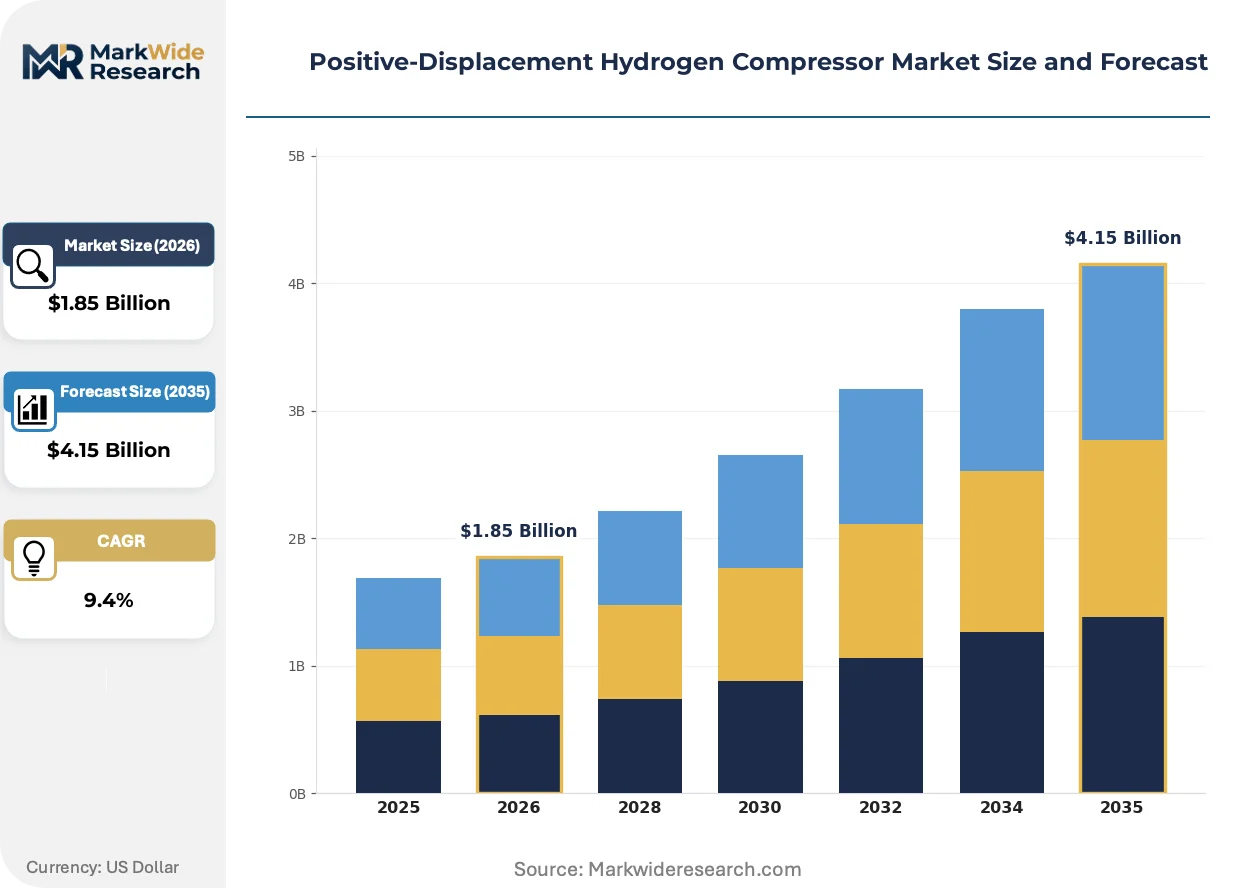
Market Dynamics
Dual-source procurement mandates from hydrogen refueling station operators are forcing compressor manufacturers to reconfigure supply chains and certification documentation, creating competitive pressure on single-source incumbents.
Growth Catalysts
- EU Green Deal leakage standards:The F-Gas Regulation's tightening of allowable hydrogen leakage rates is accelerating replacement cycles for legacy compression equipment across European refueling corridors.
- Fuel cell vehicle fleet expansion:Station developers in Germany, Japan, and South Korea are scaling compressor procurement to match dedicated hydrogen supply corridor buildouts.
- Diaphragm sealing advances:Hermetic sealing technology achieving zero leakage characteristics is automating qualification for automotive refueling protocols demanding sub-0.01 ppm contaminant thresholds.
Market Restraints
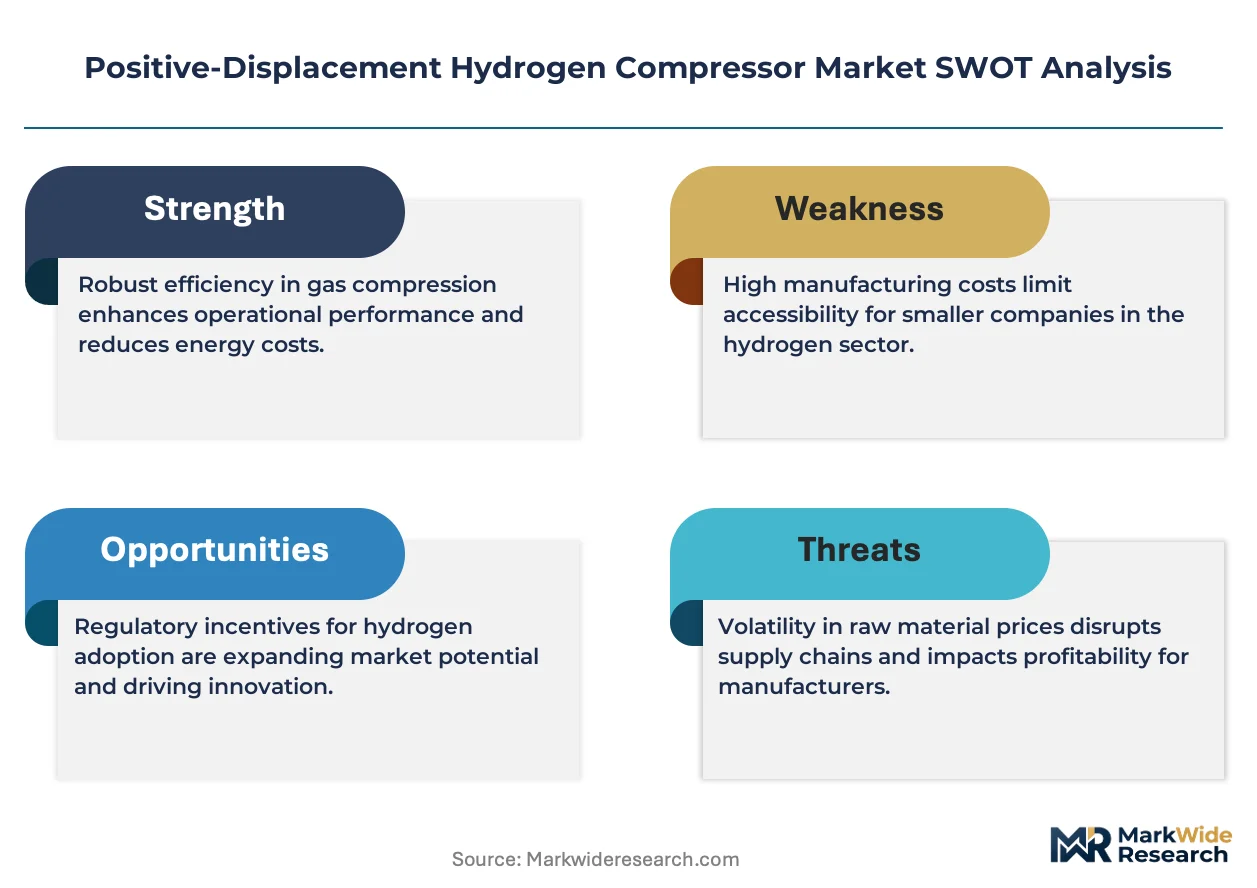
- Specialized alloy supply concentration:High-pressure vessel manufacturing depends on nickel-based superalloy sourcing concentrated among a limited supplier base in Germany and Japan.
- Multi-jurisdiction certification costs:Simultaneous compliance with Germany's DVGW technical rules, Japan's METI hydrogen roadmap, and South Korea's KGS framework inflates validation timelines.
- Ionic liquid compressor substitution:Non-mechanical compression technologies are displacing positive-displacement systems in select low-purity industrial hydrogen applications.
Strategic Opportunities
- US production tax credit alignment:EPA hydrogen production tax credit guidelines are creating procurement timing advantages for compressor fleet investments tied to qualifying production facilities.
- Distributed production site integration:Screw compressor configurations serving medium-scale electrolysis installations represent underpenetrated demand in emerging hydrogen valleys.
- Aftermarket service unbundling:Predictive maintenance platforms and remote monitoring subscriptions are opening recurring revenue streams independent of equipment sales cycles.
Industry Challenges
- High-pressure sealing specialist scarcity:Engineering talent capable of designing metal diaphragm geometries for 900 bar discharge pressures remains concentrated among a limited workforce pool.
- Legacy petrochemical integration friction:Retrofitting positive-displacement compressors into existing hydrogen pipeline injection infrastructure requires custom manifold redesigns and control system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive-Displacement Hydrogen Compressor Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reciprocating, Rotary, Screw, Diaphragm End User: Fuel Cell Vehicles, Industrial Applications, Power Generation, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Integrated Systems Application: Hydrogen Refueling Stations, Chemical Processing, Metalworking, Electronics Manufacturing |
| Companies Covered | Burckhardt Compression AG, Ariel Corporation, NEUMAN & ESSER, Linde plc, Atlas Copco AB, Howden Group, Ingersoll Rand, HAUG Sauer Kompressoren AG, Hydro-Pac, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive-Displacement Hydrogen Compressor Market Trends and Innovations
Digital twin deployment and predictive maintenance architectures are compressing maintenance intervals and reshaping aftermarket service economics across the hydrogen compression value chain.
Machine learning-driven vibration analysis is automating real-time condition monitoring for reciprocating compressor crankshaft assemblies and valve plate wear patterns. Refueling station operators in South Korea and Germany are deploying these systems at scale to prevent unplanned downtime during peak fleet charging windows. The technology is automating shift from calendar-based to condition-based maintenance scheduling, extending mean time between overhauls.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is forcing seal material transitions toward perfluoroelastomer alternatives in diaphragm compressor head assemblies. Equipment manufacturers must revalidate leakage performance under accelerated aging protocols before 2027 compliance deadlines. Diaphragm system suppliers serving automotive refueling applications face the most compressed recertification timelines.
Station developers are consolidating compressor procurement through integrated engineering-procurement-construction contractors rather than direct manufacturer relationships. This channel shift concentrates specification influence among EPC firms with multi-site deployment mandates in Germany and Japan. The pattern is most visible in greenfield hydrogen hub projects where single-contractor accountability reduces interface risk.
Positive-Displacement Hydrogen Compressor Market Segmentation
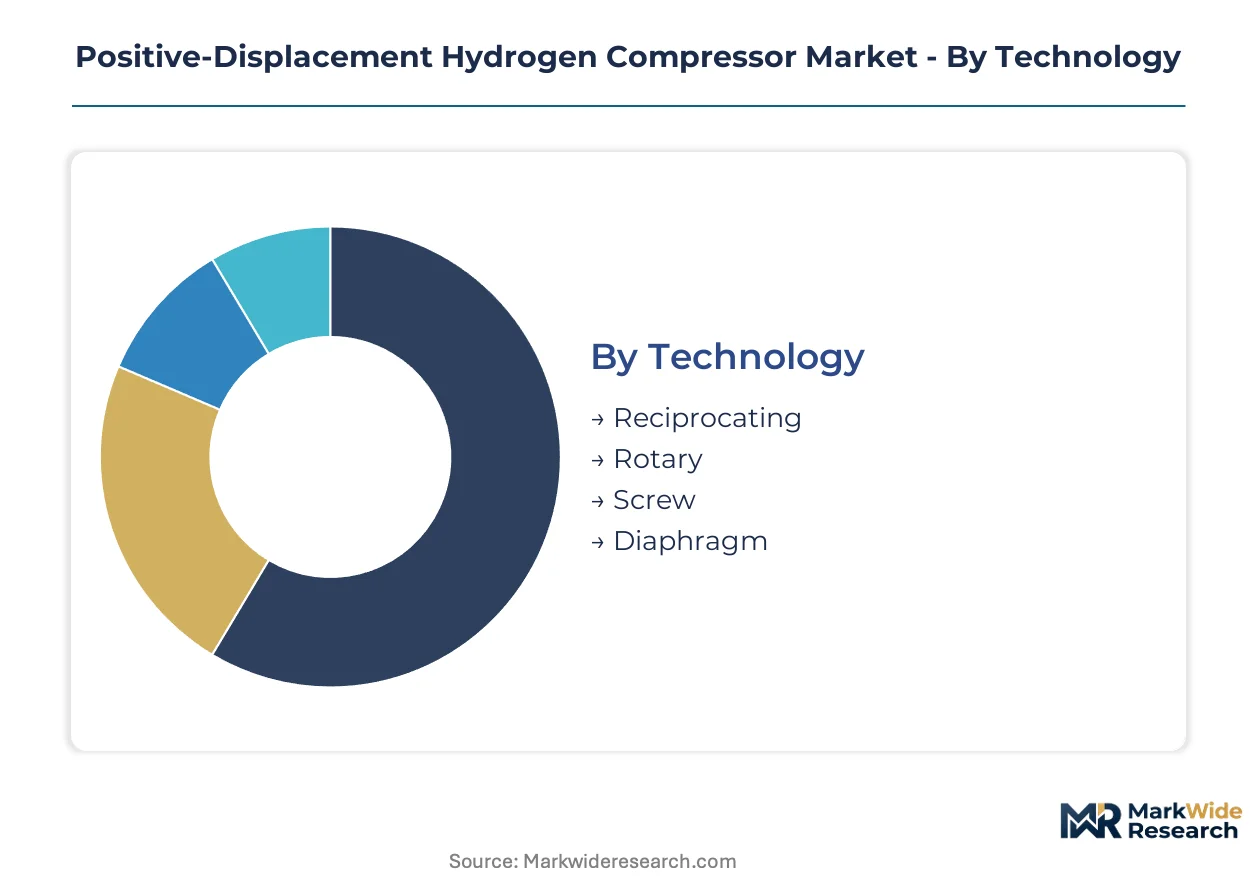
Technology selection in positive-displacement hydrogen compressors determines purity thresholds, pressure capabilities, and maintenance economics. End-user procurement patterns diverge sharply between automotive refueling protocols and industrial process tolerances.
Technology:
Purchase decisions pivot on leakage tolerance and discharge pressure requirements rather than initial capital outlay.
- Diaphragm:Hermetic metal diaphragm assemblies achieve zero leakage and discharge pressures exceeding 900 bar. Automotive refueling station operators in Germany and Japan specify this technology exclusively to meet sub-0.01 ppm contaminant protocols for fuel cell vehicle fleets.
- Reciprocating:Piston-driven compression handles high-volume flows through multiple compression stages with robust sealing systems. Chemical processing installations across the US Gulf Coast and Rotterdam harbor prioritize these systems where capex efficiency outweighs absolute purity requirements.
- Screw:Intermeshing rotors deliver continuous duty cycles in compact footprints for distributed electrolysis sites. Medium-scale hydrogen valleys in Denmark and Spain are standardizing on oil-free screw configurations.
- Rotary:Lobe and vane mechanisms serve low-pressure buffer storage and circulation duties. Industrial gas distributors deploy rotary systems for tube trailer loading operations where final compression stages handle pressure elevation.
Reciprocating systems lead on installed scale; diaphragm configurations lead on specification momentum in refueling corridors.
End User:
Customer archetypes separate cleanly between mobility-focused purity demands and process-tolerant volume buyers.
- Fuel Cell Vehicles:Station operators demand 99.999% hydrogen purity with real-time contamination monitoring. South Korea's KGS certification framework mandates redundant diaphragm compression trains for public refueling infrastructure.
- Industrial Applications:Ammonia synthesis, methanol production, and steel decarbonization drive bulk hydrogen demand. Rotterdam and Houston petrochemical clusters specify reciprocating packages for 350-700 bar pipeline injection.
- Power Generation:Gas turbine blending and long-duration storage applications require variable flow compression. Utility-scale projects in California and Saudi Arabia are piloting screw-integrated storage systems.
- Research Institutions:National laboratories and university facilities require ultra-high-purity compression for materials testing. CERN and Oak Ridge National Laboratory procure custom diaphragm systems with specialized metallurgy.
Industrial applications dominate current procurement volumes; fuel cell vehicle infrastructure is expanding most quickly.
Capacity:
Scale selection correlates with hydrogen source configuration and downstream distribution topology.
- Large Scale:Centralized production hubs processing 10+ tonnes daily demand multi-stage compression with integrated cooling and control architectures. NEOM and Hamburg hydrogen valleys specify these integrated packages.
- Integrated Systems:Electrolyzer-compressor skids combine generation and pressurization in single-source procurement. Danish and Dutch distributed production sites favor this configuration to minimize interface risk.
- Medium Scale:1-5 tonne daily capacity serves regional supply corridors and industrial parks. German Mittelstand chemical processors standardize on modular reciprocating trains.
- Small Scale:Pilot and demonstration projects under 500 kg daily utilize containerized compressor units. Japanese metropolitan refueling stations deploy small-scale diaphragm systems for constrained urban footprints.
Large-scale systems anchor revenue concentration; integrated configurations gain share fastest in greenfield developments.
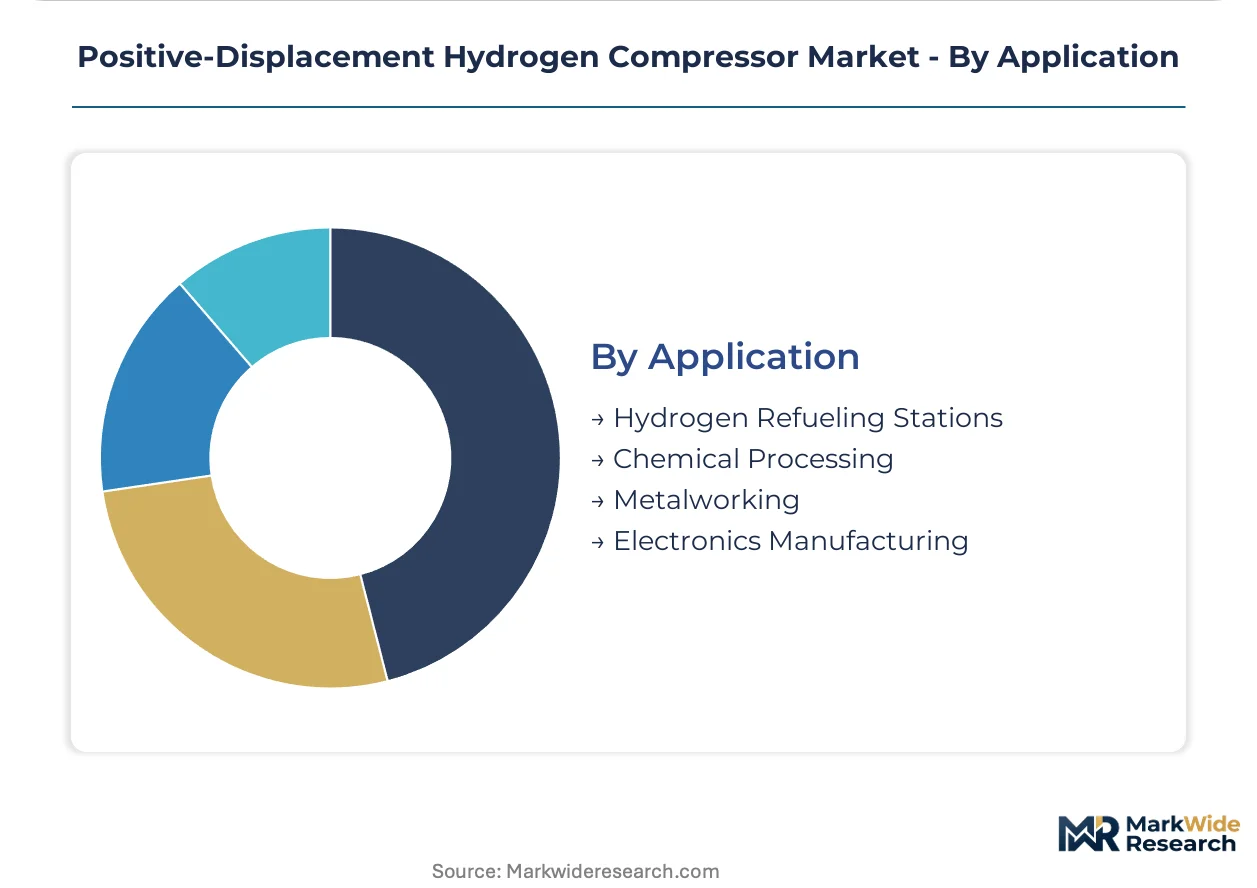
Application:
Operating environment dictates material selection, safety system redundancy, and regulatory compliance pathway.
- Hydrogen Refueling Stations:Public automotive dispensing requires SAE J2601 protocol compliance with 350 bar and 700 bar dispensing capability. California and Germany's DVGW technical rules govern station compressor certification.
- Chemical Processing:Ammonia and methanol synthesis demand continuous-duty compression with minimal unplanned downtime. US EPA hydrogen production tax credit eligibility influences procurement timing for qualifying facilities.
- Metalworking:Heat treatment and cutting operations utilize medium-purity hydrogen at moderate pressures. Japanese automotive component suppliers specify oil-free compression to prevent surface contamination.
- Electronics Manufacturing:Semiconductor fabrication requires ultra-high-purity hydrogen for epitaxial growth processes. South Korean and Taiwanese fabs procure diaphragm systems with specialized surface finishing.
Hydrogen refueling stations command premium pricing; electronics manufacturing shows the steepest expansion trajectory in purity-specified segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping compressor procurement geography as equipment manufacturers seek jurisdictions with streamlined certification pathways and aligned hydrogen production incentives. Production tax credit differentials between the United States and European Union are accelerating facility siting decisions that cascade into regional compressor demand patterns.
Germany
DVGW technical rules govern hydrogen refueling station compressor certification with stringent leakage rate thresholds. The EU Green Deal's F-Gas Regulation mandates seal material transitions by 2027, compressing recertification timelines for diaphragm system suppliers. Hamburg and the Ruhr hydrogen valleys anchor large-scale integrated compression package procurement for 10+ tonne daily production hubs.
United States
EPA hydrogen production tax credit guidelines under the IRA create procurement timing advantages for compressor investments tied to qualifying facilities. FERC interstate pipeline rules and OSHA process safety standards shape high-pressure compression system specifications. The US Gulf Coast petrochemical cluster and California refueling corridors drive divergent demand for reciprocating and diaphragm configurations respectively.
Japan
METI's hydrogen roadmap mandates third-party validation of compressor safety systems for public refueling infrastructure deployment. KHKS and JIS standards specify metal diaphragm geometries for 700 bar automotive dispensing protocols. Tokyo and Osaka metropolitan stations deploy small-scale containerized units within constrained urban footprints.
South Korea
KGS certification framework requires redundant diaphragm compression trains for public refueling station licensing. MFDS-aligned purity protocols for fuel cell vehicle hydrogen mirror automotive industry quality standards. Ulsan and the Seoul Capital Area concentrate station buildouts matching expanding domestic fuel cell bus and passenger vehicle fleets.
Netherlands
REACH and CE marking requirements integrate with EU-wide F-Gas leakage standards for hydrogen handling equipment. The Rotterdam harbor petrochemical cluster specifies reciprocating packages for 350-700 bar pipeline injection into ammonia and methanol synthesis facilities. Dutch distributed electrolysis sites favor integrated electrolyzer-compressor skids to minimize interface risk.
Positive-Displacement Hydrogen Compressor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular integrated systems and aftermarket service unbundling. The vendor base stratifies across three maturity tiers: heritage engineering houses with century-long compression expertise, diversified industrial gas equipment conglomerates, and specialized hydrogen-purity technology boutiques. Strategic archetypes include Swiss-German precision diaphragm specialists, North American reciprocating volume leaders, and Scandinavian integrated package providers. Competitive moves concentrate on dual-source procurement compliance documentation and predictive maintenance platform development.
Within the heritage engineering tier, Burckhardt Compression AG and NEUMAN & ESSER exemplify European precision-manufacturing lineage. Burckhardt Compression AG, a Swiss Aktiengesellschaft, occupies a position representing diaphragm technology heritage for ultra-high-purity applications. NEUMAN & ESSER, a German GmbH, anchors integrated package solutions combining compression, cooling, and control architectures. Among North American volume producers, Ariel Corporation, an Ohio-based corporation, exemplifies reciprocating compressor expertise serving refueling and chemical processing installations. These three entities represent distinct competitive positioning vectors: hermetic sealing specialization, system integration scale, and regional market anchoring respectively.
| Leading Market Players |
|---|
| Burckhardt Compression AG |
| Ariel Corporation |
| NEUMAN & ESSER |
| Linde plc |
| Atlas Copco AB |
| Howden Group |
| Ingersoll Rand |
| HAUG Sauer Kompressoren AG |
| Hydro-Pac, Inc. |
| Others |
Pricing and Supply Chain Analysis
Nickel-based superalloy pricing indices cascade through three distinct equipment tiers, compressing margins for standard reciprocating packages while hermetic diaphragm systems retain premium positioning through metallurgical scarcity and certification bundling.
Pricing Analysis
Input-cost pass-through from specialized alloys and fluorinated seal materials is accelerating price divergence between purity grades. Pricing stratifies across automotive refueling, industrial process, and pilot-scale tiers, with SAE J2601 certification and KGS redundancy mandates commanding substantial premia. Cost compression in mid-tier reciprocating systems is intensifying because of ionic liquid compressor substitution in bulk chemical applications. Industrial gas distributors exhibit highest price sensitivity; fuel cell station operators prioritize leakage performance over capital outlay.
Supply Chain Analysis
High-pressure vessel manufacturing rests on nickel-based superalloy sourcing concentrated in Germany and Japan, with secondary forging capacity in the United States. Critical inputs include hermetic metal diaphragm assemblies, perfluoroelastomer seal compounds, and precision-machined crankshaft forgings. Single-source vulnerability in superalloy melt capacity exposes lead times to aerospace contract prioritization. Distribution runs through integrated engineering-procurement-construction contractors consolidating multi-site procurement in German and Japanese hydrogen corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service unbundling and predictive maintenance platforms, as hardware commoditization pressures mount on standard compression packages.
For Market Incumbents: Hedge against ionic liquid substitution by deepening captive supply of diaphragm metallurgy and securing redundant superalloy sourcing from German and Japanese melt shops. Accelerate certification documentation for dual-source procurement compliance to defend EPC channel relationships. Prioritize predictive maintenance platform development to capture recurring revenue independent of equipment sales cycles. For New Entrants and Emerging Players: Modular integrated electrolyzer-compressor skids offer a technology-first wedge into Danish and Dutch distributed hydrogen valleys where interface risk minimization drives procurement decisions. Target medium-scale screw compressor configurations for underpenetrated 1-5 tonne daily production sites. Pursue direct relationships with distributed electrolysis developers bypassing EPC consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized diaphragm metallurgy boutiques possessing 900 bar design capabilities and established KGS/METI validation histories. Long-term viability favors acquisition targets with installed base density enabling aftermarket service scaling. Watch for EPA hydrogen production tax credit qualification thresholds as procurement timing inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Recurring revenue capture from South Korean and German refueling station operators prevents hardware margin erosion. |
| Superalloy Backward Integration | Captive supply of nickel-based forgings insulates against aerospace contract prioritization and lead time volatility. |
| Dual-Source Certification Investment | Documentation readiness for EPC procurement mandates secures channel access in German hydrogen valley buildouts. |
| Screw Compressor Modularization | Standardized skids for Danish electrolysis sites reduce engineering overhead and accelerate deployment timelines. |
| Perfluoroelastomer Seal Transition | EU F-Gas Regulation compliance by 2027 deadlines preserves automotive refueling market access. |
Research Methodology
Multiple input streams — primary interviews with refueling station operators, EPC procurement directors, and aftermarket service heads; secondary validation through DVGW certification records, KGS licensing databases, and customs trade data; plus SEC filings from listed industrial gas equipment conglomerates — were reconciled through bottom-up and top-down triangulation.
Historical deployment patterns were cross-referenced against expert panel inputs across technology, end-user, capacity, and application dimensions to model adoption trajectories throughout the forecast period. CAGRs were derived from electrolyzer capacity announcements, fuel cell vehicle fleet projections, and hydrogen production tax credit qualification thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to superalloy supply disruptions, ionic liquid compressor cost curves, and EU F-Gas Regulation enforcement stringency. A small set of triggers — EPA credit guidance revisions, METI roadmap updates, and KGS redundancy requirement changes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Compressor Wheel Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
North America Centrifugal Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Gas Compressors Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
CNG Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
LNG Compressor Market