
 Europe Industrial Heat Pump Market | 2026-2036
Europe Industrial Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Heat Pump Market Analysis
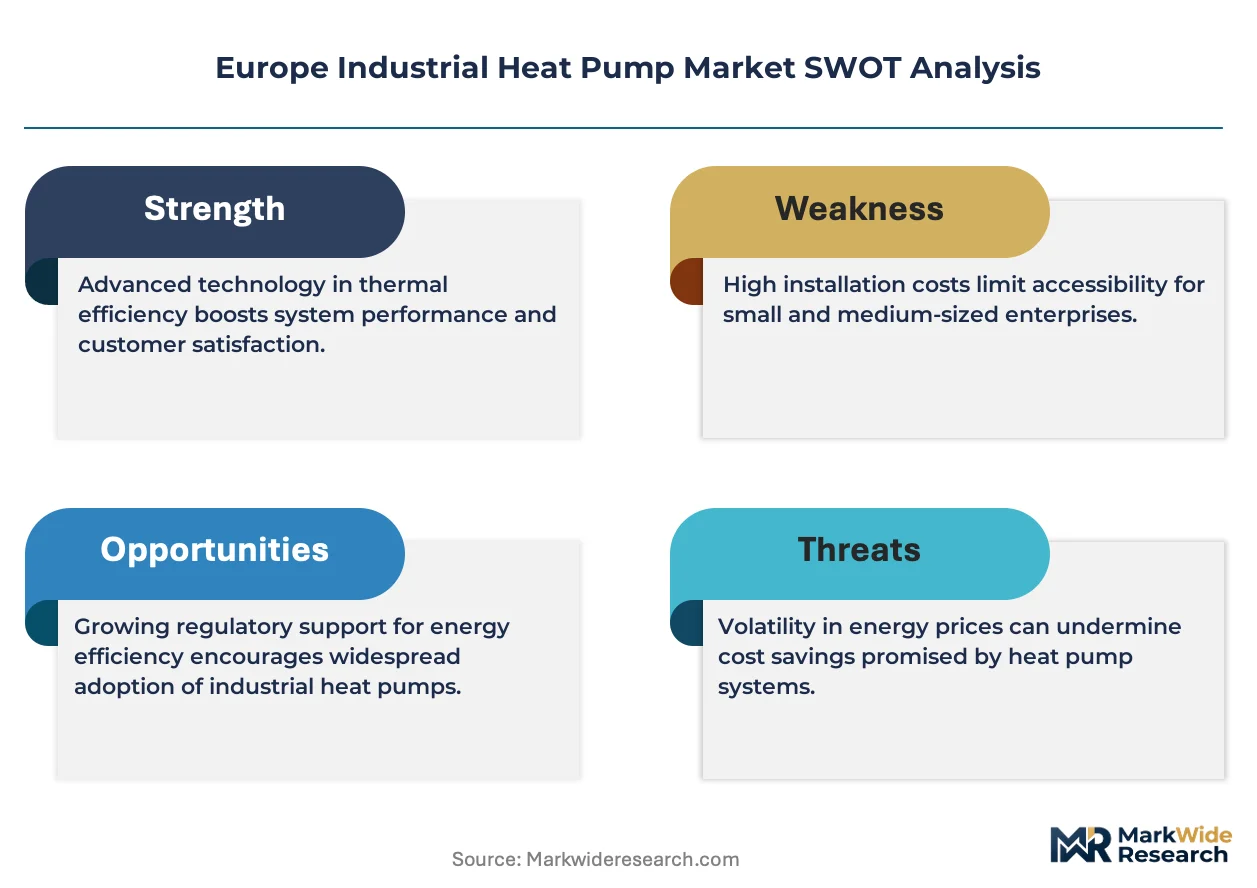
Food and beverage processors is collapsing as the dominant buyer archetype in the Europe Industrial Heat Pump Market, with chemical processing and textile manufacturers rapidly gaining procurement share. NIBE Industrier anchors its position through backward integration into compressor manufacturing, while Siemens Energy leads on high-temperature industrial applications above 150°C. Danfoss differentiates through proprietary valve and control systems that optimize coefficient of performance across variable load conditions.
An industrial heat pump extracts thermal energy from ambient air, water, ground, or waste exhaust streams and upgrades it to useful process temperatures through vapor-compression or absorption cycles, typically achieving coefficient of performance values between three and five depending on source temperature and lift requirements. Water source systems dominate installed capacity across Northern Europe where district heating networks and river access provide stable thermal reservoirs, while exhaust air configurations represent the fastest-growing segment as manufacturers seek to capture waste heat from drying, curing, and smelting operations. Retrofit installations command premium margins due to engineering complexity, though new integrated systems offer superior lifecycle economics for greenfield industrial developments.
The EU Green Deal, F-Gas Regulation, and Ecodesign Directive collectively mandate phase-down of fossil-fired process heating and restrict high-global-warming-potential refrigerants, directly expanding addressable demand for electrically driven thermal solutions. EMA and national regulators in Germany, France, and the Netherlands are aligning building codes and industrial permitting to prioritize heat pump compatibility in factory retrofits. Stakeholders must monitor refrigerant chemistry transitions and grid capacity auctions as these will determine which system architectures achieve total cost of ownership parity against gas boilers within the next planning cycle.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing the planning horizon for industrial decarbonization, forcing facility managers to accelerate electrification timelines and renegotiate long-term thermal supply contracts before carbon border adjustments take full effect.
Growth Catalysts
- EU Green Deal carbon pricing:The escalating cost of emissions certificates under the EU ETS makes electrically driven heat pumps economically competitive against gas boilers for process steam generation in German chemical clusters.
- Waste heat recovery mandates:The Netherlands' national heat strategy requires large industrial installations to assess heat pump integration for exhaust streams above 80°C before permitting renewal.
- Grid balancing incentives:Demand-response tariffs in France reward industrial thermal storage coupled with heat pumps, creating new revenue streams for food processors with batch operations.
Market Restraints
- Refrigerant supply concentration:Production of low-GWP hydrofluoroolefins concentrates among three chemical suppliers, exposing heat pump OEMs to input volatility during the F-Gas phase-down schedule.
- High-temperature technical ceiling:Vapor-compression systems face thermodynamic limits near 150°C process temperatures, leaving cement and glass manufacturing without electrification pathways.
- Grid capacity auction friction:Germany's regional distribution operators queue industrial connection requests for 18-24 months, delaying project commissioning beyond capital budgeting cycles.
Strategic Opportunities
- Polish industrial corridor expansion:Silesian steel and coal processing regions lack district heating density, creating white space for modular exhaust-air heat pump systems serving individual plant thermal loops.
- EU Innovation Fund deployment:The first large-scale project call prioritizes industrial electrification demonstrations above 10 MW thermal capacity, covering 60% of capital costs for pioneering installations.
- Digital twin integration:Convergence of physics-based thermal modeling with predictive maintenance platforms enables performance guarantees that de-risk heat pump adoption for risk-averse procurement committees.
Industry Challenges
- Refrigerant handling certification gaps:The F-Gas Regulation's tightened technician qualification requirements outpace vocational training capacity in France and Italy, extending commissioning timelines.
- Legacy control system integration:Brownfield facilities running 1990s-era SCADA architectures require costly middleware development to synchronize heat pump variable-speed compressors with existing process logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Heat Pump Market |
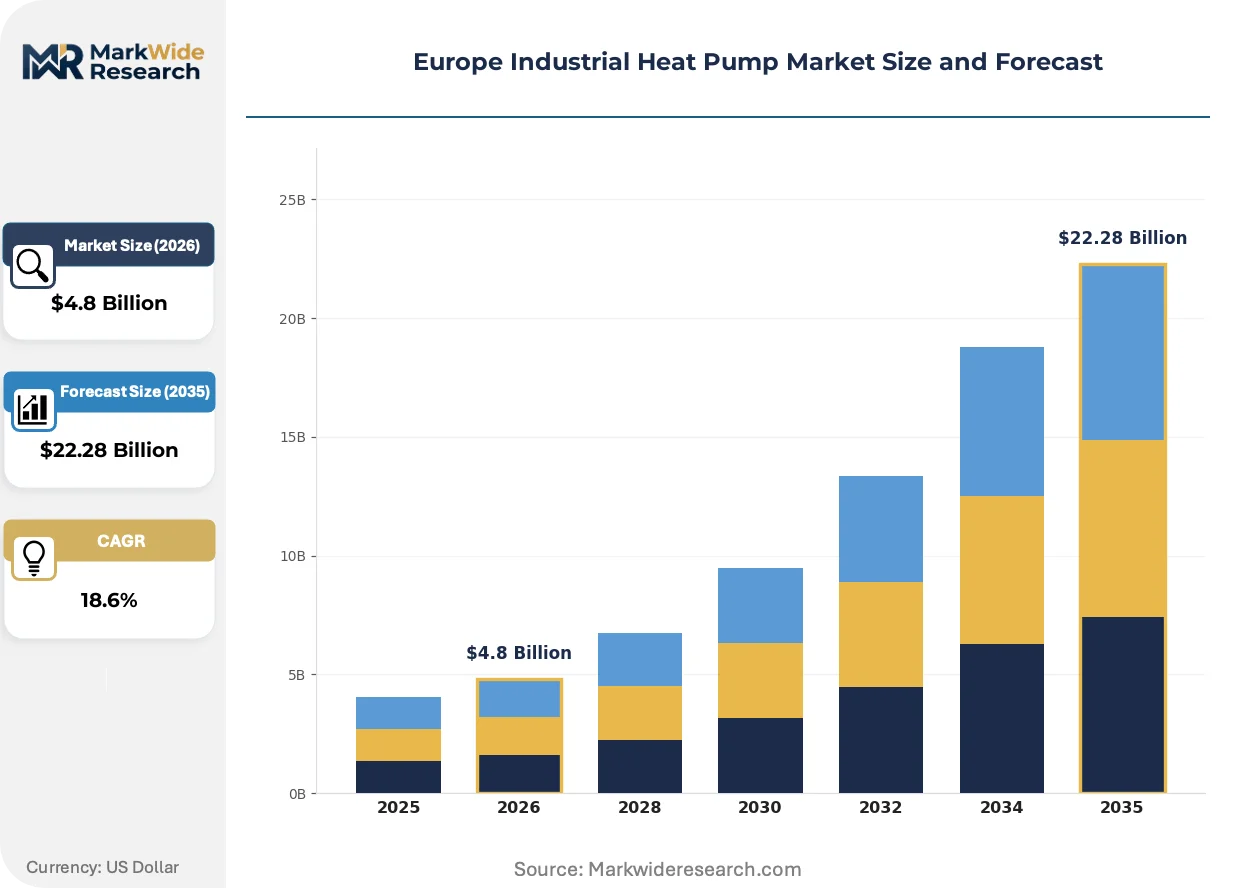
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Ground Source, Exhaust Air End User: Manufacturing, Chemical Processing, Food & Beverage, Textile Installation Type: New Installation, Retrofit Installation, Integrated Systems, Modular Solutions Application: Process Heating, Space Heating, Hot Water Supply, Heat Recovery |
| Companies Covered | NIBE Industrier, Johnson Controls, Siemens Energy, GEA Group, Mitsubishi Electric, Man Energy Solutions, Alfa Laval, Bosch Thermotechnik, Danfoss, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Heat Pump Market Emerging Trajectories
Transcritical CO₂ cycles and solid-state thermal storage are compressing the performance gap between heat pumps and fossil combustion across temperature ranges previously considered uneconomical for electrification.
Magnetic bearing compressor technology is miniaturizing oil-free turbomachinery for industrial heat pumps, enabling maintenance intervals beyond 80,000 hours. Food processors in Denmark and Sweden are adopting these systems for hygienic process steam applications. The elimination of lubricant contamination risk is displacing absorption chillers in dairy pasteurization lines where thermal quality standards are non-negotiable.
The F-Gas Regulation's refrigerant quota reductions are forcing OEMs to accelerate natural working fluid development, with ammonia and CO₂ systems capturing specification share in chemical processing. ECHA's ongoing restriction proposals for PFAS compounds threaten synthetic refrigerant alternatives, pushing engineering resources toward transcritical cycle optimization. German industrial clusters are pre-qualifying only ammonia and hydrocarbon systems for new procurement frameworks to avoid stranded asset risk.
Energy-as-a-service contracting is displacing capital purchase models for heat pump installations in mid-sized manufacturing. Dutch and Belgian food processors now lease thermal capacity with guaranteed output temperatures, transferring performance risk to equipment financiers. This shift concentrates procurement authority with sustainability officers rather than engineering departments, favoring vendors with standardized monitoring platforms and long-term service commitments.
Europe Industrial Heat Pump Market Segmentation
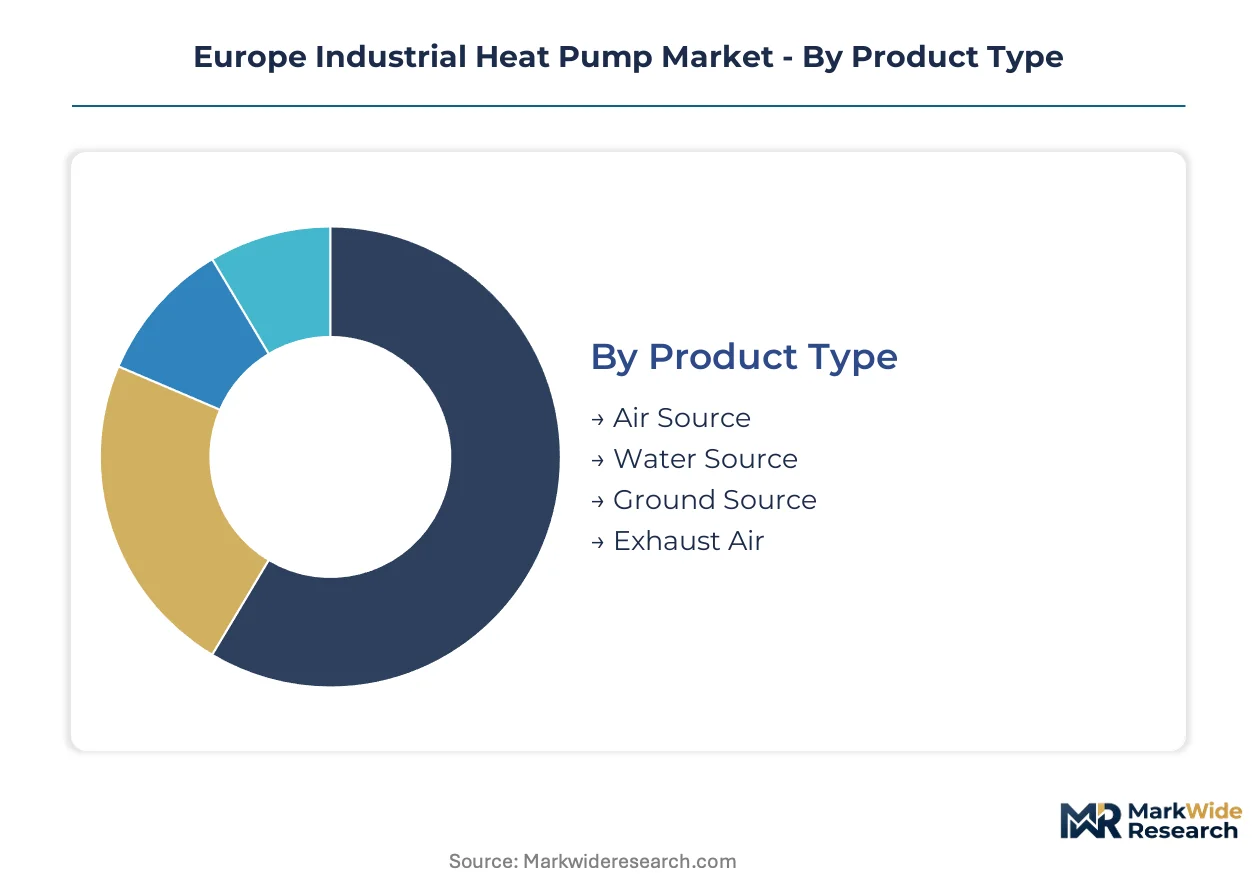
Industrial heat pump procurement in Europe fragments across thermal source technologies, end-use process requirements, and installation constraints that determine total cost of ownership. Each segmentation dimension carries distinct regulatory exposure and substitution risk against fossil-fired alternatives.
Product Type:
Substitute threat from gas boilers intensifies for segments with limited temperature lift or unstable source conditions, compressing pricing power for basic configurations.
- Water Source:These systems extract thermal energy from rivers, lakes, or district heating return lines, delivering coefficient of performance values above four in Nordic conditions. German chemical clusters along the Rhine and Dutch food processors connected to district networks anchor procurement volumes, though expanding river temperature regulations under the EU Water Framework Directive constrain siting flexibility.
- Exhaust Air:Configurations capture waste heat from drying, curing, and smelting operations, achieving payback periods under four years where exhaust streams exceed 80°C. Polish steel processors and Italian ceramic manufacturers are expanding adoption ahead of national waste heat recovery mandates, with modular designs reducing upfront capital barriers for mid-sized installations.
- Air Source:Ambient air systems face performance degradation below -15°C, limiting specification share to Southern European facilities with moderate heating loads.
- Ground Source:Geothermal exchange delivers stable source temperatures but requires substantial land area or vertical drilling, restricting deployment to greenfield industrial parks.
Water source retains volume leadership; exhaust air holds the steepest expansion curve.
End User:
Margin structures diverge sharply between process-critical applications demanding guaranteed uptime and thermal loads where backup combustion remains viable.
- Food & Beverage:Pasteurization, sterilization, and drying operations require precise temperature control across 60-120°C ranges, with hygienic standards favoring oil-free compressor technologies. Danish dairy cooperatives and Belgian brewing facilities are consolidating procurement around ammonia-based systems to preempt F-Gas Regulation quota restrictions.
- Chemical Processing:Distillation and reactor heating demands push vapor-compression systems toward thermodynamic limits near 150°C, leaving only specialty applications electrified. German BASF and Bayer cluster sites are piloting high-temperature heat pumps with thermal storage integration to arbitrage spot electricity prices.
- Textile:Dyeing and finishing operations consume substantial low-grade heat, with Turkish-owned mills in Bulgaria and Romania adopting exhaust-air recovery to meet EU ETS compliance costs.
- Manufacturing:General metalworking and assembly facilities exhibit heterogeneous thermal loads, slowing standardization and stretching sales cycles.
Food & Beverage dominates current procurement value; Chemical Processing is climbing the fastest as carbon border adjustments tighten.
Installation Type:
Customer capital constraints and facility vintage determine whether vendors capture equipment margin or recurring service revenue.
- Retrofit Installation:Brownfield integration demands custom engineering to synchronize with legacy SCADA architectures and confined mechanical rooms, commanding premium pricing but extending project timelines. French automotive suppliers and Italian packaging manufacturers are accelerating retrofit assessments ahead of 2030 decarbonization deadlines.
- New Installation:Greenfield projects allow optimized system sizing and thermal storage integration, delivering superior lifecycle economics but concentrated in limited industrial development zones.
- Integrated Systems:Factory-packaged heat pump and storage combinations reduce commissioning complexity for standardized process loads.
- Modular Solutions:Containerized units enable phased capacity expansion, reducing initial capital exposure for mid-sized processors.
Retrofit Installation captures the largest revenue pool; New Installation is expanding most quickly in Polish and Romanian industrial zones.
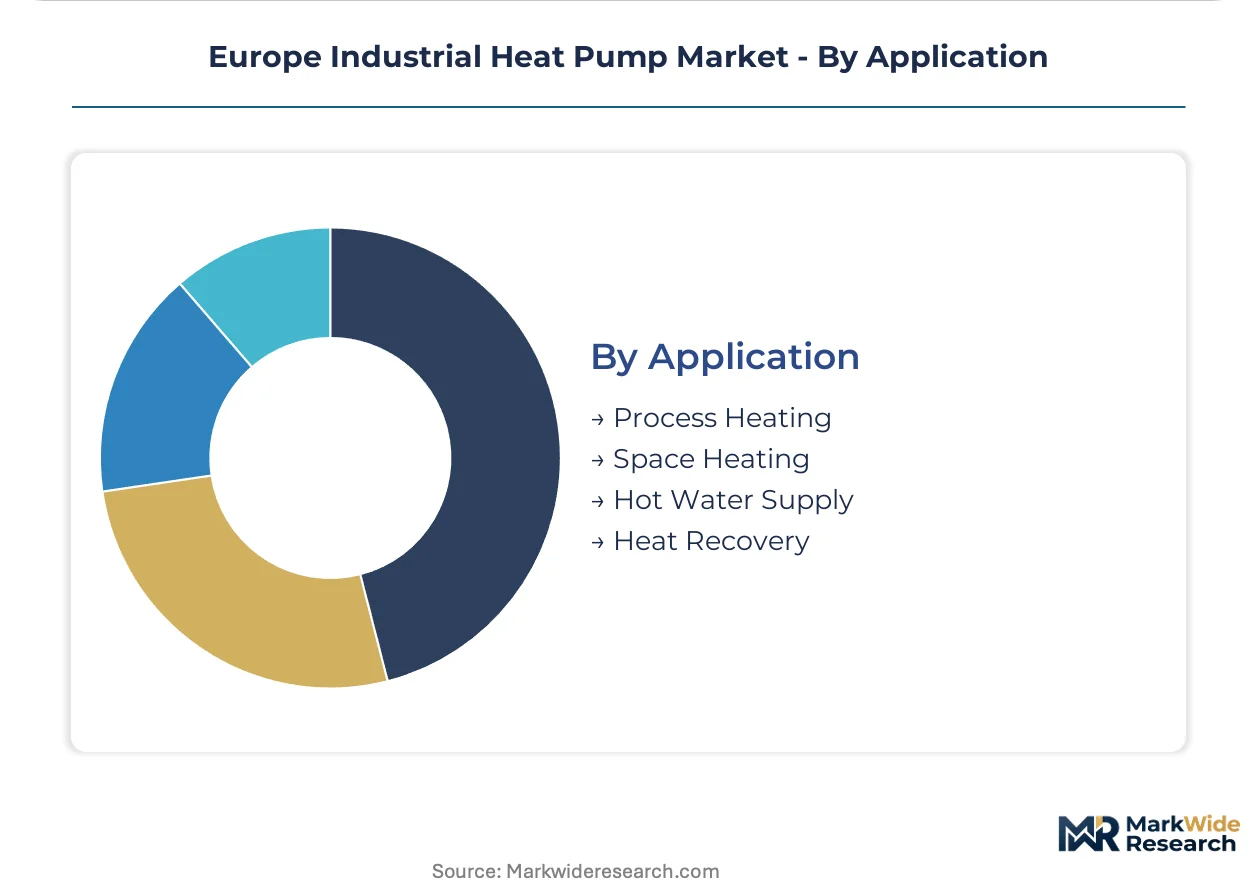
Application:
Process integration depth determines whether heat pumps displace primary combustion or merely supplement existing thermal infrastructure.
- Process Heating:Direct steam and hot fluid generation for reactors, dryers, and curing ovens requires the highest temperature lift, with Dutch chemical processors and Swedish pulp mills leading specification of transcritical CO₂ systems above 120°C.
- Heat Recovery:Waste stream capture and upgrading to useful process temperatures delivers the shortest payback periods where exhaust flows are continuous and high-volume. German cement pre-heater stacks and French glass furnace flues represent priority targets for second-generation absorption heat pumps.
- Space Heating:Warehouse and administrative building conditioning offers lower technical barriers but competes against established district heating connections in Northern Europe.
- Hot Water Supply:Sanitary and cleaning applications require modest temperatures, limiting differentiation and compressing vendor margins.
Process Heating retains technology leadership; Heat Recovery is gaining share fastest as waste stream monitoring mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine river corridor and its dense district heating networks anchor industrial heat pump deployment across Northwestern Europe, while Baltic Sea port infrastructure enables component import flows serving Nordic installation demand.
Germany
Chemical processors along the Rhine-Main industrial belt drive specification of high-temperature systems above 120°C. The EU ETS carbon price escalation forces BASF and Bayer cluster sites to renegotiate thermal supply contracts before 2026. North Rhine-Westphalia's grid operators queue connection requests for 18-24 months, compressing project timelines.
Netherlands
Food processors in the Rotterdam port hinterland adopt exhaust-air recovery to meet national waste heat mandates. The country's heat strategy requires installations above 80°C exhaust streams to assess heat pump integration before permitting renewal. Eindhoven's high-tech manufacturing corridor experiments with thermal storage arbitrage under demand-response tariffs.
France
Automotive suppliers in the Grand Est region accelerate retrofit assessments ahead of 2030 decarbonization deadlines. ANSM-aligned industrial permitting now prioritizes heat pump compatibility in factory renovation codes. The Dunkirk steel cluster pilots absorption heat pumps for blast furnace exhaust recovery.
Poland
Silesian steel and coal processing regions lack district heating density, creating white space for modular exhaust-air systems. National grid auctions favor industrial electrification projects above 10 MW thermal capacity. The Katowice metropolitan area hosts pioneering installations funded through EU Innovation Fund deployment.
Sweden
Pulp mills and dairy cooperatives consolidate procurement around ammonia-based systems to preempt F-Gas quota restrictions. District heating return lines provide stable thermal reservoirs achieving coefficient of performance values above four. Stockholm's industrial parks lead specification of transcritical CO₂ cycles for process steam generation.
Europe Industrial Heat Pump Market Vendor Landscape
Concentration sits with diversified industrial conglomerates possessing captive compressor manufacturing and control system expertise. The vendor base stratifies across three tiers: integrated thermal solution providers commanding premium positioning in chemical processing, specialized heat pump OEMs focused on food and beverage verticals, and regional fabricators serving retrofit installation demand. Dominant competitive moves include backward integration into refrigerant handling capabilities and strategic partnerships with district heating operators to secure siting advantages.
Within the integrated conglomerate tier, NIBE Industrier and Siemens Energy exemplify divergent strategic positioning. NIBE Industrier anchors its market presence through captive supply of compressor manufacturing assets. Siemens Energy occupies a position emphasizing high-temperature industrial applications. Danfoss represents the specialized component tier, with its proprietary valve and control systems serving as reference architecture for optimizing coefficient of performance across variable load conditions.
| Leading Market Players |
|---|
| NIBE Industrier |
| Johnson Controls |
| Siemens Energy |
| GEA Group |
| Mitsubishi Electric |
| Man Energy Solutions |
| Alfa Laval |
| Bosch Thermotechnik |
| Danfoss |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements lock in both refrigerant supply access and heat pump unit price visibility for German chemical processors facing F-Gas quota restrictions. These contracts transfer input volatility risk from OEMs to buyers while securing priority allocation during supply crunches.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-temperature systems above 150°C from mid-range configurations and basic water-source units. Price differentiation hinges on certification grade under the EU ETS compliance framework and volume scale of thermal capacity ordered. Cost compression in the economy tier is intensifying because Polish and Romanian fabricators are entering with modular exhaust-air designs. Food and beverage processors exhibit the highest price sensitivity due to thin operating margins, while chemical clusters prioritize performance guarantees over unit economics.
Supply Chain Analysis
Germany and Sweden anchor compressor manufacturing and control system production for high-performance industrial heat pumps. China and South Korea feed critical rare earth magnet supplies for magnetic bearing turbomachinery, while the Netherlands specializes in ammonia heat exchanger fabrication. Supply chain risk centers on single-source vulnerability for low-GWP hydrofluoroolefin refrigerants concentrated among three chemical suppliers. Distribution runs through authorized system integrators serving district heating operators and direct OEM relationships with large chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by EU ETS carbon price escalation, which has restored project economics for electrification investments deferred during the energy crisis.
For Market Incumbents: Compound defensive positioning through backward integration into refrigerant handling capabilities and captive compressor manufacturing assets. The threat of stranded inventory during F-Gas phase-down schedules demands pre-qualification of ammonia and CO₂ systems in procurement frameworks. Capacity addition in Poland's Silesian corridor captures white-space demand from steel processors lacking district heating access. For New Entrants and Emerging Players: Differentiate on digital twin integration and performance-guaranteed energy-as-a-service contracting. The most penetrable segment sits with mid-sized Dutch and Belgian food processors seeking to transfer capital risk to equipment financiers. A direct go-to-market angle targets sustainability officers rather than engineering departments with standardized monitoring platforms and long-term thermal output commitments. For Investors and Strategic Acquirers: Specialized heat pump OEMs with food and beverage vertical focus and established ammonia system certifications represent the priority acquisition archetype. Long-term viability frames around the 5-10 year window of EU Green Deal implementation and carbon border adjustment enforcement. The signal to watch is grid capacity auction clearing prices in Germany's North Rhine-Westphalia region as an inflection indicator for project commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | NIBE Industrier's captive supply strategy secures margin control amid refrigerant input volatility. |
| Natural Working Fluid Pre-Qualification | German chemical clusters now mandate ammonia and hydrocarbon systems to avoid stranded asset risk. |
| Energy-as-a-Service Contracting | Dutch food processors lease thermal capacity, transferring performance risk to equipment financiers. |
| Digital Twin Integration | Physics-based thermal modeling enables performance guarantees that de-risk procurement committee decisions. |
| Polish Industrial Corridor Expansion | Silesian steel regions lacking district heating density create white space for modular exhaust-air systems. |
Methodological Framework
The analysis maps water source, exhaust air, air source, and ground source heat pump technologies, each validated through plant engineers, OEM procurement teams, district heating operators, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from ETS carbon price registries, F-Gas quota tracking databases, EU Innovation Fund award disclosures, and national heat strategy filings. Bottom-up installation capacity modeling and top-down energy demand projections triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include thermal source technology, end-use process requirements, installation constraints, and regional regulatory cluster. CAGRs were derived from scenario-weighted capacity deployment curves incorporating EU ETS price trajectories and grid connection queue dynamics. Industry-specific forecast inputs include refrigerant chemistry transition timelines and waste heat recovery mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU carbon price elevation or accelerated grid infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding F-Gas phase-down adherence and national heat strategy enforcement. Specific risk factors that could revise projections include PFAS compound restriction proposals from ECHA and regional distribution operator queue management reforms. Recalibration cycles align with material shifts in EU ETS price bands and grid capacity auction outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Residential Furnaces Market