
 Modular Refrigeration Unit Market | 2026-2036
Modular Refrigeration Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Refrigeration Unit Market Insights
Energy-efficiency tier upgrades is rotating demand toward variable-speed compressors and low-GWP refrigerant architectures. Carrier Global Corporation leverages its integrated controls portfolio to capture premium specification contracts in North American food retail. Daikin Industries Ltd. anchors its position through in-house production of inverter-driven scroll compressors for industrial cold storage. Johnson Controls International differentiates via building-automation integration that bundles modular refrigeration with HVAC energy management.
Modular refrigeration units are self-contained, factory-assembled cooling systems built from standardized compressor racks, heat exchangers, and electronic expansion valves that deploy as plug-and-play nodes within distributed cold-chain networks. These systems typically operate between minus forty degrees Celsius and fifteen degrees Celsius, serving supermarkets, pharmaceutical warehouses, and food-processing plants that require scalable, redundant cooling capacity without centralized ammonia-based infrastructure. Commercial units occupy the largest installed base due to supermarket retrofit cycles, while precision refrigeration commands the strongest margin pools from pharmaceutical cold-chain validation requirements. Eco-friendly refrigeration technology is expanding fastest as F-gas regulations tighten across multiple jurisdictions, though energy-efficient refrigeration retains volume leadership in cost-sensitive warehouse deployments.
The EPA enforces hydrofluorocarbon phasedown timelines under the AIM Act, directly constraining refrigerant choices and accelerating equipment replacement schedules. Ecodesign requirements under the EU F-Gas Regulation and the EU Green Deal's refrigeration sector targets are pushing OEMs toward CO2 transcritical and hydrocarbon-based system architectures. Stakeholders must monitor refrigerant supply allocations, certification lag times for new chemistries, and the evolving patchwork of state-level efficiency standards that fragment product qualification pathways across the United States.
Market Dynamics
The EPA's AIM Act phasedown of hydrofluorocarbon refrigerants is forcing a wholesale architecture shift across cold-chain infrastructure, compressing replacement cycles and eliminating legacy equipment pathways.
Growth Catalysts
- Biologics cold-chain expansion:Pharmaceutical distributors are scaling modular capacity to handle temperature-sensitive gene therapies and mRNA vaccines, creating pull for precision refrigeration systems.
- F-Gas Regulation tier upgrades:Ecodesign mandates under the EU Green Deal are accelerating supermarket retrofit demand for CO2 transcritical systems in Germany and France.
- Food retail consolidation:Banner mergers across European grocery chains are standardizing on modular architectures to achieve fleet uniformity and maintenance simplification.
Market Restraints
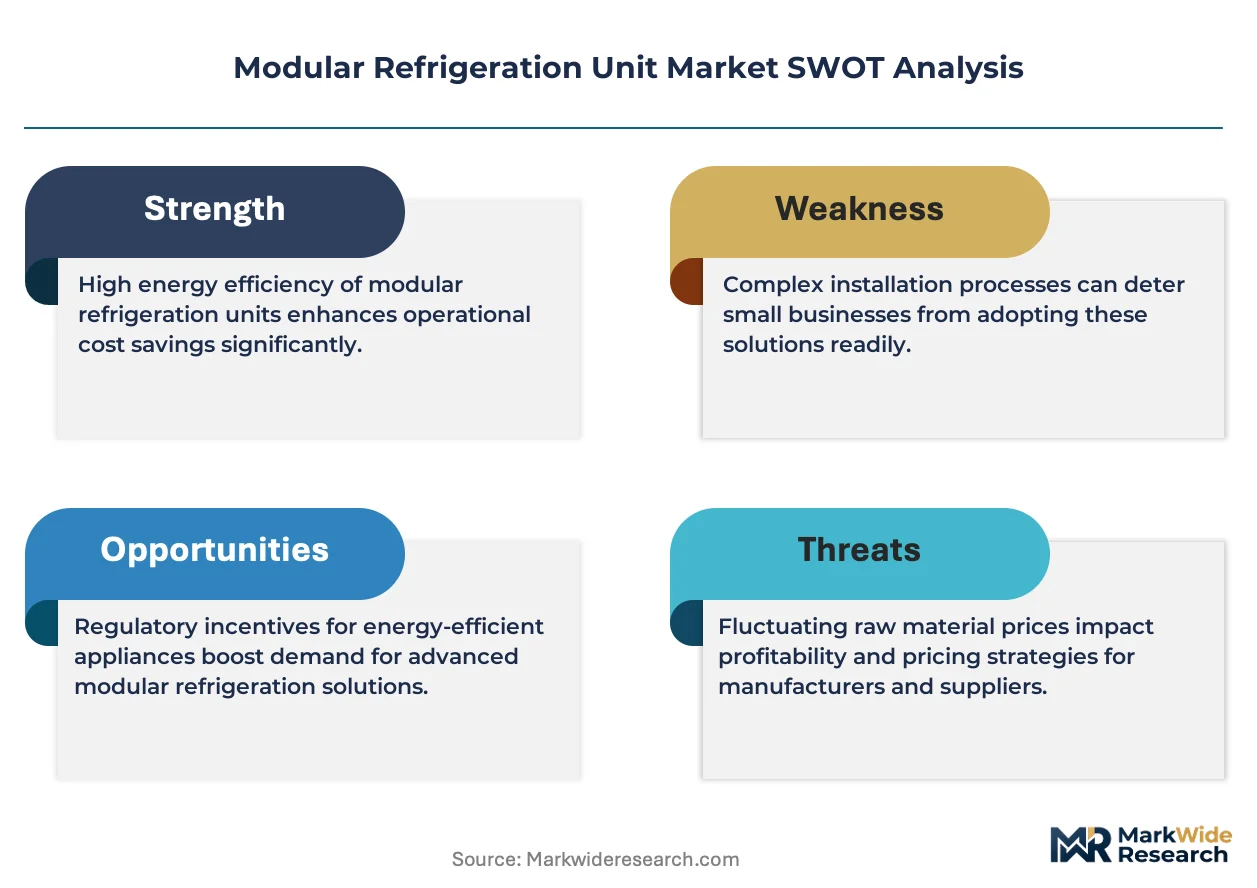
- Copper and aluminum input volatility:Heat exchanger and compressor housing costs swing with base metal markets, compressing OEM margins on fixed-price contracts.
- Refrigerant supply concentration:Low-GWP alternative chemistries remain concentrated among a handful of specialty chemical producers, creating allocation risk during scale-up phases.
- Certification lag for hydrocarbon systems:UL and IEC safety standards for flammable refrigerant architectures trail commercial availability by 18-24 months.
Strategic Opportunities
- Indian pharmaceutical cold-chain:CDSCO validation requirements for vaccine distribution are opening specification windows for modular units in Mumbai and Hyderabad clusters.
- Grid-interactive demand response:Utility incentive programs in California and Texas reward refrigeration load flexibility, bundling modular controls with energy management platforms.
- Last-mile food delivery refrigeration:Dark store and ghost kitchen proliferation is creating demand for compact, rapid-deploy cooling nodes in urban logistics.
Industry Challenges
- Refrigerant transition skill gaps:Field technicians lack training on CO2 transcritical charge procedures and hydrocarbon safety protocols, slowing deployment velocity.
- Legacy control integration:BACnet and Modbus interoperability gaps between new modular units and existing building management systems extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Refrigeration Unit Market |
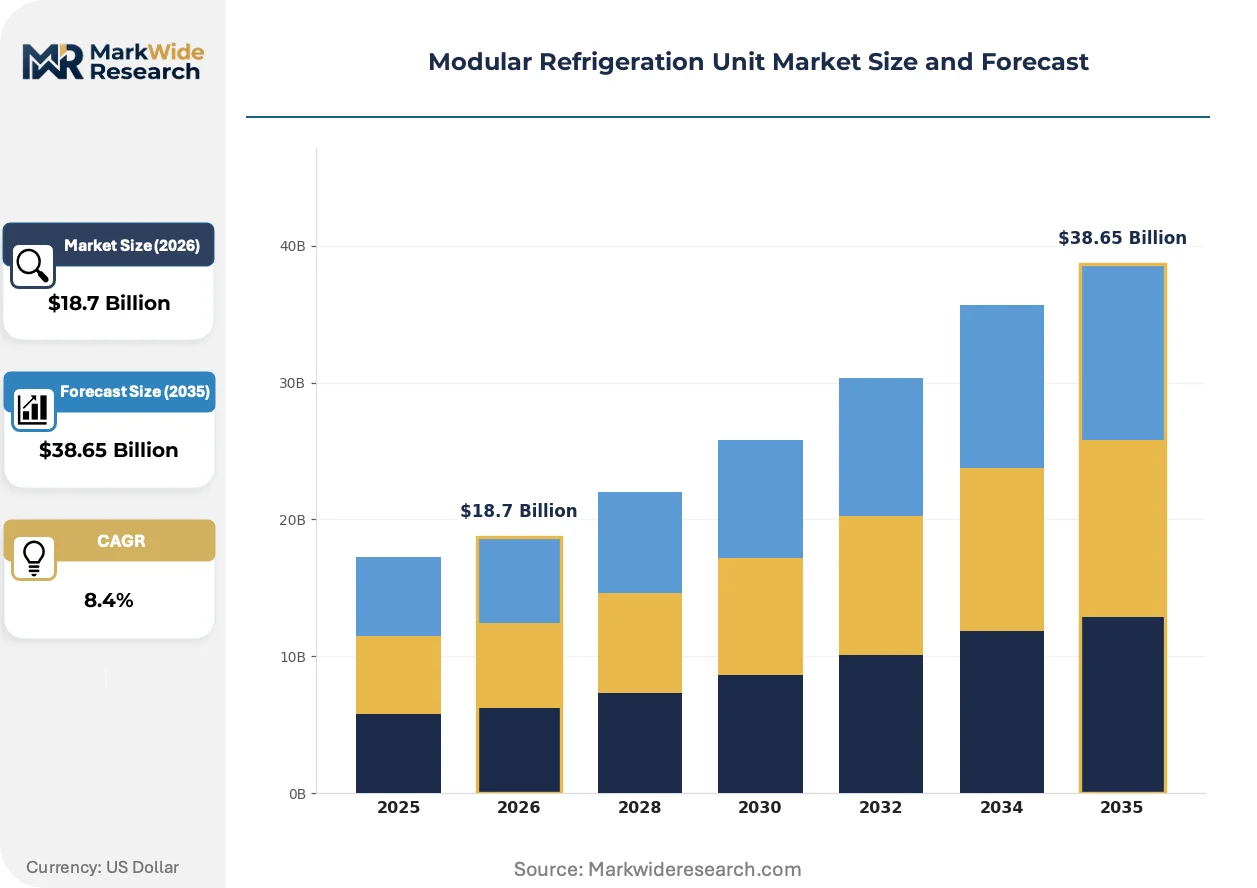
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Units, Industrial Units, Specialized Units, Portable Units End User: Supermarkets, Restaurants, Warehouses, Pharmaceutical Companies Technology: Standard Refrigeration, Eco-Friendly Refrigeration, Precision Refrigeration, Energy-Efficient Refrigeration Installation: Onsite Installation, Factory Installation, Mobile Installation, Remote Installation |
| Companies Covered | Carrier Global Corporation, Daikin Industries Ltd., Johnson Controls International, Trane Technologies plc, Emerson Electric Co., GEA Group AG, Blue Star Limited, Thermo King Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Refrigeration Unit Market Trends and Innovations
Equipment architectures are pivoting from centralized ammonia plants toward distributed, refrigerant-agnostic nodes that can be reconfigured as regulations and load profiles evolve.
Variable-speed scroll compressor technology is fragmenting the traditional reciprocating compressor installed base. Supermarket operators in Germany and the Netherlands are specifying inverter-driven systems to hit Ecodesign efficiency tiers. This fragmentation is compressing the market share of fixed-speed architectures and enabling smaller-capacity modular deployments that match load more precisely.
The EPA's phasedown mandates under the AIM Act are eliminating R-404A and R-507A from new equipment specifications. Cold storage developers in California and Texas are now defaulting to CO2 transcritical or R-290 hydrocarbon systems to preempt compliance deadlines. Food processing plants with long asset horizons are most affected, accelerating their specification reviews to avoid stranded equipment risk.
Asset-light service models are displacing capital purchase patterns among mid-size cold storage operators. Third-party temperature-controlled logistics providers in the Netherlands and Belgium are leasing modular capacity with bundled maintenance rather than owning refrigeration assets. This shift concentrates buying power with fleet operators and compresses manufacturer margins through volume contracting.
Modular Refrigeration Unit Market Segmentation
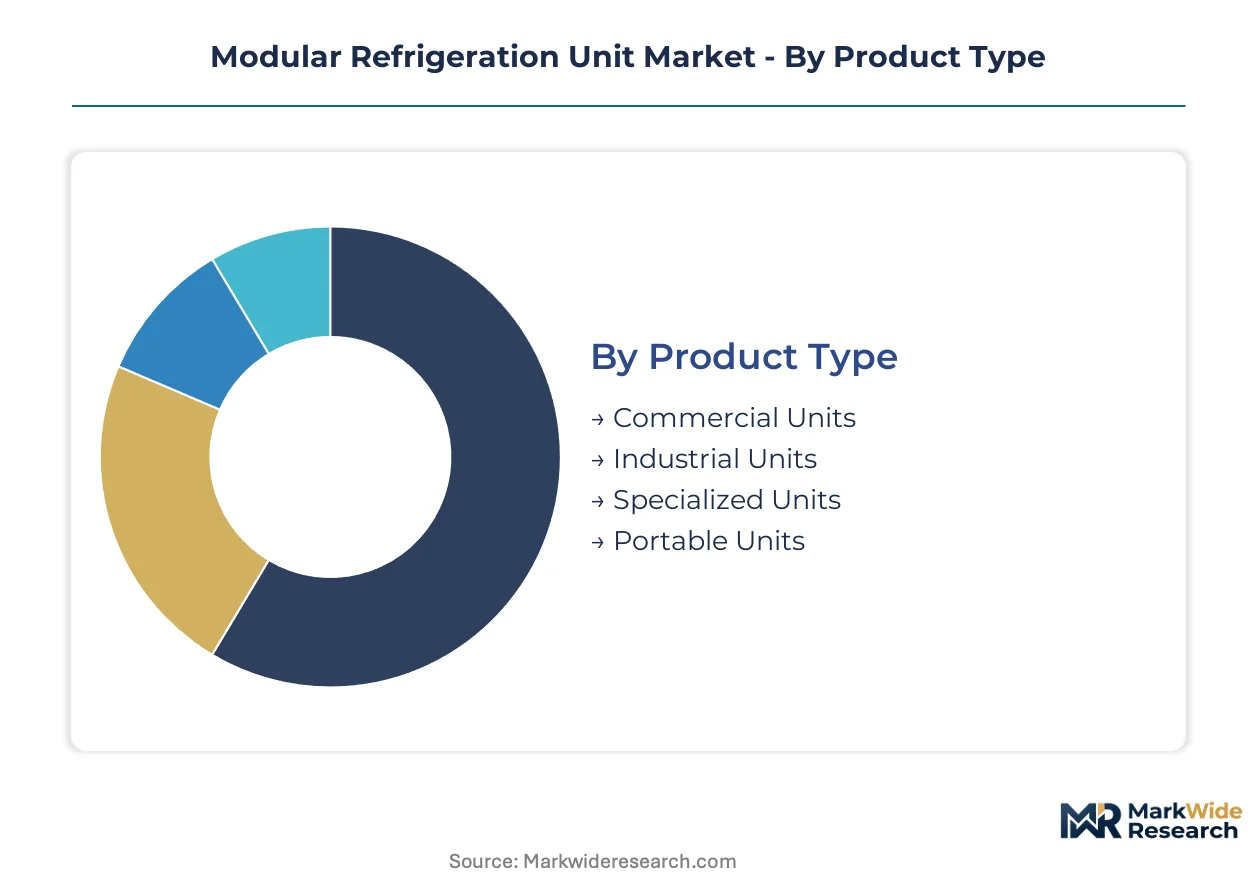
Modular refrigeration unit segmentation reveals distinct substitution pressures across product architectures. Each category exhibits divergent vulnerability to alternative cooling technologies and competing equipment formats.
Product Type:
Commercial units face intensifying substitution from distributed HVAC-integrated systems, while portable formats confront battery-powered mobile cooling alternatives.
- Commercial Units:Self-contained compressor racks and heat exchangers configured for supermarket retrofit cycles and food retail redundancy requirements. Demand concentrates in Germany where Ecodesign mandates accelerate replacement schedules for standardized fleet architectures.
- Industrial Units:Higher-capacity modular nodes serving cold storage warehouses and food processing plants with scalable redundancy. Pharmaceutical warehouses in Mumbai and Hyderabad clusters are scaling specifications to meet CDSCO validation requirements for vaccine distribution networks.
- Specialized Units:Purpose-built configurations for controlled-atmosphere applications and rapid freezing protocols.
- Portable Units:Compact, rapid-deploy cooling nodes for dark stores and ghost kitchen proliferation in urban logistics corridors.
Commercial units retain volume leadership; portable units hold the steepest expansion curve.
End User:
Supermarket procurement patterns now favor leasing over capital purchase, compressing OEM margins through fleet-operator concentration.
- Supermarkets:Banner mergers across European grocery chains standardize on modular architectures for fleet uniformity. Third-party logistics providers in the Netherlands and Belgium are displacing direct ownership with bundled maintenance contracts.
- Pharmaceutical Companies:Gene therapy and mRNA vaccine cold chains demand precision temperature validation and redundant cooling capacity. CDSCO regulations in India and FDA requirements in the US create specification windows for validated modular systems.
- Restaurants:Ghost kitchen proliferation drives compact, rapid-deploy cooling node specifications.
- Warehouses:Cost-sensitive deployments prioritize energy-efficient architectures over eco-friendly alternatives despite tightening F-gas regulations.
Supermarkets dominate procurement volume; pharmaceutical companies command the strongest margin pools.
Technology:
Refrigerant chemistry constraints under EPA AIM Act and EU F-Gas Regulation are fragmenting legacy technology adoption curves.
- Eco-Friendly Refrigeration:CO2 transcritical and hydrocarbon-based architectures replacing R-404A and R-507A specifications. California and Texas cold storage developers default to these systems to preempt EPA compliance deadlines and avoid stranded equipment risk.
- Precision Refrigeration:Tight temperature tolerance systems for biologics and temperature-sensitive pharmaceuticals. Validation requirements from EMA and FDA create specification barriers that sustain premium positioning.
- Standard Refrigeration:Fixed-speed reciprocating compressor architectures facing displacement by inverter-driven alternatives.
- Energy-Efficient Refrigeration:Variable-speed scroll and inverter-driven systems capturing supermarket retrofit demand in Germany and the Netherlands to hit Ecodesign efficiency tiers.
Energy-efficient refrigeration retains volume leadership; eco-friendly refrigeration gains share fastest.
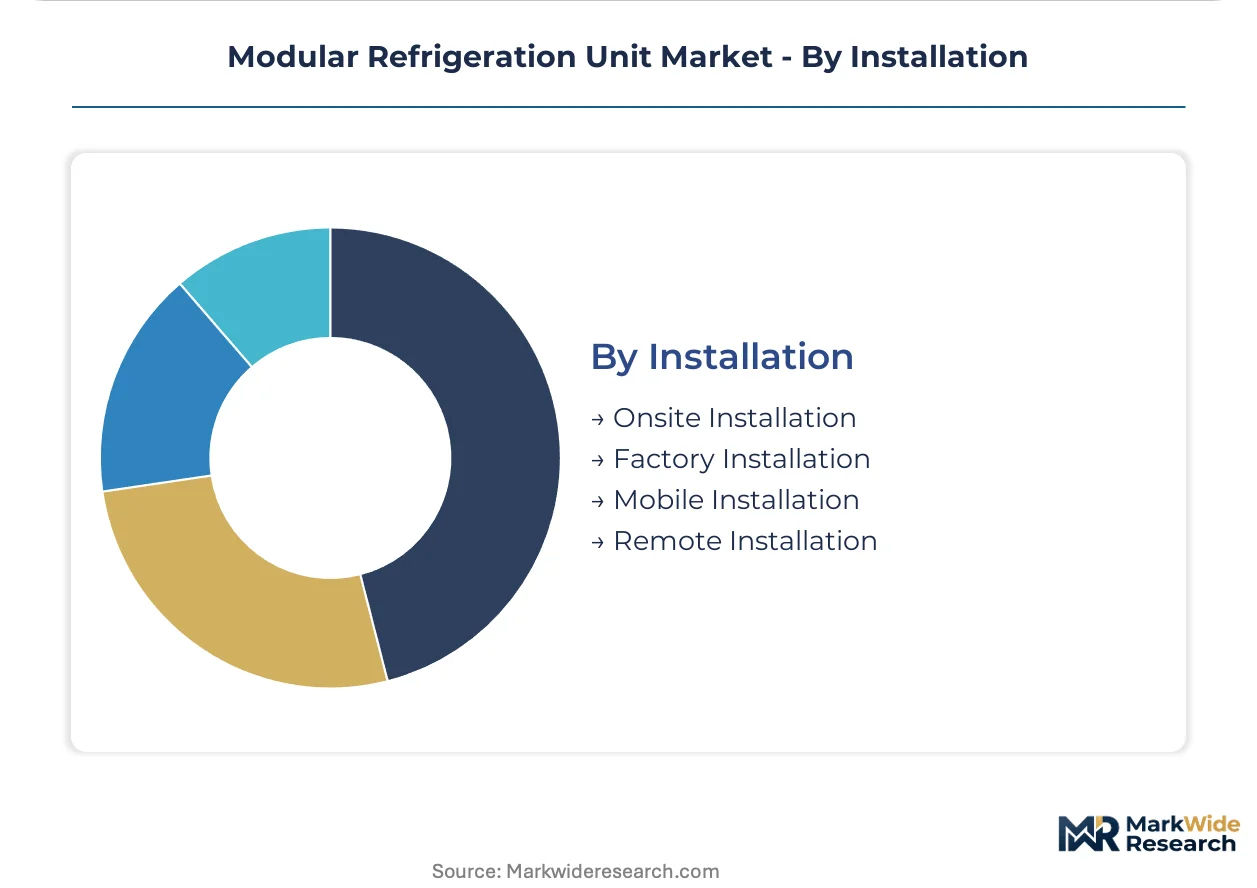
Installation:
Factory pre-commissioning is displacing field assembly as refrigerant transition skill gaps extend onsite timelines.
- Factory Installation:Pre-charged, tested systems reducing field technician dependency for CO2 transcritical and hydrocarbon protocols. OEMs capture margin through controlled assembly environments while mitigating UL and IEC certification lag risks.
- Onsite Installation:Traditional field assembly facing compression from BACnet and Modbus interoperability gaps with existing building management systems.
- Mobile Installation:Rapid-deploy configurations for temporary cold capacity and emergency redundancy.
- Remote Installation:Distributed nodes managed through centralized monitoring platforms for grid-interactive demand response programs in California and Texas.
Factory installation commands the dominant share; mobile installation shows the most rapid uptake trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for compressor racks and electronic expansion valves shapes procurement strategies across major cold-chain markets, with equipment trade flows concentrated between German engineering centers and Asian component fabricators.
United States
California cold storage developers and Texas food processors are accelerating equipment replacement schedules ahead of EPA AIM Act phasedown deadlines. The EPA enforces hydrofluorocarbon reduction timelines that eliminate R-404A and R-507A from new specifications. Dallas-Fort Worth logistics corridors see concentrated demand for CO2 transcritical systems as operators seek to avoid stranded equipment risk.
Germany
Supermarket banner mergers and Ecodesign tier upgrades are compressing replacement cycles for modular fleet architectures. The EU F-Gas Regulation mandates progressive refrigerant phase-downs through 2030. The Ruhr industrial belt and Bavarian food processing clusters anchor specification demand for variable-speed compressor systems.
India
Pharmaceutical cold-chain expansion in Mumbai and Hyderabad is scaling validated modular capacity for vaccine distribution networks. CDSCO validation requirements create specification barriers for temperature-sensitive biologics. The Maharashtra and Telangana state clusters concentrate procurement pull from third-party logistics providers.
Netherlands
Asset-light leasing models are displacing capital purchases among mid-size cold storage operators seeking bundled maintenance contracts. The EU Green Deal refrigeration sector targets accelerate supermarket retrofit demand. Rotterdam port logistics and Belgian border warehousing corridors standardize on modular architectures for fleet uniformity.
Japan
Precision refrigeration demand from pharmaceutical manufacturers sustains premium positioning for tight-tolerance systems. METI energy efficiency standards drive inverter-driven compressor adoption. The Osaka-Kobe industrial zone and Greater Tokyo pharmaceutical clusters specify redundant modular nodes for biologics cold-chain validation.
Modular Refrigeration Unit Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized HVAC-R engineering houses that command specification relationships with supermarket banners and pharmaceutical distributors. The vendor base spans three strategic tiers: integrated building-automation providers capturing bundled energy management contracts, compressor technology specialists leveraging in-house inverter production, and regional fabrication houses serving cost-sensitive warehouse deployments. Competitive moves center on vertical integration into refrigerant-agnostic system architectures and geographic expansion into Indian pharmaceutical clusters through CDSCO validation partnerships.
Within the diversified conglomerate tier, Carrier Global Corporation and Daikin Industries Ltd. exemplify scale-driven positioning, while Johnson Controls International anchors the building-automation integration archetype. These three entities represent distinct competitive vectors: controls-led specification capture, captive compressor manufacturing, and bundled HVAC-refrigeration energy management. Their collective presence across North American food retail and European supermarket retrofit cycles demonstrates how technology breadth and service integration determine contract outcomes in regulated replacement markets.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries Ltd. |
| Johnson Controls International |
| Trane Technologies plc |
| Emerson Electric Co. |
| GEA Group AG |
| Blue Star Limited |
| Thermo King Corporation |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day compressor rack lead times from Asian fabricators concentrate procurement leverage with OEMs holding buffer inventory in Germany and the United States, compressing margin recovery for second-tier suppliers facing fixed-price supermarket contracts. This inventory asymmetry shapes tiered pricing power across the modular refrigeration value chain, where factory-pre-charged systems command premiums over field-assembled alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with CO2 transcritical architectures and UL-certified hydrocarbon systems commanding tier-one positioning. Price differentiation rests on certification grade and after-sales service bundling, while cost compression in standard reciprocating compressor tiers is intensifying because of copper and aluminum input volatility. Warehouse operators in cost-sensitive deployments exhibit highest price sensitivity; pharmaceutical cold-chain validators show lowest sensitivity due to CDSCO and FDA compliance requirements.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for electronic expansion valves and scroll compressor castings, compressing landed cost predictability for European OEMs. Manufacturing concentrates in China, South Korea, and Germany for compressor technology, heat exchanger fabrication, and precision controls assembly respectively. The supply chain draws from copper cathode, aluminum coil, and rare-earth magnet inputs. Single-source vulnerability in low-GWP refrigerant chemistry creates allocation risk. Distribution runs through OEM direct channels and third-party logistics fleet operators in the Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular refrigeration unit market sits in early-cycle expansion as F-gas regulatory phasedowns force replacement demand ahead of natural equipment lifecycles, creating a compressed adoption window for refrigerant-agnostic architectures.
For Market Incumbents: Shield specification relationships with supermarket banners through captive production of inverter-driven scroll compressors and pre-certified CO2 transcritical system architectures. Deepen backward integration into electronic expansion valve manufacturing to offset heat exchanger input volatility. Prioritize CDSCO validation partnerships in Indian pharmaceutical clusters to preempt emerging entrant access.
For New Entrants and Emerging Players: Lead with rapid-deploy portable units for dark store and ghost kitchen proliferation in urban logistics corridors, where asset-light leasing models displace capital purchases and lower barriers to fleet penetration. Target Mumbai and Hyderabad pharmaceutical cold-chain expansion with validated precision refrigeration systems. Anchor go-to-market through third-party temperature-controlled logistics providers seeking bundled maintenance contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-mandated replacement cycle play because EPA AIM Act and EU F-Gas Regulation timelines eliminate legacy equipment pathways regardless of macroeconomic conditions. Acquisition targets should demonstrate refrigerant-agnostic platform architectures and established validation relationships with EMA or FDA. The signal to watch is state-level efficiency standard fragmentation in the United States, which would accelerate specification consolidation toward integrated building-automation providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | In-house inverter-driven scroll production secures margin control against copper price volatility. |
| CDSCO Validation Partnership | Indian pharmaceutical regulator certification opens specification windows in Mumbai and Hyderabad clusters. |
| CO2 Transcritical Platform Development | Refrigerant-agnostic architecture preempts EPA AIM Act compliance deadlines and stranded equipment risk. |
| Grid-Interactive Controls Integration | Utility demand response programs in California and Texas bundle refrigeration with energy management platforms. |
| Asset-Light Leasing Model Launch | Fleet-operator concentration in the Netherlands and Belgium displaces capital purchase patterns. |
Research Methodology
A spread of perspectives from cold-chain logistics operators, supermarket procurement directors, pharmaceutical quality assurance leads, and HVAC-R field technicians converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from EPA enforcement timelines, EU Ecodesign regulatory filings, CDSCO validation protocols, and customs trade data for compressor rack imports. Bottom-up equipment deployment estimates triangulated against top-down cold-chain infrastructure investment tracking.
Segmentation dimensions modeled span product type, end-user vertical, refrigerant technology architecture, and installation format across the projection horizon. CAGRs derived from replacement cycle compression analysis, regulatory deadline acceleration effects, and penetration rate assumptions for CO2 transcritical systems in California and Texas cold storage. Industry-specific forecast inputs include F-gas phasedown trajectory scenarios and supermarket banner merger consolidation patterns in Germany.
The analysis sits within stated boundaries; outcomes outside continued EPA AIM Act enforcement, EU Green Deal refrigeration sector targets, and sustained biologics cold-chain expansion would require recalibration. Forecasts reflect documented assumptions regarding refrigerant supply allocation stability and certification lag resolution for hydrocarbon safety standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
South America Compressor Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Compressor Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Japan Commercial HVAC Market